
 Europe EV Charging Stations Market | 2026-2036
Europe EV Charging Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Europe EV Charging Stations Market Intelligence
The shift towards open-protocol software platforms is fragmenting the previously closed-loop network operator model across Europe. Hubject leverages its eRoaming platform to connect disparate charging networks, creating a unified access point for drivers. In contrast, Ionity specializes in building out a proprietary high-power charging network along major European transit corridors. Wallbox dominates the residential and semi-public AC charging hardware segment with its smart charging solutions.
Europe EV charging stations are electrical supply equipment designed to recharge electric vehicle batteries using alternating (AC) or direct current (DC). DC fast chargers deliver over 50 kW via the Combined Charging System (CCS) standard, while AC units typically use the Type 2 connector. The DC Fast Charger segment leads growth in public car parks to address driver range anxiety. In parallel, AC Slow Charger installations dominate the residential complexes segment due to lower hardware costs.
The European Union's Green Deal and its associated Alternative Fuels Infrastructure Regulation (AFIR) mandate minimum charging infrastructure density across member states. All charging equipment sold within the EU must also adhere to CE marking requirements, which ensures safety and electromagnetic compatibility standards. The critical challenge for network operators and utilities will be managing grid stability as charging demand from corporate fleets and individual owners escalates.
Market Dynamics
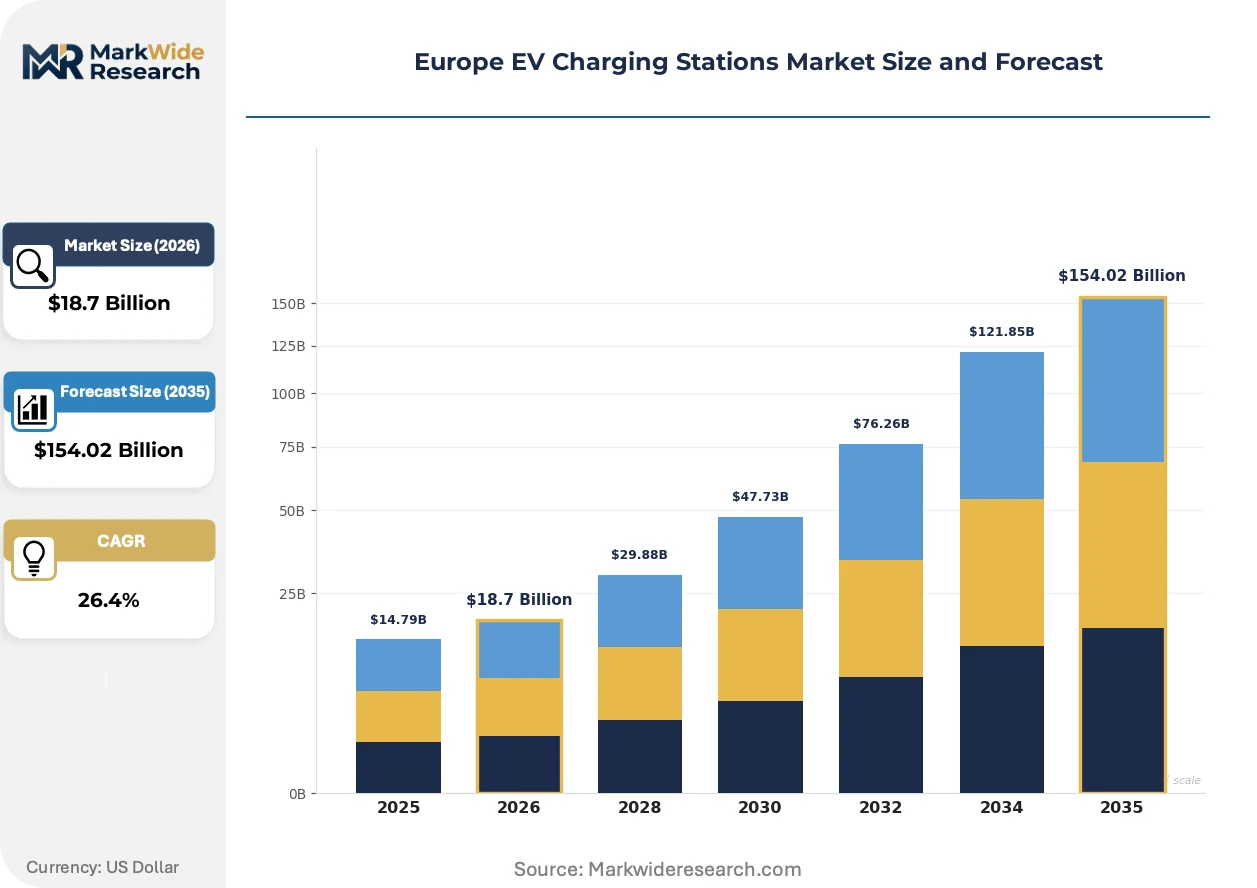
The market's expansion is fundamentally shaped by top-down regulatory mandates from the European Union. The Alternative Fuels Infrastructure Regulation (AFIR) creates a predictable, policy-driven demand floor, compelling accelerated public charging infrastructure deployment across all member states.
Growth Catalysts
- EU Green Deal Targets:Stringent CO2 emissions standards compel the transition to EVs, creating foundational demand for charging infrastructure across the EU.
- Corporate Fleet Electrification:European corporations are converting vehicle fleets to meet sustainability goals, driving bulk demand for workplace and depot charging solutions.
- German Federal Subsidies:National subsidies in Germany lower the capital cost of installing private and semi-public charging points, accelerating network density.
Market Restraints
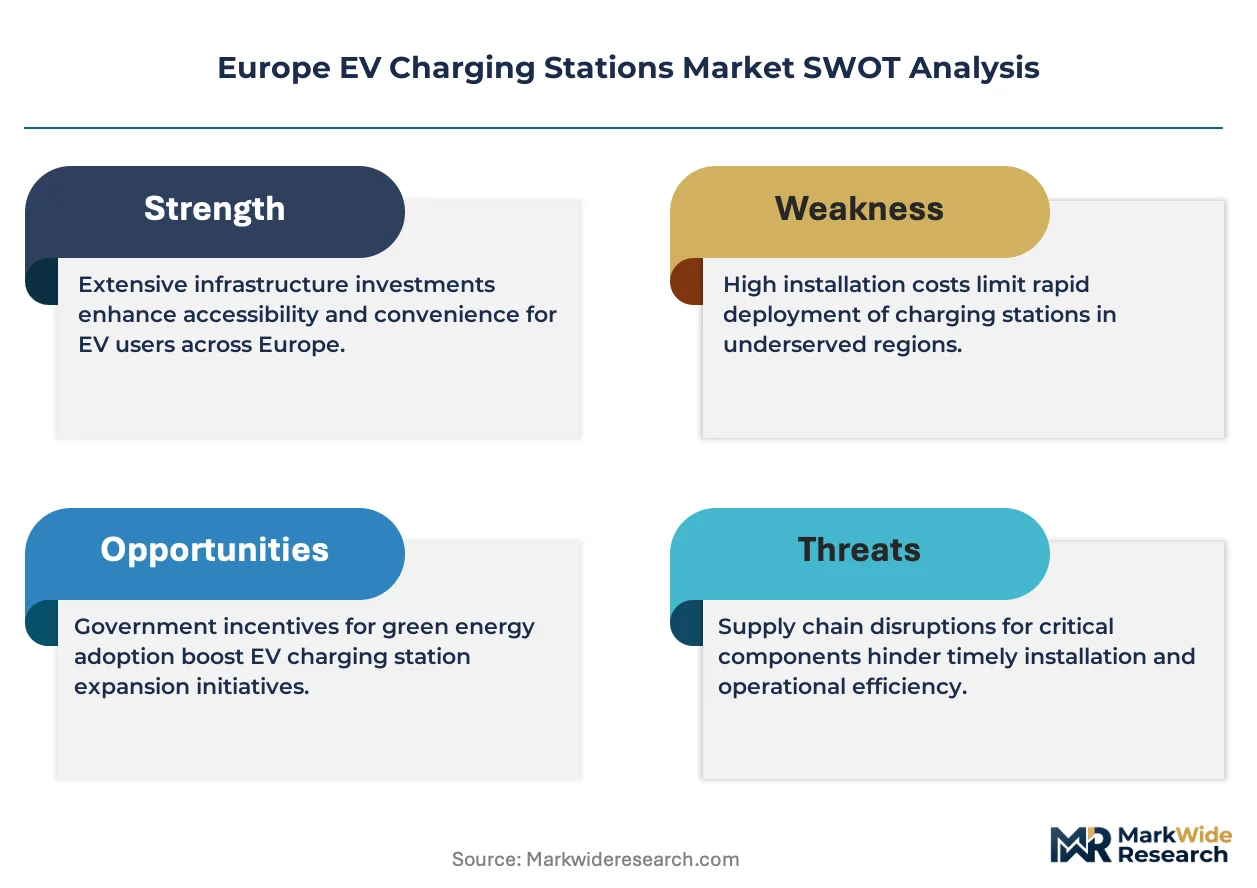
- Grid Capacity Constraints:Local electricity grids in many European regions lack capacity for DC fast charger clusters, requiring costly upgrades that slow deployment.
- Fragmented Permitting:Inconsistent and slow municipal permitting processes, particularly in Southern Europe, create significant delays for new public charging site construction.
- High Capital Expenditure:The substantial upfront cost for DC fast charging hardware and grid connection remains a primary financial barrier for many potential site hosts.
Strategic Opportunities
- Vehicle-to-Grid (V2G) Services:Bidirectional chargers offer new revenue from grid balancing services, particularly in markets with advanced smart grids like the Netherlands.
- Eastern Europe Expansion:Markets like Poland and Romania have low charger density, presenting a significant growth opportunity as regional EV adoption accelerates.
- Charging-as-a-Service Models:Subscription-based offerings for hardware and maintenance can unlock the small business segment by lowering the initial capital investment.
Industry Challenges
- Network Interoperability:Achieving seamless roaming and payment authentication across dozens of competing charging networks in Europe remains a persistent operational hurdle for providing a consistent driver experience.
- Grid Management at Peak Times:Utilities face the immense challenge of managing grid stability as charging demand escalates, particularly from the simultaneous charging of large corporate EV fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe EV Charging Stations Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: AC Slow Charger, DC Fast Charger, Wireless Charger, Ultra-Fast Charger Installation Setting: Residential Complexes, Commercial Buildings, Public Car Parks, Fleet Depots, Hospitality Venues Charging Network Model: Proprietary Network, Open Network, Hybrid Network, Peer-to-Peer Network End User Segment: Individual Vehicle Owners, Municipal Governments, Corporate Fleets, Rental Agencies |
| Companies Covered | Electromaps, Octopus Electroverse, BYD, Electra, Hubject, Wallbox, Moeve, Hitachi Energy, Ionity, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe EV Charging Stations Market Strategic Shifts & Innovations
The competitive landscape is shifting from a pure hardware focus towards integrated software platforms and intelligent energy management. This evolution prioritizes network efficiency, driver experience, and grid integration over the simple provision of power.
Smart charging software, which optimizes charging sessions based on grid conditions and electricity prices, is becoming a standard feature in new AC and DC chargers. Residential users and commercial fleet managers are rapidly adopting these solutions to minimize electricity costs and reduce strain on local electrical circuits. The market's value proposition is migrating from selling kilowatt-hours to providing sophisticated energy management services that integrate with smart homes and building management systems.
Europe's Alternative Fuels Infrastructure Regulation (AFIR) establishes mandatory deployment targets for public charging stations along the TEN-T transport network. This regulation forces member states to ensure minimum power outputs and charger densities, creating a guaranteed infrastructure pipeline for manufacturers. High-power charging providers are most affected, as they must accelerate network build-out on major transit corridors to meet legally binding deadlines.
A significant shift is occurring away from closed, subscription-only charging networks towards open-access payment models. Drivers are increasingly demanding the convenience of ad-hoc payment via contactless credit cards or QR codes, reducing reliance on multiple network-specific RFID cards and apps. This trend is most pronounced in Germany and the Netherlands, where consumer protection regulations have accelerated the adoption of open payment terminals on new DC fast chargers.
Europe EV Charging Stations Market Segmentation
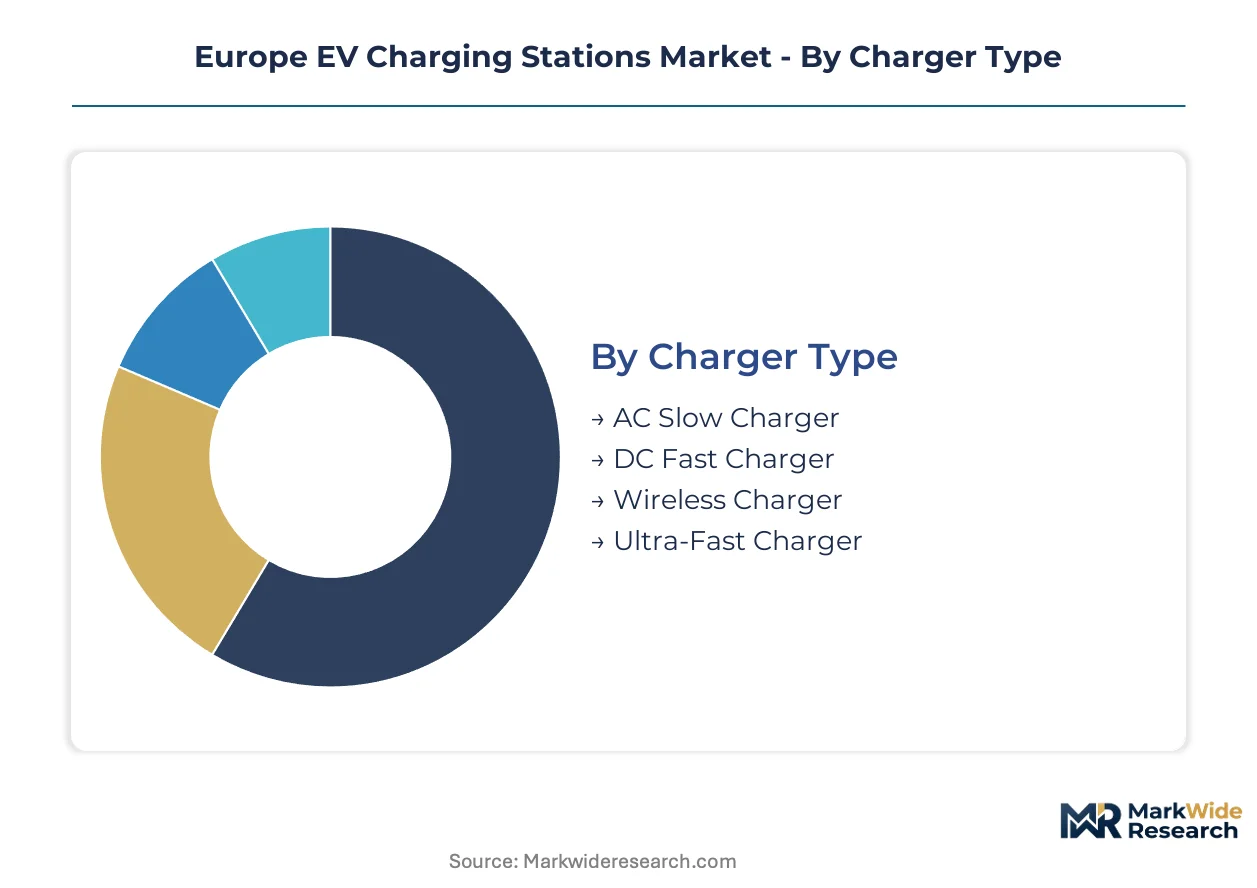
The Europe EV charging stations market is multifaceted, requiring a granular understanding of its various components to identify growth vectors and operational challenges. Segmentation provides a structured view of the market, highlighting distinct product offerings, deployment environments, network philosophies, and end-user demands across the European landscape.
Charger Type:
The operational characteristics and power delivery of EV charging stations are primarily defined by their charger type.
- DC Fast Charger:These units provide significant power output, typically exceeding 50 kW, leveraging standards like the Combined Charging System (CCS). Demand for these chargers is concentrating in public car parks and along major transit corridors to alleviate driver range anxiety throughout Europe.
- AC Slow Charger:AC units typically use the Type 2 connector, offering lower power output suitable for extended charging sessions. Residential complexes and workplace charging in European cities drive demand due to their lower hardware costs and grid compatibility.
- Ultra-Fast Charger:Represents the highest tier of DC charging, often exceeding 150 kW, for rapid top-ups on European highways.
- Wireless Charger:Emerging technology using inductive charging pads, currently seeing limited deployment in pilot projects within specific European urban areas.
AC Slow Charger commands the established base. The steepest expansion runs through DC Fast Charger.
Installation Setting:
Deployment locations for EV charging infrastructure reflect diverse user needs and operational requirements across the continent.
- Fleet Depots:Dedicated charging infrastructure supports the electrification of corporate and logistics fleets, ensuring operational readiness. European corporations are investing heavily in depot charging to meet sustainability targets and regulatory mandates.
- Public Car Parks:These locations offer convenient charging access for drivers during daily activities, often featuring a mix of AC and DC units. Urban centers in Germany and the Netherlands are prioritizing public car park installations to support daily EV usage.
- Residential Complexes:Chargers installed in multi-unit dwellings or private homes, primarily AC units, cater to overnight charging needs for individual owners.
- Commercial Buildings:Workplace charging solutions and visitor charging points are integrated into office parks and retail centers, enhancing employee and customer convenience.
- Hospitality Venues:Hotels, restaurants, and leisure facilities provide charging as an amenity, attracting EV drivers and extending their stay.
Deployment in Residential Complexes currently holds the largest volume. Fleet Depots are rapidly gaining share due to corporate electrification mandates.
Charging Network Model:
The operational structure and access protocols define how charging services are delivered to European EV drivers.
- Open Network:These platforms allow interoperability and access for various EV drivers, often through eRoaming agreements or standardized payment methods. Hubject's eRoaming platform exemplifies this model, connecting disparate networks across Europe for unified driver access.
- Proprietary Network:Operated by a single entity, these networks typically offer exclusive access or preferential rates to their own customers. Ionity specializes in building out its proprietary high-power charging network along major European transit corridors for premium EV brands.
- Hybrid Network:Combines elements of both proprietary and open models, offering a mix of exclusive and public access options to optimize resource utilization.
- Peer-to-Peer Network:Decentralized models where individuals can share their private charging points, fostering community-based charging solutions in urban areas.
The market is currently dominated by Proprietary Network models. However, Open Network approaches are experiencing accelerated adoption due to regulatory pressure and consumer demand.
End User Segment:
Demand for EV charging infrastructure varies significantly across different user groups within the European market.
- Corporate Fleets:Businesses transitioning their vehicle fleets to electric models require extensive charging solutions for depots, workplaces, and employee homes. The EU Green Deal and corporate sustainability goals are compelling European companies to electrify their operations, driving bulk demand.
- Individual Vehicle Owners:Private consumers who own electric vehicles require home charging solutions and access to public infrastructure for longer journeys. Residential complexes and public car parks cater to these owners, with AC slow chargers being a common choice for daily use.
- Municipal Governments:Local authorities invest in public charging infrastructure to support urban EV adoption and meet regional environmental targets.
- Rental Agencies:Car rental companies are increasingly electrifying their fleets, necessitating charging solutions at rental hubs and partner locations across Europe.
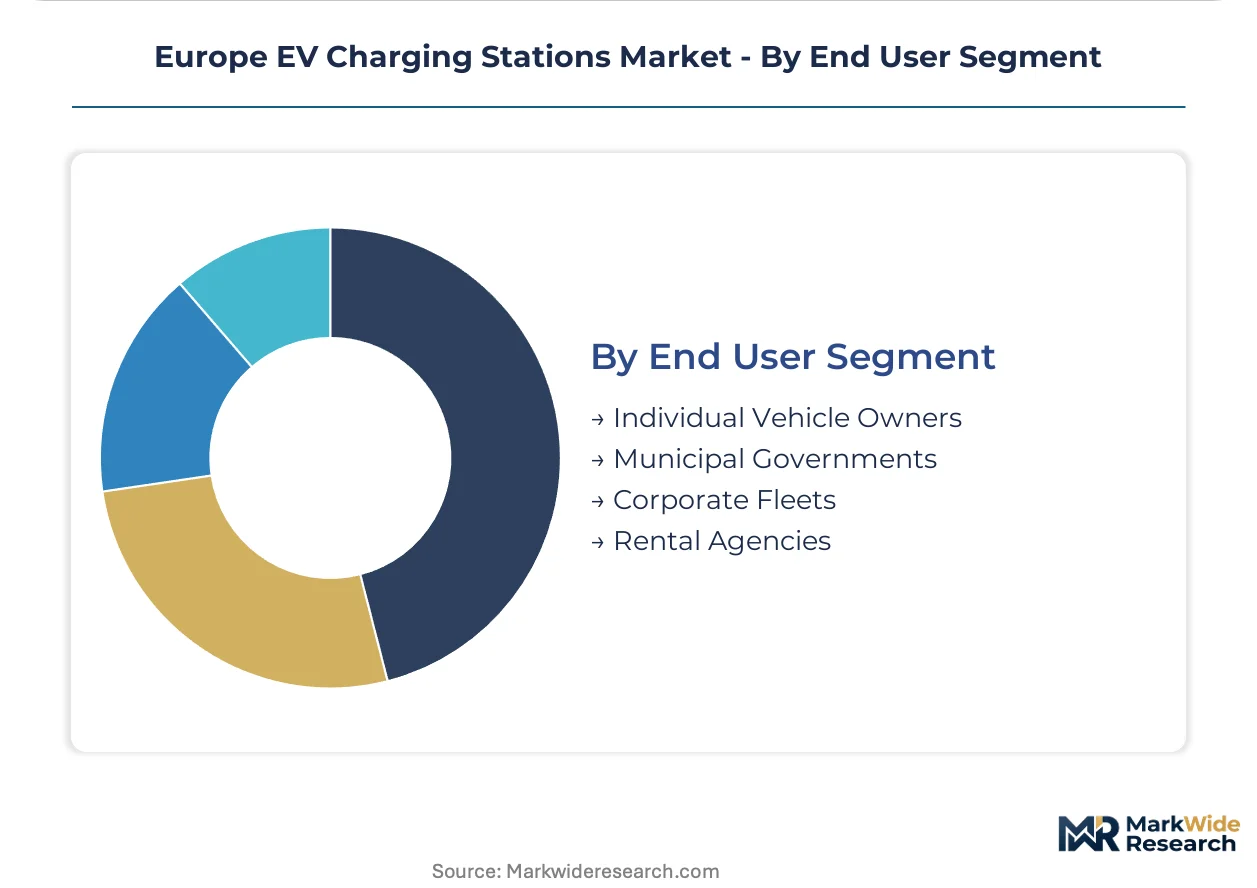
Individual Vehicle Owners represent the largest installed base. Demand from Corporate Fleets is expanding most quickly due to policy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate fleets and individual owners represent the primary buyer archetypes driving demand for EV charging infrastructure across Europe. This diverse user base necessitates a varied approach to deployment and technology. Policy mandates from the EU Green Deal consistently shape investment priorities.
Germany
Germany's robust federal subsidies accelerate the deployment of charging points, particularly for corporate fleet electrification. The German government's Ladeinfrastrukturprogramm supports both public and private charging installations. Berlin's urban planning integrates public charging solutions into new developments, supporting daily EV usage.
France
French individual vehicle owners consistently seek convenient public charging access for daily commutes and longer journeys. The country's ADVENIR program incentivizes the installation of private and public charging infrastructure. Paris actively prioritizes smart charging solutions in residential complexes to manage grid demand.
Netherlands
Dutch municipalities drive significant investment in public car park charging to address driver range anxiety. The national government's Climate Agreement sets ambitious targets for EV adoption and charging density. Amsterdam leads in Vehicle-to-Grid (V2G) pilot projects, exploring new revenue streams for grid balancing.
Poland
Poland experiences rapidly expanding demand from corporate fleets as companies electrify their logistics operations. The Polish government's National Framework for Alternative Fuels Infrastructure Development aims to accelerate network build-out. Warsaw is seeing increased deployment of depot charging solutions for commercial vehicles.
Italy
Italian individual vehicle owners require accessible AC slow chargers for overnight charging in residential settings. The country's national Electric Mobility Support Fund provides financial incentives for charging infrastructure. Milan focuses on integrating charging points within existing urban parking structures to enhance convenience.
Europe EV Charging Stations Market Key Industry Players
Channel-controlling players compete with product-specialist players across the Europe EV charging stations market, creating a dynamic competitive environment. The landscape exhibits a tiered structure, with large energy companies and automotive OEMs forming one tier, while dedicated hardware manufacturers and software platform providers form another. Strategic archetypes include comprehensive network operators, specialized hardware innovators, and critical eRoaming platform providers that ensure connectivity. Companies primarily engage in strategic partnerships, geographic expansion into underserved regions, and portfolio diversification to secure competitive positioning.
Specialists in interoperability and high-power networks, Hubject exemplifies the open network model across Europe, facilitating seamless driver access and payment authentication for a consistent user experience. Ionity, conversely, represents a proprietary high-power charging network, primarily serving premium EV brands along major European transit corridors with rapid top-up capabilities for long-distance travel. Wallbox occupies a position as a leading hardware innovator, focusing on residential and semi-public AC charging solutions, integrating smart charging software for optimized energy management and cost savings. Electromaps also plays a role in connecting drivers to available charging points through its platform, enhancing accessibility.
| Leading Market Players |
|---|
| Electromaps |
| Octopus Electroverse |
| BYD |
| Electra |
| Hubject |
| Wallbox |
| Moeve |
| Hitachi Energy |
| Ionity |
| Others |
Cost & Logistics Intelligence
European charging infrastructure build-out, driven by AFIR mandates, dictates supplier behavior and pricing posture. This rapid expansion creates both demand for hardware and pressure on installation costs.
Pricing Analysis
Installation contracts for public charging infrastructure often follow a cost-plus model, indexed to raw material costs like copper and steel. The dominant end-user pricing combines subscription-based services with transactional ad-hoc payments. Price differentiation stems from charger power output, integrated smart charging software, and bundled after-sales service. Pricing pressure intensifies from regulatory mandates for open access, making individual vehicle owners highly price-sensitive.
Supply Chain Analysis
Export-control regimes impacting advanced power semiconductor components, primarily from East Asian manufacturers, limit the free flow of critical hardware for EV chargers. Geographic supply concentrates in China, Germany, and South Korea for finished hardware and key components. The supply chain relies on power semiconductors, copper, and specialized plastics. Geopolitical tensions affecting component supply present a structural risk, while distribution runs through direct sales to large network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe EV charging stations market presents a defensive-moat story, primarily due to regulatory entrenchment from EU mandates. These regulations create predictable demand and high barriers to entry for new infrastructure providers.
For Market Incumbents: Build a regulatory moat by proactively engaging with EU and national policymakers on infrastructure standards. Consolidate market share through strategic acquisitions of smaller network operators, especially in underserved Eastern European regions like Poland. This mitigates the threat from fragmented new entrants. Invest in advanced smart grid integration R&D to manage peak demand challenges.
For New Entrants and Emerging Players: Establish a beachhead in Eastern European markets like Romania, where charger density remains low. Focus on niche segments such as Vehicle-to-Grid (V2G) services for commercial fleets, leveraging advanced software platforms. Offer Charging-as-a-Service models to small businesses, lowering initial capital investment barriers. This go-to-market angle captures underserved segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the public fast charging and fleet depot segments due to grid upgrade requirements. The long-term viability for this market spans a 5-10 year window, driven by sustained EV adoption. Target acquisition archetypes include specialized software platform providers or regional hardware installers. The signal to watch is the pace of grid infrastructure upgrades in Southern Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate DC Fast Charger Deployment | Addresses driver range anxiety and meets AFIR mandates on major European transit corridors. |
| Develop Advanced Smart Charging Software | Optimizes energy management for corporate fleets and reduces strain on local electricity grids. |
| Form eRoaming Partnerships | Enhances network interoperability and improves the seamless charging experience for European EV drivers. |
| Expand into Eastern Europe | Captures low-density markets like Poland and Romania as regional EV adoption accelerates. |
| Invest in Vehicle-to-Grid (V2G) Technology | Unlocks new revenue streams from grid balancing services in markets with advanced smart grids. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews. These discussions involved network operators, utility planning officers, corporate fleet managers, and charging hardware manufacturers. Secondary validation utilized EU Green Deal directives, AFIR regulations, national subsidy program details, and relevant industry publications. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
The analytical framework was calibrated against historical market trends and future policy trajectories across the analysis window. Segmentation dimensions modeled included charger type, installation setting, network model, and end-user segment. Compound annual growth rates were derived by projecting EV adoption rates and infrastructure deployment targets. Key forecast inputs included EV sales forecasts and national charging point subsidy programs.
Sensitivities concentrate around unforeseen regulatory shifts, grid capacity constraints, and geopolitical events impacting component supply. Forecasts reflect assumptions documented at the time of publication. Material shifts in EU policy or energy infrastructure investment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Electric Car Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Solar Carport Charging Station Market