
 North America Lead Acid Battery Market | 2026-2036
North America Lead Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
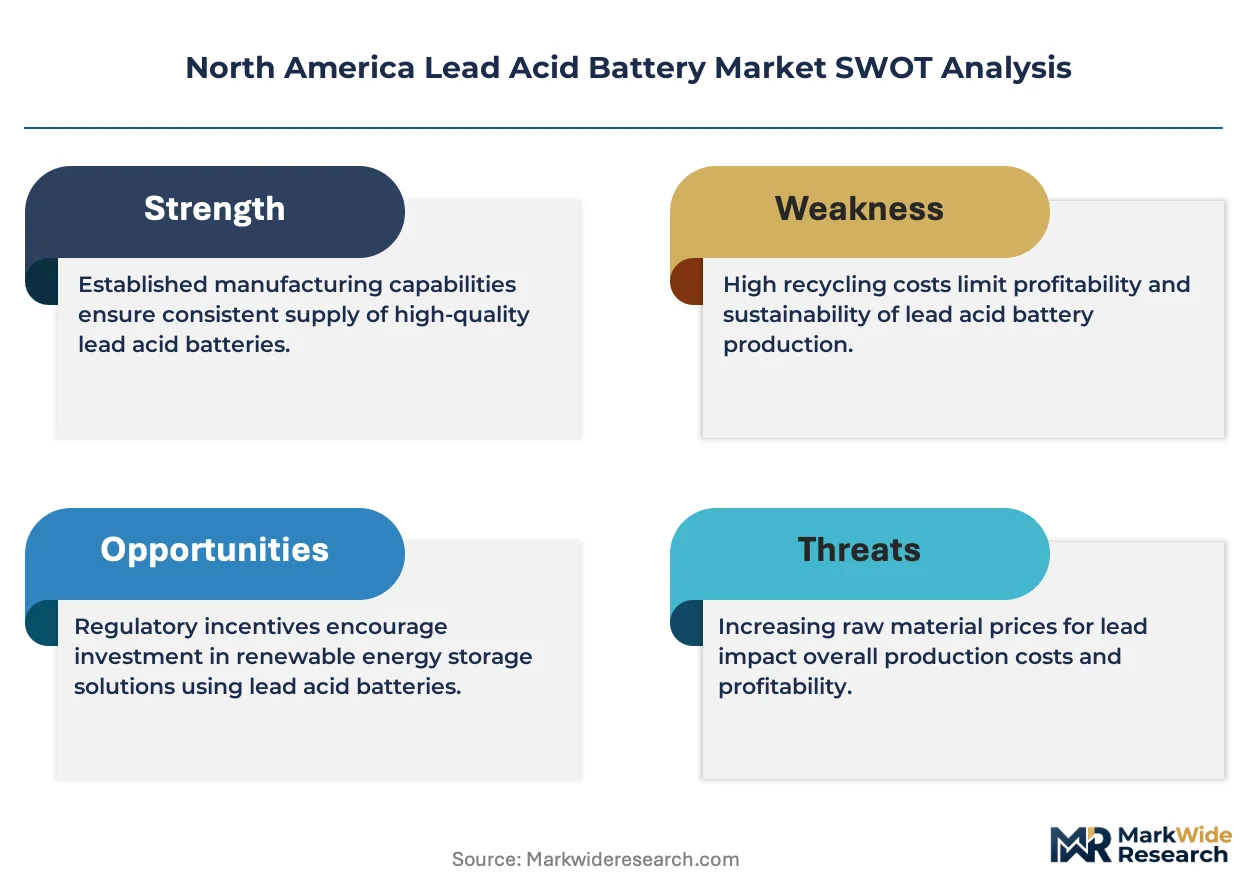
North America Lead Acid Battery Market Insights
The aftermarket battery distribution channel is rewriting competitive access across North America. Clarios leverages its recycling infrastructure to secure closed-loop material flows. East Penn Manufacturing Co. anchors production scale in Pennsylvania while competing on heavy-duty fleet contracts. EnerSys Inc. specializes in industrial motive power applications across Mexican manufacturing corridors.
North America lead acid batteries employ lead dioxide cathodes, sponge lead anodes, and sulfuric acid electrolyte in cells delivering 2V nominal potential, assembled for 6V or 12V service. SLI products dominate replacement demand across passenger vehicle fleets, though VRLA designs are displacing flooded units in telecom and UPS installations where maintenance access proves costly. AGM technology captures premium positioning in start-stop automotive applications, while gel variants serve renewable energy storage in off-grid solar deployments across the Southwest.
EPA enforcement of the Battery Act shapes recycling economics, while OSHA standards govern manufacturing plant emissions and worker exposure limits in U.S. production facilities. Transport Canada administers parallel hazardous materials regulations affecting cross-border battery shipments. Stakeholders must monitor how state-level extended producer responsibility frameworks in California and New York reshape collection network economics and compliance costs.
Market Dynamics
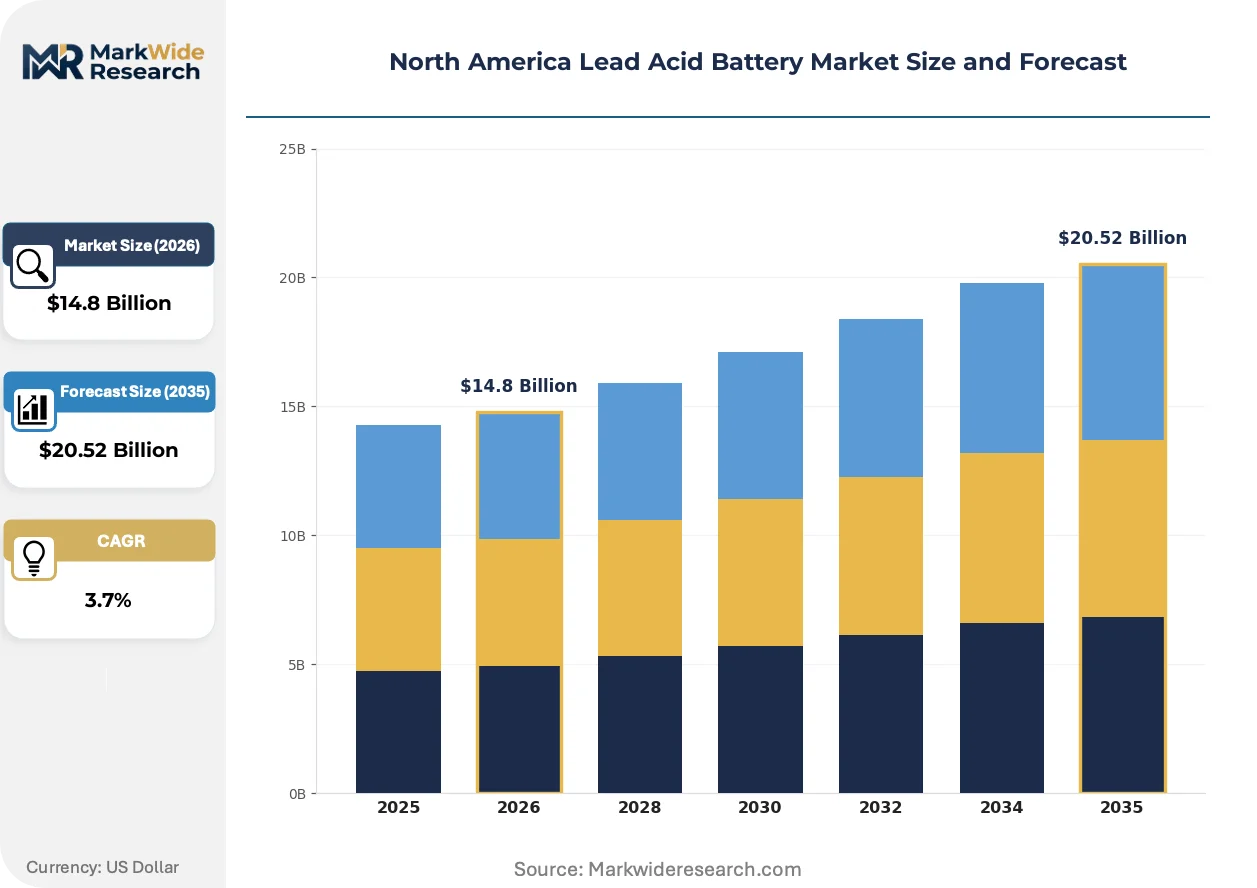
The North America lead acid battery market is experiencing structural compression as data center UPS demand in Texas and Virginia collides with tightening EPA Battery Act enforcement on recycling compliance, forcing producers to reconfigure material recovery networks while scaling for automotive start-stop volumes.
Growth Catalysts
- Data center UPS expansion:Hyperscale facilities across Texas and Virginia are procuring VRLA systems at accelerated rates, creating dedicated demand corridors for industrial battery suppliers.
- EPA Battery Act enforcement:Tighter material recovery standards are legitimizing closed-loop recyclers and penalizing non-compliant collectors, consolidating legitimate supply channels.
- Automotive start-stop proliferation:AGM technology penetration in United States and Mexico passenger vehicle fleets is generating premium product demand with higher lead throughput per unit.
Market Restraints
- Lead price volatility:London Metal Exchange lead pricing swings directly compress margin structures for flooded battery producers serving price-sensitive replacement markets.
- Smelter concentration risk:Primary lead refining capacity concentrates in Missouri and secondary smelting in Texas, creating geographic single-point vulnerabilities for North American supply security.
- Lithium-ion substitution:Forklift motive power and telecom backup applications are migrating to lithium iron phosphate systems where total cost of ownership calculations favor chemistry switching.
Strategic Opportunities
- Mexican manufacturing corridors:Industrial motive power demand from automotive OEM plants in Querétaro and Guanajuato remains underpenetrated by regional battery service networks.
- California EPR frameworks:Extended producer responsibility mandates in California and New York are creating first-mover advantages for producers with pre-positioned collection infrastructure.
- AGM-gel convergence:Hybrid electrolyte formulations combining AGM cycle life with gel temperature tolerance are opening renewable energy storage applications in Southwest off-grid solar deployments.
Industry Challenges
- Smelter technician scarcity:Lead battery recycling facilities face acute shortages of pyrometallurgical engineers qualified under OSHA lead exposure monitoring protocols.
- Cross-border hazmat friction:Transport Canada and DOT harmonization gaps in UN 2794 classification are delaying just-in-time battery shipments between Ontario and Michigan assembly plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lead Acid Battery Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.52 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLI, VRLA, Flooded, AGM End User: Automotive, Industrial, UPS, Renewable Energy Application: Start-Stop Systems, Backup Power, Electric Vehicles, Heavy Duty Vehicles Technology: Lead-Crystal, Gel, Lithium-ion, Hybrid |
| Companies Covered | Clarios, Johnson Controls Inc., East Penn Manufacturing Co., Exide Technologies Inc., EnerSys Inc., C&D Technologies Inc., Crown Battery Manufacturing Company, GS Yuasa Corporation, NorthStar Battery Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lead Acid Battery Market Trends and Innovations
Technology virtualization and regulatory tightening are restructuring how lead acid batteries are manufactured, distributed, and recovered across the United States, Canada, and Mexico, with digital integration and compliance automation emerging as the dominant vectors of change.
Carbon-enhanced negative active material formulations are virtualizing traditional lead sponge anode architectures by embedding conductive additives that reduce sulfation and extend partial state-of-charge cycling life. Telecom operators and data center engineers are specifying these enhanced AGM designs for remote installations where maintenance access carries premium labor costs. The technology is virtualizing the conventional trade-off between upfront battery cost and service life, compressing replacement cycles and reshaping procurement evaluation frameworks.
EPA enforcement of the Battery Act is mandating real-time tracking of spent battery flows from generator through smelter, with digital manifests replacing paper documentation. This regulatory shift is disqualifying informal collectors and consolidating legitimate recycling channels under permitted facility networks. United States-based aftermarket distributors are responding by integrating reverse logistics software that automates compliance documentation and optimizes collection route density.
Fleet operators are unbundling battery procurement from vehicle acquisition, creating standalone power system contracts with performance guarantees and remote monitoring obligations. This purchasing pattern shift is displacing traditional distributor markup structures with direct manufacturer-to-fleet relationships backed by telematics-enabled service level agreements. The transformation is most visible in heavy-duty trucking corridors across the Interstate 35 and Interstate 10 corridors where large fleet concentration enables scale-based contracting.
North America Lead Acid Battery Market Segmentation
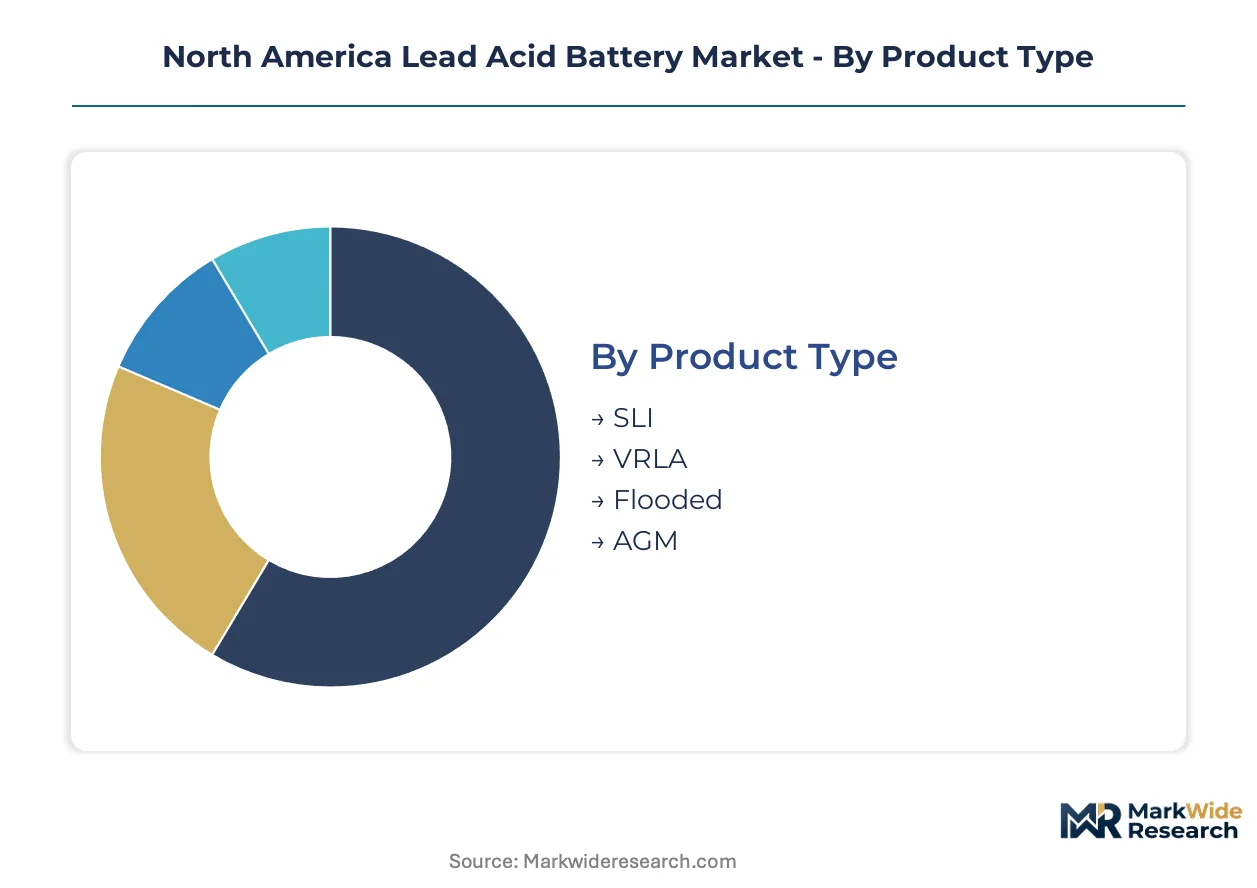
Lead acid battery segmentation across North America reflects divergent technical requirements between automotive OEM specifications and industrial duty cycles. Product architecture, end-use environment, and discharge profile determine margin structures and supplier positioning in each category.
Product Type:
The use-case spectrum spans cranking intensity in passenger vehicles through deep-cycle endurance in renewable installations.
- SLI:Starting, lighting, and ignition batteries employ thin-plate construction optimized for high-current bursts. Replacement demand concentrates across United States passenger vehicle fleets where start-stop system proliferation is elevating AGM substitution rates.
- VRLA:Valve-regulated lead acid designs seal electrolyte within absorbed glass mat or gel matrices, eliminating maintenance access requirements. Data center UPS installations across Texas and Virginia are specifying these units for confined rack spaces where spill containment proves costly.
- Flooded:Conventional vented-cell construction with free-flowing sulfuric acid electrolyte dominates price-sensitive aftermarket replacement. Mexican commercial vehicle fleets and agricultural equipment operators favor these units for serviceability in remote locations.
- AGM:Absorbed glass mat separators immobilize electrolyte while enabling higher compression and faster charge acceptance. Premium automotive start-stop applications in the United States and Canada specify AGM for vibration resistance and cycle life under micro-hybrid duty.
Established volume favors SLI; emerging adoption favors AGM.
End User:
Customer archetypes range from high-volume OEM procurement through fragmented aftermarket service networks.
- Automotive:OEM and aftermarket channels serving passenger cars, light trucks, and commercial vehicles. United States start-stop system mandates and Mexican vehicle production growth are concentrating procurement volumes with AGM-capable suppliers.
- Industrial:Forklift motive power, mining equipment, and material handling systems requiring deep-cycle endurance. Querétaro and Guanajuato automotive manufacturing corridors are generating unmet demand for regional battery service networks.
- UPS:Uninterruptible power supply installations protecting critical infrastructure from grid instability. Hyperscale data center construction across Northern Virginia and Dallas-Fort Worth is expanding VRLA procurement at utility-scale volumes.
- Renewable Energy:Off-grid solar and wind storage applications in Southwestern United States and remote Canadian territories. Gel and carbon-enhanced AGM variants are penetrating these installations where temperature extremes stress conventional designs.
Automotive commands present revenue concentration; renewable energy is climbing the fastest.
Application:
Duty cycle intensity and discharge depth separate architectural requirements across mobility and stationary contexts.
- Start-Stop Systems:Micro-hybrid vehicle architectures demanding 5-10x cycle life versus conventional SLI. United States EPA fuel economy standards and California CARB mandates are accelerating OEM fitment rates.
- Backup Power:Standby discharge applications in telecom, healthcare, and data center infrastructure. Virginia and Texas grid reliability concerns are extending runtime requirements beyond traditional 15-minute UPS designs.
- Electric Vehicles:Low-speed and neighborhood electric vehicles utilizing lead acid for cost containment. Golf cart fleets and campus mobility systems across Arizona and Florida retirement communities sustain niche demand.
- Heavy Duty Vehicles:Commercial trucking, construction, and agricultural equipment requiring vibration tolerance and cold-cranking reliability. Interstate 35 and Interstate 10 corridor fleets are unbundling battery procurement from vehicle acquisition.
Backup power anchors present installed base; start-stop systems are gaining share fastest.
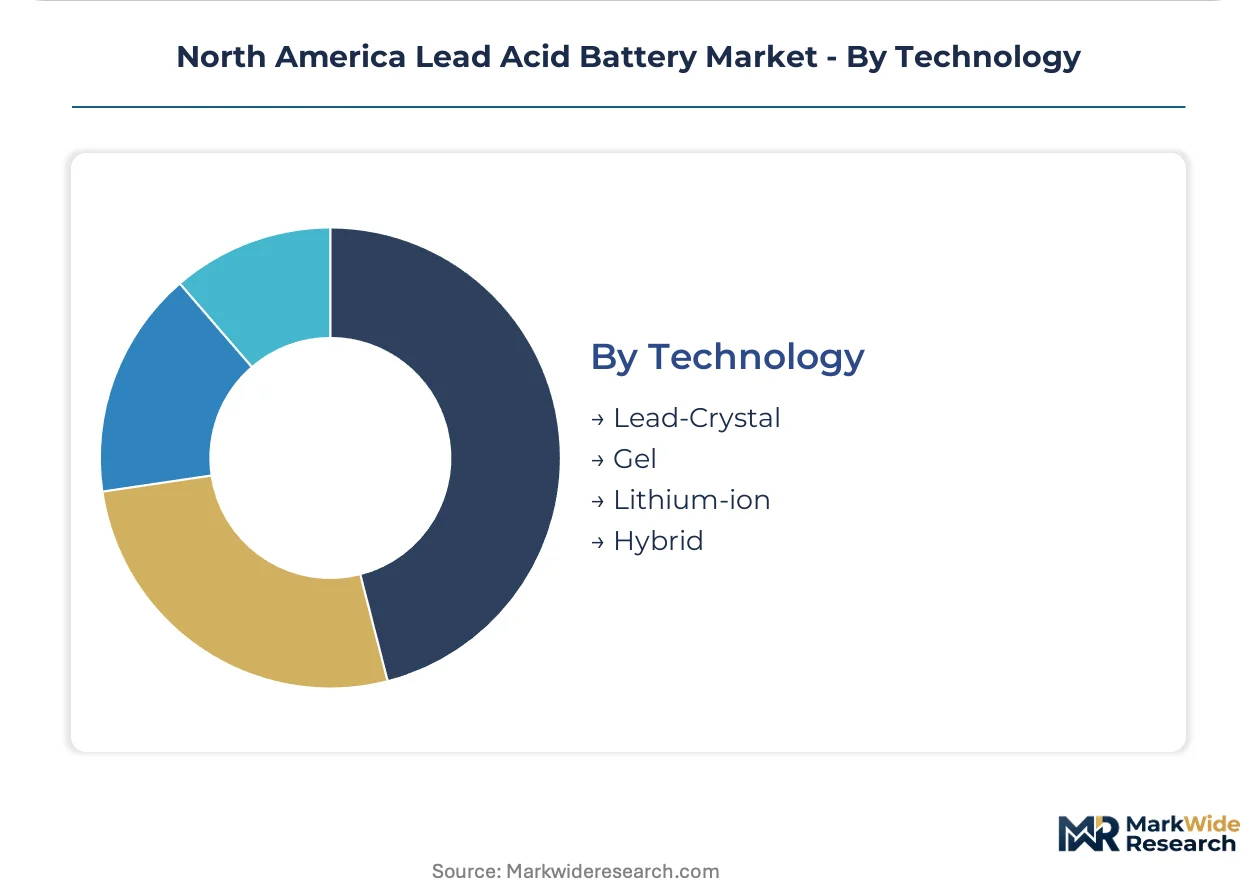
Technology:
Material science differentiation separates incumbent lead architectures from hybrid and alternative chemistries.
- Lead-Crystal:Silicon-doped electrolyte formulations claiming enhanced cycle life and temperature tolerance. Southwest off-grid solar installers are field-testing these units against conventional gel alternatives.
- Gel:Silica-thickened electrolyte immobilization for deep-cycle applications with minimal gassing. Renewable energy storage across Arizona and New Mexico desert installations favors gel for thermal stability.
- Lithium-ion:Competing chemistry penetrating forklift motive power and telecom backup where total cost of ownership calculations favor energy density advantages. California and New York industrial facilities are piloting conversions.
- Hybrid:Dual-chemistry systems combining lead acid cost structure with lithium-ion peak power supplementation. Experimental configurations in United States military and aerospace applications test viability for extreme temperature cycling.
Gel dominates renewable storage economics; lead-crystal represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 10 and Interstate 35 freight corridors anchor North American lead acid battery logistics, connecting Gulf Coast smelters to Midwest assembly plants and Mexican manufacturing zones.
United States
Texas and Virginia hyperscale data centers are procuring VRLA systems at utility-scale volumes for UPS redundancy. EPA Battery Act enforcement mandates real-time tracking of spent battery flows from generator through permitted smelters. Dallas-Fort Worth and Northern Virginia clusters concentrate procurement decisions for telecom and data center operators.
Mexico
Querétaro and Guanajuato automotive manufacturing corridors generate unmet demand for industrial motive power battery service networks. Mexican environmental regulations under SEMARNAT are tightening hazardous waste handling standards for battery recyclers. Mexico City Metro serves as the distribution hub for aftermarket battery flows to central and southern regions.
Canada
Ontario mining equipment fleets and Alberta oilfield operations sustain deep-cycle battery demand for extreme temperature duty. Transport Canada administers UN 2794 hazardous materials classifications affecting cross-border battery shipments to Michigan assembly plants. Toronto and Montreal anchor distribution networks serving provincial industrial markets.
North America Lead Acid Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and cell fabrication. The North America lead acid battery market consolidates around three strategic archetypes: closed-loop recyclers leveraging permitted smelter networks, regional manufacturers anchoring heavy-duty fleet contracts, and industrial specialists targeting motive power applications. Competitive moves center on backward integration into lead recovery operations and geographic expansion into underpenetrated Mexican manufacturing corridors.
Among North American-based producers, Clarios, East Penn Manufacturing Co., and EnerSys Inc. exemplify the dominant competitive archetypes. Clarios occupies a position as the closed-loop recycling integrator, East Penn Manufacturing Co. anchors scale-driven production in Pennsylvania, and EnerSys Inc. represents the industrial specialization vector targeting Mexican manufacturing demand. These three companies collectively illustrate how competitive positioning stratifies across recycling control, regional manufacturing scale, and end-use vertical focus.
| Leading Market Players |
|---|
| Clarios |
| Johnson Controls Inc. |
| East Penn Manufacturing Co. |
| Exide Technologies Inc. |
| EnerSys Inc. |
| C&D Technologies Inc. |
| Crown Battery Manufacturing Company |
| GS Yuasa Corporation |
| NorthStar Battery Company |
| Others |
Pricing and Supply Chain Analysis
Interstate 10 freight corridors linking Gulf Coast lead smelters to Southwestern distribution hubs impose fuel-surcharge volatility that amplifies cost spreads between concentrated upstream suppliers and dispersed aftermarket buyers, forcing three-tier price stratification across premium AGM, standard flooded, and economy SLI product lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs North American lead acid battery transactions, with AGM start-stop units commanding certification-grade premiums for OEM fitment while flooded aftermarket replacements compete on volume scale and distributor rebate programs. Price differentiation hinges on UL certification tiers and geographic delivery cost to remote service territories. Cost compression in economy SLI tiers is intensifying because London Metal Exchange lead price swings directly squeeze margin structures for non-integrated assemblers. Fleet operators show least price sensitivity due to telematics-backed performance guarantees, while independent repair shops in price-sensitive replacement markets resist premium positioning.
Supply Chain Analysis
Upstream feedstock flows draw from primary lead refining capacity concentrated in Missouri and secondary smelting operations anchored in Texas, with sulfuric acid electrolyte and polypropylene casing materials sourced from regional chemical producers across Louisiana and Alberta. Raw material dependencies rest on lead concentrate imports, recycled battery scrap collection networks, and separator mat supply from glass fiber specialists. Single-source vulnerability concentrates in Missouri primary refining, where any disruption would cascade through North American plate stock availability. Distribution runs through permitted smelter networks feeding regional assembly plants, with reverse logistics channels recovering spent units for closed-loop material recovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified pyrometallurgical engineers under OSHA lead exposure protocols represent the critical capability gap constraining North American recycling expansion, with technician scarcity threatening smelter throughput targets regardless of capital deployment.
For Market Incumbents: Build closed-loop recycling moats by securing permitted smelter network access and integrating reverse logistics software that automates EPA Battery Act compliance documentation. Defensive consolidation should prioritize captive lead recovery capacity to offset London Metal Exchange price volatility, while channel control investments lock in fleet operator direct relationships before lithium-ion substitution accelerates in forklift motive power segments. For New Entrants and Emerging Players: Querétaro and Guanajuato automotive manufacturing corridors offer the most penetrable white-space for industrial motive power battery service networks, with regional OEM plant density outpacing incumbent service coverage. Target aftermarket distribution partnerships with Mexico City Metro hub operators to bypass capital-intensive smelter investments, while positioning carbon-enhanced AGM formulations for Southwest off-grid solar installers seeking temperature-tolerant alternatives to conventional gel designs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded lead acid battery assets lacking recycling integration or Mexican market presence. Long-term viability hinges on positioning for extended producer responsibility framework expansion across California and New York, where pre-positioned collection infrastructure commands regulatory preference. Monitor lithium iron phosphate penetration rates in telecom backup applications as the inflection signal for chemistry-switching acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Recovery | Captive smelter access insulates margin structures from LME price swings. |
| EPA Compliance Automation Platform | Digital manifest systems disqualify informal collectors and consolidate legitimate channels. |
| Querétaro Service Network Expansion | Regional OEM plant density generates unmet industrial motive power demand. |
| Carbon-Enhanced AGM Product Line | Southwest solar installers specify these units for desert temperature extremes. |
| Fleet Telematics Partnership | Direct manufacturer-to-fleet relationships displace traditional distributor markups. |
Research Methodology
Operator-level perspectives from recycling plant managers, OEM battery procurement leads, aftermarket distributor principals, and fleet maintenance directors anchored the qualitative base, cross-referenced against EPA enforcement records, Transport Canada hazmat classification databases, SEC 10-K filings from publicly traded battery producers, and regional vehicle production statistics from IHS Markit. Bottom-up installation forecasts triangulated with top-down lead consumption models derived from London Metal Exchange flow data.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning product architecture, end-use vertical, discharge duty cycle, and regional regulatory cluster dimensions. CAGRs were derived from trend-line extrapolation of historical replacement rates, OEM fitment penetration curves, and data center capex deployment patterns. Key inputs included hyperscale facility pipeline tracking in Northern Virginia and Dallas-Fort Worth, plus start-stop system mandate compliance schedules under EPA fuel economy standards.
The forecast holds incumbent behavior within observed patterns; aggressive moves by lithium iron phosphate specialists or closed-loop recycling integrators would shift outcomes beyond modeled ranges. Cross-checking against London Metal Exchange lead forward curves and regional smelter capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
East Asia Battery Market
Batteries
Indonesia Battery Market
Batteries
South Africa Battery Market
Batteries
West Africa Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Alkaline Secondary Battery Market
Batteries
Power Tool Batteries Market
Batteries
Submarine Batteries Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
UAV Battery Pack Market
Batteries
Aluminum Wire Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market