
 China Oil and Gas Market | 2026-2036
China Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
China Oil and Gas Market Analysis
Digital twin integration across upstream operations is rewriting reservoir management protocols in China's oilfields. CNOOC leverages subsea robotics and real-time analytics to sustain deepwater production economics at the Lingshui field. CNPC anchors western China's pipeline infrastructure, controlling overland flows from Tarim Basin to coastal refineries. Sinopec differentiates through integrated refining-chemical complexes that occupy the higher-margin petrochemical value chain.
The China oil and gas sector encompasses the exploration, extraction, processing, transportation, and distribution of hydrocarbon resources including crude oil with API gravities ranging from light sweet to heavy sour grades, natural gas in conventional and unconventional formations, and derived petrochemical products. Its primary commercial purpose is to supply energy feedstocks for industrial combustion, transportation fuels, and chemical manufacturing precursors. Crude oil extraction remains the revenue foundation, though natural gas and LNG segments are expanding fastest as pipeline imports from Central Asia and seaborne cargoes diversify supply security. The petrochemicals category captures the deepest margin pools, where naphtha crackers and aromatics complexes convert raw hydrocarbons into higher-value plastics and synthetic materials.
MIIT's GB standards for refinery emissions and the National Energy Administration's dual carbon framework are tightening product specifications and capping carbon intensity at major processing facilities. SAMR enforces quality certification for pipeline steels and pressure equipment, shaping procurement standards across state-owned operators. Stakeholders must monitor how provincial carbon allowance trading schemes interact with national production quotas to determine capital allocation timing for downstream upgrades.
Market Dynamics
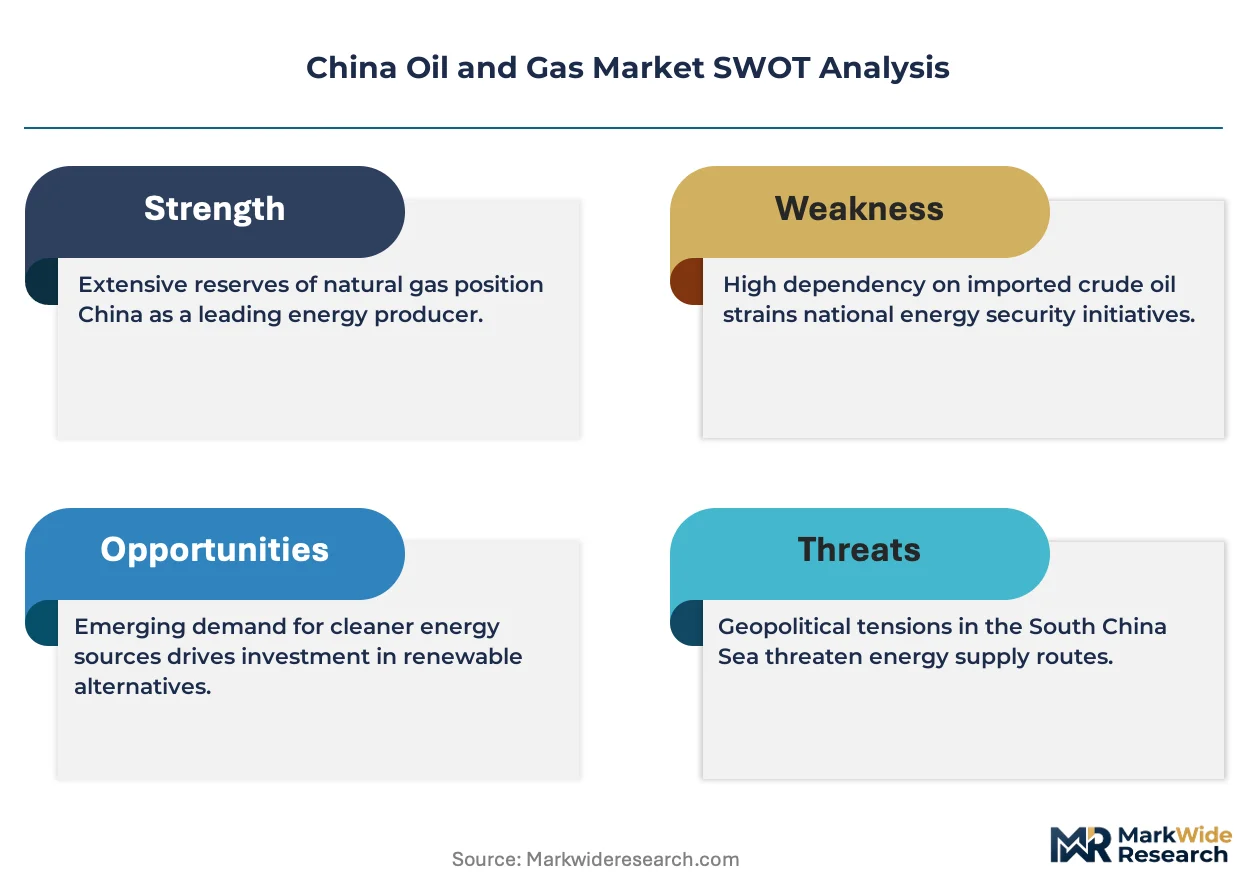
The China oil and gas sector pivots on the collision between MIIT's tightening GB emissions standards and the National Energy Administration's dual carbon framework, which together force processing facilities into expensive carbon capture retrofits while capping throughput expansion permits.
Growth Catalysts
- Tarim Basin pipeline expansion:CNPC's west-to-east trunk lines unlock stranded conventional gas reserves for coastal demand centers, displacing higher-carbon coal in industrial boilers.
- Coal-to-chemical carbon capture mandates:The dual carbon framework channels state capital into retrofitting Shenhua and other CTL complexes with post-combustion capture, preserving feedstock access under tightening MEE oversight.
- Lingshui deepwater robotics:CNOOC's subsea autonomous systems cut deepwater opex enough to sustain production economics at marginal fields previously classified as non-commercial.
Market Restraints
- Middle Eastern crude dependency:Over half of Shandong independent refiners source heavy sour grades from Saudi and Iraqi term contracts, exposing margin compression when OPEC+ withholds supply.
- Tarim Basin geological complexity:Ultra-deep reservoirs with high H2S content require specialized metallurgy that domestic suppliers cannot yet certify to SAMR pressure-equipment standards.
- Coal-to-olefins substitution ceiling:MEE emissions quotas cap naphtha cracker expansion, but coal-based methanol-to-olefins routes face carbon-intensity penalties that erode their cost advantage.
Strategic Opportunities
- Guangdong hydrogen hub development:The province's carbon-market pilot allows refiners to monetize blue hydrogen production from steam methane reforming with CCS, accessing industrial offtake in the Pearl River Delta.
- Small-scale LNG satellite stations:Truck-delivered ISO tank supply chains bypass pipeline access constraints in inland manufacturing clusters along the Yangtze corridor.
- Digital twin reservoir management:Integration of real-time downhole sensors with cloud-based simulation platforms enables CNPC to recover additional barrels from mature Daqing fields without new drilling.
Industry Challenges
- Deepwater subsea engineering talent scarcity:CNOOC and contractors compete for finite crews qualified in high-pressure high-temperature completions, inflating project timelines at Lingshui-phase developments.
- Pipeline steel certification delays:SAMR's GB/T 9711 quality enforcement for X80-grade line pipe creates 8-12 month procurement bottlenecks for trunk line expansions.
- Refinery-chemical complex integration complexity:Sinopec's integrated sites require simultaneous commissioning of hydrocracking and aromatics units, multiplying startup risk when catalyst supply chains destabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Oil and Gas Market |
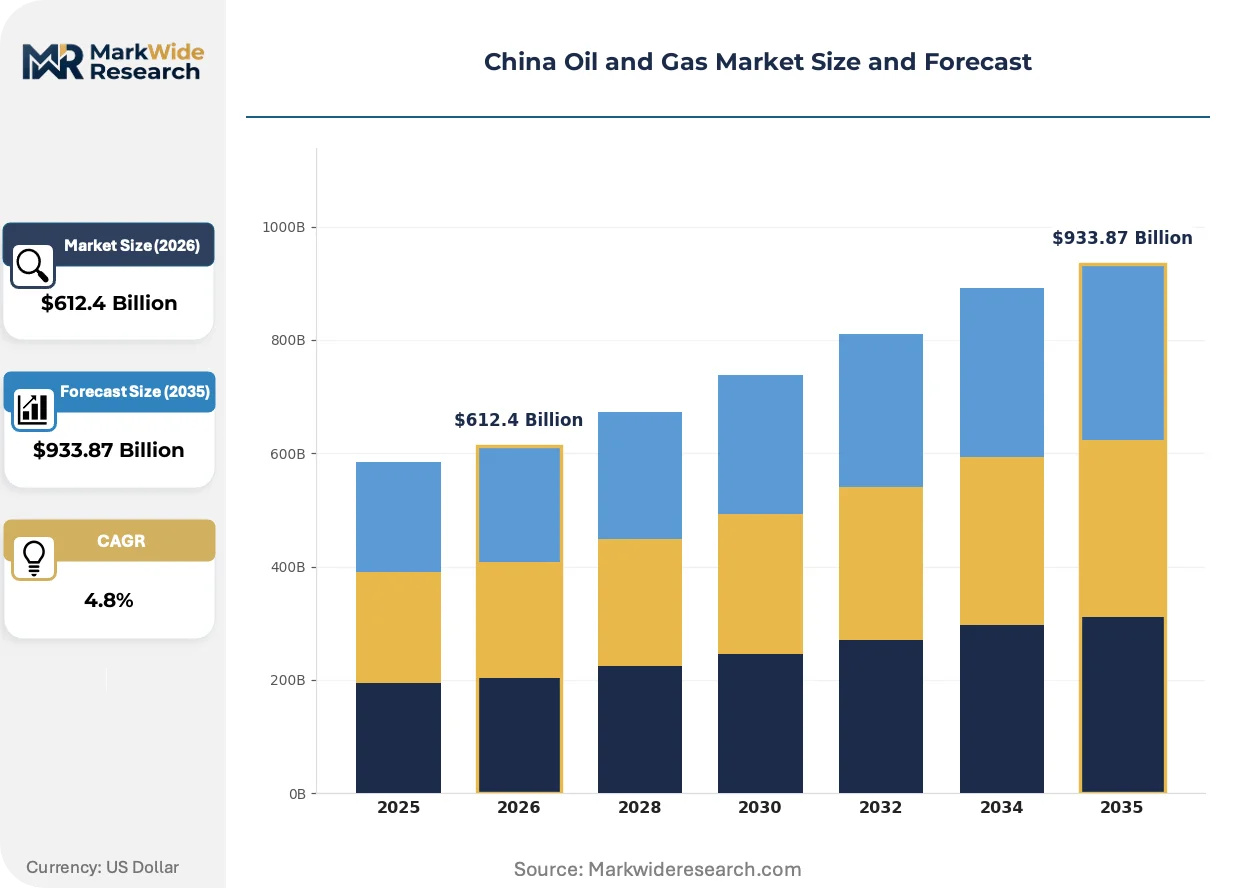
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $933.87 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crude Oil, Natural Gas, Petrochemicals, LNG Application: Industrial, Transportation, Residential, Commercial End User: Utilities, Refineries, Power Plants, Manufacturing Technology: Exploration, Drilling, Refining, Distribution |
| Companies Covered | China National Offshore Oil Corporation (CNOOC), Shaanxi Yanchang Petroleum, China National Petroleum Corporation (CNPC), Shell plc (via CNOOC Joint Ventures), Guanghui Energy Co. Ltd, PetroChina Company Limited, Sinochem Group, SPT Energy Group, Inc., China Petroleum & Chemical Corporation (Sinopec), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Oil and Gas Market Emerging Trajectories
Automation and carbon accounting are rewriting operational protocols across China's hydrocarbon value chain, compressing decision cycles from reservoir to terminal while exposing legacy assets to stranded-cost risk.
Electromagnetic flow metering with edge-computing analytics is migrating from pilot installations at CNOOC's Bohai Bay platforms to standard procurement specifications for new greenfield developments. Offshore engineering divisions now mandate real-time sand detection and multiphase measurement as baseline requirements. This capability compression eliminates manual well testing cycles and enables subsea tieback economics at marginal fields.
MIIT's 2024 GB 31570 revision tightens particulate and sulfur dioxide limits for refinery flue gas, forcing Shandong independents to choose between wet scrubber retrofits or throughput cuts. The standard's phased implementation through 2026 creates uneven compliance timelines between state-controlled and private processors. Coastal refineries with existing desulfurization infrastructure gain permit headroom for chemical expansion, while inland competitors face consolidation pressure.
Long-term offtake contracting is compressing as Yangtze River Delta petrochemical buyers shift from annual term agreements to quarterly price-reopener structures indexed to Platts Dubai and domestic coal benchmarks. Trading desks at major chemical groups now maintain dedicated LNG and naphtha procurement teams that bypass traditional supply intermediaries. This disintermediation concentrates most visibly in Jiangsu province, where integrated chemical parks negotiate direct pipeline connections with receiving terminals.
China Oil and Gas Market Segmentation
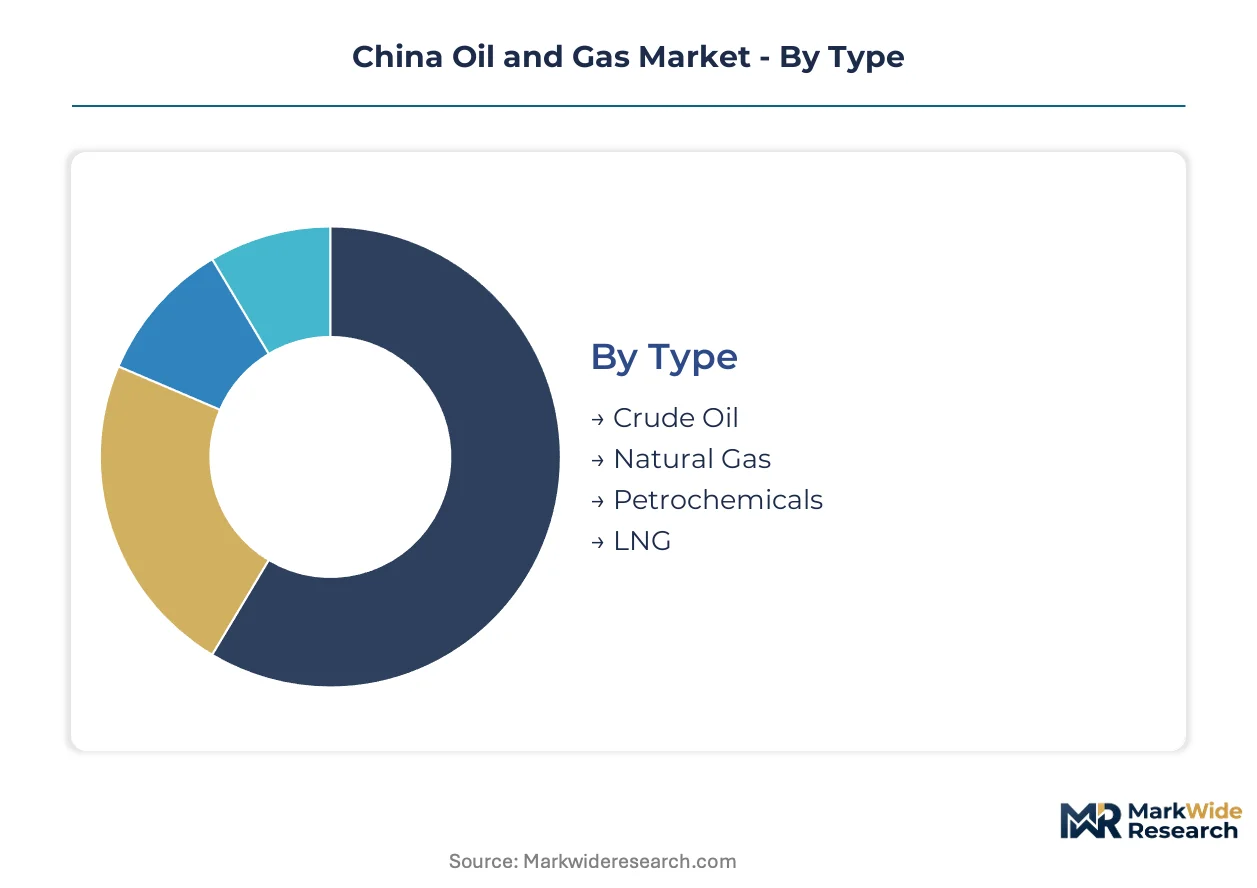
Segmentation reveals how capital cycles diverge across China's hydrocarbon value chain. Exploration assets lock up investment for decades while refining throughput responds to quarterly permit adjustments. Understanding these velocity differences shapes procurement timing and partnership structures.
Type:
Crude oil inventory turns slowest, cycling through strategic reserves and term contracts. LNG cargoes clear fastest, with spot markets repricing weekly. Petrochemicals and natural gas occupy intermediate positions, tied to crackers and pipeline nominations.
- Crude Oil:API gravities range from light sweet (Daqing) to heavy sour (Middle Eastern imports). Shandong independent refiners concentrate demand for discounted heavy grades, though OPEC+ supply withholding compresses margins unpredictably.
- Natural Gas:Conventional pipeline flows from Tarim Basin and Sichuan dominate supply. The Yangtze River Delta manufacturing corridor drives consumption growth as coal displacement accelerates under MEE emissions quotas.
- Petrochemicals:Naphtha crackers and aromatics complexes convert feedstock into plastics precursors. Integrated refining-chemical sites at Sinopec facilities capture margin pools unavailable to standalone processors.
- LNG:Seaborne cargoes diversify supply security beyond pipeline dependence. Small-scale satellite stations in inland provinces bypass infrastructure constraints through truck-delivered ISO tank logistics.
Crude oil dominates installed base. LNG is where expansion concentrates.
Application:
Industrial offtake carries the highest volume concentration. Residential demand shows steadiest load profiles. Transportation and commercial segments split between fuel substitution and stationary combustion needs.
- Industrial:Process heat and chemical feedstock absorption at Jiangsu and Zhejiang manufacturing parks. Dual carbon targets force boiler fuel switching from coal to gas, tightening pipeline nomination windows.
- Transportation:Road fuels face electrification pressure while marine bunkers and aviation kerosene retain hydrocarbon lock-in. Coastal provinces enforce earlier emission standards than inland jurisdictions.
- Residential:Urban district heating networks and distributed gas supply. Northern provinces prioritize winter heating security over cost optimization.
- Commercial:Hospitality and retail cooling loads. Peak shaving requirements align with industrial demand patterns in dense urban clusters.
Industrial applications command volume leadership. Transportation is climbing the fastest.
End User:
Refineries anchor procurement scale with continuous throughput requirements. Power plants face dispatch competition from renewables. Manufacturing and utilities segment by reliability tier.
- Utilities:Grid-connected gas turbines and peaking plants. Provincial dispatch curves increasingly favor renewables, compressing gas plant utilization hours.
- Refineries:Complex processing units at Sinopec and CNPC facilities. Shandong independents operate simpler configurations with lower conversion complexity.
- Power Plants:Combined-cycle installations in coastal load centers. Carbon allowance trading schemes alter merit order dispatch against coal baseload.
- Manufacturing:Petrochemical precursors and process energy. Yangtze corridor chemical parks negotiate direct pipeline connections to receiving terminals.
Refineries dominate installed base. Manufacturing is gaining share fastest.
Technology:
Exploration and drilling absorb capital longest, with decade-long development timelines. Refining and distribution monetize throughput within quarterly cycles. Technology selection locks in carbon intensity profiles for asset lifetimes.
- Exploration:Seismic imaging and reservoir characterization across Tarim Basin ultra-deep formations. CNOOC deploys subsea robotics at Lingshui to sustain deepwater economics.
- Drilling:High-pressure high-temperature completions in sour gas environments. Domestic metallurgy suppliers struggle to certify equipment to SAMR pressure-equipment standards.
- Refining:Hydrocracking and aromatics integration at Sinopec complexes. MIIT's GB 31570 revision forces wet scrubber retrofits or throughput reductions.
- Distribution:West-to-east trunk lines and coastal receiving terminals. X80-grade line pipe procurement faces 8-12 month certification delays under GB/T 9711 enforcement.
Distribution infrastructure dominates installed base. Exploration technology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CNPC's west-to-east trunk lines channel Tarim Basin gas toward coastal demand centers, while CNOOC's deepwater operations at Lingshui feed the Pearl River Delta manufacturing complex. These trade corridors anchor regional investment patterns across China's hydrocarbon geography.
Yangtze River Delta
Petrochemical feedstock demand from Jiangsu and Zhejiang chemical parks drives natural gas consumption growth. MEE emissions quotas accelerate coal-to-gas switching in industrial boilers. Shanghai's Lingang and Ningbo's Zhenhai refining clusters negotiate direct pipeline connections to LNG receiving terminals.
Pearl River Delta
Guangdong's carbon-market pilot enables refiners to monetize blue hydrogen production from steam methane reforming with CCS. The province's dual carbon framework channels capital into retrofitting coastal processing facilities. Shenzhen and Huizhou manufacturing corridors absorb industrial gas offtake from CNOOC's Lingshui deepwater supply.
Shandong Peninsula
Independent refiners concentrate demand for discounted heavy sour crude grades from Middle Eastern term contracts. MIIT's GB 31570 revision forces wet scrubber retrofits or throughput reductions at processing facilities. Qingdao and Dongying refining clusters face margin compression when OPEC+ withholds supply.
Sichuan-Chongqing
Sichuan Basin shale gas development expands unconventional production for western consumption centers. SAMR pressure-equipment standards delay domestic certification of specialized metallurgy for sour gas environments. Chongqing's chemical industrial park absorbs regional pipeline flows for methanol-to-olefins production.
Western China
Tarim Basin ultra-deep conventional gas reserves require high-pressure high-temperature completions technology. CNPC controls overland pipeline infrastructure connecting Xinjiang production to coastal refineries. Korla and Urumqi serve as logistics nodes for west-to-east trunk line expansion projects facing X80-grade steel procurement delays.
China Oil and Gas Market Vendor Landscape
Channel-controlling players compete with product-specialist players across China's hydrocarbon value chain. State-owned enterprises anchor upstream production and trunk line infrastructure, while independent refiners and service contractors occupy downstream and technology niches. Three archetypes dominate: integrated national champions controlling full value chains, regional independents optimizing single-site economics, and international joint-venture partners contributing deepwater expertise. Competitive dynamics center on pipeline access negotiations and carbon capture retrofit partnerships.
Among national champions, China National Petroleum Corporation (CNPC), China Petroleum & Chemical Corporation (Sinopec), and China National Offshore Oil Corporation (CNOOC) occupy positions spanning upstream production through downstream refining. These entities exemplify the integrated archetype, with each representing distinct geographic and technological specializations—CNPC anchoring western pipeline infrastructure, Sinopec dominating coastal refining-chemical integration, and CNOOC controlling deepwater frontier development.
| Leading Market Players |
|---|
| China National Offshore Oil Corporation (CNOOC) |
| Shaanxi Yanchang Petroleum |
| China National Petroleum Corporation (CNPC) |
| Shell plc (via CNOOC Joint Ventures) |
| Guanghui Energy Co. Ltd |
| PetroChina Company Limited |
| Sinochem Group |
| SPT Energy Group, Inc. |
| China Petroleum & Chemical Corporation (Sinopec) |
| Others |
Supply Flow & Price Mechanics
Shandong refinery undercapacity relative to crude import quotas forces independent processors to bid aggressively for Middle Eastern term volumes, compressing margins while amplifying pricing power at integrated state-owned complexes with captive supply.
Pricing Analysis
Long-term offtake contracts indexed to Platts Dubai and domestic coal benchmarks dominate procurement at Yangtze River Delta chemical parks. Price differentiation hinges on sulfur content grades and MIIT GB 31570 compliance certification, with coastal refineries holding permit headroom commanding premiums. Pricing pressure stems from OPEC+ supply withholding on heavy sour grades, squeezing Shandong independents most acutely while integrated Sinopec facilities absorb shocks through naphtha cracker arbitrage.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities have become standard for X80-grade line pipe procurement, where SAMR GB/T 9711 certification delays stretch to 8-12 months. Geographic concentration centers on China for refining capacity, Saudi Arabia and Iraq for crude term contracts, and South Korea for specialized subsea metallurgy. Raw material dependencies include Middle Eastern heavy sour grades, Tarim Basin conventional gas, and imported LNG for coastal receiving terminals. Single-source vulnerability runs through CNOOC's deepwater robotics supply for Lingshui-phase developments. Distribution runs through CNPC's west-to-east trunk lines and truck-delivered ISO tank logistics for inland satellite stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated Yangtze River Delta chemical parks that negotiate direct pipeline connections, fragmenting traditional supply intermediaries and forcing sellers into quarterly price-reopener structures.
For Market Incumbents: Entrench pipeline access control through exclusive terminal connections at Ningbo Zhenhai and Shanghai Lingang, while accelerating carbon capture retrofit partnerships to preserve permit headroom under MEE emissions quotas. Defensive moves must address the threat of small-scale LNG satellite stations bypassing infrastructure constraints in inland manufacturing clusters. For New Entrants and Emerging Players: Sichuan-Chongqing shale gas development presents the most penetrable white-space target, where SAMR pressure-equipment certification gaps delay domestic suppliers and create entry windows for specialized metallurgy providers. Target methanol-to-olefins producers in Chongqing's chemical industrial park with modular carbon capture units. Go-to-market leverage rests on direct EPC partnerships with provincial energy groups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital twin reservoir management platforms serving CNPC's mature Daqing fields, where subscription analytics displace project-based consulting. Long-term viability favors asset-light technology licensors over capital-intensive processing capacity. Acquisition targets should display proprietary subsea robotics capabilities or certified X80-grade domestic steel production. Watch CNOOC's Lingshui-phase development timelines as the inflection signal for deepwater engineering talent scarcity resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | Preserves feedstock access under tightening MEE oversight at coal-to-chemical complexes. |
| Small-Scale LNG Satellite Station Buildout | Bypasses pipeline constraints in Yangtze corridor manufacturing clusters via ISO tank logistics. |
| Digital Twin Platform Licensing | Enables CNPC to recover additional barrels from mature Daqing fields without new drilling. |
| West-to-East Trunk Line Expansion | Unlocks stranded Tarim Basin gas reserves for coastal demand centers displacing coal. |
| Blue Hydrogen Production Monetization | Accesses Guangdong carbon-market pilot for industrial offtake in Pearl River Delta. |
Methodological Framework
The analysis maps upstream exploration, midstream pipeline infrastructure, downstream refining, and petrochemical conversion, each validated through reservoir engineers, refinery operations managers, and LNG terminal procurement leads. Primary interviews with CNOOC subsea robotics specialists, CNPC pipeline planning officers, and Sinopec aromatics complex supervisors combined with secondary validation through National Energy Administration production statistics, MIIT GB standard filings, and customs crude import records. Bottom-up field economics and top-down policy scenario triangulation anchored volume estimates.
Assumptions held fixed include MIIT's phased GB 31570 implementation timeline and OPEC+ term contract availability for Shandong independents; variables tested included carbon allowance pricing trajectories and X80-grade steel certification resolution speeds. Segmentation dimensions spanned hydrocarbon type, application, end-user category, and technology intensity across the projection horizon. CAGRs derived from production quota trajectories, refinery throughput permits, and chemical park expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by independent refiners to secure alternative crude sources or by provincial governments to accelerate carbon-market pilots would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Sidetracking Market
Oil & Gas
Well Casing Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
North America Shale Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Latin America Drilling Fluids Market