
 Oil & Gas Equipment MRO Market | 2026-2036
Oil & Gas Equipment MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Oil & Gas Equipment MRO Market Insights
The offshore service contractor channel is reconfiguring as integrated energy firms consolidate vendor panels and push outcome-based contracts. Baker Hughes Company leverages its turbomachinery installed base to capture recurring overhaul work. Schlumberger anchors deepwater MRO demand through its subsea intervention portfolio. Aker Solutions competes on North Sea decommissioning-linked maintenance scopes.
Oil and gas equipment MRO encompasses the repair, maintenance, and overhaul of pressure-containing and rotating machinery used in hydrocarbon extraction, processing, and transport, typically requiring compliance with API 510/570/653 inspection intervals and ASME pressure equipment codes. Pumps and valves generate the largest service revenue pools due to high failure frequency in sour service conditions. Compressor overhauls represent the fastest-growing service line as gas processing capacity expands. The exploration segment demands specialized drilling rig MRO, though refining and downstream transportation now absorb a growing share of inspection budgets.
OSHA process safety management rules and EPA leak detection mandates tighten maintenance scheduling and documentation requirements across US facilities. API standards govern repair procedures and material substitutions, while BSEE well control regulations drive blowout preventer testing frequency. Stakeholders must weigh capital allocation between predictive sensor networks and traditional time-based overhaul cycles as equipment utilization rates fluctuate.
Market Dynamics
Predictive maintenance analytics are compressing traditional time-based overhaul cycles as operators reallocate capital toward sensor networks and condition-monitoring platforms. This shift forces MRO providers to restructure service offerings around uptime guarantees rather than scheduled interventions.
Growth Catalysts
- API 510/570/653 inspection mandates:US refineries and midstream operators face escalating compliance deadlines for pressure vessel and piping integrity assessments, expanding third-party MRO contract volumes.
- Sour service pump failures:Hydrogen sulfide corrosion in Permian Basin and North Sea production accelerates replacement cycles for centrifugal pumps and valve trim packages.
- Subsea BOP testing frequency:BSEE well control regulations in the Gulf of Mexico require more frequent blowout preventer pressure testing, driving specialized offshore MRO demand.
Market Restraints
- Specialized alloy supply concentration:Super duplex stainless steel and Inconel sourcing depends on a limited European and Japanese mill base, exposing MRO shops to raw material lead time volatility.
- API repair procedure rigidity:Material substitution restrictions and weld procedure qualification requirements extend turnaround durations and limit field-level improvisation.
- Electrification substitution pressure:Electrified gas compression and solar-powered artificial lift systems reduce rotating machinery counts in new greenfield developments.
Strategic Opportunities
- North Sea decommissioning wave:Norway and UK offshore infrastructure retirement creates maintenance-to-abandonment conversion contracts for platform topsides and subsea architecture.
- Digital twin convergence:Physics-based simulation combined with real-time sensor feeds enables remote diagnostics and pre-positioned spare parts logistics for floating production units.
- Outcome-based contracting:Integrated energy firms now tender availability-based service agreements that transfer operational risk to MRO vendors with turbomachinery expertise.
Industry Challenges
- API 936 refractory certification scarcity:Qualified ceramic welders and furnace lining specialists command premium wages, constraining turnaround crew scaling for delayed coker and hydrogen reformer maintenance.
- Legacy SCADA integration friction:Brownfield facilities with proprietary control architectures resist seamless connectivity to cloud-based predictive analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil & Gas Equipment MRO Market |
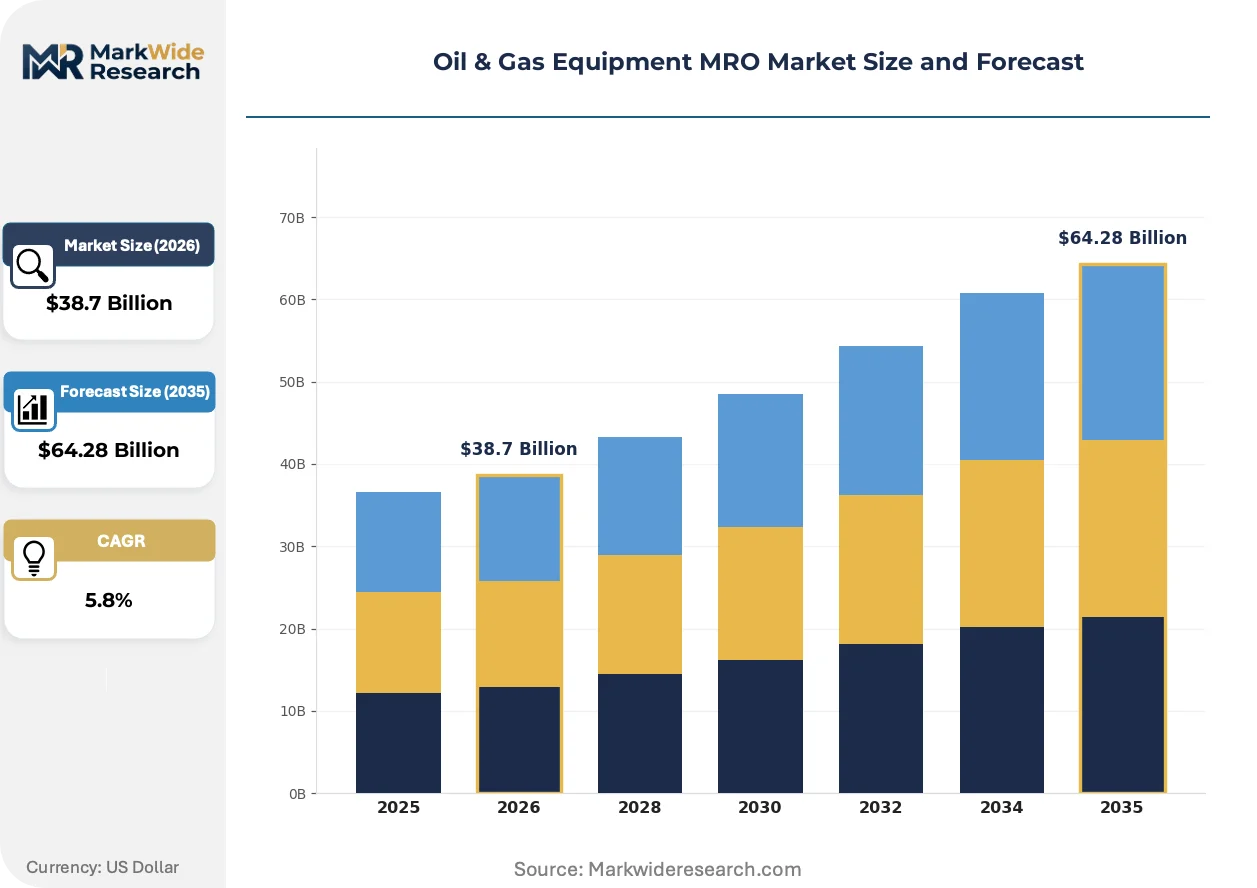
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Pumps, Valves, Compressors, Drilling Rigs Service Type: Repair, Maintenance, Overhaul, Inspection Industry Segment: Exploration, Production, Refining, Transportation End User: Operators, Contractors, Service Providers, Regulatory Bodies |
| Companies Covered | Oceaneering International, Inc., ABB Ltd., General Electric, RWG (Repair & Overhauls) Limited, Linde PLC, Schlumberger, Aker Solutions, Neptunus Power, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil & Gas Equipment MRO Market Trends and Innovations
Condition-based monitoring architectures are supplanting calendar-driven maintenance regimes across upstream and downstream asset bases. This transformation reconfigures vendor relationships, technical workforce requirements, and capital deployment patterns throughout the MRO value chain.
Wireless vibration sensors paired with edge computing analytics is rendering obsolete manual route-based data collection by rotating equipment technicians. Offshore platform operators in the Gulf of Mexico and North Sea are deploying these networks at scale. The technology compresses failure detection windows from weeks to hours, collapsing traditional time-between-overhaul intervals.
EPA methane detection mandates and OSHA process safety management enforcement are tightening documentation and leak survey frequencies across US refining and gas processing complexes. Facilities must now integrate optical gas imaging and continuous emissions monitoring into maintenance planning cycles. Downstream operators in Texas and Louisiana are absorbing the largest compliance cost burdens, accelerating outsourcing to certified third-party inspection contractors.
Service contract unbundling is fragmenting the integrated MRO procurement model that dominated the 2010s. Supermajors now separate mechanical, electrical, and instrumentation scopes across multiple specialist vendors rather than awarding single-source turnaround packages. This pattern is most pronounced in US shale patch maintenance programs, where operators optimize vendor selection by discipline-specific capability scores rather than historical relationship breadth.
Oil & Gas Equipment MRO Market Segmentation
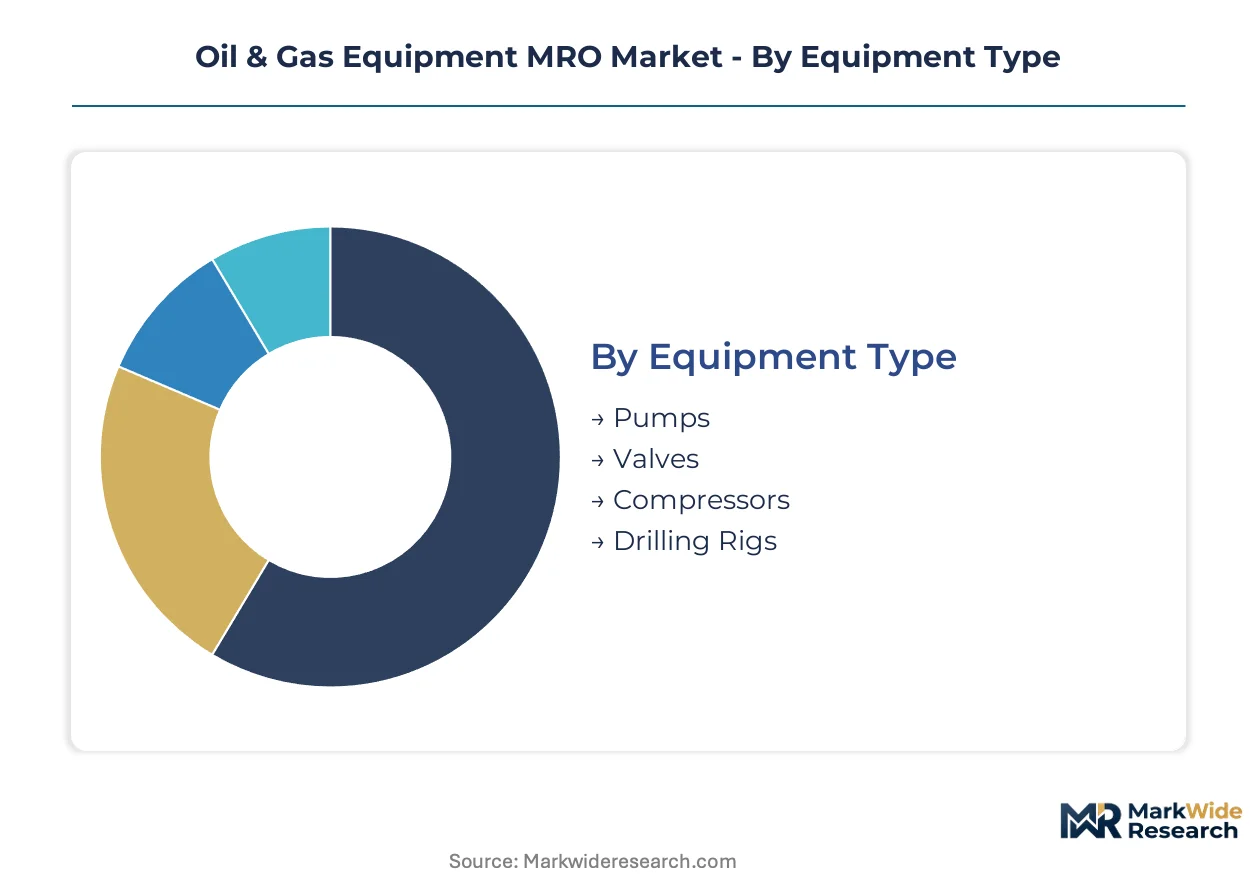
Segmentation reveals how MRO value pools concentrate around high-rotation equipment categories and inspection-intensive service lines. Equipment type and service type together determine contract sizing, technical workforce requirements, and margin profiles across upstream through downstream asset bases.
Equipment Type:
After-sales-service intensity varies dramatically across rotating versus static equipment, driving divergent vendor capability requirements and contract renewal frequencies.
- Pumps:Centrifugal and positive displacement units face accelerated wear in sour service conditions with hydrogen sulfide exposure. Permian Basin operators and North Sea producers absorb the largest replacement volumes for seals, bearings, and impeller assemblies. API 610 compliance mandates drive recurring overhaul scheduling.
- Valves:Pressure-containing devices span gate, globe, check, and control configurations with trim packages engineered for corrosive hydrocarbon streams. Gulf of Mexico offshore platforms and Texas refining complexes generate concentrated demand for emergency shutdown valve testing and actuator recalibration.
- Compressors:Reciprocating and centrifugal gas compression units require precision overhaul of crankshaft bearings, piston rings, and intercooler systems. Expanding gas processing capacity in Louisiana and Norway pushes maintenance contract volumes upward.
- Drilling Rigs:Mast structures, drawworks, and top drives demand specialized inspection protocols for fatigue cracking and hoisting equipment certification. Deepwater contractors in the Gulf of Mexico sustain the most intensive rig MRO programs.
Pumps hold the largest share; momentum sits with compressors as gas processing infrastructure expands.
Service Type:
Cost tier stratification separates commodity repair work from certified overhaul and regulatory-mandated inspection scopes with divergent pricing power.
- Repair:Breakdown response and component replacement address unplanned failures across all equipment categories. Field service crews in Texas and Louisiana execute the highest volume of emergency pump and valve repairs.
- Maintenance:Scheduled preventive interventions include lubrication, alignment verification, and consumable replacement. Production operators increasingly bundle maintenance with remote monitoring subscriptions.
- Overhaul:Complete equipment disassembly, dimensional inspection, and reassembly to OEM specifications demands specialized shop facilities. Compressor overhauls command premium pricing due to precision balancing requirements.
- Inspection:API 510 pressure vessel, API 570 piping, and API 653 tank integrity assessments generate fixed-fee contract structures. Third-party inspection contractors capture growing share as operators outsource compliance documentation.
Inspection holds the largest share; momentum sits with overhaul as operators extend equipment life cycles.
Industry Segment:
Application context determines equipment utilization rates, environmental exposure severity, and regulatory inspection frequency across the hydrocarbon value chain.
- Exploration:Drilling rig MRO and wellhead equipment maintenance support wildcat and development drilling programs. Deepwater Gulf of Mexico contractors sustain specialized blowout preventer service demand.
- Production:Artificial lift systems, separation equipment, and gathering compression require continuous field maintenance. Permian Basin and North Sea production assets generate the highest pump and valve replacement frequencies.
- Refining:Process units, delayed cokers, and hydrogen reformers demand turnaround-intensive maintenance with refractory and catalyst handling scopes. Texas and Louisiana refining complexes absorb the largest third-party MRO contract values.
- Transportation:Pipeline compression, terminal loading equipment, and tankage maintenance link upstream supply to downstream markets. Midstream operators in Texas prioritize leak detection system integration with maintenance planning.
Production holds the largest share; momentum sits with refining as EPA methane detection mandates tighten inspection frequencies.
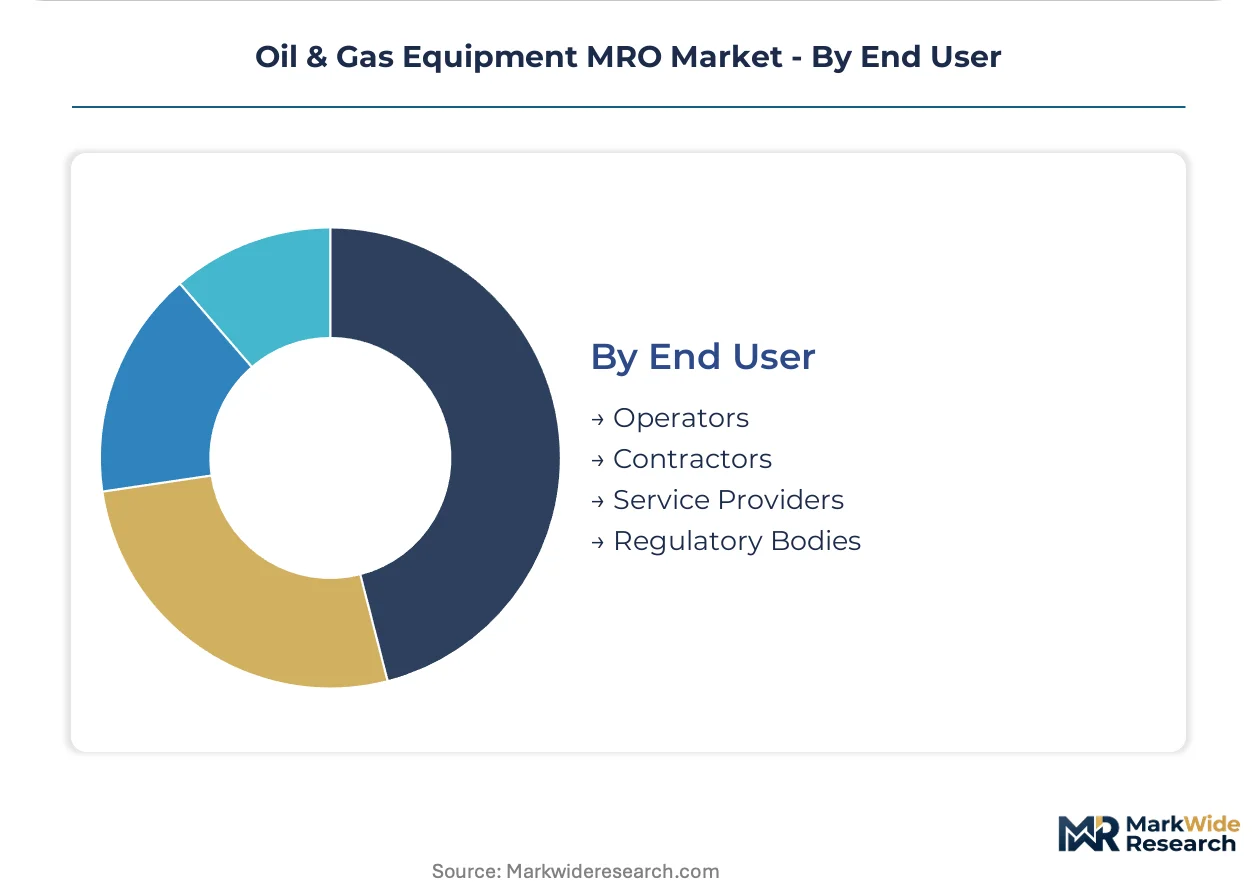
End User:
Customer type shapes procurement centralization, technical specification authority, and contract duration preferences across the MRO value chain.
- Operators:Integrated and independent production companies own hydrocarbon reserves and control capital allocation for maintenance programs. Supermajors consolidate vendor panels and push outcome-based contracting structures.
- Contractors:Drilling and well service companies lease equipment and outsource specialized repair to certified shops. Gulf of Mexico offshore contractors concentrate demand for subsea intervention MRO.
- Service Providers:Equipment rental firms and aftermarket parts distributors maintain internal repair capabilities for rotating machinery. Regional pump and compressor shops compete on turnaround speed.
- Regulatory Bodies:BSEE, EPA, and state environmental agencies mandate inspection frequencies and documentation standards that drive third-party contract volumes. Compliance enforcement in the Gulf of Mexico accelerates blowout preventer testing demand.
Operators hold the largest share; momentum sits with contractors as drilling activity intensifies and equipment leasing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for subsea intervention work concentrates in Norway's North Sea basin, while Gulf of Mexico operators extract cost concessions through consolidated vendor panels. This asymmetry reflects divergent regulatory enforcement intensity and local supply scarcity.
United States
Permian Basin pump replacement cycles and Gulf of Mexico blowout preventer testing drive contract volumes. OSHA process safety management and EPA methane detection mandates tighten documentation requirements across Texas and Louisiana refining complexes. Houston anchors the largest concentration of third-party inspection contractors serving midstream compression assets.
Norway
North Sea platform decommissioning and subsea infrastructure maintenance sustain premium service rates. Petroleum Safety Authority Norway enforces strict well integrity standards that accelerate specialized MRO demand. Stavanger and Bergen host the densest clusters of turbomachinery overhaul shops serving floating production units.
United Kingdom
Legacy North Sea asset life extension and abandonment preparation create hybrid maintenance contracts. Health and Safety Executive offshore safety case requirements mandate rigorous pressure equipment inspection frequencies. Aberdeen maintains its position as the primary logistics hub for subsea intervention vessel mobilization.
Brazil
Pre-salt field development expands gas compression and artificial lift maintenance requirements. ANP regulatory frameworks govern well control equipment certification and testing intervals. Rio de Janeiro concentrates national oil company procurement offices and subsea equipment fabrication yards.
Saudi Arabia
Gas processing capacity expansion and master gas system upgrades drive compressor overhaul demand. Saudi Aramco engineering standards exceed API baselines for sour service equipment specifications. Dhahran and Jubail Industrial City house the largest rotating machinery repair facilities serving eastern province production assets.
Oil & Gas Equipment MRO Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a fragmented supply base. The market structures around three tiers: integrated energy firms with captive service arms, independent turbomachinery shops, and specialized inspection contractors. Consolidation pressures favor outcome-based contracting and vendor panel reduction. Geographic expansion and technology licensing represent the dominant competitive vectors as players seek scale in high-barrier subsea niches.
Within the integrated service tier, Baker Hughes Company, Schlumberger, and Aker Solutions occupy positions that exemplify divergent strategic emphases. Baker Hughes leverages turbomachinery installed base density to capture recurring overhaul work. Schlumberger anchors deepwater demand through subsea intervention capabilities. Aker Solutions competes on North Sea decommissioning-linked maintenance scopes where regulatory familiarity commands premium positioning.
| Leading Market Players |
|---|
| Oceaneering International, Inc. |
| ABB Ltd. |
| General Electric |
| RWG (Repair & Overhauls) Limited |
| Linde PLC |
| Schlumberger |
| Aker Solutions |
| Neptunus Power |
| Baker Hughes Company |
| Others |
Pricing and Supply Chain Analysis
Houston's dense concentration of API-certified repair facilities and turbomachinery overhaul shops creates asymmetric pricing power against Permian Basin operators seeking rapid turnaround services. This geographic concentration of technical capacity allows specialized MRO providers to command premium rates for sour service pump rebuilds and emergency blowout preventer testing, while standard valve recalibration work faces cost compression from regional competition.
Pricing Analysis
The customization-premium spread between configured-to-order overhaul pricing and standard maintenance rates runs wide in this market, with API 936 refractory-certified work and subsea BOP pressure testing commanding substantial premiums over commodity pump seal replacements. Price differentiation hinges on certification tier—API 510/570/653 inspection authorization levels—and geographic delivery cost to offshore platforms. Pricing pressure stems from integrated operators consolidating vendor panels and demanding outcome-based availability guarantees. National oil companies exhibit lowest price sensitivity due to operational risk aversion, while independent shale operators drive hardest bargain on routine maintenance scopes.
Supply Chain Analysis
Super duplex stainless steel and Inconel alloy feedstock for high-pressure equipment repairs draws from concentrated European and Japanese mill capacity, creating raw material dependencies that constrain MRO shop scheduling flexibility. Specialized alloy sourcing rests on mills in Sweden, Germany, and Japan for corrosion-resistant grades essential to sour service conditions. Single-source vulnerability around super duplex plate stock exposes repair facilities to lead time volatility when mill allocations tighten. Distribution runs through authorized stocking distributors in Houston, Stavanger, and Singapore, with field service crews maintaining forward-deployed spare parts caches at major production basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance subscriptions and remote monitoring contracts expand faster than hardware overhaul revenue, rewarding vendors who embed analytics into long-term service agreements.
For Market Incumbents: Harden installed base capture by embedding wireless vibration sensors and edge analytics into recurring service contracts before electrified compression systems displace rotating machinery counts in greenfield developments. Deepen backward integration into specialized alloy sourcing through mill partnerships in Sweden and Japan to defend margin position against raw material volatility. Prioritize API 936 refractory certification investment to capture delayed coker and hydrogen reformer turnaround work as refining capacity utilization tightens. For New Entrants and Emerging Players: Pursue white-space positioning in North Sea decommissioning-linked maintenance-to-abandonment conversion contracts, where regulatory familiarity barriers limit incumbent expansion. Target Brazil's pre-salt gas compression maintenance market through ANP certification pathways and local content partnerships with Rio de Janeiro fabrication yards. Penetrate via specialized subsea intervention capabilities rather than competing head-to-head with integrated turbomachinery shops. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors inspection contractors with proprietary digital twin platforms and physics-based simulation capabilities that enable remote diagnostics for floating production units. Long-term viability across the analysis window rests on vendors who combine turbomachinery overhaul expertise with predictive analytics subscription revenue. The signal to watch is integrated operator RFP language shifting from time-based overhaul specifications to guaranteed availability contracts with penalty clauses.| Strategic Initiative | Industry Significance |
|---|---|
| API Certification Investment | API 936 and subsea BOP testing authorizations unlock premium turnaround and offshore intervention contracts. |
| Predictive Analytics Platform Deployment | Wireless sensor networks paired with edge computing compress failure detection windows from weeks to hours. |
| Specialized Alloy Supply Agreement | Long-term mill partnerships in Sweden and Japan hedge raw material lead time volatility for sour service repairs. |
| North Sea Decommissioning Capability Buildout | Platform topsides and subsea architecture retirement creates maintenance-to-abandonment conversion revenue pools. |
| Outcome-Based Contracting Structure | Availability guarantees with penalty clauses transfer operational risk from operators to MRO vendors. |
Research Methodology
A spread of perspectives from maintenance directors at integrated operators, turbomachinery overhaul shop managers, API certification auditors, and aftermarket parts distributors converged on the working assumptions shaping this analysis. Primary field engagement with plant engineers in Texas and Louisiana, subsea intervention coordinators in the Gulf of Mexico, and procurement leads at national oil companies informed demand-side validation. Secondary sources included BSEE well control enforcement data, EPA methane detection compliance records, API standards documentation, and SEC filings from listed oilfield service companies. Bottom-up equipment count modeling and top-down contract value triangulation anchored market sizing.
Demand-supply balance framing structured the forecast architecture across the projection horizon, with segmentation dimensions spanning equipment type, service line, industry segment, and end-user category. Equipment-specific failure rate curves, inspection interval mandates under API 510/570/653, and operator capital allocation patterns for predictive versus preventive maintenance informed growth trajectory modeling. CAGRs derived from equipment installed base expansion, regulatory enforcement intensity shifts, and technology substitution curves for electrified systems.
Macroeconomic conditions sit as an overlay; deviation in crude price cycles, offshore drilling rig utilization, and North American gas processing capacity buildout would shift the trajectory materially. Forecasts embed assumptions around regulatory enforcement continuity at BSEE and EPA, alloy supply chain stability, and integrated operator vendor consolidation pace. Cross-checking against IEA upstream investment outlooks and EIA drilling productivity reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Delayed Coker Unit Process Technology Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Denmark Oil and Gas Midstream Market