
 Oil and Gas Seals Market | 2026-2036
Oil and Gas Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Seals Market Analytics
Aftermarket service contracts for seal monitoring and predictive replacement is shifting how vendors capture lifetime value from energy operators. Parker Hannifin Corporation leverages its distributed service network to anchor long-term maintenance agreements across North American shale fields. Freudenberg Group specializes in fluorocarbon compound formulations that sustain performance under hydrogen sulfide exposure. John Crane dominates aftermarket logistics for rotating equipment in offshore environments.
Oil and gas seals are engineered containment devices manufactured from elastomeric compounds, thermoplastics, or metal alloys, typically rated for pressures exceeding 10,000 psi and temperatures ranging from cryogenic to 300°C, designed to prevent fluid or gas leakage in wellheads, valves, pumps, and pipeline connectors. Gaskets and O-rings occupy the largest volume share in mature onshore replacement cycles, while composite materials represent the fastest-expanding material class as operators seek weight reduction and chemical resistance in deepwater riser systems. Offshore applications command premium positioning due to qualification complexity and extended certification timelines.
The American Petroleum Institute governs material qualification and performance testing protocols that directly determine product eligibility for US upstream projects, while the EU F-Gas Regulation restricts fluorinated seal materials in European offshore installations, redirecting R&D toward hydrogenated nitrile alternatives. Brazil's national petroleum regulator ANP mandates local content thresholds for subsea equipment procurement, shaping supplier entry strategies. Stakeholders must weigh certification investment against the contracting windows of pre-salt development campaigns.
Market Dynamics
Deepwater exploration economics are compressing qualification timelines for high-pressure sealing systems as operators in Brazil's pre-salt basins and the US Gulf of Mexico accelerate drilling schedules. API well integrity standards now mandate material traceability that extends from compound formulation through final assembly.
Growth Catalysts
- Pre-salt development campaigns:Brazil's ANP local content thresholds are redirecting supplier investment toward domestic manufacturing partnerships for subsea equipment.
- API well integrity standards:Tightened material certification requirements are filtering out uncertified competitors and concentrating procurement among qualified vendors.
- Hydrogenated nitrile compounds:EU F-Gas Regulation restrictions on fluorinated seal materials are accelerating R&D investment in alternative elastomer formulations.
Market Restraints
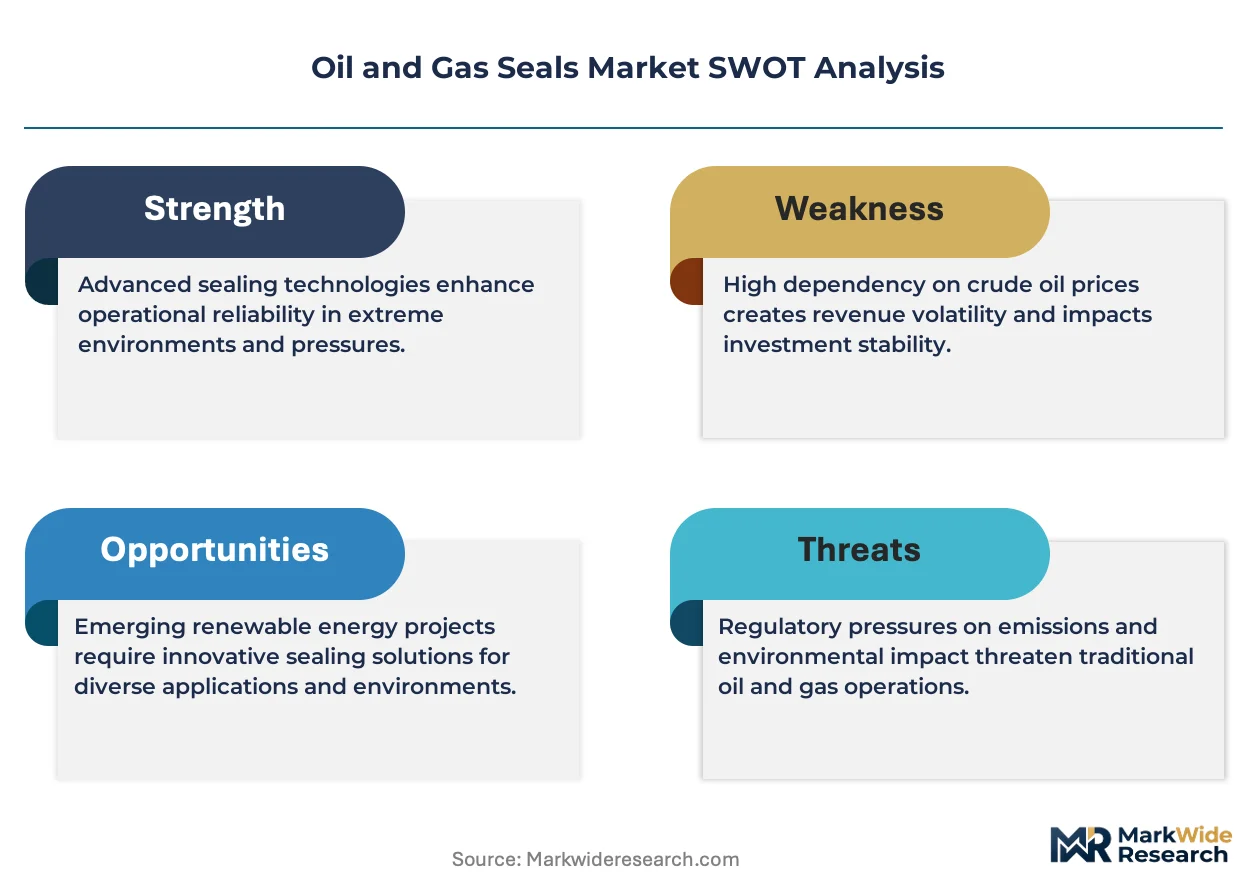
- Fluorocarbon feedstock volatility:Price swings in specialty polymer precursors compress margin predictability for compound formulators serving offshore projects.
- Extended certification timelines:API qualification protocols require 18-24 month validation cycles that delay revenue recognition for new product introductions.
- Deepwater riser weight constraints:Steel-reinforced elastomeric seals face displacement pressure from thermoplastic composites in tension-leg platform applications.
Strategic Opportunities
- Predictive replacement services:Sensor-integrated seal monitoring creates recurring revenue streams that decouple vendor economics from new equipment sales cycles.
- ANP local content mandates:Joint ventures with Brazilian fabricators unlock access to pre-salt procurement windows that exclude pure imports.
- Hydrogen sulfide exposure applications:Sour gas reservoir development in the Middle East creates demand for fluorocarbon formulations that sustain performance above 200°C.
Industry Challenges
- Compound formulation expertise scarcity:Specialized knowledge in hydrogenated nitrile-HNBR blending for high-pressure hydrogen environments concentrates among legacy European compounders.
- Multi-standard compliance burden:Simultaneous API, ISO, and ANP certification requirements fragment engineering resources and extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Seals Market |
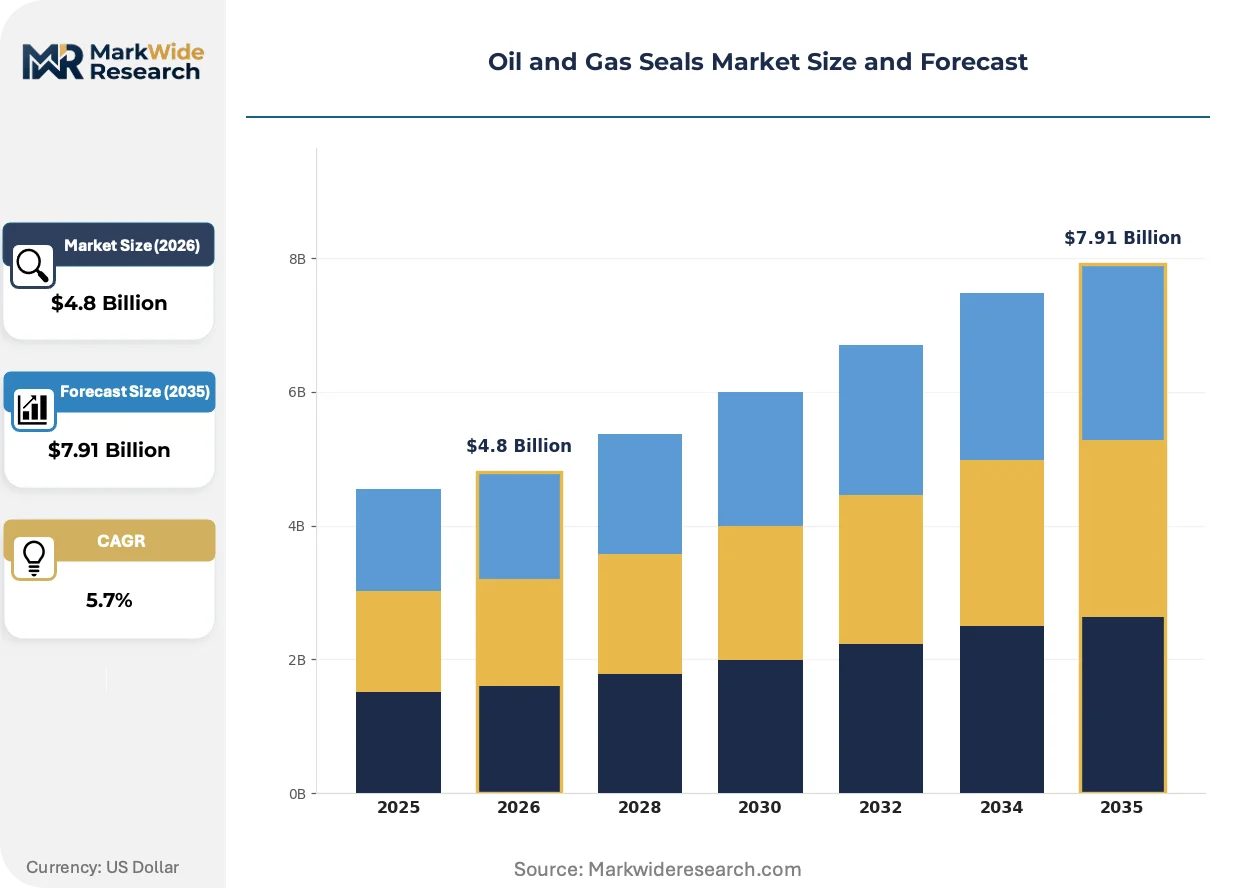
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seal Type: O-Rings, Gaskets, Valve Seals, Packing Seals Material: Rubber, PTFE, Metal, Composite Application: Upstream, Midstream, Downstream, Offshore Installation Type: Static, Dynamic, Rotating, Custom |
| Companies Covered | Parker Hannifin Corporation, Flowserve Corporation, Freudenberg Group, John Crane, Trelleborg AB, EnPro Industries, Sinoseal Holding Co., Ltd., EagleBurgmann, NAK Sealing Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Seals Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape compound selection criteria across upstream and midstream sealing applications. The transition from legacy elastomers to engineered thermoplastics is compressing traditional supplier hierarchies.
Thermoplastic composite seals are consolidating position in deepwater riser systems where weight reduction and chemical resistance outweigh elastomer flexibility advantages. Offshore operators in Brazil and the Gulf of Mexico are specifying these materials for newbuild tension-leg platforms. This consolidation is compressing the addressable market for steel-reinforced elastomeric alternatives in high-pressure subsea connectors.
EU F-Gas Regulation phase-down schedules are forcing reformulation of fluorinated seal compounds used in North Sea and Barents Sea installations. The restriction redirects R&D investment toward hydrogenated nitrile and perfluoroelastomer alternatives that maintain performance under hydrogen sulfide exposure. European offshore contractors are accelerating qualification of non-fluorinated compounds to avoid supply disruption as 2030 reduction targets approach.
Aftermarket service unbundling is fragmenting traditional equipment procurement relationships in North American shale fields. Operators are separating seal monitoring and predictive replacement from original equipment vendor contracts, creating entry points for specialized service providers. This pattern is most visible in Permian Basin wellhead maintenance where independent service networks compete against integrated OEM offerings.
Oil and Gas Seals Market Segmentation
Sealing system selection in oil and gas operations hinges on pressure ratings, chemical exposure profiles, and regulatory compliance requirements that vary sharply across extraction environments. Material certification timelines and installation complexity create divergent margin structures that reward specialized suppliers.
Seal Type:
Pressure containment geometry determines qualification protocols and replacement frequency across wellhead and pipeline applications.
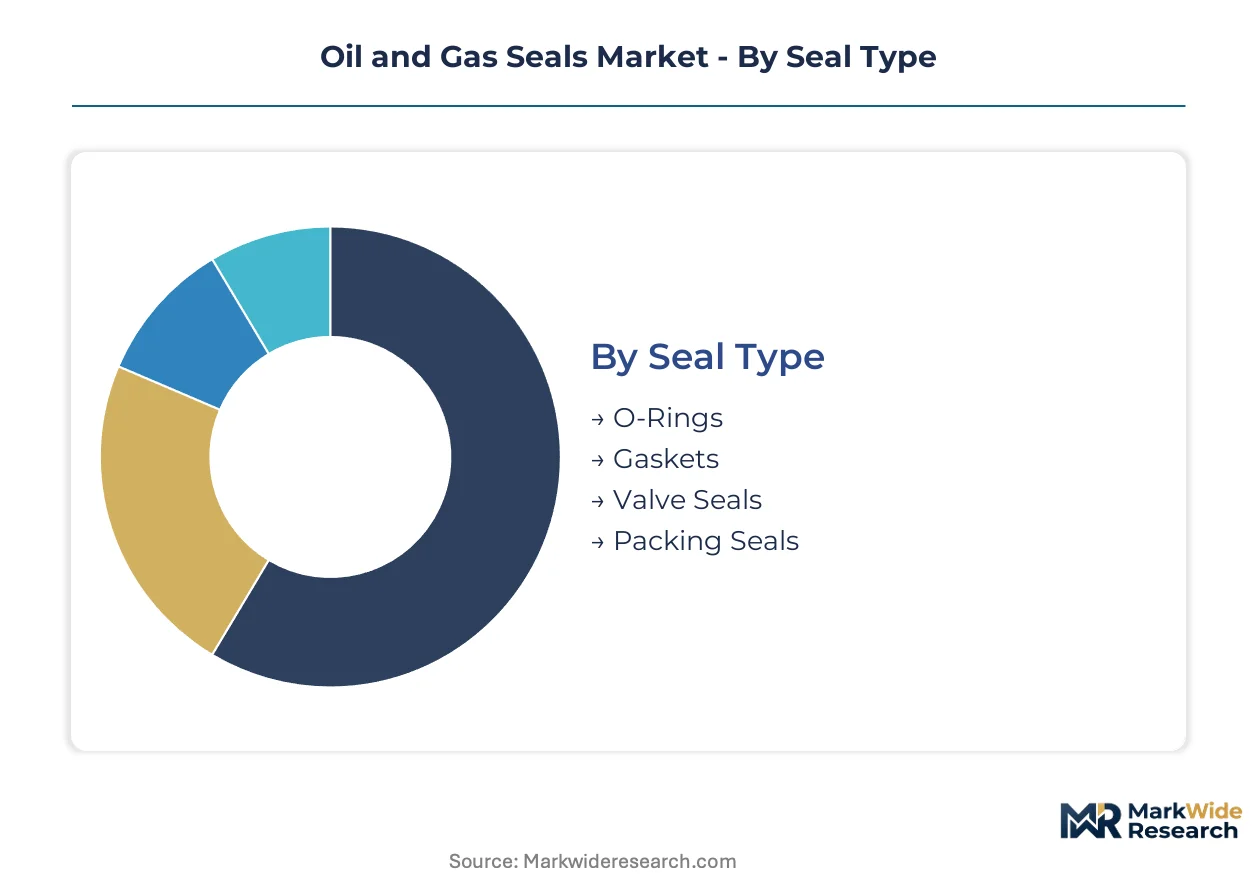
- O-Rings:Circular elastomeric or thermoplastic toroids compressed between mating surfaces to block fluid escape. Procurement concentrates in Permian Basin wellhead maintenance cycles where API material traceability mandates filter supplier pools.
- Gaskets:Flat mechanical seals spanning flange interfaces, fabricated from compressed fiber, spiral-wound metal, or PTFE composites. Demand clusters in North American shale field pipeline turnaround schedules driven by methane emission reduction targets.
- Valve Seals:Stem and seat sealing elements engineered for cyclic pressure and temperature exposure.
- Packing Seals:Compressible fiber or polymer assemblies for pump and valve stuffing boxes.
O-Rings lead on scale; Gaskets lead on momentum.
Material:
Compound chemistry dictates hydrogen sulfide resistance, temperature ceiling, and regulatory eligibility under regional environmental frameworks.
- Rubber:Hydrogenated nitrile (HNBR) and fluoroelastomer formulations dominate sour gas and high-temperature applications. Brazilian pre-salt procurement specifications favor HNBR for ANP-compliant local content sourcing.
- PTFE:Polytetrafluoroethylene and modified fluoropolymer variants deliver chemical inertness across pH extremes. EU F-Gas Regulation phase-down schedules are redirecting North Sea platform procurement toward PTFE alternatives as 2030 reduction targets approach.
- Metal:Stainless steel and nickel alloy seals for cryogenic and ultra-high-pressure service.
- Composite:Engineered thermoplastic and fiber-reinforced polymer systems.
Rubber leads on scale; PTFE leads on momentum.
Application:
Operational stage determines pressure cycling intensity, exposure to production fluids, and accessibility for maintenance intervention.
- Upstream:Wellhead, Christmas tree, and downhole sealing systems rated for reservoir pressure and corrosive formation fluids. Investment concentrates in US Gulf of Mexico deepwater tiebacks where API well integrity standards mandate material traceability from compound formulation through final assembly.
- Midstream:Pipeline flange, pump, and compressor seals for hydrocarbon transport networks. Replacement demand is accelerating in Permian Basin gathering systems as operators separate seal monitoring from original equipment vendor contracts.
- Downstream:Refinery and petrochemical process unit sealing for catalytic and thermal cracking operations.
- Offshore:Subsea connector, riser, and tension-leg platform sealing systems.
Upstream leads on scale; Midstream leads on momentum.
Installation Type:
Relative motion between sealed surfaces dictates wear mechanisms and predictive replacement scheduling.
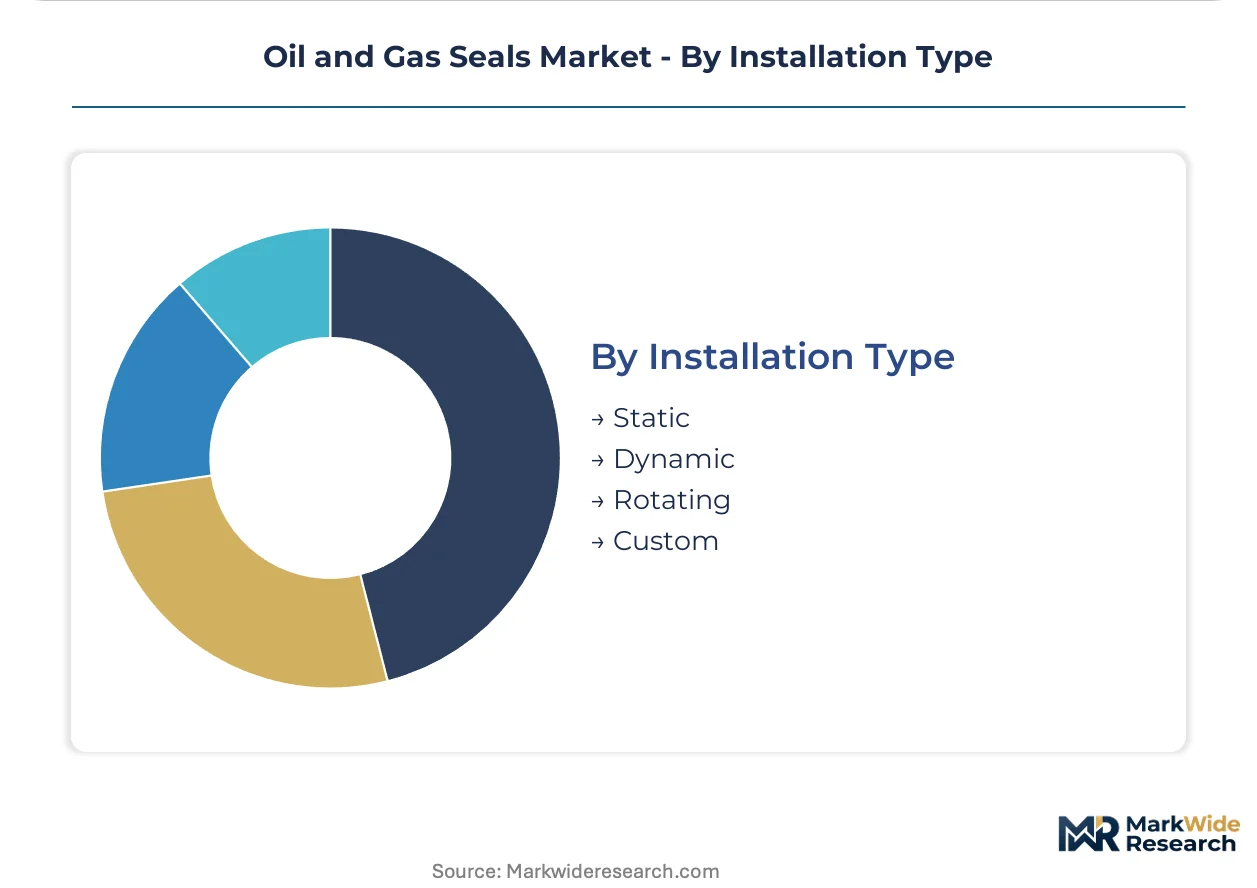
- Static:Non-moving flange and cover seals where compression set and thermal cycling drive failure modes. Procurement dominates mature onshore field maintenance programs in Texas and Oklahoma where sensor-integrated monitoring is unbundling from equipment sales.
- Dynamic:Reciprocating rod and piston seals for valves and actuators. Demand is climbing fastest in Middle East sour gas development where hydrogen sulfide exposure above 200°C requires specialized fluorocarbon formulations.
- Rotating:Shaft and bore seals for pumps, compressors, and turbines.
- Custom:Application-specific geometries for subsea and extreme-pressure service.
Static leads on scale; Dynamic leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands deepwater procurement volume while the United States dominates shale field replacement cycles. Both markets operate under distinct regulatory architectures that reshape supplier qualification requirements. Material certification timelines diverge sharply between ANP-mandated local content thresholds and API well integrity protocols.
United States
Permian Basin wellhead maintenance and Gulf of Mexico deepwater tiebacks drive procurement intensity. The American Petroleum Institute governs material traceability from compound formulation through final assembly. Houston anchors the largest concentration of seal distributors and service networks for North American shale operators.
Brazil
Pre-salt basin development campaigns accelerate demand for high-pressure subsea sealing systems. The national petroleum regulator ANP mandates local content thresholds that redirect supplier investment toward domestic manufacturing partnerships. Rio de Janeiro hosts the primary cluster of fabrication yards serving Petrobras procurement specifications.
Germany
Specialized compound formulators supply hydrogenated nitrile formulations for sour gas applications across European offshore installations. The EU F-Gas Regulation restricts fluorinated seal materials and redirects R&D investment toward alternative elastomer chemistries. Industrial centers in Baden-Württemberg concentrate legacy expertise in high-performance polymer blending.
Saudi Arabia
Sour gas reservoir development above 200°C creates demand for fluorocarbon formulations with hydrogen sulfide resistance. The national oil company procurement frameworks prioritize qualified vendors with established Middle East service infrastructure. The Eastern Province concentrates downstream processing capacity requiring high-temperature sealing solutions.
China
Domestic shale gas development and pipeline network expansion sustain replacement demand for flange and valve sealing systems. GB standards and MIIT regulations govern material qualification for pressure-containing equipment in hydrocarbon service. Sichuan-Chongqing basin operations concentrate procurement for unconventional gas extraction sealing requirements.
Oil and Gas Seals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates among integrated sealing system providers with compound formulation capabilities and distributed service networks. Three archetypes dominate: legacy European compounders with hydrogenated nitrile expertise, North American integrated OEMs with shale field logistics, and Asian fabricators serving cost-sensitive pipeline replacement cycles. Competitive positioning hardens through API qualification investment and ANP joint venture formation.
Among North American integrated suppliers, Parker Hannifin Corporation anchors aftermarket service networks across shale basins. Freudenberg Group exemplifies the European compounder archetype with specialized fluorocarbon formulation capabilities. John Crane occupies a position within offshore rotating equipment logistics. These three represent distinct strategic postures: service-network anchoring, material science specialization, and aftermarket infrastructure control.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Flowserve Corporation |
| Freudenberg Group |
| John Crane |
| Trelleborg AB |
| EnPro Industries |
| Sinoseal Holding Co., Ltd. |
| EagleBurgmann |
| NAK Sealing Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Fluorocarbon feedstock indices cascade through compound formulation costs into three-tier pricing structure across premium, standard, and economy levels. API certification tiers anchor premium positioning for deepwater projects, while uncertified alternatives compete on unit economics in mature onshore replacement cycles.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for hydrogenated nitrile compounds used in sour gas applications. Pricing stratifies across premium, standard, and economy tiers based on API qualification status and material traceability depth. Cost compression in standard-grade segments is intensifying because Brazilian fabricators are scaling domestic HNBR blending capacity. National oil companies exhibit lowest price sensitivity due to procurement frameworks that prioritize qualification longevity over unit cost.
Supply Chain Analysis
Freight cost inflation on specialty polymer precursors from European compounders to Gulf of Mexico assembly yards is redrawing sourcing radii. Supply concentrates in Germany for fluorocarbon formulation expertise, the United States for API-certified assembly, and Brazil for ANP-compliant domestic content. Raw material dependencies include fluoroelastomer polymers, hydrogenated nitrile base stocks, and fiber-reinforced thermoplastic resins. Single-source vulnerability concentrates in legacy European hydrogenated nitrile-HNBR blending knowledge. Distribution runs through Houston and Rio de Janeiro as dual logistics hubs serving deepwater procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as pre-salt development campaigns and API well integrity standards concentrate procurement among qualified vendors with full material traceability.
For Market Incumbents: Lock in compound formulation expertise through captive supply of hydrogenated nitrile blending capacity or exclusive partnerships with legacy European compounders. Deepen API certification investment to filter out emerging competitors before pre-salt contracting windows close. Thermoplastic composite displacement in tension-leg platform applications threatens steel-reinforced elastomeric seal margins. For New Entrants and Emerging Players: Launch via sensor-integrated seal monitoring services that unbundle from original equipment vendor contracts in Permian Basin wellhead maintenance. Target midstream pipeline flange replacement cycles where methane emission reduction targets accelerate turnaround schedules without requiring deepwater qualification timelines. White space exists in predictive replacement logistics for North American shale operators separating service from equipment procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized compounders possessing hydrogenated nitrile-HNBR formulation expertise for high-pressure hydrogen environments. Long-term viability hinges on 5-10 year positioning around EU F-Gas Regulation compliance and ANP local content mandate fulfillment. Signal to monitor: acceleration of thermoplastic composite qualification timelines in Brazil's pre-salt procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with Brazilian Fabricator | ANP local content thresholds unlock pre-salt procurement windows that exclude pure imports. |
| Backward Integration into Compound Formulation | Captive hydrogenated nitrile blending secures margin control against fluorocarbon feedstock volatility. |
| Predictive Replacement Service Launch | Sensor-integrated monitoring creates recurring revenue decoupled from new equipment sales cycles. |
| API Certification Investment | Material traceability mandates filter supplier pools and concentrate procurement among qualified vendors. |
| Thermoplastic Composite Qualification | Weight reduction specifications in tension-leg platforms displace steel-reinforced elastomeric alternatives. |
Research Methodology
Coverage spans North America, South America, and Europe, with primary inputs from each region's deepwater procurement clusters. Interviews with procurement directors at national oil companies, maintenance supervisors at Permian Basin operators, compound formulation chemists at European specialty polymer houses, and aftermarket service heads at rotating equipment OEMs combined with secondary validation from API specification documents, ANP local content regulations, EU F-Gas Regulation filings, and customs trade data. Bottom-up segment sizing triangulated against top-down energy capex flow analysis.
Granularity-level modeling operated at seal type, material chemistry, application stage, and installation geometry dimensions across the analysis window. CAGRs derived from segment-level volume build-ups incorporating replacement cycle intensity, certification timeline lag effects, and regional contracting window phasing. Industry-specific forecast inputs included pre-salt development campaign schedules, API well integrity standard revision timelines, and EU F-Gas Regulation phase-down compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained fluorocarbon feedstock price volatility or accelerated thermoplastic composite displacement in deepwater riser specifications. Forecasts reflect documented assumptions regarding ANP local content threshold enforcement intensity and API material traceability audit frequency. A model refresh is warranted upon material change in Brazilian pre-salt contracting cadence or EU F-Gas Regulation amendment timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Drilling Fluids Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
South America Oil and Gas Storage Tank Market
Oil & Gas
Frac Stack Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Hydraulic Fracturing Market