
 Casing and Cementation Hardware Market | 2026-2036
Casing and Cementation Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Casing and Cementation Hardware Market Outlook
Premium alloy-grade casing specifications is reorganizing procurement criteria across the Casing and Cementation Hardware Market. Baker Hughes Company leverages integrated manufacturing of high-collapse casing strings to anchor its position in deepwater applications. National Oilwell Varco Inc. competes through aftermarket service density across North American shale basins. Tenaris S.A. dominates seamless pipe supply for sour-service wells where material traceability commands priority.
Casing and cementation hardware encompasses mechanical devices and consumables installed during well construction to secure casing strings, isolate formations, and ensure zonal isolation through cement placement. Centralizers manufactured from spring steel or thermoplastic composites maintain standoff ratios exceeding 67% during primary cementing operations. Float equipment and cementing heads represent the fastest-growing product categories as extended-reach laterals require redundant backpressure control. Smart cementing technology segments capture margin concentration through real-time pressure telemetry and automated slurry density adjustment, while conventional cementing retains volume leadership in standard vertical wells.
API specification 5CT and 10D frameworks govern material grades and centralizer performance testing for US onshore and offshore deployment. The EPA's UIC Class II well integrity standards and BSEE blowout preventer regulations shape demand for redundant float valve configurations in Gulf of Mexico operations. Stakeholders must monitor how evolving methane emission detection requirements and cement bond log verification protocols will redefine hardware qualification thresholds and service provider liability structures.
Market Dynamics
API 5CT specification upgrades are tightening material qualification thresholds across the casing and cementation hardware sector, forcing manufacturers to revalidate alloy compositions and collapse ratings while deepwater operators in Brazil and West Africa accelerate procurement of premium-grade accessories for high-pressure formations.
Growth Catalysts
- Deepwater Development Surge:Brazil's pre-salt basins and West African offshore blocks are expanding float equipment orders as operators target reservoirs below 2,000 meters water depth requiring redundant backpressure control systems.
- Smart Cementing Adoption:Real-time pressure telemetry and automated slurry density adjustment are penetrating extended-reach laterals in the Permian Basin where well complexity demands precise zonal isolation.
- EPA UIC Class II Standards:The EPA's well integrity mandates are mandating redundant float valve configurations for Gulf of Mexico shelf projects, directly expanding hardware procurement volumes.
Market Restraints
- Alloy Supply Concentration:Premium chromium-molybdenum steel sourcing concentrates among a limited set of specialty mills, creating input cost volatility and lead time uncertainty for sour-service casing grades.
- BSEE Certification Friction:The Bureau of Safety and Environmental Enforcement's blowout preventer integration rules extend qualification timelines for cementing heads destined for federal offshore leases.
- Composite Centralizer Substitution:Thermoplastic composite centralizers are displacing spring steel variants in low-temperature onshore applications, compressing margins for traditional metal-forming suppliers.
Strategic Opportunities
- Methane Detection Integration:Evolving EPA methane emission verification protocols are creating demand for cement bond log hardware with embedded sensor arrays capable of continuous annular integrity monitoring.
- Automated Cementing Convergence:Integration of real-time telemetry with automated mixing systems is opening service contracts that bundle hardware deployment with performance-guaranteed slurry placement.
- Argentina Vaca Muerta Expansion:Shale operators in Neuquén province are importing premium centralizer systems as lateral lengths extend beyond 3,000 meters requiring precise standoff maintenance.
Industry Challenges
- Materials Engineering Talent Gap:Sour-service metallurgy expertise remains scarce as API 5CT Grade C110 and Q125 specifications demand specialized corrosion fatigue analysis capabilities.
- Legacy Equipment Integration:Smart cementing systems must interface with decades-old rig infrastructure, creating field calibration complexity and deployment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casing and Cementation Hardware Market |
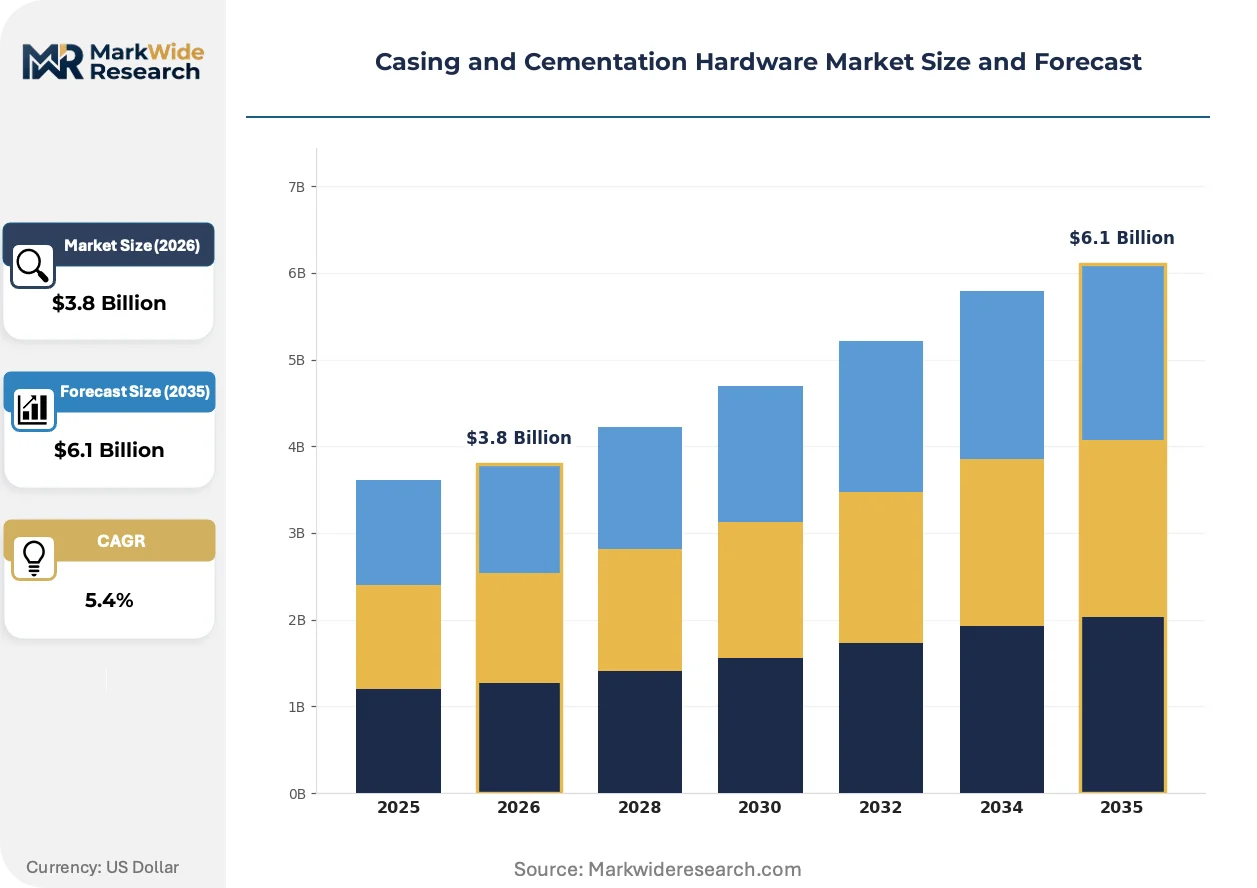
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casing Centralizers, Casing Scrapers, Float Equipment, Cementing Heads End User: Oil & Gas Operators, Drilling Contractors, Service Providers, Offshore Developers Technology: Conventional Cementing, Smart Cementing, Eco-friendly Solutions, Advanced Monitoring Application: Onshore Drilling, Offshore Drilling, Wellbore Stability, Hydraulic Fracturing |
| Companies Covered | Baker Hughes Company, National Oilwell Varco Inc., Tenaris S.A., Centek Group, Summit Casing Equipment, Vallourec S.A., Weatherford International plc, Schlumberger Ltd., Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casing and Cementation Hardware Market Strategic Shifts
Digital instrumentation is penetrating cementing hardware at the wellsite, transforming passive mechanical devices into sensor-enabled systems that feed real-time data into drilling optimization platforms and reshape supplier value propositions.
Composite centralizer technology is fragmenting the conventional spring steel market as thermoplastic variants with embedded RFID tracking tags gain adoption in North American shale basins. Operators running extended-reach laterals in the Permian Basin are specifying these units for their corrosion resistance and reduced friction coefficients during casing runs. The shift is compressing addressable volume for traditional metal-forming suppliers while opening margin pools for polymer compounders with oilfield certification.
EPA methane emission detection requirements are tightening hardware qualification protocols for Gulf of Mexico operations. The agency's evolving verification standards are mandating cement bond log systems with continuous annular monitoring capabilities rather than post-cementing spot checks. Deepwater contractors are responding by specifying float equipment with integrated pressure transducers capable of transmitting real-time integrity data to surface control systems.
Buying patterns among independent shale operators are consolidating around integrated service packages that bundle casing accessories with cementing execution. Mid-size producers in the Permian and Eagle Ford are abandoning discrete hardware procurement in favor of performance-based contracts where suppliers assume zonal isolation risk. This restructuring is compressing distributor margins while rewarding manufacturers with in-house cementing service capabilities.
Casing and Cementation Hardware Market Segmentation
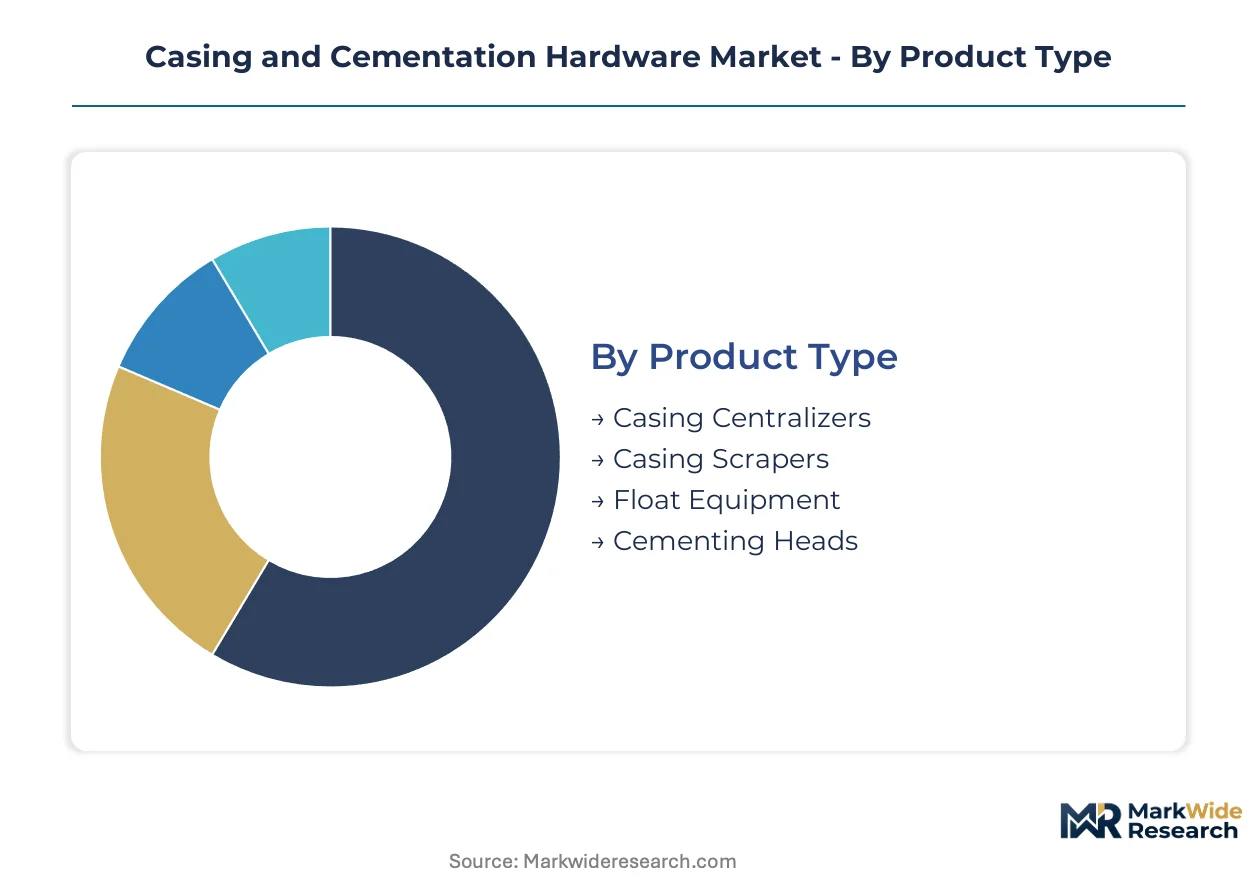
Casing and cementation hardware demand fragments across product specifications, end-user procurement patterns, and technology tiers that reshape competitive positioning. Understanding these divisions clarifies where margin pools concentrate and which segments drive replacement cycles versus greenfield expansion.
Product Type:
Domestic manufacturing concentrates float equipment and cementing heads for Gulf of Mexico shelf projects, while casing centralizers and scrapers flow from export-oriented mills serving Brazilian pre-salt and West African deepwater developments.
- Float Equipment:Redundant backpressure control systems incorporating dual-valve configurations prevent cement fallback during primary cementing in high-pressure formations. Brazilian operators below 2,000 meters water depth specify API 5CT-compliant units with enhanced collapse ratings, driving premium-grade procurement from specialty foundries.
- Cementing Heads:Automated rotating heads with real-time pressure telemetry enable continuous circulation during extended-reach laterals. Permian Basin drilling contractors specify these for wells exceeding 3,000 meters measured depth where zonal isolation failure carries catastrophic completion cost exposure.
- Casing Centralizers:Spring steel and thermoplastic composite variants maintain standoff ratios above 67% during cement placement.
- Casing Scrapers:Mechanical and hydraulic designs remove drilling mud and filter cake from casing interiors before cementing operations.
Float equipment commands the established base. The steepest expansion runs through cementing heads.
End User:
Cost tier stratification separates integrated oil companies running proprietary procurement standards from independent operators purchasing through bundled service contracts.
- Oil & Gas Operators:Supermajors and national oil companies specify API 5CT Grade C110 and Q125 sour-service alloys with full material traceability documentation. These buyers maintain direct relationships with seamless pipe mills, bypassing distributor markups for high-volume casing string orders.
- Offshore Developers:Deepwater contractors in Brazil and West Africa demand redundant float valve configurations and continuous annular monitoring capabilities under evolving EPA methane verification protocols. Their procurement cycles align with multi-billion dollar field development timelines spanning five to seven years.
- Drilling Contractors:Onshore rig operators source standardized centralizer systems through bulk purchasing agreements with oilfield distributors.
- Service Providers:Cementing companies bundle hardware deployment with slurry placement execution under performance-based contracts.
Oil & Gas Operators anchor volume leadership. Offshore Developers are climbing the fastest as deepwater sanctioning accelerates.
Technology:
Application complexity determines technology selection, with conventional systems retaining dominance in vertical wells while smart systems penetrate extended-reach and high-pressure formations.
- Smart Cementing:Real-time pressure telemetry and automated slurry density adjustment systems integrate with surface control networks to optimize cement placement. Permian Basin laterals deploy these for precise zonal isolation where natural fracture networks threaten cement sheath integrity.
- Advanced Monitoring:Cement bond log hardware with embedded sensor arrays enables continuous annular integrity verification rather than post-cementing spot checks. Gulf of Mexico contractors specify these under tightening EPA methane emission detection requirements.
- Conventional Cementing:Standard mechanical centralizers and single-valve float equipment serve low-complexity vertical wells.
- Eco-friendly Solutions:Biodegradable drilling fluid additives and reduced-cement-volume systems address environmental compliance in sensitive geographies.
Conventional Cementing retains volume dominance. Smart Cementing gains share fastest as telemetry costs decline and well complexity escalates.
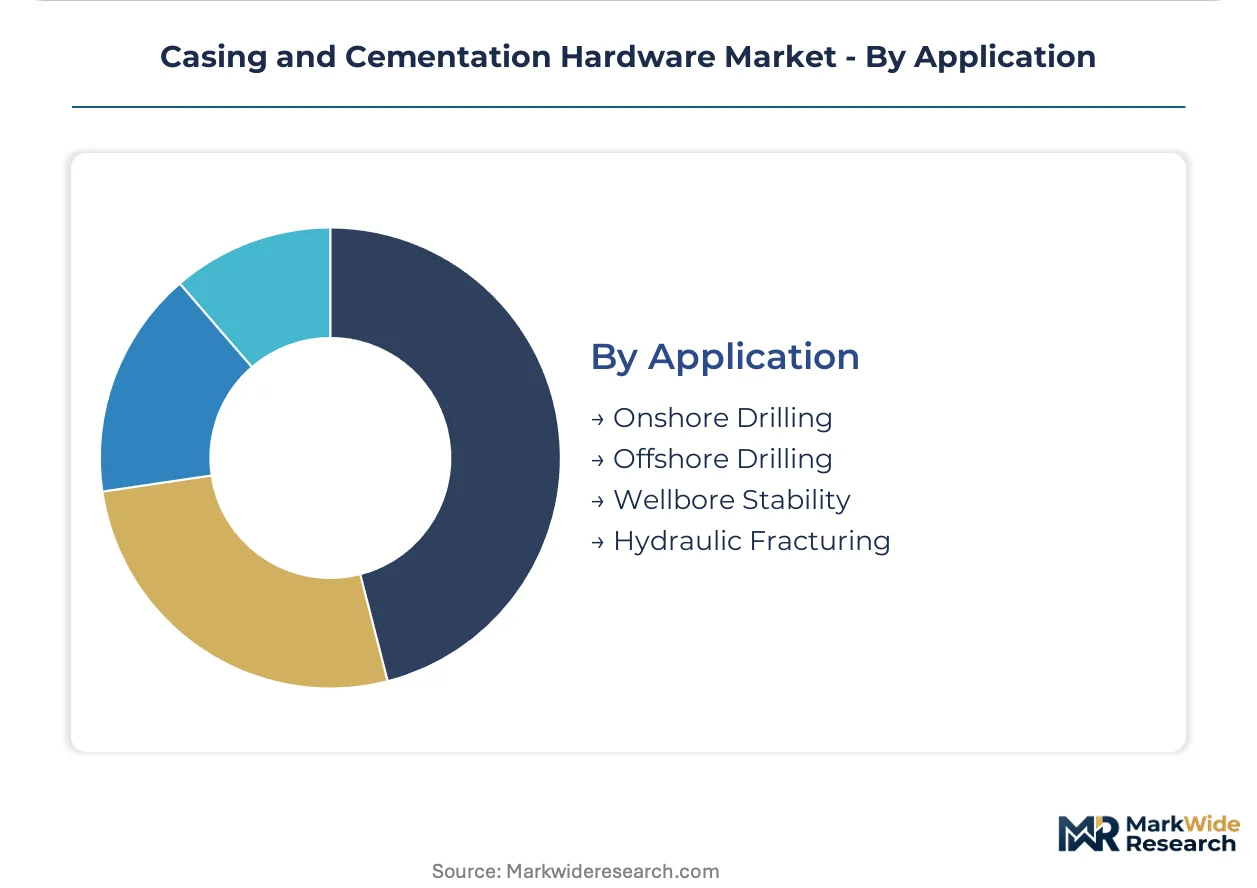
Application:
Volume concentration versus margin opportunity splits across onshore standardization and offshore customization requirements.
- Offshore Drilling:High-pressure high-temperature formations beneath 2,000 meters water depth require premium alloy casing strings with integrated centralizer subs and redundant float equipment. Brazilian pre-salt and West African subsalt projects specify API 5CT Q125 grades with specialized corrosion fatigue analysis.
- Hydraulic Fracturing:Extended-reach laterals in the Permian Basin demand precise standoff maintenance through composite centralizers and cementing heads with automated density control. Lateral lengths exceeding 3,000 meters strain conventional cementing practices.
- Onshore Drilling:Standard vertical and directional wells deploy conventional cementing hardware with minimal instrumentation.
- Wellbore Stability:Casing programs in geologically complex formations require specialized centralizer spacing and cement sheath design.
Onshore Drilling holds the volume base. Offshore Drilling shows the steepest expansion trajectory as deepwater breakevens improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty steel mills in the United States, Germany, and Japan control premium alloy supply for sour-service casing grades. Deepwater procurement cycles in Brazil and West Africa now drive hardware qualification timelines. Shale operators in Argentina and Australia are importing centralizer systems as lateral lengths extend beyond 3,000 meters.
United States
Permian Basin drilling contractors specify composite centralizers and automated cementing heads for extended-reach laterals exceeding 3,000 meters measured depth. The EPA's UIC Class II well integrity standards mandate redundant float valve configurations for Gulf of Mexico shelf projects. Houston anchors domestic manufacturing capacity for float equipment serving federal offshore leases.
Brazil
Pre-salt basin operators below 2,000 meters water depth procure API 5CT Q125-grade casing strings with enhanced collapse ratings. The country's national petroleum regulator ANP enforces blowout preventer integration rules that extend qualification timelines for cementing hardware. Macaé industrial cluster concentrates foundry capacity for premium float equipment destined for deepwater developments.
Germany
Specialty steel producers supply chromium-molybdenum alloys for sour-service casing specifications across European offshore projects. REACH chemical regulations govern thermoplastic composite centralizer formulations used in North Sea applications. Duisburg-Ruhr industrial corridor hosts precision metal-forming operations for spring steel centralizer manufacturing.
West Africa
Angolan and Nigerian offshore contractors demand redundant backpressure control systems for high-pressure subsalt formations. Local content regulations require hardware assembly within regional fabrication yards to qualify for production sharing contract incentives. Port Harcourt and Luanda anchorage zones concentrate cementing service provider operations for deepwater field developments.
Argentina
Vaca Muerta shale operators in Neuquén province import premium centralizer systems as lateral lengths strain conventional cementing practices. The country's hydrocarbon investment promotion regime offers tax stability certificates for hardware procurement tied to unconventional development. Neuquén city industrial parks host assembly operations for composite centralizers with embedded RFID tracking capabilities.
Casing and Cementation Hardware Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the casing and cementation hardware sector. Integrated oilfield service conglomerates anchor premium-tier positioning through proprietary smart cementing systems and real-time telemetry integration. Specialized casing accessory manufacturers compete on alloy metallurgy expertise and API certification density. The dominant competitive moves involve backward integration into specialty steel supply and geographic expansion through regional fabrication yard partnerships.
Within the integrated service tier, Baker Hughes Company and Schlumberger Ltd. occupy positions defined by bundled hardware-deployment contracts. Among seamless pipe specialists, Tenaris S.A. and Vallourec S.A. exemplify manufacturers where material traceability documentation commands procurement priority for sour-service well applications. National Oilwell Varco Inc. represents the aftermarket service density archetype competing through North American shale basin coverage rather than manufacturing scale.
| Leading Market Players |
|---|
| Baker Hughes Company |
| National Oilwell Varco Inc. |
| Tenaris S.A. |
| Centek Group |
| Summit Casing Equipment |
| Vallourec S.A. |
| Weatherford International plc |
| Schlumberger Ltd. |
| Halliburton Company |
| Others |
Value Chain & Pricing Dynamics
API 5CT specification upgrades gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb metallurgical revalidation costs while creating tiered access based on certification density and material traceability documentation.
Pricing Analysis
API 5CT dictates the pricing tier structure across premium, standard, and economy levels, separating Q125 sour-service alloys with full material pedigree from commodity-grade alternatives. Price differentiation rests on collapse rating certification and geographic delivery cost to deepwater basins. Cost compression in standard-grade segments intensifies because composite centralizer substitution erodes metal-forming margins. Independent shale operators exhibit highest price sensitivity, while Brazilian pre-salt contractors prioritize performance guarantees over unit economics.
Supply Chain Analysis
United States, Germany, and Japan anchor specialty steel production for chromium-molybdenum alloys serving sour-service specifications. Raw material flows draw from premium-grade steel mills, thermoplastic compounders with oilfield certification, and sensor component suppliers for telemetry integration. Single-source vulnerability concentrates in specialty alloy supply from limited-charge foundries. Distribution runs through oilfield service distributors, direct mill relationships for supermajors, and bundled performance contracts for mid-size operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart cementing technology penetration signals early-cycle expansion, with real-time telemetry adoption in extended-reach laterals creating outsized growth pockets before market saturation.
For Market Incumbents: Compound manufacturing scale in Brazilian and West African fabrication yards to capture deepwater procurement cycles. Defend against composite centralizer displacement by acquiring polymer compounders with API certification. Prioritize backward integration into specialty steel supply to offset alloy cost volatility and secure Q125-grade allocation.
For New Entrants and Emerging Players: Anchor in Argentina's Vaca Muerta shale expansion where lateral length extension strains incumbent capacity. Target cementing head automation for Permian Basin contractors abandoning discrete hardware procurement. Pursue performance-based contracting models that bundle hardware deployment with zonal isolation guarantees.
For Investors and Strategic Acquirers: EPA methane emission verification protocols reshape the acquisition landscape toward sensor-embedded hardware capabilities. Five-to-ten-year viability favors targets with smart cementing telemetry integration and cement bond log sensor array development. Monitor BSEE certification timeline extensions as inflection signal for qualification bottleneck severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Cementing Technology Integration | Real-time pressure telemetry from Baker Hughes and Schlumberger captures premium-tier contracts in Permian extended-reach laterals. |
| Specialty Alloy Backward Integration | Tenaris and Vallourec captive supply of chromium-molybdenum steel insulates against foundry capacity constraints. |
| Composite Centralizer Manufacturing Scale-Up | Thermoplastic variants with embedded RFID displace spring steel in North American shale basins. |
| Deepwater Fabrication Yard Partnerships | Macaé and Port Harcourt regional assembly qualifies suppliers for Brazilian and West African local content incentives. |
| Performance-Based Service Contracting | Bundled hardware-deployment with zonal isolation risk transfer aligns with independent operator procurement consolidation. |
Study Parameters
A spread of perspectives from drilling contractors, cementing service engineers, procurement managers at national oil companies, and specialty steel metallurgists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through API specification documentation, BSEE regulatory filings, EPA enforcement databases, and customs trade records for alloy-grade steel imports. Bottom-up product category sizing triangulated against top-down energy sector capital expenditure patterns.
Segmentation dimensions modeled include product type, end-user procurement tier, technology sophistication, and application complexity across the projection horizon. CAGRs derived from installation volume trajectories weighted by specification-grade pricing differentials. Forecast inputs incorporated deepwater sanctioning timelines, shale lateral length extension curves, and regulatory compliance cost escalators.
Material uncertainties — alloy supply disruption, BSEE certification delays, or composite substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption rates and procurement pattern stability. Recalibration cycles align with material shifts in regulatory enforcement intensity and deepwater project sanctioning velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Well Test Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Slickline Services Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Subsea Well Intervention Market