
 Hydraulic Workover Units Market | 2026-2036
Hydraulic Workover Units Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Workover Units Market Analysis
Asset-light leasing and project-based financing is rewriting competitive entry barriers for hydraulic workover capacity. Halliburton leverages its integrated service portfolio to bundle workover units with complementary well intervention technologies. Superior Energy Services anchors its position through specialized offshore deployment capabilities in the Gulf of Mexico. National Oilwell Varco controls critical manufacturing scale for mast and substructure assemblies that service companies depend upon.
Hydraulic workover units are self-contained rig systems that use hydraulic power to perform snubbing, tubing conveyance, and wellbore maintenance operations at working pressures typically exceeding 5,000 psi, designed to access wells without removing the existing Christmas tree or wellhead. Their primary purpose centers on live-well intervention, plug and abandonment, and completion work in mature fields where full drilling rigs prove economically unjustified. Modular and skid-mounted configurations command attention for their transportability between marginal well clusters and rapid mobilization timelines. Electric drive variants are gaining traction where operators face flaring restrictions and seek to reduce engine exhaust emissions during prolonged workover campaigns. Conventional hydraulic units still dominate total installed fleet hours due to proven reliability in remote locations with limited electrical infrastructure.
API standards govern pressure control equipment certification requirements that manufacturers and service providers must satisfy for North American market access. OSHA workplace safety regulations mandate fall protection and pressure testing protocols that directly influence unit design and crew training expenditures. EPA emissions standards for non-road diesel engines are accelerating capital turnover toward Tier 4 Final and equivalent powertrain configurations. Stakeholders must weigh fleet electrification roadmaps against the residual value of conventional hydraulic assets as regulatory thresholds tighten across major operating basins.
Market Dynamics
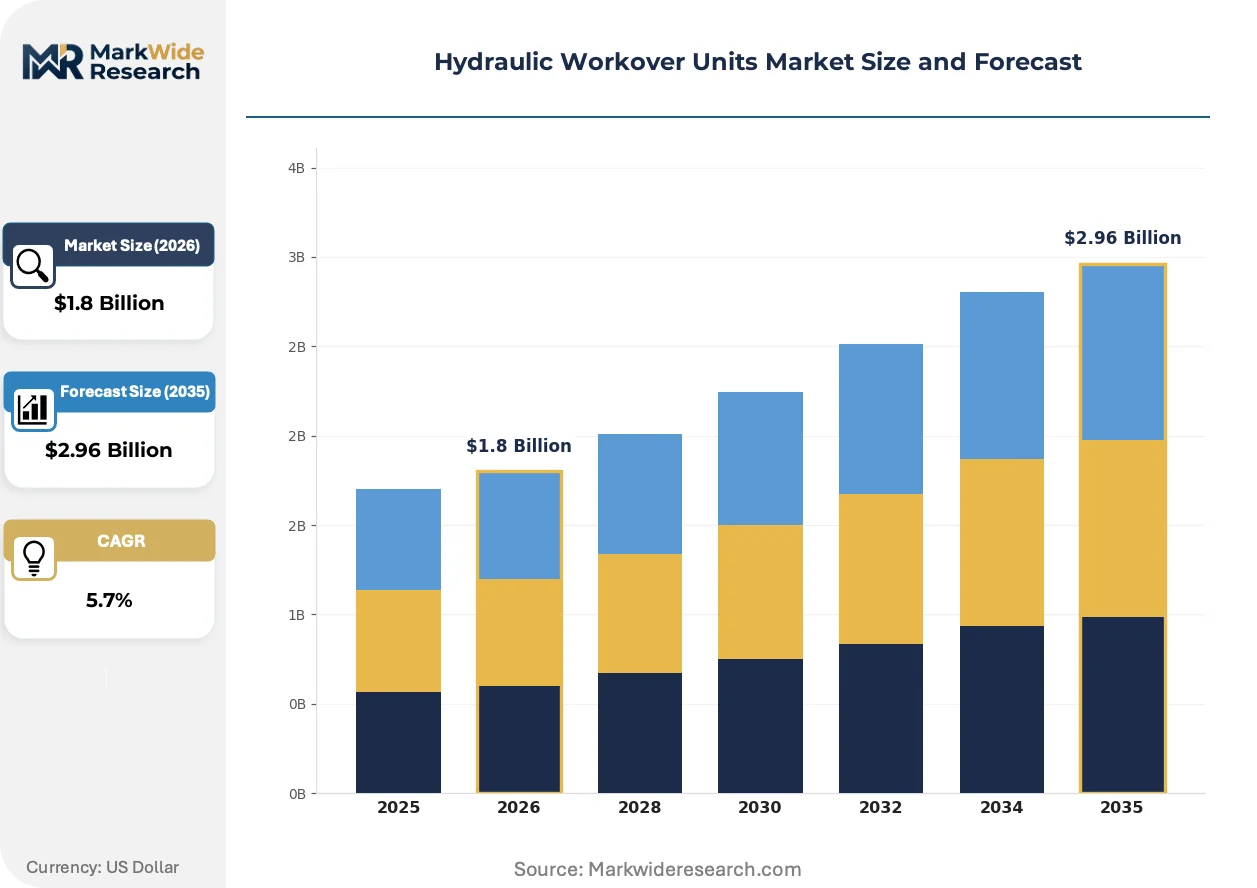
Asset-light leasing models are compressing capital barriers for hydraulic workover capacity deployment, while EPA Tier 4 Final emissions mandates accelerate fleet turnover toward cleaner powertrains. This structural tension between financial flexibility and regulatory compliance is redrawing competitive positioning across North American well intervention services.
Growth Catalysts
- Legacy well stock maturation:The Permian Basin's aging horizontal wells require sustained snubbing and recompletion services that hydraulic workover units deliver more economically than full drilling rigs.
- OSHA workplace safety mandates:Stricter fall protection and pressure testing protocols are standardizing crew training and equipment certification, elevating demand for compliant, professionally operated units.
- Electric drive technology maturation:Battery-hybrid powertrains are penetrating flaring-restricted basins where operators face methane emission penalties and seek to eliminate diesel exhaust during extended campaigns.
Market Restraints
- Specialized steel and mast assembly concentration:Critical substructure components rely on a concentrated supplier base in Gulf Coast fabrication yards, creating vulnerability to input cost volatility and delivery delays.
- API 16ST certification complexity:Pressure control equipment standards impose lengthy testing timelines and documentation burdens that extend new unit time-to-market by 6-12 months.
- Coiled tubing substitution:Continuous pipe technologies are capturing select live-well intervention applications previously dominated by hydraulic snubbing units, particularly in shallow, low-pressure environments.
Strategic Opportunities
- Modular skid-mounted configurations:Transportable systems designed for marginal well clusters enable rapid mobilization between pad sites, opening service models in the Bakken and Eagle Ford.
- Project-based financing structures:Leasing partnerships with regional banks and equipment lessors allow mid-tier operators to access workover capacity without balance sheet strain.
- Offshore Gulf of Mexico specialization:Platform-based intervention demand for plug and abandonment work creates premium pricing potential for units with marine certification and dynamic positioning compatibility.
Industry Challenges
- Experienced snubbing crew scarcity:Live-well intervention demands specialized technicians certified in pressure control and wellbore dynamics, with training pipelines failing to match retirement outflows.
- Legacy fleet electrification retrofit economics:Conventional hydraulic units retain residual value in remote basins with limited grid access, complicating capital allocation toward zero-emission replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Workover Units Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Conventional, Electric, Modular, Skid-mounted Application: Well Intervention, Abandonment, Completion, Maintenance End User: Oil & Gas Operators, Service Companies, Contractors, Independents Deployment: Onshore, Offshore, Mobile, Fixed |
| Companies Covered | Cudd Energy Services, Superior Energy Services, Halliburton, Basic Energy Services, High Arctic Energy Services, National Oilwell Varco, Precision Drilling Corporation, Schlumberger, Archer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Workover Units Market Emerging Trajectories
Technology convergence and regulatory stringency are forcing simultaneous evolution across powertrain design, pressure control architecture, and service delivery models. These shifts are compressing traditional equipment lifecycles while opening new competitive wedges for adaptable suppliers.
Electric drive systems are migrating from niche demonstration projects to mainstream deployment in emissions-constrained basins. Operators in the Delaware Basin and parts of Colorado are specifying battery-hybrid units for multi-well pad campaigns where flaring restrictions apply. This transition is compressing demand for conventional diesel-hydraulic configurations while creating aftermarket service opportunities for grid infrastructure and charging logistics.
EPA non-road diesel engine standards are tightening certification requirements for hydraulic powerpacks and mast hoisting systems. Manufacturers must now validate Tier 4 Final compliance across the full operating envelope, not just rated power conditions. This regulatory pressure falls most heavily on smaller fleet operators lacking in-house emissions engineering capabilities, accelerating consolidation toward integrated service companies with dedicated compliance resources.
Service contracting is fragmenting from bundled rig-and-crew arrangements toward unbundled equipment leasing with operator-supplied personnel. Large independents in the Permian are piloting this model to retain operational control while avoiding capital ownership. The shift is most visible in West Texas and southeastern New Mexico, where asset-light structures are displacing traditional day-rate contracts for routine workover programs.
Hydraulic Workover Units Market Segmentation
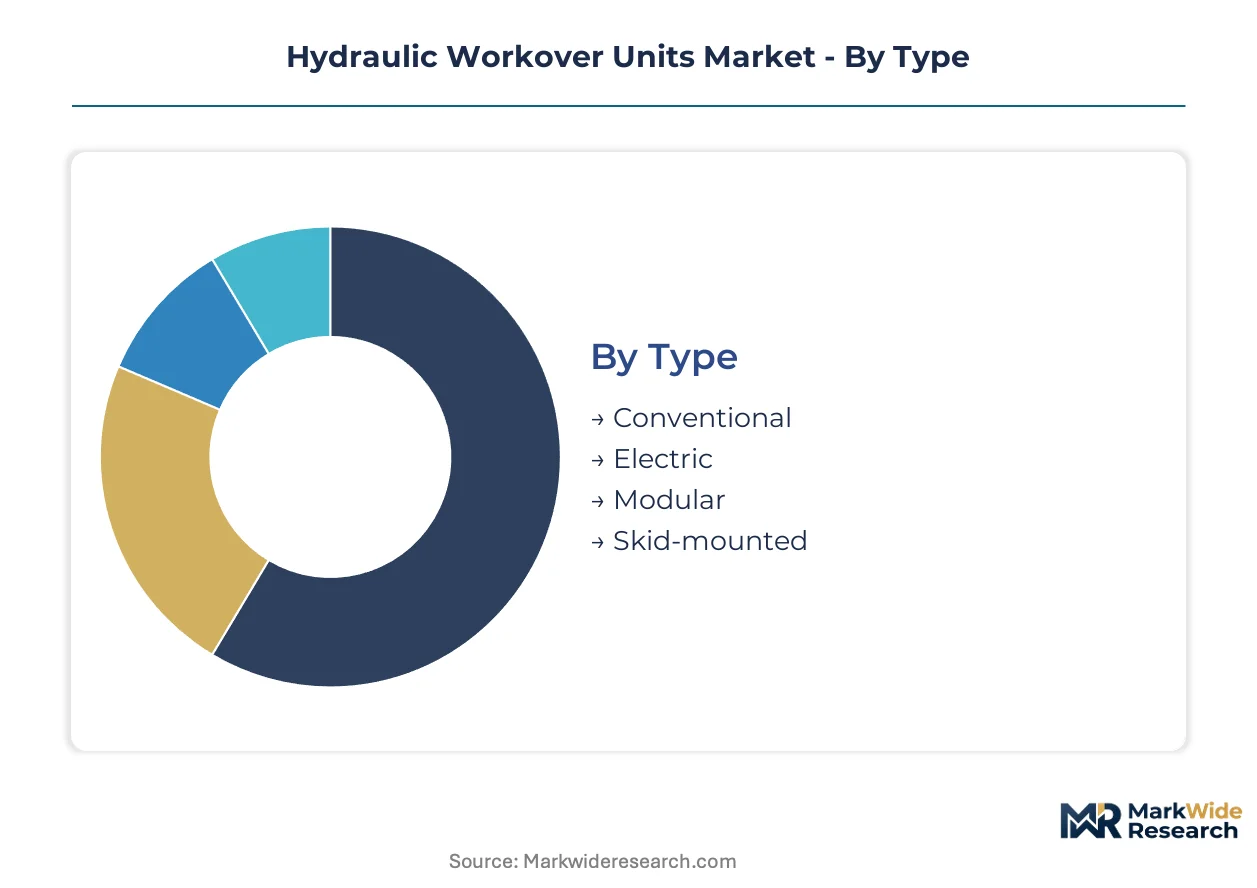
Hydraulic workover unit configurations vary dramatically in capital intensity and mobilization speed. Segment selection directly determines project economics, regulatory exposure, and crew certification requirements across well intervention programs.
Type:
Cycle times differ sharply across powertrain architectures, with conventional diesel units turning over fastest in spot markets while electric variants face longer procurement lead times tied to battery system integration.
- Conventional:Diesel-hydraulic powerpacks deliver proven reliability in remote Permian Basin locations lacking electrical infrastructure. Demand concentrates among legacy operators prioritizing asset utilization over emissions compliance, though EPA Tier 4 Final mandates are compressing residual value horizons.
- Electric:Battery-hybrid configurations eliminate exhaust emissions during extended Delaware Basin campaigns where flaring restrictions apply. Operators in Colorado and New Mexico are specifying these units for multi-well pad programs, accepting longer mobilization timelines for regulatory compliance benefits.
- Modular:Component-based architectures enable field reconfiguration between snubbing and conveyance operations.
- Skid-mounted:Transportable frames suit marginal well clusters requiring rapid site-to-site relocation.
Conventional units dominate installed base. Electric configurations are where expansion concentrates.
Application:
Revenue concentration tracks well lifecycle stage, with intervention work generating recurring demand while abandonment projects spike episodically around regulatory deadlines.
- Well Intervention:Live-well snubbing and recompletion services address aging horizontal wellbores in West Texas legacy fields. Service companies bundle hydraulic workover units with coiled tubing for integrated intervention packages, capturing sustained demand from Permian Basin operators managing declining production curves.
- Abandonment:Plug and abandonment operations accelerate around Gulf of Mexico platform decommissioning schedules and state-mandated orphan well programs. Units with marine certification command premium pricing for offshore deployment where full rig economics prove unjustified.
- Completion:Final well assembly and testing support new drill programs in the Bakken and Eagle Ford.
- Maintenance:Routine tubing replacement and wellhead servicing sustains marginal producer operations.
Intervention work dominates installed base. Abandonment services are expanding most quickly.
End User:
Procurement authority splits between capital-owning operators and asset-light service providers, reshaping contract structures and equipment financing requirements.
- Oil & Gas Operators:Majors and large independents in southeastern New Mexico retain workover units for proprietary well programs, prioritizing operational control over cost flexibility. These buyers specify electric drive variants for ESG reporting compliance and direct vendor relationships for pressure control equipment certification.
- Service Companies:Halliburton and Superior Energy Services maintain owned fleets for bundled service delivery, capturing margin through integrated crew and equipment deployment. Their procurement concentrates on modular configurations enabling rapid reallocation between client programs.
- Contractors:Third-party operators lease capacity to smaller producers lacking in-house intervention expertise.
- Independents:Privately held exploration companies favor project-based financing for episodic workover demand.
Service companies dominate installed base. Independents are where fleet expansion concentrates.
Deployment:
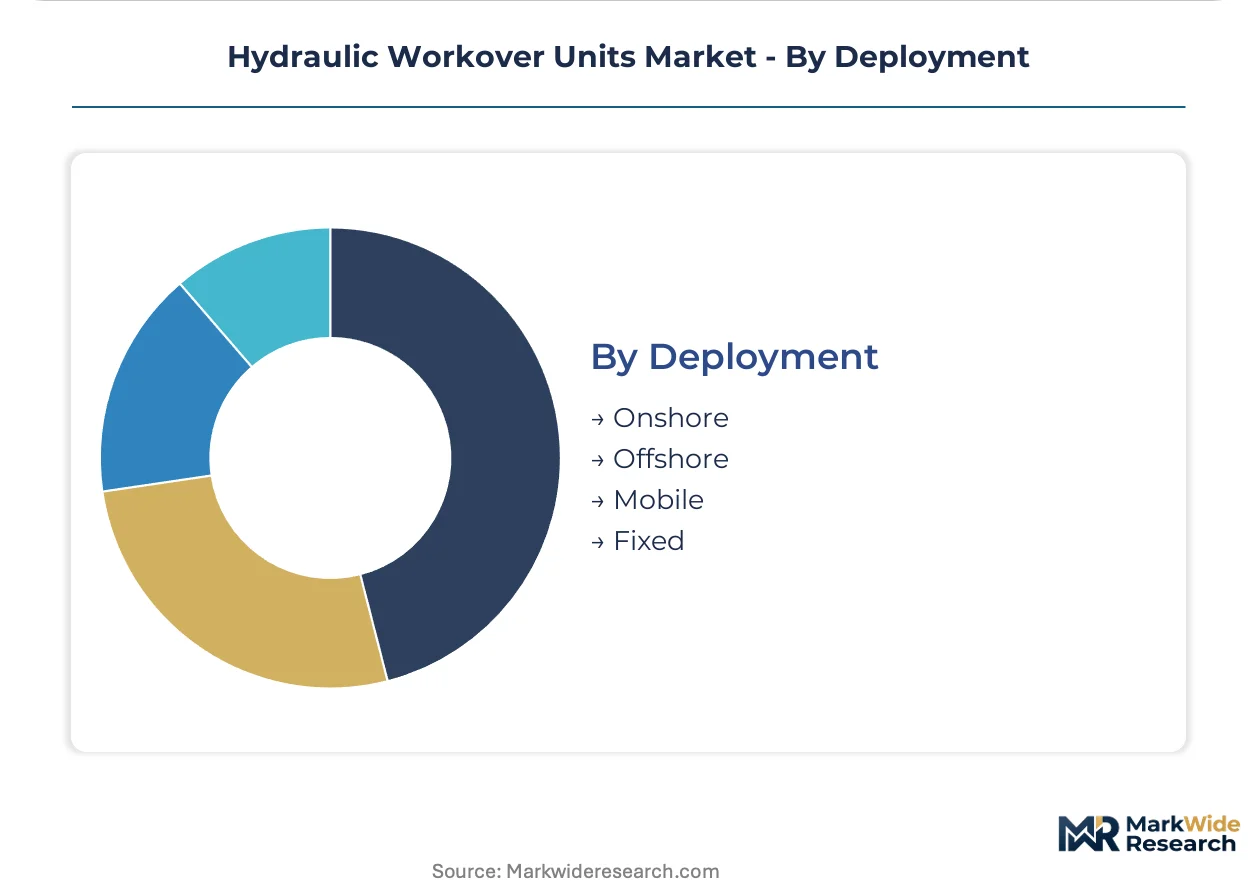
Geographic mobility requirements dictate structural design, with offshore units carrying marine certification costs that onshore configurations avoid.
- Onshore:Pad-mounted and mobile systems serve Permian Basin well clusters where road access permits rapid relocation. These units face the steepest competitive pressure from coiled tubing substitution in shallow, low-pressure environments.
- Offshore:Platform-compatible configurations with dynamic positioning integration target Gulf of Mexico plug and abandonment demand. Marine certification requirements from the US Coast Guard extend delivery timelines and elevate crew training expenditures.
- Mobile:Truck-transportable units enable spot market participation across multiple basins.
- Fixed:Permanent installation on production platforms suits long-term field maintenance programs.
Onshore deployment dominates installed base. Offshore specialization is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in pressure control equipment tilt toward net importing positions across most consuming basins, with specialized mast assemblies and substructure components moving from Gulf Coast fabrication centers to Permian Basin deployment sites. Equipment certification standards create regulatory friction that shapes cross-border trade patterns.
United States
West Texas and southeastern New Mexico anchor domestic demand through legacy well intervention programs in the Permian Basin. EPA Tier 4 Final emissions standards for non-road diesel engines accelerate capital turnover toward cleaner powertrain configurations. Houston-Galveston fabrication yards concentrate critical mast and substructure manufacturing capacity that supplies North American service companies.
Canada
Alberta's oil sands and conventional heavy oil fields generate sustained abandonment and workover demand as mature assets reach end-of-life. Health Canada and provincial regulators enforce pressure equipment safety standards aligned with API specifications but with additional provincial registration requirements. Calgary-based equipment lessors are expanding asset-light leasing models into the Bakken formation straddling the Saskatchewan-Montana border.
Mexico
Pemex's mature onshore fields in Veracruz and Tabasco require rehabilitation services as production declines accelerate from aging infrastructure. The national hydrocarbons regulator imposes equipment certification requirements that favor suppliers with established Mexican operating history. Tampico-Madero industrial corridor hosts service company logistics hubs supporting Burgos Basin intervention campaigns.
Norway
North Sea platform decommissioning schedules drive premium demand for offshore-certified hydraulic workover capacity. The Norwegian Petroleum Safety Authority enforces strict well intervention standards that exceed baseline API requirements. Stavanger and Bergen anchor specialized service company clusters focused on subsea and platform-based plug and abandonment work.
Saudi Arabia
Ghawar and Safaniya mature field maintenance programs sustain workover activity as Saudi Aramco manages decline curves across supergiant assets. The national oil company imposes vendor qualification systems that restrict market access to pre-approved equipment suppliers. Dhahran-Riyadh industrial corridor concentrates service company joint ventures and local manufacturing partnerships.
Hydraulic Workover Units Market Vendor Landscape
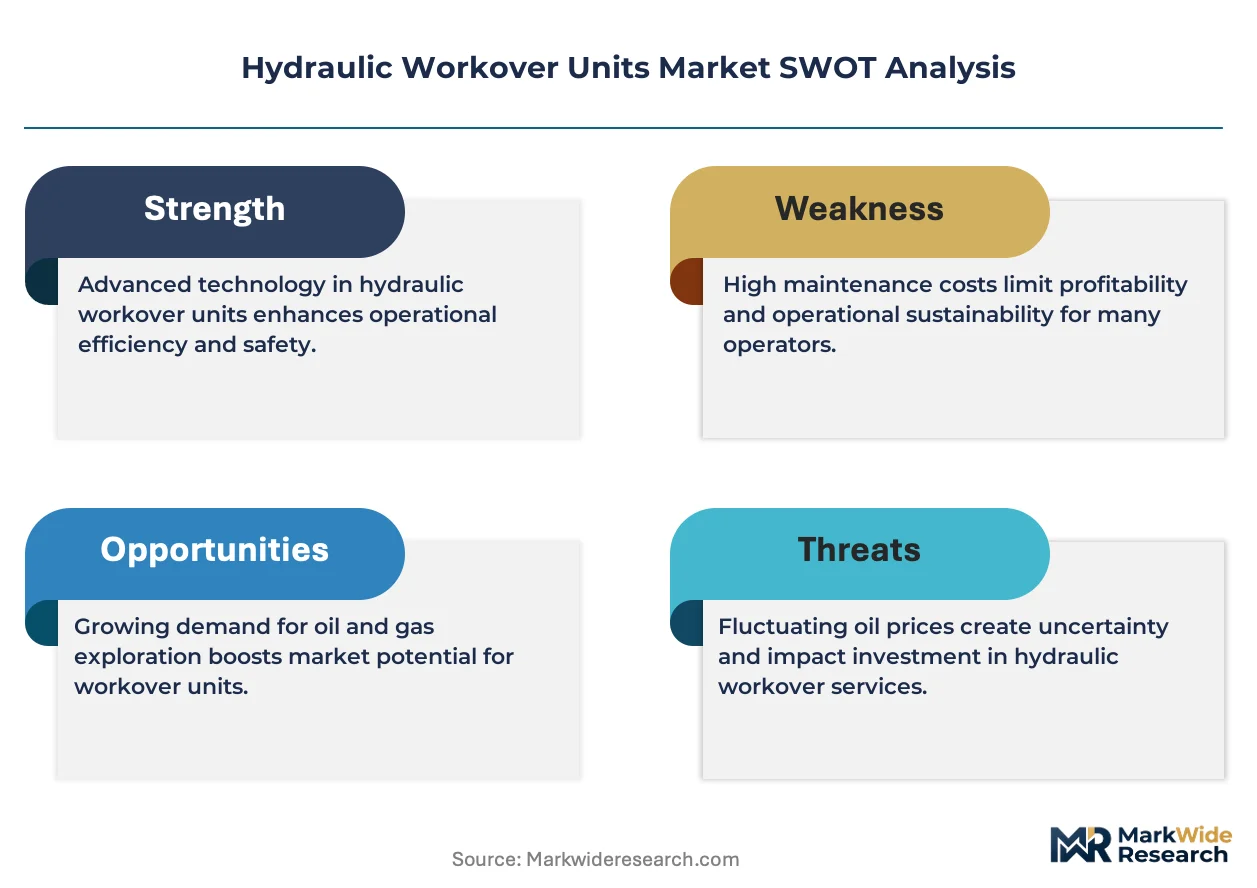
On the supply side, the industry is consolidating around integrated service companies with captive equipment manufacturing and specialized regional operators with basin-specific expertise. Three strategic archetypes dominate: full-service oilfield conglomerates bundling workover units with complementary intervention technologies; pure-play snubbing specialists deploying modular configurations for rapid basin mobility; and equipment fabricators supplying mast assemblies to third-party service providers. Competitive positioning hinges on M&A activity absorbing regional specialists into national platforms and strategic partnerships between service companies and battery-hybrid powertrain suppliers.
Within the integrated service tier, Halliburton and Schlumberger exemplify full-scope operators leveraging global procurement scale and bundled service portfolios. Superior Energy Services occupies a position among specialized North American intervention providers with concentrated Gulf of Mexico offshore capabilities. National Oilwell Varco anchors the equipment manufacturing vector, supplying critical mast and substructure assemblies that independent service companies depend upon for fleet expansion.
| Leading Market Players |
|---|
| Cudd Energy Services |
| Superior Energy Services |
| Halliburton |
| Basic Energy Services |
| High Arctic Energy Services |
| National Oilwell Varco |
| Precision Drilling Corporation |
| Schlumberger |
| Archer |
| Others |
Supply Flow & Price Mechanics
Houston-Galveston freight corridors carry specialized mast assemblies from Gulf Coast fabrication yards to Permian Basin deployment sites, with transport cost volatility feeding directly into equipment lease rate differentiation and compressing margins for operators lacking captive manufacturing capacity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across API 16ST certification grade, volume scale, and after-sales service bundling. Price differentiation tracks pressure control equipment certification tiers and geographic delivery distance from Houston fabrication centers. Cost compression in standard diesel-hydraulic configurations is intensifying because EPA Tier 4 Final compliance investments are squeezing residual value horizons. Small independents exhibit highest price sensitivity, while majors prioritize operational control over rate negotiation.
Supply Chain Analysis
Extended payment terms from regional equipment lessors are easing working capital constraints for mid-tier service companies acquiring modular configurations. Critical substructure components draw from United States, Canada, and Norway fabrication centers. High-grade alloy steel, hydraulic powerpacks, and mast hoisting systems constitute primary input dependencies. Single-source vulnerability concentrates in Gulf Coast mast assembly yards. Distribution runs through Houston-Galveston logistics hubs serving North American basin operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydraulic workover units represent early-cycle expansion as electric drive technology penetration accelerates in emissions-constrained basins, with battery-hybrid configurations capturing share from conventional diesel fleets.
For Market Incumbents: Harden fleet electrification roadmaps through backward integration into battery-hybrid powertrain partnerships, insulating against Tier 4 Final residual value erosion. Consolidate regional specialists in the Bakken and Eagle Ford to defend against asset-light leasing models eroding day-rate contract structures. API 16ST certification investment serves as the priority defensive lever against unbundled equipment leasing fragmentation. For New Entrants and Emerging Players: Mid-market independents in Colorado and New Mexico represent the most penetrable entry point, where ESG reporting requirements outpace legacy fleet turnover capabilities. Project-based financing partnerships with regional banks unlock access to operators avoiding balance sheet ownership. Target modular skid-mounted configurations for rapid mobilization between marginal well clusters. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oilfield conglomerates spinning non-core snubbing divisions, particularly Gulf of Mexico offshore specialists with marine certification assets. Long-term viability centers on electrification transition execution and regulatory compliance infrastructure. Watch EPA enforcement intensity in the Delaware Basin as the inflection signal for electric drive adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Electric drive fleet expansion captures EPA Tier 4 Final compliance premiums in the Permian Basin. |
| Backward Integration | In-house mast assembly production reduces Gulf Coast supplier concentration vulnerability. |
| Technology Licensing | Battery-hybrid powertrain partnerships accelerate fleet turnover without proprietary R&D investment. |
| Long-term Supply Agreement | Fixed-price alloy steel contracts hedge input cost volatility for substructure fabrication. |
| Joint Venture | Regional bank partnerships enable asset-light leasing structures for mid-tier operator access. |
Methodological Framework
The analysis maps conventional, electric, modular, and skid-mounted configurations, each validated through snubbing crew supervisors, equipment procurement managers at service companies, regional bank leasing officers, and aftermarket parts distributors. Primary interviews with these stakeholders combined with secondary validation from API specification documents, EPA emissions certification databases, SEC 10-K filings of listed service companies, and North American well intervention activity reports. Bottom-up unit deployment counts triangulate against top-down basin-level expenditure estimates.
Assumptions held fixed include regulatory enforcement intensity and battery system cost curves, while oil price volatility and electrification subsidy programs were varied across sensitivity scenarios. Segmentation dimensions modeled span powertrain architecture, application type, end-user procurement authority, and deployment environment. CAGRs derive from equipment fleet turnover rates tied to emissions compliance deadlines and well intervention demand intensity. Forecast inputs incorporate EPA Tier 4 Final adoption timelines and electric drive procurement lead times.
Macroeconomic conditions sit as an overlay; deviation in oil price levels, interest rate environments, or steel input costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement and technology cost progression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market
Oil & Gas
Slickline Services Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Perforating Gun Market