
 APAC Oil and Gas Automation Market | 2026-2036
APAC Oil and Gas Automation Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Oil and Gas Automation Market Outlook
China's GB standards for industrial emissions and cybersecurity is broadening the cost-of-entry calculus for automation suppliers seeking refinery contracts. ABB Ltd leverages its integrated electrification portfolio to anchor large-scale DCS deployments across Chinese petrochemical complexes. Yokogawa Electric Corporation specializes in high-reliability safety instrumented systems that sustain operator confidence in hazardous offshore environments.
Oil and gas automation encompasses the hardware, software, and communication layers that enable remote monitoring, process control, and safety management across hydrocarbon extraction, transport, and refining operations, typically operating in temperature ranges from minus 40°C to 85°C for field devices and requiring SIL 3 certification for safety-critical loops. Its primary purpose is to minimize unplanned shutdowns, reduce personnel exposure to hazardous conditions, and optimize throughput across geographically dispersed assets. Control systems and safety systems together capture the dominant share of product-level value, reflecting the irreplaceable role of DCS and SIS platforms in continuous process industries where failure costs escalate exponentially. SCADA and IoT Solutions represent the fastest-expanding technology layer, as pipeline operators and offshore platforms prioritize real-time visibility over vast distances with lean on-site staffing.
China's MEE enforces escalating emissions benchmarks that force refinery operators into automation-led efficiency investments, while Australia's national offshore petroleum safety regulator mandates functional safety audits that shape vendor qualification criteria. Japan's METI promotes digital transformation frameworks that accelerate PLC and IoT adoption across downstream facilities. Stakeholders must weigh regulatory divergence against platform standardization when configuring regional service architectures.
Market Dynamics
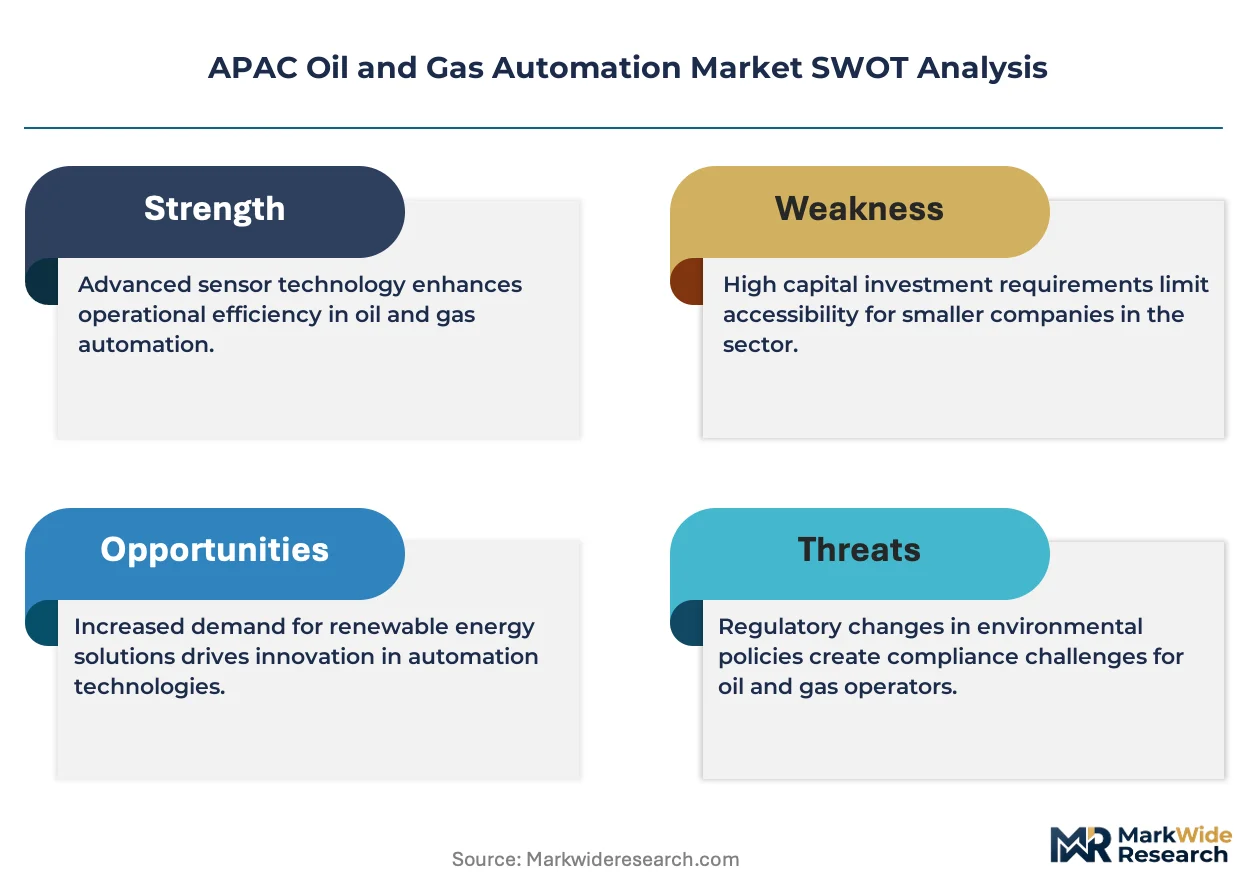
China's dual carbon goals and Australia's offshore safety mandates are compressing procurement cycles for integrated control platforms, forcing automation vendors to reconfigure service architectures around divergent national compliance pathways rather than standardized regional offerings.
Growth Catalysts
- Emissions Benchmarks:China's MEE enforces escalating refinery efficiency standards that mandate automation-led retrofit investments across aging petrochemical corridors.
- Offshore Safety Mandates:Australia's national offshore petroleum safety regulator requires functional safety audits that accelerate safety instrumented system replacements on aging platforms.
- Digital Transformation Frameworks:Japan's METI promotes PLC and IoT adoption across downstream facilities, creating pull for connected field device networks.
Market Restraints
- Semiconductor Supply Concentration:Specialized industrial chip fabrication concentrates in Taiwan and South Korea, exposing DCS and SIS lead times to geopolitical disruption.
- Legacy Protocol Fragmentation:Proprietary fieldbus standards across Chinese, Japanese, and Australian installed bases obstruct seamless platform integration.
- Skilled Technician Scarcity:Certified SIL 3 system engineers remain concentrated in Singapore and Tokyo, constraining deployment velocity in Indonesia and Vietnam.
Strategic Opportunities
- Vietnam Offshore Expansion:Underpenetrated deepwater blocks in the Cuu Long and Nam Con Son basins offer first-mover positioning for remote asset management platforms.
- Hydrogen Blending Infrastructure:Emerging ammonia and hydrogen transport networks require new flow control and leak detection automation architectures.
- Cloud-Native SCADA:Pipeline operators in Western Australia and Queensland are piloting subscription-based visibility platforms that displace capital-intensive on-premise systems.
Industry Challenges
- Cybersecurity Certification Lag:China's GB standards for industrial control system security create multi-month vendor qualification delays for foreign suppliers.
- Intergenerational System Integration:Brownfield refineries in South Korea and Japan must bridge 1980s-era DCS architectures with modern IoT sensor networks without operational shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Oil and Gas Automation Market |
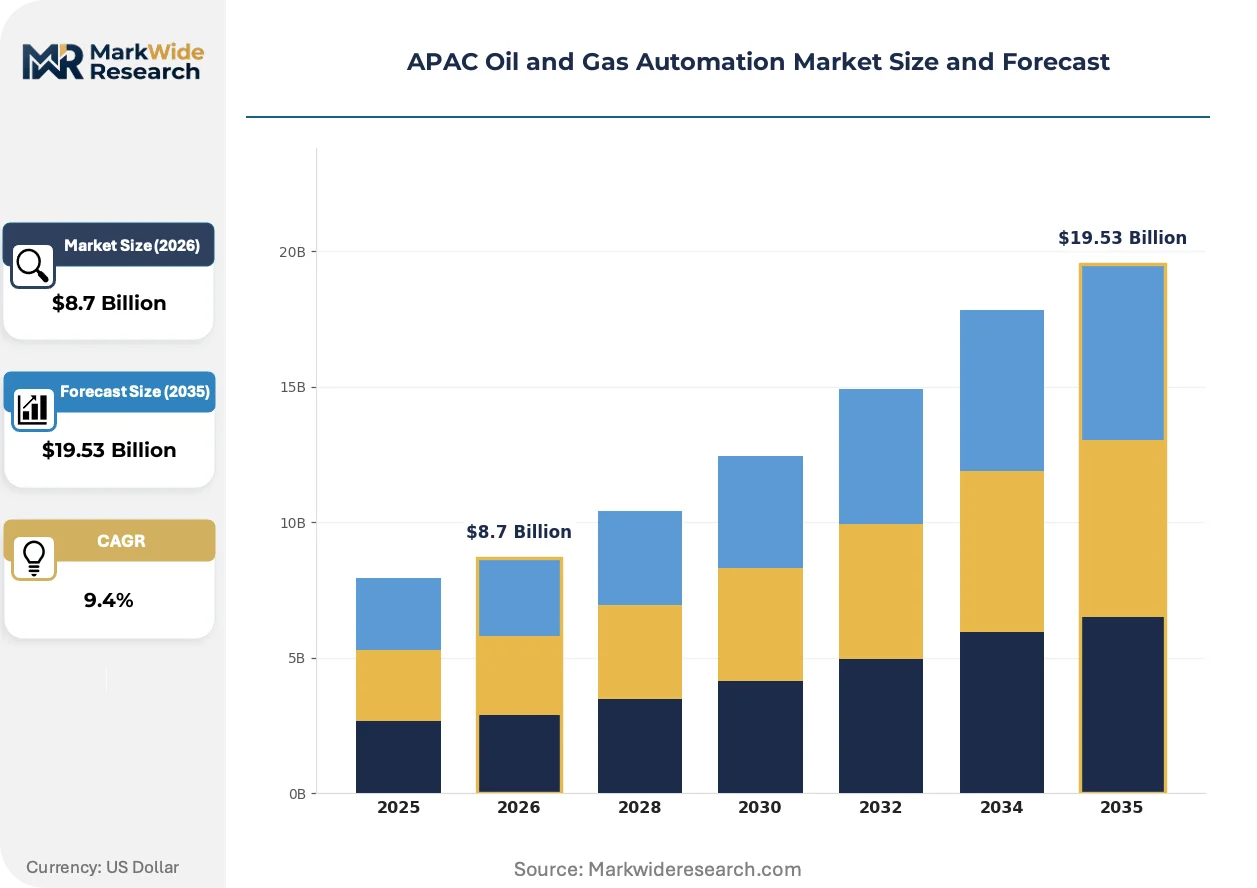
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Safety Systems, Software Solutions, Communication Infrastructure End User: Upstream, Midstream, Downstream, Refineries Technology: SCADA, DCS, PLC, IoT Solutions Application: Drilling Automation, Production Optimization, Asset Management, Pipeline Monitoring |
| Companies Covered | ABB Ltd, Honeywell International Inc., Schneider Electric SE, Rockwell Automation, Emerson Electric Co., Yokogawa Electric Corporation, Siemens AG, Mitsubishi Electric Corporation, General Electric Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Oil and Gas Automation Market Strategic Shifts
Edge computing architectures and AI-driven predictive maintenance are compressing the latency between field data generation and control action, reshaping how operators staff remote facilities across Southeast Asian offshore blocks.
Digital twin technology is rewriting how Australian LNG operators simulate process deviations before they trigger unplanned shutdowns. Major export terminal operators in the Pilbara and Queensland are deploying high-fidelity virtual replicas of cryogenic trains to compress commissioning timelines for expansion projects. This capability is compressing the competitive advantage of established system integrators who previously monopolized startup expertise.
China's GB standards for industrial cybersecurity and emissions monitoring are forcing foreign automation suppliers to localize firmware development and certification testing within mainland facilities. The regulation fragments previously standardized product roadmaps, compelling ABB and Yokogawa to maintain parallel hardware variants for Chinese versus non-Chinese deployments. Refinery operators in Shandong and Guangdong provinces now prioritize vendors with domestic certification laboratories to compress procurement cycles.
Asset operators across the region are unbundling after-sales service contracts from initial system procurement, favoring third-party maintenance specialists over original equipment manufacturer service arms. This pattern concentrates most visibly in Australia's mature North West Shelf LNG infrastructure, where specialized contractors now perform safety system validation previously captive to Yokogawa and Honeywell service divisions. The shift compresses vendor margin pools while expanding opportunities for independent system integrators with offshore certification credentials.
APAC Oil and Gas Automation Market Segmentation
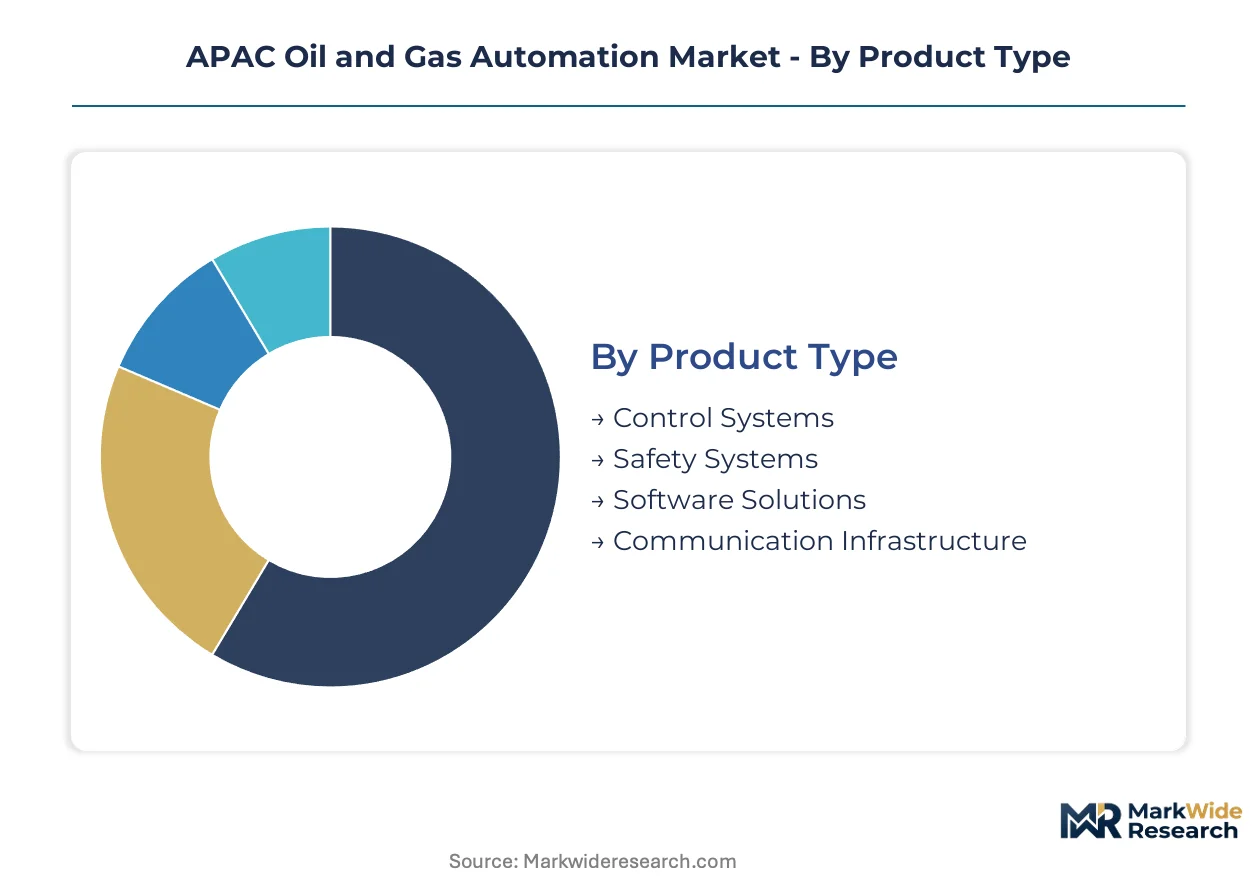
Automation procurement in APAC oil and gas hinges on matching technology layers to operational risk profiles and regulatory compliance burdens. Buyers prioritize certified interoperability over point solutions, compressing vendor shortlists to platforms that span multiple segment boundaries.
Product Type:
Capital allocation intensity separates procurement tiers, with buyers weighting total lifecycle cost against safety certification depth.
- Control Systems:Distributed control platforms orchestrate continuous process variables across refining and petrochemical trains. Chinese state-owned refiners in Shandong and Guangdong provinces anchor regional demand, driven by MEE emissions retrofit mandates that require closed-loop optimization.
- Safety Systems:SIL 3-certified safety instrumented systems execute emergency shutdown sequences in hazardous hydrocarbon environments. Australia's North West Shelf LNG infrastructure and Vietnam's emerging Nam Con Son offshore blocks concentrate replacement demand, shaped by Australia's national offshore petroleum safety regulator audit requirements.
- Software Solutions:Engineering and operations software layers enable alarm management, batch control, and regulatory reporting across heterogeneous installed bases.
- Communication Infrastructure:Hardened industrial Ethernet and wireless field networks bridge geographically dispersed wellheads, platforms, and processing facilities.
Control Systems leads on scale; Software Solutions leads on momentum.
End User:
Operational complexity and regulatory exposure determine technology sophistication thresholds across the value chain.
- Upstream:Exploration and production automation spans subsea control systems, artificial lift optimization, and wellhead monitoring in remote offshore blocks. Australia's LNG export corridor and Vietnam's Cuu Long basin drive platform architecture decisions, constrained by lean staffing models that demand high-reliability remote operation.
- Downstream:Refining automation integrates catalytic process control, emissions monitoring, and product blending optimization. China's aging petrochemical complexes in Jiangsu and Zhejiang provinces concentrate retrofit investment, compelled by dual carbon targets and GB emissions standards.
- Midstream:Pipeline and storage terminal automation prioritizes leak detection, pigging control, and custody transfer metering across extended distances.
- Refineries:Dedicated refining automation captures complex conversion unit control, hydrocracker safety systems, and sulfur recovery optimization in integrated sites.
Downstream commands the largest installed base; Upstream is climbing the fastest.
Technology:
Integration architecture preferences split between centralized deterministic control and distributed connected-device networks.
- SCADA:Supervisory control and data acquisition platforms deliver wide-area visibility across pipeline networks and distributed well pads. Western Australia and Queensland pipeline operators pilot cloud-native subscription models that displace capital-intensive on-premise deployments.
- DCS:Distributed control systems anchor continuous process industries with deterministic loop control and redundant fault tolerance. Japanese METI digital transformation frameworks accelerate PLC-DCS hybrid architectures in downstream facilities.
- PLC:Programmable logic controllers execute discrete sequencing and machine control in auxiliary systems and modular skids.
- IoT Solutions:Connected sensor networks and edge analytics enable predictive maintenance and real-time emissions monitoring.
DCS retains the deepest revenue concentration; IoT Solutions is gaining share fastest.
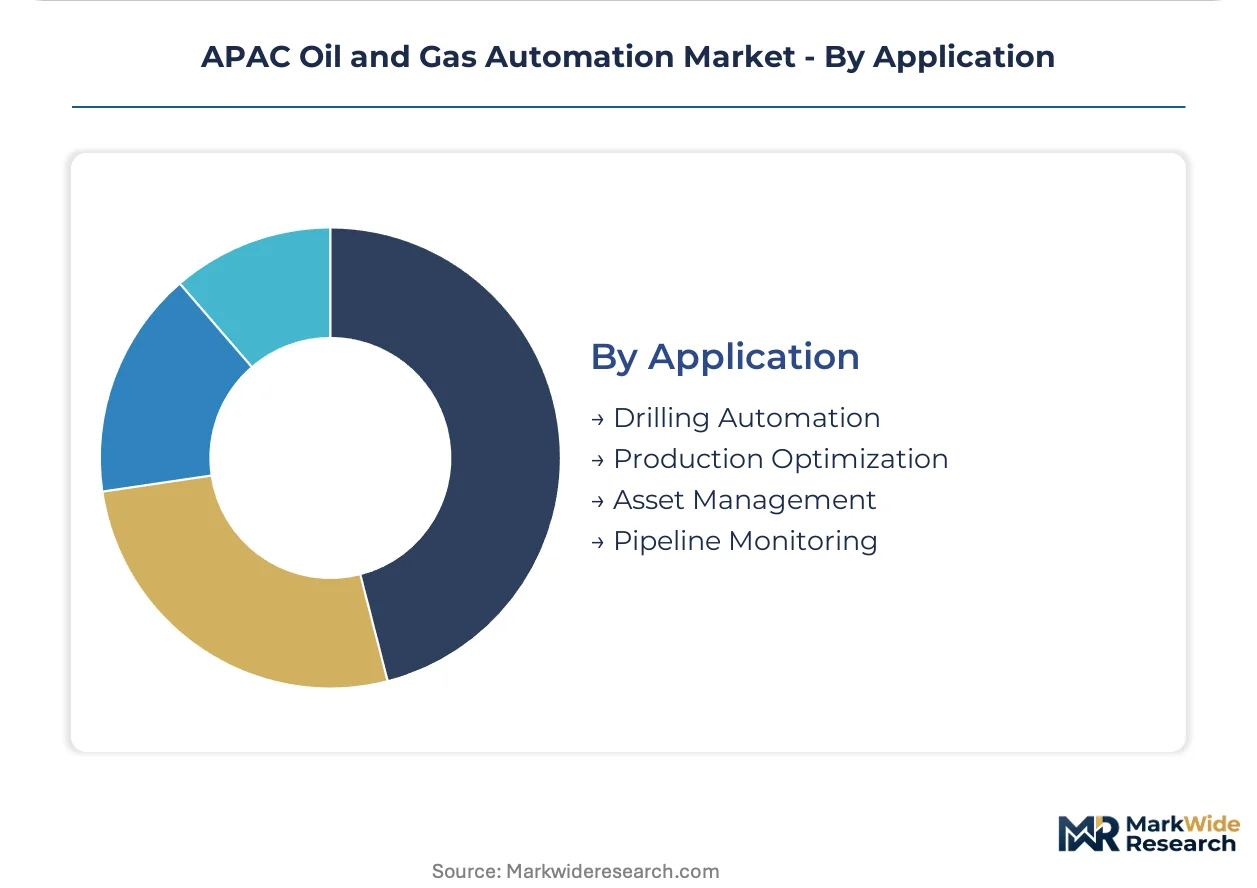
Application:
Specific operational pain points dictate automation priority sequencing within capital budgets.
- Production Optimization:Advanced process control and real-time optimization algorithms maximize throughput across variable feedstock conditions. Australian LNG cryogenic train operators deploy digital twin simulations to compress commissioning timelines and minimize unplanned shutdowns.
- Asset Management:Condition monitoring and predictive maintenance platforms extend equipment life across rotating machinery and electrical infrastructure. Third-party maintenance specialists now perform safety system validation previously captive to OEM service divisions in Australia's mature North West Shelf.
- Drilling Automation:Managed pressure drilling and automated rig control reduce non-productive time in deepwater and unconventional wells.
- Pipeline Monitoring:Fiber optic sensing and computational leak detection protect extended subsea and overland transport corridors.
Production Optimization dominates current spending; Asset Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified SIL 3 system engineers concentrate in Singapore and Tokyo, constraining deployment velocity across Southeast Asian offshore blocks while compressing procurement cycles for integrated control platforms.
China
State-owned refiners in Shandong and Guangdong provinces anchor regional demand for distributed control systems, compelled by MEE emissions retrofit mandates that require closed-loop optimization. GB standards for industrial cybersecurity and emissions monitoring force foreign suppliers to localize firmware development within mainland facilities. Aging petrochemical complexes in Jiangsu and Zhejiang provinces concentrate automation-led efficiency investments driven by dual carbon targets.
Australia
The national offshore petroleum safety regulator mandates functional safety audits that accelerate safety instrumented system replacements on aging North West Shelf platforms. LNG export terminal operators in the Pilbara and Queensland deploy digital twin simulations to compress commissioning timelines for cryogenic train expansions. Third-party maintenance specialists now perform safety system validation previously captive to OEM service divisions across mature infrastructure.
Japan
METI digital transformation frameworks accelerate PLC and IoT adoption across downstream facilities, creating pull for connected field device networks. Refinery operators bridge 1980s-era DCS architectures with modern IoT sensor networks without operational shutdown. The Chubu and Kansai industrial corridors concentrate hybrid automation deployments integrating deterministic control with distributed sensor networks.
Vietnam
Underpenetrated deepwater blocks in the Cuu Long and Nam Con Son basins offer first-mover positioning for remote asset management platforms. Lean staffing models across emerging offshore infrastructure demand high-reliability remote operation capabilities. International operators expanding production sharing contracts prioritize vendors with offshore certification credentials and localized service presence.
South Korea
Brownfield refineries must integrate legacy proprietary fieldbus standards with modern platform architectures without disrupting continuous operations. Semiconductor supply concentration in domestic fabrication facilities exposes DCS and SIS lead times to geopolitical disruption. Ulsan and Yeosu petrochemical clusters drive replacement demand for safety-critical automation systems approaching end-of-design-life.
APAC Oil and Gas Automation Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with capital allocation intensity separating vendor shortlists. The vendor base spans integrated electrification portfolios, high-reliability safety instrumented systems, and cloud-native visibility platforms. Three archetypes dominate: full-spectrum automation conglomerates, safety-system specialists, and emerging IoT-native challengers. Competitive moves concentrate on strategic partnerships for cybersecurity certification and geographic expansion through localized service hubs.
Among diversified industrial conglomerates, ABB Ltd and Siemens AG exemplify full-spectrum positioning spanning electrification through digitalization, while Yokogawa Electric Corporation occupies a specialist tier concentrated on high-integrity safety systems for hazardous hydrocarbon environments. Honeywell International Inc. and Emerson Electric Co. represent North American-headquartered competitors with established Asia-Pacific service architectures. Rockwell Automation and Schneider Electric SE anchor the industrial software and connected-device layer. Mitsubishi Electric Corporation and General Electric Company complete the competitive set with regional manufacturing presence and energy-sector heritage.
| Leading Market Players |
|---|
| ABB Ltd |
| Honeywell International Inc. |
| Schneider Electric SE |
| Rockwell Automation |
| Emerson Electric Co. |
| Yokogawa Electric Corporation |
| Siemens AG |
| Mitsubishi Electric Corporation |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between SIL 3 safety systems and standard control platforms manifests in both pricing premiums and supply chain configurations across the APAC oil and gas automation market. Foreign suppliers absorbing GB compliance costs for Chinese deployments face elongated procurement cycles that compress margin structures, while domestic certification laboratories command pricing power through accelerated vendor qualification pathways.
Pricing Analysis
The bundled-versus-unbundled service split now dominates pricing architecture across Australian LNG infrastructure and Chinese refinery retrofits. Asset operators unbundling after-sales contracts from initial system procurement expose OEM service divisions to margin compression while elevating third-party maintenance specialists. Price differentiation hinges on cybersecurity certification depth and SIL 3 engineering density, with foreign suppliers facing cost premiums for mainland Chinese localization. Pricing pressure stems from semiconductor supply concentration in Taiwan and South Korea elongating DCS lead times. Downstream refiners in Jiangsu and Zhejiang provinces exhibit highest price sensitivity due to dual carbon compliance burdens, while Australia's North West Shelf operators prioritize reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale refinery demand across Chinese state-owned enterprises, while specialized system integrators serve lean-staffed offshore platforms in Vietnam's Nam Con Son basin. Industrial semiconductor fabrication concentrates in Taiwan and South Korea, with legacy DCS components sourcing from Japanese and German manufacturing bases. Raw material dependencies span specialized industrial chips, hardened field cabling, and corrosion-resistant enclosure materials. Supply chain risk centers on single-source vulnerability for SIL 3-certified safety processors. Distribution runs through Singapore-based regional hubs that consolidate certification engineering and spare parts logistics for Southeast Asian offshore blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC oil and gas automation market functions as a geographic-arbitrage play where certification engineering costs in Singapore and Tokyo create margin expansion opportunities for vendors establishing localized technical centers in Vietnam and Indonesia.
For Market Incumbents: Anticipate margin compression from unbundled service contracts by deepening captive maintenance capabilities through certification investments in Vietnam's emerging offshore blocks. Consolidate position via backward integration into edge computing hardware production to offset semiconductor supply volatility. Prioritize GB cybersecurity pre-certification for Chinese refinery procurement cycles. For New Entrants and Emerging Players: Launch via cloud-native SCADA subscription models targeting Western Australian pipeline operators piloting operational-expenditure-based visibility platforms. Penetrate Vietnam's Cuu Long basin through partnerships with international operators expanding production sharing contracts. Target hydrogen blending infrastructure automation as a white-space application with limited incumbent specialization. For Investors and Strategic Acquirers: Consolidation pressure builds where certified SIL 3 engineering scarcity constrains deployment velocity across Indonesian and Vietnamese offshore assets. Long-term viability favors vendors with hybrid DCS-IoT architectures bridging brownfield legacy systems. Monitor China's MEE emissions enforcement intensity as the inflection signal for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Certification Investment | GB standards compliance in Shandong and Guangdong compresses foreign supplier procurement cycles. |
| Cloud-Native SCADA Development | Subscription platforms displace capital-intensive on-premise systems across Queensland pipeline networks. |
| SIL 3 Engineering Hub Expansion | Singapore and Tokyo certification concentration creates bottleneck for Southeast Asian offshore deployment. |
| Digital Twin Integration | Pilbara LNG operators deploy virtual replicas to compress cryogenic train commissioning timelines. |
| Hydrogen Infrastructure Automation | Ammonia transport networks require new flow control architectures with limited incumbent specialization. |
Study Parameters
Bottom-up refinery and offshore platform modeling reconciled against top-down automation supplier shipment tracking forms the analytical core of this study. Primary interviews with control system engineers, offshore safety auditors, refinery procurement directors, and third-party maintenance contractors were validated against secondary sources including MEE emissions filings, Australian offshore petroleum safety regulator audit records, METI digital transformation white papers, and customs data for industrial control equipment imports. Triangulation between demand-side capital expenditure patterns and supply-side order book visibility ensures segmentation integrity.
Historical trendline analysis of DCS and SIS replacement cycles across the North West Shelf and Chinese petrochemical corridors established baseline growth parameters. The analytical framework segments by product type, end-user category, technology layer, and application focus across the projection horizon. CAGRs were derived from regression analysis of procurement cycle compression factors and regulatory enforcement intensity. Industry-specific forecast inputs include MEE emissions benchmark escalation schedules and Australia's functional safety audit mandate implementation velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption scenarios affecting Taiwan semiconductor supply. Periodic stress-testing of base assumptions is recommended given regulatory divergence between Chinese GB standards, Australian offshore safety mandates, and Japanese METI digital frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Wireline Services Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Well Abandonment Services Market