
 Oil and Gas MIC Testing Market | 2026-2036
Oil and Gas MIC Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas MIC Testing Market Insights
Aftermarket service revenue from recurring MIC monitoring contracts is rewriting how testing providers capture lifetime value from infrastructure operators. Baker Hughes leverages its integrated oilfield services footprint to bundle corrosion diagnostics with production chemistry programs. SGS SA anchors its position through accredited laboratory networks that sustain long-term client relationships across upstream and midstream assets.
Oil and Gas MIC Testing encompasses analytical methods that detect, quantify, and characterize microbial populations—particularly sulfate-reducing bacteria and acid-producing bacteria—that accelerate metal degradation in hydrocarbon production, transport, and storage systems. These tests typically employ electrochemical impedance spectroscopy, culture-based enumeration, and molecular DNA analysis to identify corrosion risk thresholds before wall loss compromises structural integrity. Pipeline Inspection services currently dominate the service type segment as operators extend asset life across aging midstream networks. Electrochemical Testing technology leads the instrumentation category, though Sensors deployment is accelerating fastest where real-time monitoring replaces periodic manual sampling. Consulting services occupy the highest margin tier, particularly for root-cause failure investigations linking microbiological activity to specific operational upsets.
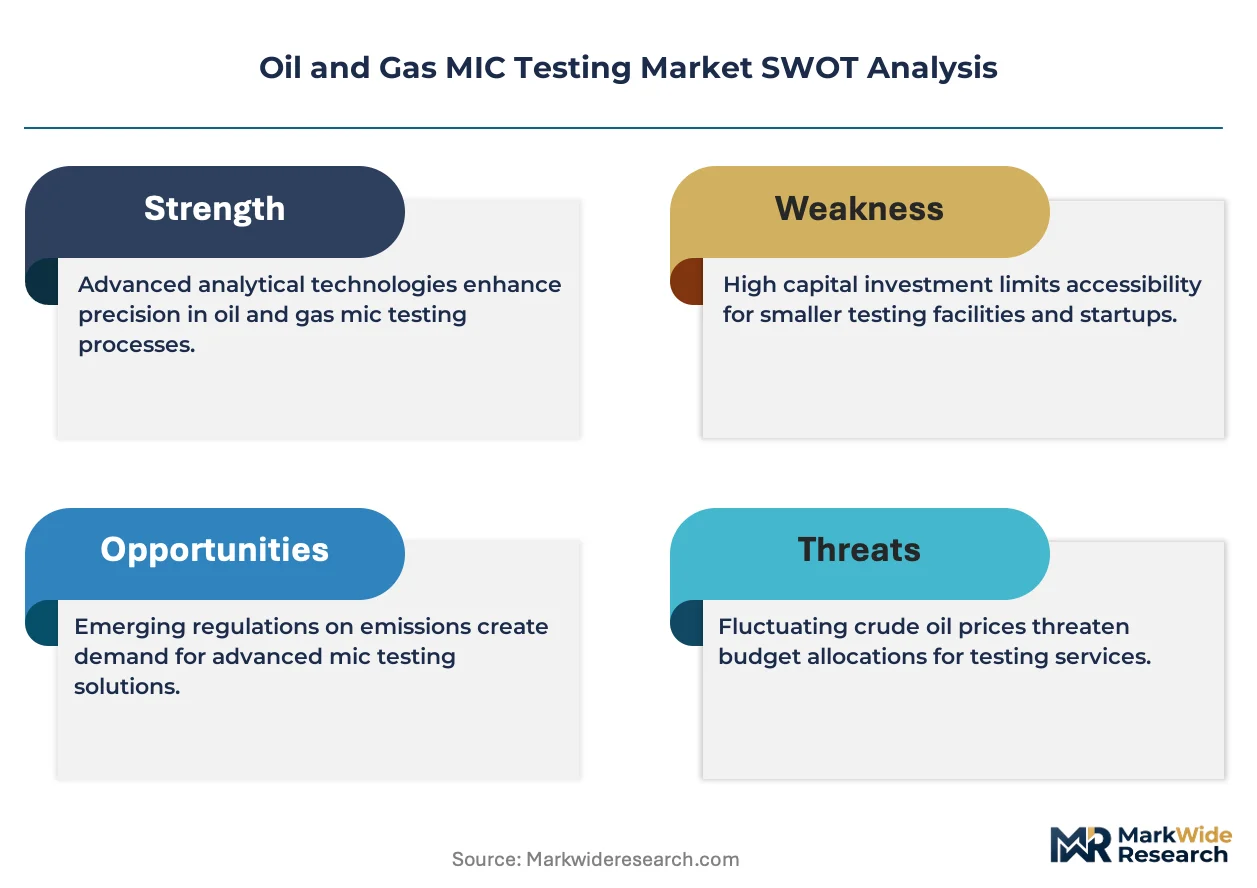
NACE International standards, API recommended practices, and EPA wastewater discharge requirements collectively shape MIC testing protocols and reporting obligations for US operators. The EPA regulates biocide discharge limits that directly constrain corrosion prevention strategies, while NACE SP0775 mandates standardized test methods for qualifying protective coatings against microbial attack. Stakeholders must weigh capital allocation between predictive sensor deployment and reactive laboratory analysis as regulatory scrutiny intensifies on methane leakage and asset integrity disclosures.
Market Dynamics
Offshore production operators are accelerating microbiologically influenced corrosion monitoring programs as aging subsea infrastructure faces intensified regulatory scrutiny under tightening NACE SP0775 and API RP 38 protocols.
Growth Catalysts
- NACE SP0775 Standardization:The updated standard mandates standardized test methods for qualifying protective coatings against microbial attack, forcing operators to expand testing frequency across Gulf Coast refining assets.
- EPA Wastewater Discharge Rules:Biocide discharge limits constrain corrosion prevention strategies, driving demand for precise microbial population quantification to optimize treatment dosing.
- Electrochemical Impedance Spectroscopy:This analytical method enables real-time corrosion risk detection, replacing periodic manual sampling with continuous monitoring in high-pressure pipeline systems.
Market Restraints
- Specialized Laboratory Infrastructure:Accredited molecular DNA analysis facilities concentrate in the US Gulf Coast and Western Europe, creating geographic access barriers for remote upstream operators.
- Culture-Based Enumeration Limitations:Traditional cultivation methods require extended incubation periods and fail to detect viable but non-culturable microbial populations, delaying corrosion risk assessment.
- Skilled Technician Scarcity:Interpretation of electrochemical impedance spectra and molecular diagnostics demands cross-trained microbiology-corrosion specialists, constraining service expansion.
Strategic Opportunities
- Sensor Network Deployment:Real-time monitoring systems are displacing laboratory-dependent workflows in North Sea offshore platforms, creating recurring hardware-software revenue streams.
- Root-Cause Failure Investigation Services:Consulting engagements linking microbiological activity to specific operational upsets command premium pricing in downstream petrochemical corridors.
- Integrated Production Chemistry Bundling:Corrosion diagnostics packaged with chemical treatment programs penetrate integrated oilfield service contracts, deepening client retention.
Industry Challenges
- Legacy System Integration:Electrochemical sensors must interface with decades-old SCADA infrastructure in midstream pipeline networks, requiring custom protocol adaptation and extended commissioning timelines.
- Accreditation Maintenance Burden:ISO 17025 laboratory certification and NACE auditor qualifications demand continuous proficiency testing expenditure, squeezing margin at smaller service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas MIC Testing Market |
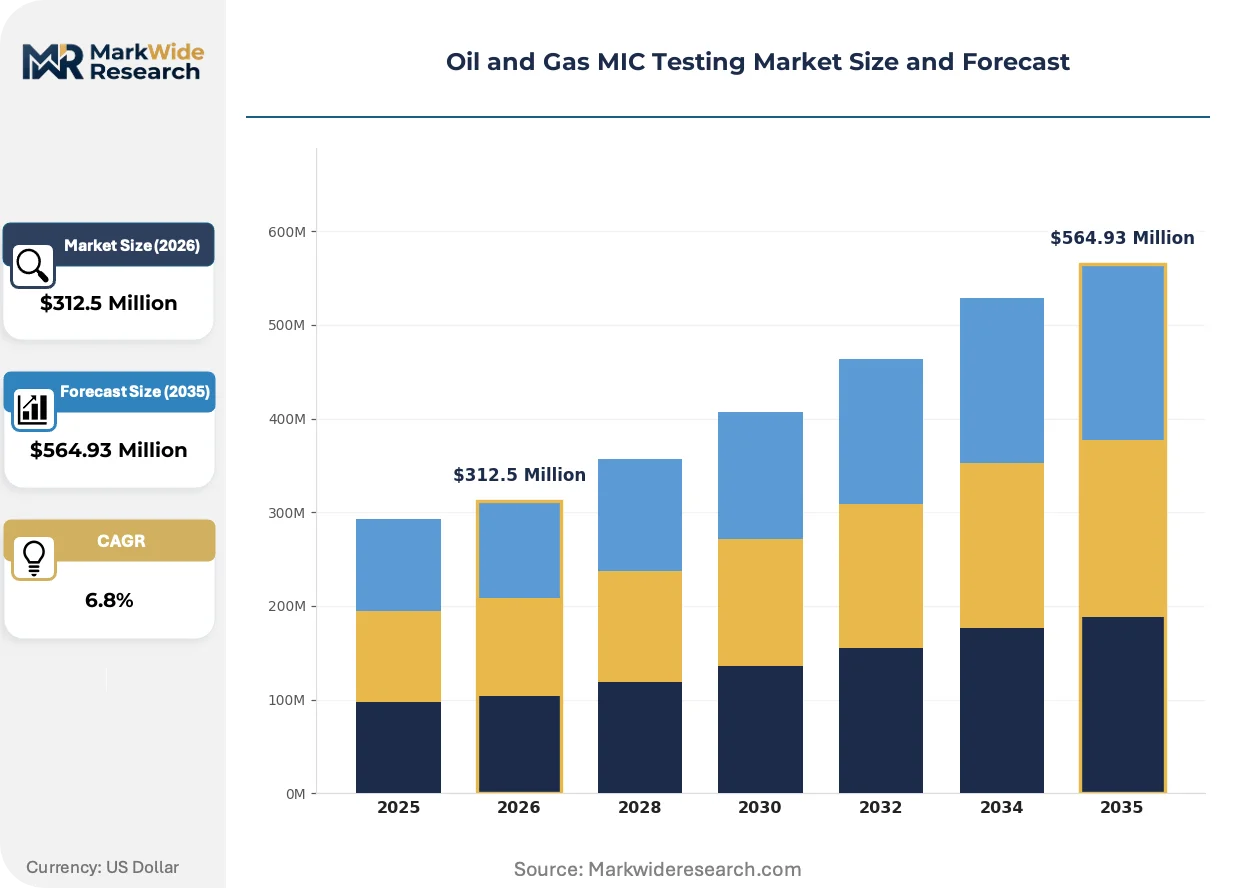
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
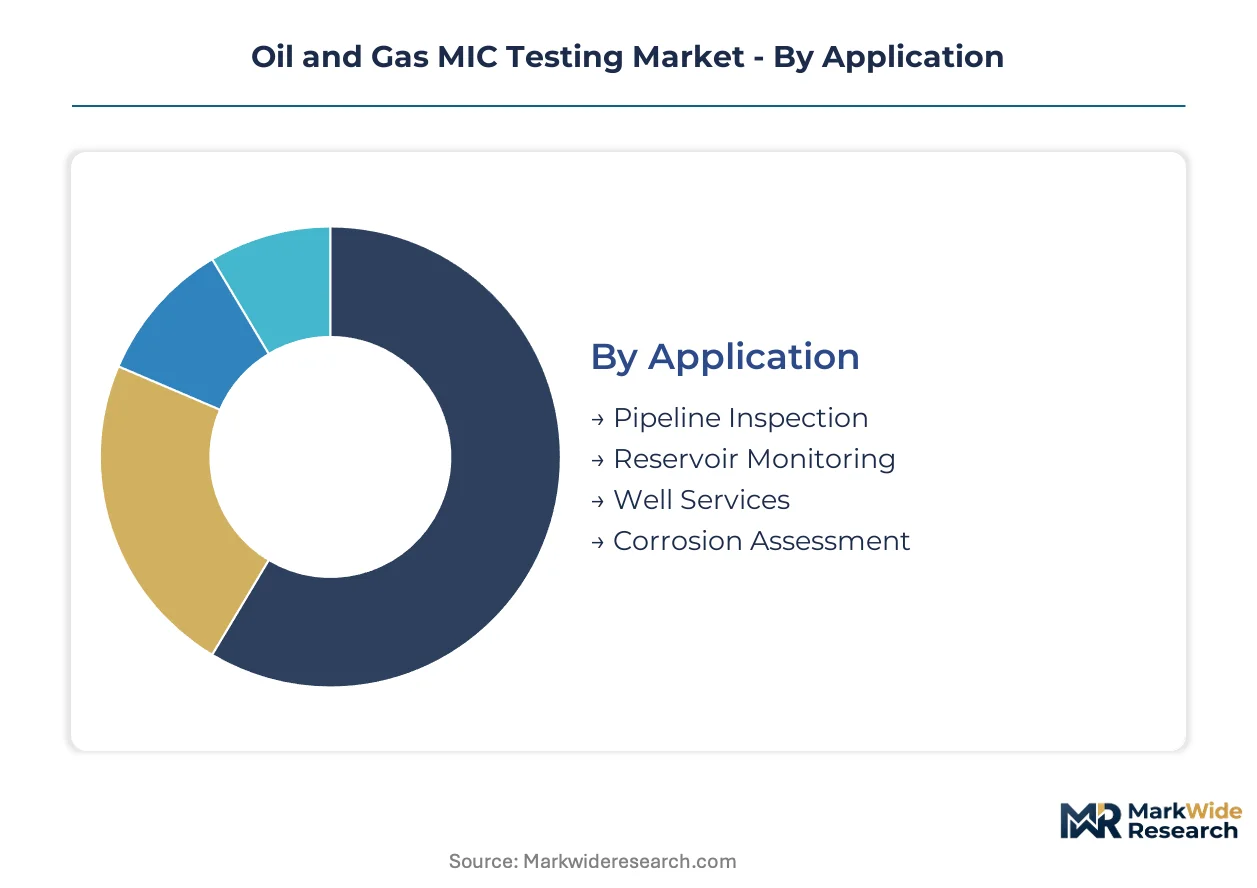
| Segmentation | Application: Pipeline Inspection, Reservoir Monitoring, Well Services, Corrosion Assessment Service Type: Consulting, Testing, Inspection, Maintenance Technology: Electrochemical Testing, Sensors, Laboratory Analysis, Field Testing End User: Exploration Firms, Production Companies, Service Providers, Government Agencies |
| Companies Covered | Baker Hughes, Schlumberger Limited, Halliburton Company, Intertek Group plc, SGS SA, DNV, LuminUltra, Mistras Group, Inc., Element Materials Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas MIC Testing Market Trends and Innovations
Digital sensor architectures and molecular diagnostic platforms are compressing detection timelines from weeks to hours, while regulatory disclosure requirements force asset integrity data into auditable digital formats.
Electrochemical sensor arrays with embedded microbiological detection capabilities are virtualizing traditional laboratory workflows, enabling continuous sulfate-reducing bacteria monitoring without sample transport delays. Offshore platform operators in the Gulf of Mexico are deploying these systems at scale, replacing monthly manual sampling with sub-hourly data streams. The technology is virtualizing the role of centralized testing laboratories, pushing analytical capability to the point of corrosion risk.
The EPA's intensified methane leakage disclosure rules and asset integrity reporting mandates are forcing operators to document corrosion prevention effectiveness in standardized digital formats. This regulatory pressure compels midstream pipeline companies to adopt NACE-compliant testing protocols that generate auditable microbial activity records. Downstream refineries face the steepest compliance burden, retrofitting legacy tank farms with automated sampling infrastructure to satisfy inspector scrutiny.
Service contract structures are fragmenting from bundled annual agreements toward unbundled, test-type-specific procurement. Pipeline operators now separately source electrochemical monitoring, molecular diagnostics, and consulting investigations, compressing vendor switching cycles and intensifying price competition. This unbundling is most pronounced in the US Gulf Coast petrochemical corridor, where integrated operators maintain multiple accredited laboratory relationships to ensure testing redundancy and competitive benchmarking.
Oil and Gas MIC Testing Market Segmentation
Segmentation in Oil and Gas MIC Testing reveals divergent margin profiles across service delivery models. Recurring monitoring contracts generate annuity-like revenue streams, while project-based consulting engagements capture premium pricing during failure investigations.
Application:
After-sales service intensity varies sharply by application, with pipeline networks demanding continuous sensor maintenance while well services rely on episodic intervention.
- Pipeline Inspection:Electrochemical impedance spectroscopy and inline inspection tools detect microbial corrosion along extended midstream networks. US Gulf Coast operators deploy these systems across aging infrastructure facing NACE SP0775 compliance deadlines.
- Reservoir Monitoring:Downhole microbial sampling identifies souring risks before sulfate-reducing bacteria proliferate in waterflood operations. North Sea platforms prioritize this application to mitigate hydrogen sulfide generation and associated asset degradation.
- Well Services:Workover operations integrate MIC testing to evaluate tubing integrity before recompletion.
- Corrosion Assessment:Root-cause investigations link microbiological activity to specific wall-loss events in storage tanks and processing equipment.
By volume, Pipeline Inspection leads. By growth pace, Reservoir Monitoring is ahead.
Service Type:
Cost tier separation distinguishes high-touch consulting from commoditized testing workflows.
- Consulting:Expert-led failure investigations and treatment optimization command premium pricing. These engagements require cross-trained microbiology-corrosion specialists capable of interpreting complex electrochemical spectra and molecular diagnostics.
- Testing:Standardized culture-based enumeration and DNA analysis form the volume base. Accredited laboratory networks concentrate in the US Gulf Coast and Western Europe, creating geographic access constraints for remote operators.
- Inspection:Field-deployed technicians execute visual and instrumented assessments of coating integrity and corrosion morphology.
- Maintenance:Recurring biocide treatment monitoring and sensor calibration sustain long-term client relationships.
Consulting captures the highest margins. Testing handles the greatest transaction volume.
Technology:
Technology maturity curves separate established laboratory methods from emerging real-time platforms.
- Electrochemical Testing:Impedance spectroscopy and polarization resistance measurements enable continuous corrosion rate monitoring without sample extraction. Gulf of Mexico offshore platforms deploy these systems to replace monthly manual sampling with sub-hourly data streams.
- Sensors:Embedded microbiological detection arrays virtualize traditional laboratory workflows, pushing analytical capability to the point of corrosion risk. Deployment accelerates fastest where SCADA integration challenges can be resolved.
- Laboratory Analysis:Culture-based enumeration and quantitative PCR remain the compliance reference standard for regulatory reporting.
- Field Testing:Portable kits deliver rapid screening at remote well sites and pipeline stations.
Laboratory Analysis retains the largest installed base. Sensors are expanding most quickly.
End User:
Procurement sophistication varies by end-user category, with integrated operators bundling services and independents sourcing à la carte.
- Exploration Firms:Early-stage screening for microbial souring risks informs field development planning and facility design specifications.
- Production Companies:Operating asset integrity programs drive recurring monitoring spend across upstream and midstream infrastructure.
- Service Providers:Oilfield service contractors embed MIC testing within integrated production chemistry and corrosion management offerings.
- Government Agencies:Regulatory bodies mandate standardized testing protocols through NACE and API standards enforcement.
Production Companies dominate current procurement. Service Providers are deepening their testing capabilities fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Gulf Coast operators prioritize real-time sensor deployment for offshore compliance, while North Sea platforms emphasize reservoir souring prevention, and Middle Eastern producers focus on bulk biocide optimization for desert pipeline networks.
United States
US Gulf Coast refining and petrochemical corridors drive the highest testing frequency globally as NACE SP0775 mandates expand. EPA wastewater discharge rules constrain biocide dosing strategies, forcing precise microbial quantification. Houston and Corpus Christi host the densest accredited laboratory networks, where operators retrofit aging tank farms with automated sampling infrastructure.
Norway
North Sea offshore platforms prioritize reservoir monitoring to preempt hydrogen sulfide generation in waterflood operations. Norwegian Petroleum Directorate regulations require documented microbial activity assessments before facility modifications. Stavanger and Bergen anchor specialized service provider clusters, where electrochemical sensor deployment displaces monthly manual sampling.
United Kingdom
UK North Sea decommissioning timelines accelerate corrosion assessment demand for aging subsea infrastructure. Health and Safety Executive mandates link microbial corrosion monitoring to asset integrity case submissions. Aberdeen concentrates consulting specialists capable of root-cause failure investigations tying microbiological activity to specific wall-loss events.
Saudi Arabia
Saudi Aramco's pipeline expansion across the Empty Quarter drives demand for bulk biocide treatment optimization in high-temperature, high-salinity conditions. Saudi Standards, Metrology and Quality Organization adoption of API RP 38 protocols standardizes test methods. Dhahran and Jubail host integrated oilfield service hubs bundling corrosion diagnostics with production chemistry programs.
Brazil
Pre-salt offshore development pushes reservoir souring risk assessment to the forefront of field planning. Brazilian National Agency of Petroleum, Natural Gas and Biofuels licensing requirements mandate microbial monitoring in high-pressure carbonate formations. Rio de Janeiro anchors service provider engineering centers adapting electrochemical impedance spectroscopy for deepwater conditions.
Oil and Gas MIC Testing Market Competitive Landscape
Capability concentration sits with integrated oilfield service conglomerates; scale advantage sits with diversified inspection and certification networks. The market structures around three tiers: full-service oilfield providers bundling corrosion diagnostics with chemical programs, accredited laboratory networks sustaining long-term client relationships, and specialized sensor technology developers pushing real-time monitoring boundaries. Dominant competitive moves include strategic partnerships between hardware developers and legacy service providers, plus geographic expansion of accredited testing facilities into underserved upstream basins.
Within the integrated service tier, Baker Hughes leverages its production chemistry footprint to embed corrosion diagnostics within broader asset integrity programs. SGS SA anchors the accredited laboratory network archetype through its Gulf Coast and Western European facilities. Schlumberger Limited occupies a position bridging reservoir characterization expertise with microbial souring risk assessment, exemplifying how upstream technology providers extend into corrosion monitoring adjacent services.
| Leading Market Players |
|---|
| Baker Hughes |
| Schlumberger Limited |
| Halliburton Company |
| Intertek Group plc |
| SGS SA |
| DNV |
| LuminUltra |
| Mistras Group, Inc. |
| Element Materials Technology |
| Others |
Pricing and Supply Chain Analysis
US Gulf Coast petrochemical corridor freight lanes connect Houston laboratory clusters to Corpus Christi refining complexes, where transport cost differentials of 15-20% separate accredited testing providers from unqualified competitors and compress margins for remote field deployments.
Pricing Analysis
Long-term offtake contracts dominate the Oil and Gas MIC Testing Market, with integrated operators locking in multi-year monitoring agreements that bundle electrochemical sensor deployment with recurring laboratory analysis. Price differentiation rests on ISO 17025 certification tier and after-sales service intensity, where NACE-accredited providers command 25-40% premiums over non-certified competitors. Cost compression in the testing tier intensifies as unbundled procurement spreads across the US Gulf Coast, squeezing smaller laboratories unable to sustain proficiency testing expenditure. Independent exploration firms exhibit highest price sensitivity, while major production companies prioritize compliance assurance over unit cost.
Supply Chain Analysis
Specialized electrochemical sensor substrates draw from Germany, Japan, and the United States, where precision manufacturing capabilities concentrate for impedance spectroscopy instrumentation. Molecular diagnostic reagents hinge on supply chains anchored in the United States and Western Europe, with quantitative PCR primers and DNA extraction kits subject to cold-chain logistics requirements. Single-source vulnerability permeates the accredited reference standard market, where NIST-traceable calibration materials flow through limited distribution channels. Distribution runs through integrated oilfield service contracts, direct laboratory relationships, and specialized corrosion consultancy networks serving downstream petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oil and Gas MIC Testing Market operates as a regulatory-entrenchment defensive moat, where NACE SP0775 and API RP 38 compliance requirements create switching costs that cement incumbent laboratory relationships across decades-long asset lifecycles.
For Market Incumbents: Insulate market position through backward integration into electrochemical sensor manufacturing, capturing hardware margins currently flowing to German and Japanese component suppliers. Expand ISO 17025 accreditation into underserved upstream basins before regulatory deadlines force operator migration to compliant providers. Threat substitution from real-time sensor virtualization demands preemptive software-telemetry investment to own the data layer. For New Entrants and Emerging Players: Establish a beachhead in reservoir monitoring services for pre-salt offshore developments, where Brazilian ANP licensing requirements create compliance-driven demand without entrenched incumbent relationships. Target independent shale operators in the Permian Basin with portable field testing kits that bypass centralized laboratory dependencies. Go-to-market angle: subscription-based sensor-as-a-service models that convert capital expenditure to operational expenditure for capital-constrained independents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors accredited laboratory networks with embedded regulatory relationships over pure-play sensor hardware developers. Long-term viability rests on EPA and NACE standard evolution sustaining compliance-driven demand rather than discretionary prevention spend. Acquisition target archetype: regional laboratories with dormant NACE accreditations awaiting capital activation. Signal to watch: API RP 38 revision timelines that would trigger mandatory retesting waves across installed infrastructure bases.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Network Expansion | ISO 17025 certification in Permian and Bakken basins captures regulatory-driven operator migration. |
| Sensor-Telemetry Integration | Embedded SCADA-compatible electrochemical arrays displace monthly manual sampling in Gulf of Mexico platforms. |
| Root-Cause Consulting Capability | Cross-trained microbiology-corrosion specialists command premium pricing for failure investigation engagements. |
| Production Chemistry Bundling | Corrosion diagnostics packaged with biocide treatment programs deepen integrated oilfield service retention. |
| Real-Time Monitoring Platform | Sub-hourly data streams from offshore sensor networks virtualize centralized laboratory workflows. |
Research Methodology
Initial hypotheses were tested against primary input from corrosion engineering directors, laboratory accreditation managers, offshore platform integrity officers, and petrochemical procurement leads and refined through secondary validation against NACE technical committee proceedings, EPA enforcement action databases, API standard revision dockets, and SEC 10-K disclosures from integrated service providers. Bottom-up testing volume estimates from accredited facility networks were triangulated against top-down infrastructure asset counts across Gulf Coast and North Sea production basins.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling across application type, service delivery model, technology platform, and end-user procurement sophistication. CAGRs were derived from installed base corrosion risk assessments, regulatory compliance deadline clustering, and sensor replacement cycle analysis. Industry-specific forecast inputs incorporated NACE SP0775 adoption curve assumptions and EPA methane disclosure rule implementation pacing.
Sensitivities concentrate around API standard revision timelines, EPA biocide discharge limit adjustments, and electrochemical sensor reliability improvements that could compress laboratory testing frequency. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and operator capital allocation priorities. Cross-checking against NACE membership growth trends and accredited laboratory expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Oilfield Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
Oilfield Services Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Asphaltene Inhibitors Market