
 Sidetracking Market | 2026-2036
Sidetracking Market Size, Share, and Industry Trends Forecast 2026-2036
Sidetracking Market Analysis
EPA methane performance standards for oil and gas operations is restructuring the capital deployment calculus for sidetracking projects across North American shale basins. Baker Hughes leverages its rotary steerable portfolio to reduce non-productive time during re-entry operations. Halliburton anchors its position through integrated wellbore construction services that bundle sidetracking with completions. Schlumberger dominates the measurement-while-drilling segment, where real-time telemetry cuts drilling uncertainty in complex geologies.
Sidetracking is the engineered deviation of an existing wellbore from its original path to access additional hydrocarbon zones, bypass damaged casing sections, or improve drainage patterns, typically employing whipstock assemblies, window milling, and directional bottom-hole assemblies rated for pressures exceeding 15,000 psi. The technology serves primary recovery enhancement, field redevelopment, and asset life extension in maturing petroleum provinces. Directional drilling technology leads the technology segment due to its ubiquity in whipstock-based sidetrack initiation, while rotary steerable systems capture the fastest expansion as operators demand continuous rotation without sliding interruptions. Onshore installation maintains the largest volume share given the installed base of aging vertical wells in Texas, Oklahoma, and Alberta, though offshore sidetracking commands premium pricing due to rig day-rate economics and subsea complexity.
API well integrity standards, BOP certification requirements from the Bureau of Safety and Environmental Enforcement, and state-level plugging obligations enforced by the Texas Railroad Commission collectively shape equipment specifications and operational protocols for sidetracking contractors. The EU F-Gas Regulation and REACH chemical restrictions additionally constrain drilling fluid formulations deployed in European North Sea re-entry campaigns. Stakeholders must monitor how regulatory stringency around methane containment and wellbore abandonment timelines alters the economic threshold for sidetrack versus greenfield drilling decisions.
Market Dynamics
Rotary steerable systems are compressing drilling uncertainty in whipstock-based sidetrack initiation, while EPA methane performance standards restructure capital deployment calculus across North American shale basins. The collision of precision directional technology with emissions containment mandates is forcing operators to recalculate re-entry economics against greenfield alternatives.
Growth Catalysts
- EPA methane performance standards:The EPA's oil and gas methane rules compel operators to invest in more precise directional drilling technologies that reduce fugitive emissions during re-entry operations.
- Permian Basin maturation:Operators in this Texas-New Mexico cluster accelerate sidetracking activity to access untapped pay zones from existing wellbores rather than drilling new vertical holes.
- Rotary steerable adoption:Continuous rotation without sliding interruptions cuts non-productive time and enables complex geologies previously uneconomical for re-entry.
Market Restraints
- High-pressure equipment costs:Directional bottom-hole assemblies rated for pressures exceeding 15,000 psi require specialized metallurgy and quality systems that inflate capital intensity.
- Rig day-rate economics:Offshore sidetracking commands premium pricing due to floating rig scarcity and subsea complexity that compresses project margins.
- Texas Railroad Commission plugging obligations:State-level abandonment timelines accelerate wellbore retirement decisions, shortening the window for economic re-entry.
Strategic Opportunities
- Alberta depleted fields:Canada's aging vertical well inventory creates optimal conditions for re-entry drilling economics with established infrastructure density.
- Integrated wellbore construction bundling:Service providers combine sidetracking with completions to capture full-cycle revenue streams and lock in operator relationships.
- EU F-Gas Regulation tailwinds:REACH chemical restrictions on drilling fluid formulations create demand for compliant re-entry technologies in European North Sea campaigns.
Industry Challenges
- Directional drilling specialist scarcity:The convergence of whipstock assembly expertise with real-time telemetry interpretation exceeds current training pipeline output.
- Bureau of Safety and Environmental Enforcement certification timelines:BOP certification requirements extend equipment qualification cycles and compress project scheduling flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sidetracking Market |
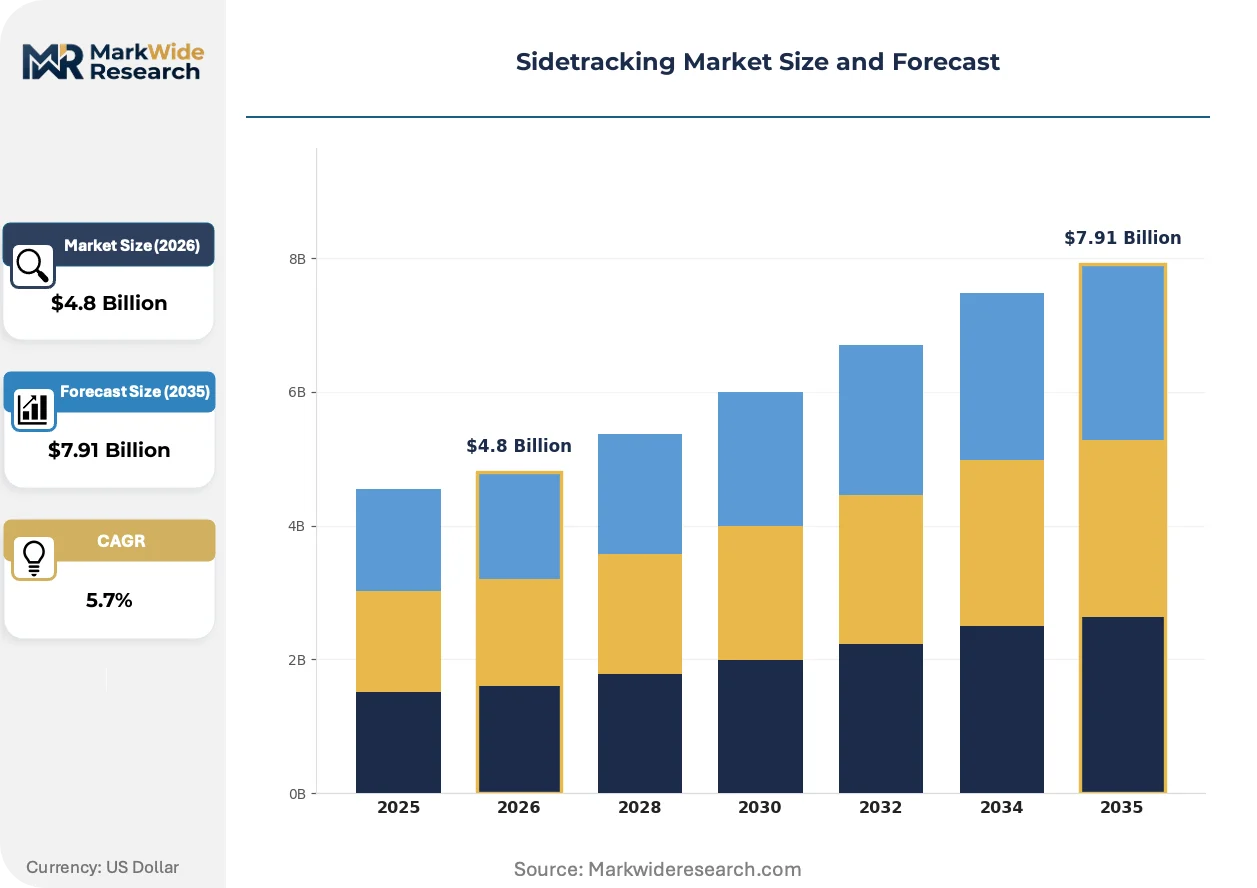
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Oil & Gas, Mining, Infrastructure, Construction Technology: Directional Drilling, Measurement While Drilling, Logging, Rotary Steerable End User: Drilling Companies, Service Providers, Engineering Firms, Contractors Installation: Onshore, Offshore, Remote Locations, Urban Areas |
| Companies Covered | National Oilwell Varco, Equinor, Baker Hughes, Eurasia Drilling, Nabors Industries, Schlumberger, Weatherford International, Yantai Jereh Oilfield Services Group, Halliburton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sidetracking Market Emerging Trajectories
Measurement-while-drilling telemetry is collapsing the information lag between downhole conditions and surface decision-making. Three convergent forces are restructuring how operators execute re-entry campaigns and justify capital allocation.
Rotary steerable systems are electrifying the directional drilling segment by eliminating sliding interruptions that historically degraded borehole quality. Operators in Oklahoma's STACK play deploy these systems for continuous rotation through abrasive Granite Wash formations. The technology is electrifying competitive positioning by compressing the economic threshold between sidetrack and greenfield drilling decisions.
The EPA's methane performance standards for oil and gas operations are forcing capital reallocation toward precision re-entry technologies that minimize formation disturbance. Operators now face portfolio-level decisions about which aging wellbores justify emissions-compliant rework versus abandonment. The Permian Basin bears the highest compliance density, with independent producers accelerating rotary steerable adoption to meet quarterly emissions reporting.
After-sales service unbundling is fragmenting traditional integrated contracts into discrete technical modules. Operators in the Gulf Coast corridor now procure whipstock window milling, directional assembly supply, and real-time telemetry as separate line items rather than bundled packages. Texas independents drive this pattern most aggressively, using unbundled procurement to pit specialized contractors against integrated service providers on individual technical scopes.
Sidetracking Market Segmentation
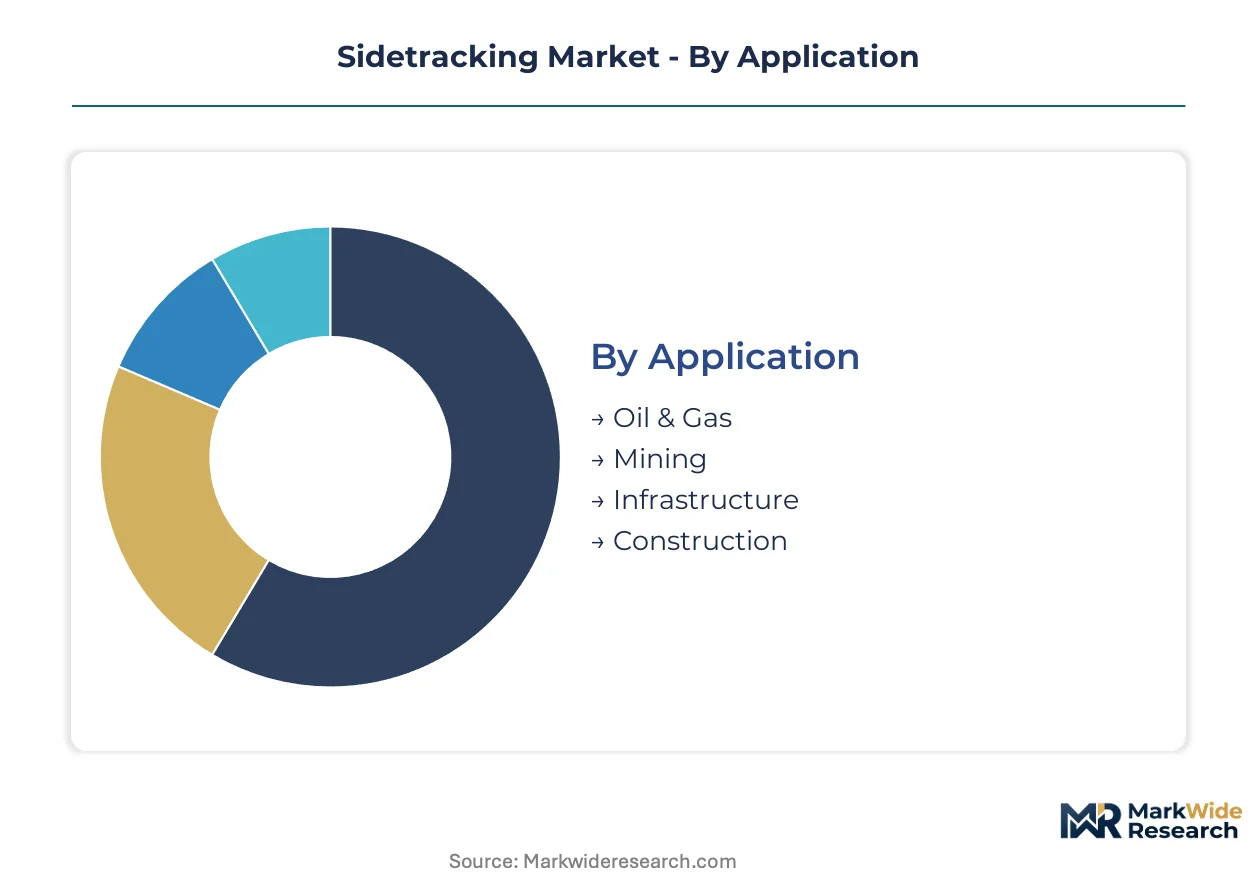
Sidetracking market segmentation reveals distinct procurement patterns across application verticals and technology tiers. Operators select technology bundles based on wellbore complexity, regulatory environment, and infrastructure density rather than uniform specifications.
Application:
Supply concentration in oilfield services creates asymmetric pricing power across application segments, with hydrocarbon recovery commanding premium equipment allocation.
- Oil & Gas:Primary pay zone access and casing bypass operations dominate equipment utilization. Permian Basin operators deploy whipstock assemblies for multilateral completions in stacked shale formations where surface footprint constraints limit greenfield drilling.
- Mining:Geotechnical borehole redirection for ore body delineation and ventilation shaft development. Australian hard-rock operations drive demand for high-torque directional assemblies capable of penetrating banded iron formations.
- Infrastructure:Utility tunneling and subsurface crossing applications require precision steering through mixed-face geology. Urban corridor projects in the United States Gulf Coast corridor specify closed-loop telemetry to minimize surface disturbance.
- Construction:Foundation remediation and anchoring systems for high-rise structures. Micro-sidetracking rigs penetrate karst limestone formations in Florida and Texas urban developments.
Oil & Gas absorbs the bulk of installed capacity; Mining is expanding most quickly.
Technology:
Cost tier stratification separates commodity whipstock services from integrated rotary steerable platforms, with mid-market Measurement While Drilling systems capturing volume share.
- Directional Drilling:Whipstock-based deviation and motor-assisted steering through conventional motor assemblies. Mature basins in Oklahoma and Alberta specify these systems for straightforward re-entry economics where trajectory complexity remains moderate.
- Rotary Steerable:Continuous rotation without sliding interruptions enables complex 3D wellbore geometries. North Sea operators and Permian independents adopt these systems to compress drilling uncertainty in abrasive formations.
- Measurement While Drilling:Real-time inclination and azimuth telemetry transmitted via mud pulse or electromagnetic carriers. Gulf Coast corridor operators unbundle this capability from integrated contracts to optimize procurement flexibility.
- Logging:Formation evaluation during sidetrack execution to confirm pay zone intersection. Wireline-conveyed and logging-while-drilling variants support geosteering decisions in depleted Texas conventional fields.
Directional Drilling retains the largest installed base; Rotary Steerable is climbing the fastest.
End User:
Customer type determines contract structure, with integrated operators favoring full-cycle bundles and independents pursuing unbundled technical modules.
- Drilling Companies:Asset owners contracting rig time and directional services as discrete line items. Texas independents increasingly self-manage whipstock procurement to bypass integrated service markups.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes anchor the tiered supply structure with bundled wellbore construction offerings. These firms capture margin through integrated directional drilling and completions sequencing.
- Engineering Firms:Technical design and project management for complex re-entry campaigns. European North Sea specialists specify REACH-compliant drilling fluid systems and F-Gas Regulation-aligned emissions controls.
- Contractors:Third-party execution of window milling and directional assembly deployment. Alberta-based contractors leverage established infrastructure density to undercut integrated provider pricing in depleted field redevelopment.
Service Providers command the deepest technical relationships; Drilling Companies are gaining procurement sophistication fastest.
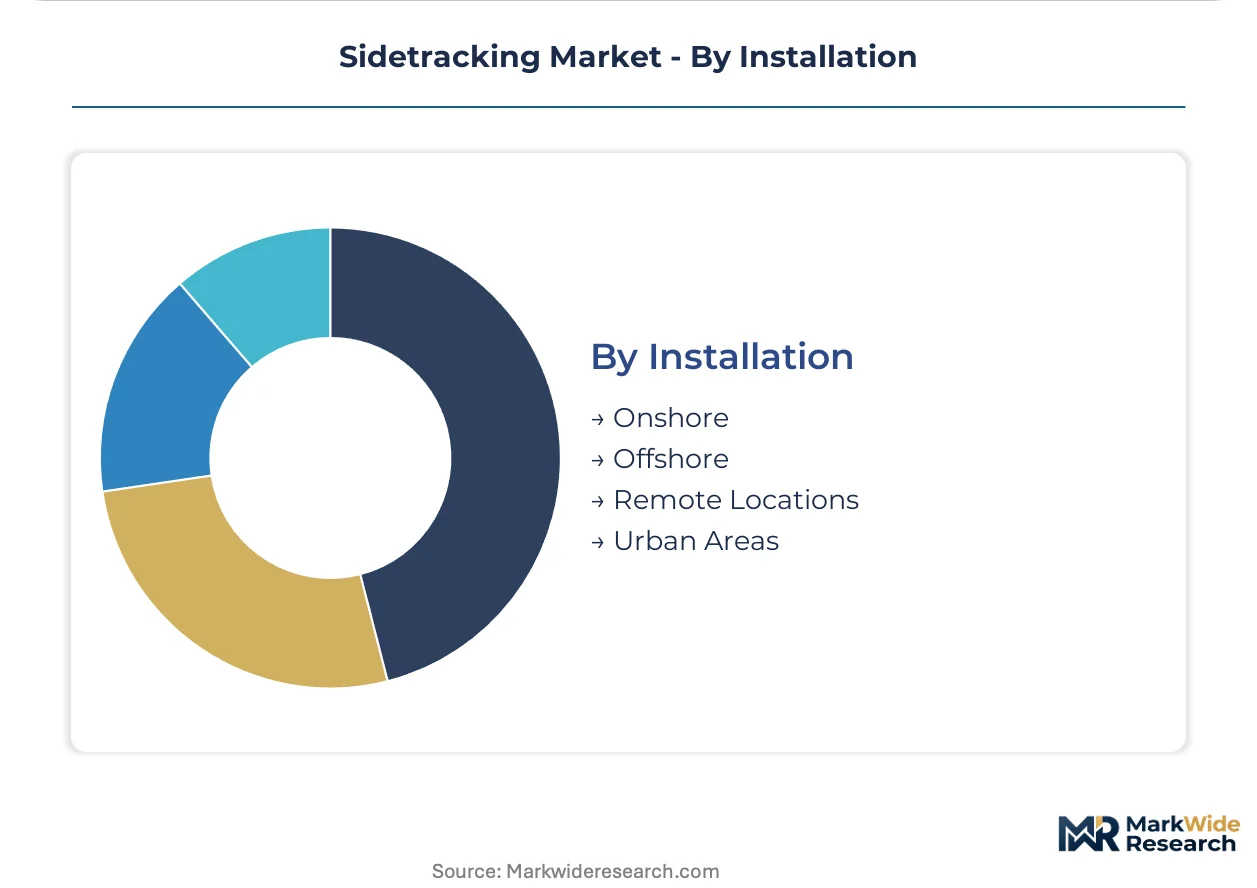
Installation:
Volume concentration in onshore re-entry masks margin compression, while offshore and remote installations sustain premium pricing through rig scarcity and logistics complexity.
- Onshore:Aging vertical well inventory in Texas, Oklahoma, and Alberta creates optimal conditions for economic re-entry. EPA methane performance standards accelerate rotary steerable adoption to minimize formation disturbance during pay zone access.
- Offshore:Subsea wellhead intervention and platform-based sidetracking command day-rate premiums. Gulf of Mexico operators face Bureau of Safety and Environmental Enforcement BOP certification timelines that compress project scheduling flexibility.
- Remote Locations:Arctic and desert environments require mobilization of self-contained rig packages. Limited infrastructure density inflates logistics costs and extends non-productive time during equipment maintenance.
- Urban Areas:Noise restrictions and surface footprint constraints dictate slim-hole directional techniques. Cities in the United States Gulf Coast corridor specify electric rig packages to comply with local emissions ordinances.
Onshore captures the greatest procedure volume; Offshore sustains the steepest expansion trajectory in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin tax incentives and Gulf Coast infrastructure density concentrate sidetracking investment in the United States, while Alberta's royalty framework and the North Sea's decommissioning timelines reshape regional deployment patterns across mature petroleum provinces.
United States
EPA methane performance standards and Permian Basin maturation accelerate rotary steerable adoption for re-entry drilling. The Texas Railroad Commission enforces plugging obligations that compress wellbore retirement windows. Houston anchors service provider headquarters density, while Midland-Odessa operators deploy whipstock assemblies for stacked shale pay zone access.
Canada
Alberta's aging vertical well inventory and depleted conventional fields create optimal re-entry economics with established pipeline infrastructure. The Alberta Energy Regulator oversees well integrity standards that shape equipment specifications. Calgary-based contractors leverage infrastructure density to undercut integrated provider pricing in Lloydminster and Medicine Hat redevelopment campaigns.
Norway
North Sea decommissioning timelines and subsea complexity sustain premium pricing for offshore sidetracking interventions. The Norwegian Petroleum Directorate regulates wellbore abandonment protocols that influence re-entry versus plug decisions. Stavanger clusters engineering expertise for complex platform-based sidetrack execution in mature Ekofisk and Statfjord fields.
China
Sinopec and PetroChina accelerate sidetracking in Shengli and Daqing mature basins to extend field life without greenfield surface footprint. The Ministry of Ecology and Environment enforces methane containment standards that favor precision directional technologies. Bohai Bay offshore platforms command specialized rotary steerable deployment for subsea wellhead intervention.
Saudi Arabia
Saudi Aramco's maximum sustainable capacity mandates drive re-entry drilling in Ghawar and Safaniya mature fields to sustain plateau production. The Ministry of Energy oversees technical standards for high-pressure high-temperature sidetrack operations. Dhahran anchors Schlumberger and Halliburton regional technical centers serving Khurais redevelopment campaigns.
Sidetracking Market Vendor Landscape
United States service conglomerates anchor the integrated tier; European engineering specialists and Chinese equipment fabricators hold differentiated positions in regional markets. The vendor base stratifies across full-cycle bundlers, technology component suppliers, and execution-focused contractors. Three archetypes dominate: integrated wellbore construction providers, directional drilling technology specialists, and regional execution contractors. Competitive moves center on integrated contract capture and rotary steerable platform differentiation.
Among Houston-based integrated providers, Schlumberger, Halliburton, and Baker Hughes exemplify the full-cycle bundling archetype. These entities occupy positions where directional drilling, measurement-while-drilling telemetry, and completions sequencing merge into single-source procurement relationships. Yantai Jereh Oilfield Services Group represents the China-based equipment and services tier, while Weatherford International and National Oilwell Varco sit within the technology-component supplier segment focused on whipstock assemblies and bottom-hole assembly metallurgy.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Equinor |
| Baker Hughes |
| Eurasia Drilling |
| Nabors Industries |
| Schlumberger |
| Weatherford International |
| Yantai Jereh Oilfield Services Group |
| Halliburton |
| Others |
Supply Flow & Price Mechanics
Operator unbundling of integrated service contracts into discrete technical modules is forcing equipment suppliers to reconfigure fulfillment networks and compress pricing across whipstock assemblies, directional bottom-hole assemblies, and real-time telemetry systems. This procurement fragmentation concentrates price negotiation leverage with Texas independents and Gulf Coast corridor operators who pit specialized contractors against integrated providers.
Pricing Analysis
Short lead-time premiums for whipstock window milling and directional assembly deployment compress margins for spot procurement while contract-based long-term offtake agreements secure capacity allocation. Three-tier pricing structure across premium rotary steerable platforms, standard motor-assisted steering systems, and economy whipstock services reflects API certification grades and after-sales service bundling. Cost compression in the economy tier intensifies because Alberta-based contractors leverage infrastructure density to undercut integrated provider pricing. Texas independents exhibit the highest price sensitivity, while North Sea offshore operators demonstrate the least due to rig day-rate economics dominating total project cost.
Supply Chain Analysis
Freight costs for high-pressure metallurgy components and specialized directional drilling equipment from Houston, Stavanger, and Dhahran manufacturing clusters inflate landed costs for remote Arctic and desert deployments. Raw material sourcing draws from German precision machining for whipstock assemblies, Japanese high-strength steel for bottom-hole assembly housings, and Chinese electronics for mud-pulse telemetry carriers. Single-source vulnerability concentrates in rotary steerable system controllers manufactured by a limited supplier base. Distribution runs through Schlumberger, Halliburton, and Baker Hughes integrated service networks, with regional execution contractors capturing spot demand in Alberta and Oklahoma.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sidetracking market represents a consolidation play as EPA methane performance standards and rotary steerable technology barriers force capital-constrained whipstock specialists toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from unbundled procurement patterns by deepening captive supply of measurement-while-drilling telemetry modules and securing exclusive channel control through integrated wellbore construction bundling. Invest in backward integration into high-pressure metallurgy manufacturing to defend against emerging Chinese equipment fabricators. Prioritize certification investment for Bureau of Safety and Environmental Enforcement BOP compliance to extend project scheduling flexibility. For New Entrants and Emerging Players: Begin with Alberta depleted field redevelopment campaigns where established infrastructure density and Calgary-based contractor relationships create penetrable white space. Target urban Gulf Coast corridor micro-sidetracking applications where electric rig packages and noise restriction compliance differentiate against legacy diesel fleets. Pursue go-to-market partnerships with engineering firms specifying REACH-compliant drilling fluid systems for European North Sea re-entry campaigns. For Investors and Strategic Acquirers: The window for entry favors directional drilling technology specialists with proprietary rotary steerable platforms and established API well integrity certification. Long-term viability hinges on 5-10 year field life extension demand in Permian Basin and Shengli Basin mature provinces. Monitor Texas Railroad Commission plugging obligation enforcement timelines as the inflection indicator for re-entry versus abandonment decision thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Rotary Steerable Platform Development | Schlumberger and Baker Hughes capture premium pricing through continuous rotation technology eliminating sliding interruptions. |
| Integrated Wellbore Construction Bundling | Halliburton locks in operator relationships by combining sidetracking with completions sequencing across Permian Basin campaigns. |
| Backward Integration into Metallurgy | National Oilwell Varco secures supply chain control over 15,000 psi-rated directional bottom-hole assembly components. |
| REACH-Compliant Fluid System Certification | European engineering specialists capture North Sea re-entry demand constrained by EU F-Gas Regulation chemical restrictions. |
| Urban Electric Rig Deployment | Gulf Coast corridor contractors comply with local emissions ordinances through slim-hole directional techniques in footprint-constrained environments. |
Methodological Framework
Independent corroboration across drilling company procurement directors, directional drilling engineers, regulatory affairs specialists at the EPA and Bureau of Safety and Environmental Enforcement, and aftermarket service managers underwrites the qualitative findings. Primary interviews with whipstock assembly technicians, rotary steerable system operators, and well integrity inspectors combined with secondary validation from API well integrity standards documentation, Texas Railroad Commission plugging obligation enforcement records, Alberta Energy Regulator field redevelopment permits, and SEC 10-K filings from listed service providers established demand-side and supply-side baselines. Bottom-up procedure volume estimates triangulated against top-down capital expenditure allocations across North American shale basins.
Rate-of-change decomposition across the analysis window separates volume growth from price realization effects in the projection framework. Segmentation dimensions modeled include application vertical, technology tier, end-user archetype, and installation environment complexity. CAGRs were derived from fitted growth curves calibrated to operator re-entry drilling announcement patterns and rig utilization data. Industry-specific forecast inputs incorporate EPA methane performance standard compliance cost trajectories and Permian Basin wellbore inventory age distributions.
Underlying measurement precision varies by segment; onshore oil and gas re-entry procedures carry tighter precision than mining geotechnical borehole redirection due to established reporting infrastructure. Forecasts reflect assumptions about regulatory stringency persistence and rotary steerable adoption curves that could revise materially if the EPA relaxes methane containment mandates or if high-pressure equipment costs accelerate faster than productivity gains. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Well Cementing Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Hydrocracking Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Drill Collar Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
GCC and North Africa Coiled Tubing Market