
 United States Fabric Shavers Market | 2026-2036
United States Fabric Shavers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Fabric Shavers Market Insights
Professional dry cleaning and tailoring services are repositioning the United States fabric shavers market toward higher-duty equipment specifications. Conair LLC leverages its established retail distribution network to sustain household segment dominance across mass-market channels. Philips Norelco anchors the rechargeable electric shaver category with advanced blade engineering that extends product lifecycles. Beautural specializes in compact travel-format devices that occupy the growing portable-care niche among urban consumers.
United States fabric shavers are electromechanical or hand-operated devices employing rotary or linear blade mechanisms to remove pills, lint, and surface fiber agglomeration from woven and knitted textiles, typically operating at speeds between 3,000 and 10,000 RPM for electric variants. Their primary commercial purpose spans garment restoration, upholstery maintenance, and pre-manufacturing textile finishing where surface integrity determines aesthetic grade. Electric fabric shavers lead product type revenue due to sustained replacement demand and motor durability expectations, while rechargeable variants represent the fastest-growing technology configuration as lithium-ion platforms displace disposable battery dependency. Cordless technology commands premium positioning among professional tailors and dry cleaners who prioritize mobility across workstations.
The Consumer Product Safety Commission governs electrical safety and blade enclosure standards for household appliances, while California's Department of Toxic Substances Control oversees battery disposal protocols that manufacturers must integrate into end-of-life product design. UL certification requirements for small motor appliances create compliance thresholds that shape competitive entry barriers and channel access. Stakeholders must monitor evolving state-level right-to-repair legislation that could mandate blade and motor component availability, fundamentally altering aftermarket revenue structures and manufacturer service models.
Market Dynamics
Professional garment care services are consolidating purchasing power around cordless lithium-ion platforms, compressing replacement cycles and elevating motor durability specifications above household-grade thresholds.
Growth Catalysts
- CPSC Electrical Safety Standards:UL certification mandates for small motor appliances create compliance barriers that filter out low-quality imports, protecting established manufacturers with testing infrastructure.
- Dry Cleaning Service Expansion:Metro-area garment care clusters in California and New York generate concentrated demand for commercial-grade cordless units with extended battery runtime.
- Lithium-Ion Battery Chemistry:Energy density improvements enable 90-minute continuous operation, eliminating workstation tethering for professional tailors.
Market Restraints
- Neodymium Magnet Supply:High-performance motor magnets concentrate in Chinese processing facilities, exposing manufacturers to export restriction volatility and price spikes.
- Blade Steel Import Dependence:Precision-hardened rotary blades rely on Japanese and German specialty steel mills, creating single-source vulnerability for domestic assemblers.
- Right-to-Repair Legislative Friction:California and New York state bills mandating component availability threaten proprietary blade attachment systems and authorized service revenue streams.
Strategic Opportunities
- Texas and Florida Metro Corridors:Underserved garment care markets in Houston, Dallas, Miami, and Tampa present expansion targets with lower competitive density than coastal hubs.
- Subscription Blade Replacement Programs:Direct-to-professional recurring revenue models bypass retail margin compression while locking in customer lifetime value.
- DTSC Battery Takeback Integration:California's extended producer responsibility framework rewards manufacturers with closed-loop recycling infrastructure through preferential retailer placement.
Industry Challenges
- Precision Machining Labor Shortage:Blade sharpening and motor assembly require specialized technicians that vocational programs have not scaled to meet.
- Multi-State Compliance Fragmentation:Divergent battery disposal rules across California, New York, and Illinois force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Fabric Shavers Market |
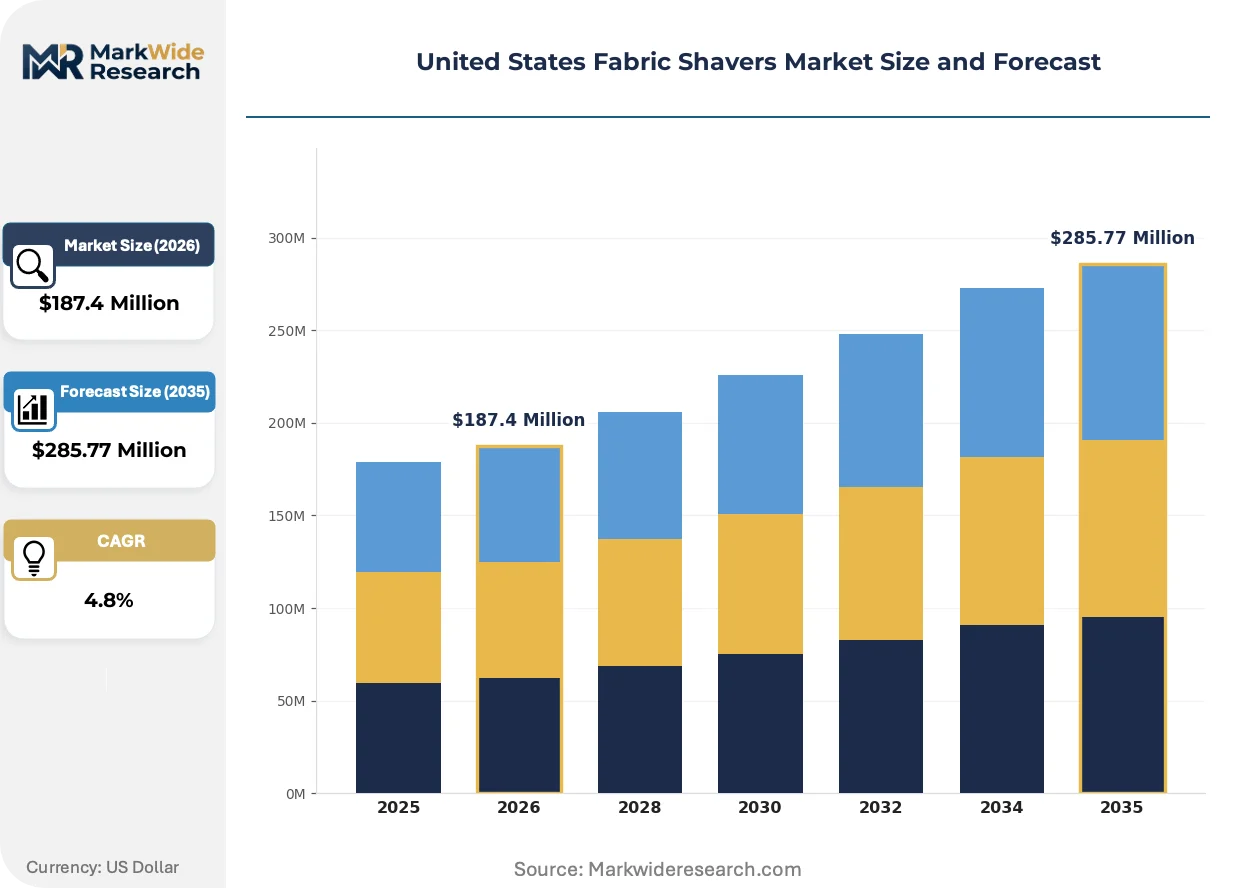
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Fabric Shavers, Manual Fabric Shavers, Rechargeable Fabric Shavers, Battery-Operated Fabric Shavers Application: Home Use, Professional Use, Commercial Use, Travel Use Technology: Corded Technology, Cordless Technology, Advanced Blade Technology, Self-Cleaning Technology End User: Retail Consumers, Tailors, Textile Manufacturers, Dry Cleaners |
| Companies Covered | Conair LLC, Philips Norelco, Beautural, Gleener, Remington Products Company, Steamery, Evercare, NORI, Falconeri, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Fabric Shavers Market Trends and Innovations
Power delivery architectures and professional mobility requirements are reshaping product development priorities away from corded household convenience toward untethered commercial endurance.
Brushless DC motor platforms are decentralizing maintenance workflows across dry cleaning floors. These electronically commutated systems eliminate carbon brush wear, extending service intervals from six months to three years. Professional operators in Manhattan and Los Angeles garment districts are adopting these units rapidly, compressing the installed base replacement cycle and shifting vendor revenue toward premium upfront hardware rather than consumable parts.
California's Department of Toxic Substances Control has tightened lithium-ion battery end-of-life protocols, mandating manufacturer-funded collection infrastructure. This regulatory pressure forces product design teams to integrate disassembly-friendly battery housings and standardized cell formats. Professional-grade shaver lines face the steepest compliance costs, as their higher-capacity battery packs trigger more stringent reporting thresholds than household units.
Garment care services are consolidating vendor relationships around authorized service networks that bundle equipment, maintenance, and blade resupply. This procurement concentration displaces fragmented retail purchasing and shifts negotiation leverage toward volume buyers with multi-location operations. The trend is most visible in Chicago and Boston, where regional dry cleaning chains now specify sole-source agreements with performance-based uptime guarantees.
United States Fabric Shavers Market Segmentation
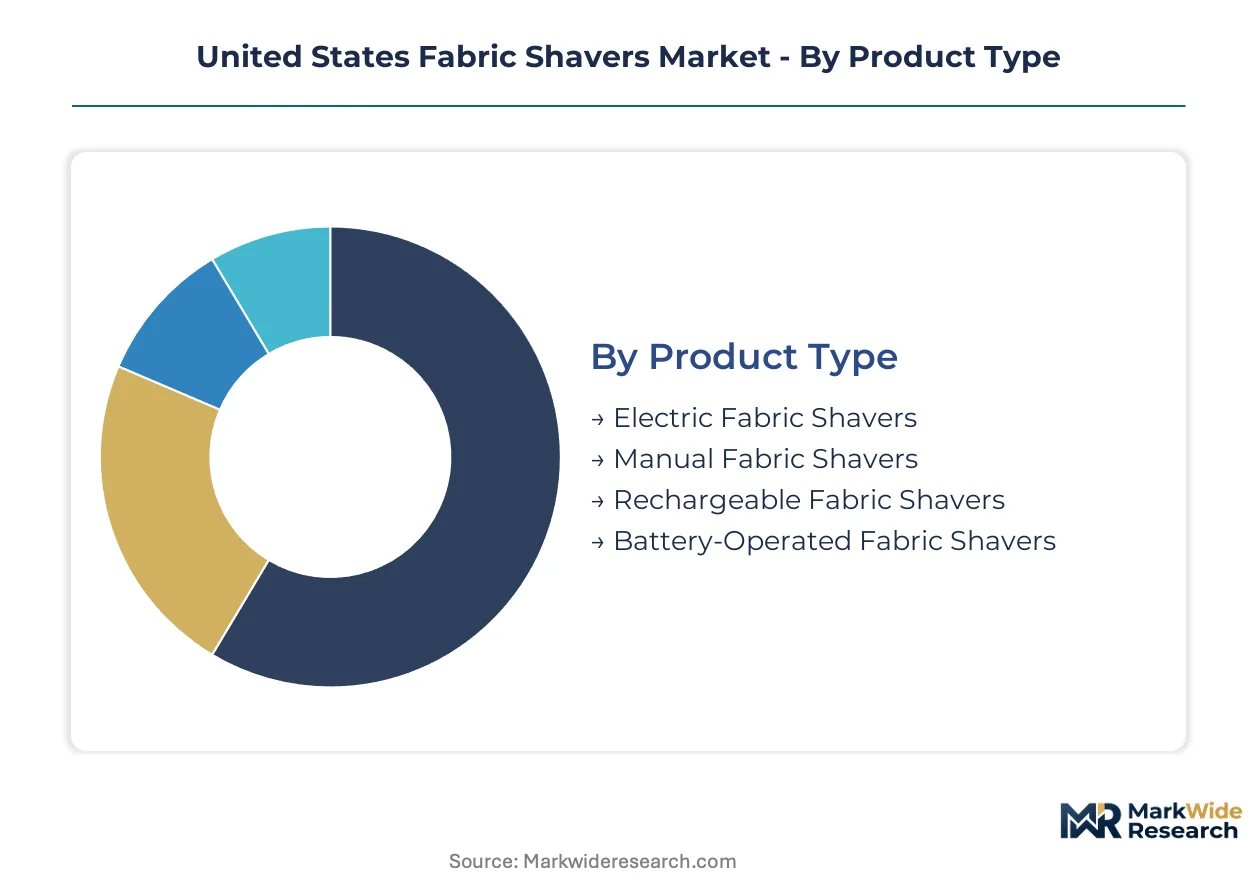
Segmentation in the United States fabric shavers market reveals divergent equipment specifications between household convenience and commercial endurance requirements. Professional operators demand cordless platforms with extended battery runtime, while retail consumers prioritize compact form factors and price accessibility.
Product Type:
Standardization dominates mass-market electric units, while rechargeable and battery-operated variants offer customization through modular battery configurations and blade interchangeability.
- Electric Fabric Shavers:Mains-powered units with AC motors deliver sustained 3,000-10,000 RPM operation for heavy-duty garment restoration. Dry cleaning chains in Manhattan and Los Angeles specify these for fixed workstation deployment where power access is guaranteed.
- Rechargeable Fabric Shavers:Lithium-ion platforms enabling 90-minute untethered operation are displacing corded alternatives in professional tailoring workflows. Chicago garment districts report rapid adoption as brushless DC motors extend service intervals from six months to three years.
- Manual Fabric Shavers:Hand-operated precision tools serve occasional home users and travel applications where electrical access is unreliable.
- Battery-Operated Fabric Shavers:Disposable battery configurations persist in price-sensitive retail channels despite environmental compliance pressures from California's Department of Toxic Substances Control.
Leading the category by volume: Electric Fabric Shavers. Growing fastest: Rechargeable Fabric Shavers.
Application:
Volume concentration follows metropolitan garment care density, with professional and commercial use commanding premium pricing against dispersed household demand.
- Home Use:Occasional-use devices with simplified blade mechanisms and reduced motor specifications. California and New York metro consumers drive replacement demand through retail mass-market channels.
- Professional Use:Tailors and alteration specialists require cordless lithium-ion platforms with rapid blade replacement systems. Boston and Chicago regional chains now specify sole-source vendor agreements with uptime guarantees.
- Commercial Use:High-throughput dry cleaning operations demand brushless DC motor durability and authorized service network coverage. Houston and Dallas markets show expansion potential with lower competitive density than coastal hubs.
- Travel Use:Compact rechargeable units with universal voltage compatibility serve mobile professionals and urban consumers with limited storage space.
Professional Use commands the highest unit margins. Travel Use expands most quickly among urban demographic segments.
Technology:
Power delivery architectures separate premium cordless platforms from cost-optimized corded alternatives, with blade engineering creating additional differentiation tiers.
- Cordless Technology:Lithium-ion battery systems with electronic motor control enable workstation mobility across dry cleaning floors. California's extended producer responsibility mandates drive design integration of disassembly-friendly battery housings.
- Advanced Blade Technology:Precision-hardened rotary mechanisms using Japanese and German specialty steel deliver extended cutting integrity. Single-source supply vulnerability constrains domestic assembler flexibility.
- Corded Technology:AC motor platforms with continuous power supply serve fixed-location commercial installations where battery runtime is non-critical.
- Self-Cleaning Technology:Automated debris removal systems reduce maintenance labor for high-volume professional operators.
Cordless Technology leads professional procurement. Advanced Blade Technology carries the steepest supply chain risk exposure.
End User:
Customer type determines purchasing channel, service expectation, and equipment specification intensity across fragmented retail and concentrated commercial segments.
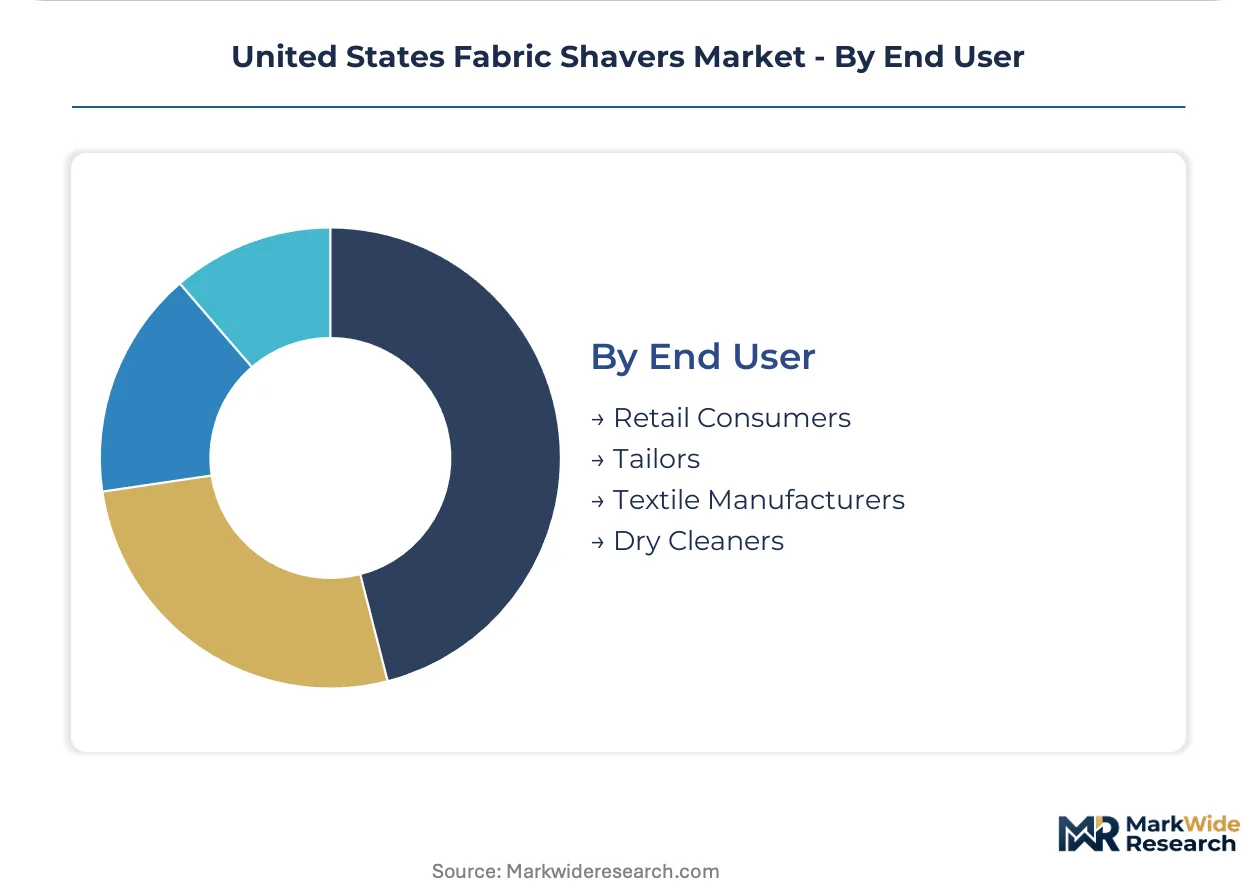
- Dry Cleaners:Multi-location garment care chains consolidate purchasing power around authorized service networks bundling equipment, maintenance, and blade resupply. Volume buyers negotiate performance-based uptime guarantees.
- Tailors:Independent alteration specialists prioritize cordless mobility and rapid blade replacement over capital cost minimization.
- Retail Consumers:Price-sensitive household purchasers drive mass-market volume through established retail distribution networks with limited service attachment.
- Textile Manufacturers:Pre-manufacturing finishing operations require industrial-grade surface integrity equipment with specialized textile-grade specifications.
Dry Cleaners dominate commercial procurement value. Tailors show fastest adoption of rechargeable cordless platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in California and New York's garment districts concentrate professional fabric shaver procurement through tax-advantaged commercial real estate development. These federal incentive structures accelerate equipment refresh cycles among dry cleaning clusters.
California
Los Angeles and San Francisco garment care corridors drive lithium-ion cordless adoption among alteration specialists. The state's Department of Toxic Substances Control enforces extended producer responsibility mandates for battery collection infrastructure. San Diego's emerging professional tailoring cluster reports rapid uptake of brushless DC motor platforms.
New York
Manhattan's dense dry cleaning network commands premium cordless equipment with 90-minute runtime specifications. Empire State Development's small business energy efficiency programs subsidize commercial-grade appliance upgrades. Brooklyn and Queens alteration districts consolidate vendor relationships around authorized service agreements.
Texas
Houston and Dallas metro areas present underserved expansion targets with lower competitive density than coastal hubs. The Texas Commission on Environmental Quality oversees industrial battery disposal protocols affecting commercial equipment lifecycle planning. Austin's growing apparel startup ecosystem generates nascent demand for textile finishing services.
Illinois
Chicago's regional dry cleaning chains now specify sole-source vendor agreements with performance-based uptime guarantees. The Illinois Environmental Protection Agency regulates small motor appliance recycling through landfill diversion mandates. The city's South Loop garment district concentrates independent tailor purchasing power.
Florida
Miami and Tampa garment care markets show expansion potential amid retiree-driven textile restoration demand. The Florida Department of Environmental Protection administers battery stewardship requirements for commercial equipment operators. Orlando's hospitality sector drives uniform maintenance procurement through centralized laundry services.
United States Fabric Shavers Market Competitive Landscape
Top-tier vendors anchor premium cordless lithium-ion platforms, while mid-tier assemblers compete on price-accessible household configurations. The market structure stratifies across three vendor archetypes: established personal care conglomerates with retail distribution depth, specialized garment care equipment fabricators, and emerging direct-to-professional service providers. Competitive moves concentrate on strategic partnerships with dry cleaning chains and geographic expansion into underserved Sun Belt metros.
Among established personal care conglomerates, Conair LLC, Philips Norelco, and Beautural occupy positions representing distinct strategic archetypes. Conair exemplifies mass-market retail dominance through established channel relationships. Philips Norelco anchors rechargeable electric platform engineering with extended product lifecycle positioning. Beautural represents the portable-care specialist archetype targeting urban consumer mobility requirements. These three entities collectively illustrate the competitive spectrum from household convenience to professional-grade specifications.
| Leading Market Players |
|---|
| Conair LLC |
| Philips Norelco |
| Beautural |
| Gleener |
| Remington Products Company |
| Steamery |
| Evercare |
| NORI |
| Falconeri |
| Others |
Pricing and Supply Chain Analysis
Specialty steel price indices from Japanese and German mills cascade through three distinct pricing tiers for fabric shavers, with battery chemistry costs and UL certification overhead determining final positioning across professional and household segments.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to rush orders from dry cleaning chains facing equipment failure, while spot inventory of prior-generation corded units trades at discounted clearance levels. Three-tier pricing structure across premium brushless-motor, standard lithium-ion, and economy disposable-battery levels segments buyers by runtime specification and service bundling. Cost compression in the economy tier is intensifying because Chinese assemblers are flooding mass-market channels with non-UL-certified alternatives. Retail consumers show highest price sensitivity, while commercial laundries prioritize uptime guarantees over unit cost.
Supply Chain Analysis
California's extended producer responsibility mandates for battery collection are reshaping sourcing decisions, forcing domestic assemblers to qualify local recycling partners before product launch. Precision-hardened rotary blades draw from Japanese and German specialty steel mills, with neodymium magnets for brushless motors concentrating in Chinese processing facilities. Single-source vulnerability in magnet supply exposes manufacturers to export restriction volatility. Distribution runs through authorized service networks for commercial accounts and mass-market retail channels for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where CPSC electrical safety standards and UL certification create barrier-to-entry moats that protect established manufacturers with testing infrastructure investments.
For Market Incumbents: To counter right-to-repair legislative threats in California and New York, secure exclusive blade attachment patents and build authorized service network density before component availability mandates take effect. Deepen backward integration into battery pack assembly to capture margin and control end-of-life collection compliance costs. For New Entrants and Emerging Players: Direct-to-professional subscription platforms offer the most penetrable route, targeting independent tailors in Houston and Dallas with blade replacement programs that bypass established retail gatekeepers. White-space concentration in Sun Belt metro corridors with lower competitive density than coastal hubs enables rapid share capture through localized service partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor brushless DC motor specialists with California DTSC-compliant battery infrastructure in the Midwest manufacturing belt. Long-term viability over the coming decade hinges on regulatory compliance scalability rather than pure cost position. Monitor state-level right-to-repair bill passage as the critical inflection signal for proprietary service revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| Authorized Service Network Expansion | Builds defensible moats against right-to-repair mandates in California and New York. |
| Brushless DC Motor Platform Migration | Extends service intervals from six months to three years, shifting revenue to premium hardware. |
| Battery Takeback Infrastructure Investment | Secures preferential retailer placement under California's extended producer responsibility framework. |
| Subscription Blade Replacement Program | Locks in customer lifetime value among professional tailors while bypassing retail margin compression. |
| Sun Belt Metro Corridor Entry | Captures underserved demand in Houston, Dallas, Miami, and Tampa with lower competitive density. |
Research Methodology
Trade publications, CPSC regulatory filings, and garment care equipment distributor databases formed the secondary backbone, supplemented by primary interviews with dry cleaning chain procurement directors, independent tailor operators, UL certification engineers, and lithium-ion battery recycling facility managers. Bottom-up and top-down triangulation validated volume estimates across product type and application segments.
Bottom-up modeling built from unit shipment data and average selling price trajectories, while top-down analysis cross-checked against aggregate equipment spend reported by commercial laundry trade associations across the projection horizon. Segmentation dimensions included product type, application, technology configuration, and end-user archetype. CAGRs derived from historical replacement cycle compression and professional adoption curve analysis, with battery chemistry cost curves and state regulatory adoption timelines as key forecast inputs.
The model holds under stable neodymium magnet supply and continued state-level environmental enforcement; deviation in export restrictions or federal preemption of right-to-repair legislation would shift replacement demand timing and vendor profitability structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Global Industrial Fabric Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Electric Fabric Shaver Market