
 Dyeing Machine Market | 2026-2036
Dyeing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Dyeing Machine Market Insights
Direct mill-to-manufacturer procurement channels across South Asia is reconfiguring how dyeing equipment reaches end users. Thies GmbH & Co. KG leverages its engineering depth in jet dyeing systems to anchor premium positioning in European technical textile mills. Fong's National Engineering Co. Ltd. dominates large-volume installations across China's integrated polyester corridor. Loris Bellini competes through specialized beam dyeing configurations for narrow fabric producers.
A dyeing machine applies colorants to textile substrates through controlled immersion, pressure, or padding processes, typically operating at liquor ratios between 1:4 and 1:12 depending on technology class. Jet dyeing machines circulate fabric in rope form using pressurized dye liquor, achieving uniform penetration on knitted and woven constructions. Water overflow dyeing retains the largest installed base across Asian textile mills, though air-flow dyeing commands margin premiums through 50% water reduction. Digital dyeing represents the fastest-expanding technology segment as garment producers demand lot-size flexibility and zero discharge compliance.
REACH restricts azo dyes and heavy metal formulations entering European supply chains, forcing equipment makers to validate chemical compatibility. China's MEE enforces wastewater discharge limits that render conventional jigger systems uneconomic in major textile provinces. India's CPCB mandates zero liquid discharge for clusters in Tirupur and Surat, redirecting capital toward closed-loop jet and pad dyeing investments. Stakeholders must weigh capital recovery timelines against regulatory trajectory uncertainty when selecting technology platforms.
Market Dynamics
Water scarcity in South Asian textile clusters is forcing capital reallocation toward closed-loop dyeing architectures, compressing payback period tolerances and elevating liquor ratio efficiency to the top of procurement criteria.
Growth Catalysts
- EU Green Deal discharge mandates:REACH restrictions on azo dyes and heavy metals are compelling European mills to validate chemical compatibility with low-liquor jet systems before supplier qualification.
- Polyester fabric demand surge:Sportswear and athleisure producers in Vietnam and Bangladesh are expanding automated beam dyeing capacity to serve export orders with shorter lead times.
- Digital dyeing maturation:Single-batch flexibility and zero-discharge compliance are attracting garment producers in Tirupur and Surat away from conventional overflow configurations.
Market Restraints
- Stainless steel input volatility:Machine construction costs fluctuate with nickel and chromium pricing, squeezing margin buffers for European and Japanese equipment fabricators.
- Technical limitation in natural fiber handling:Air-flow dyeing systems struggle to achieve consistent penetration on heavy cotton constructions, constraining adoption in denim-focused clusters.
- Regulatory friction from China's MEE:Wastewater discharge limits in Jiangsu and Zhejiang provinces have rendered conventional jigger systems uneconomic, stranding installed base values.
Strategic Opportunities
- Underpenetrated technical textile segment:Automotive airbag and industrial geotextile producers in Germany and South Korea represent untapped demand for precision beam dyeing configurations.
- Technology convergence of IoT and dye chemistry:Real-time spectral monitoring integrated with automated chemical dosing is enabling mills to reduce re-dye rates and water consumption simultaneously.
- India's PLI scheme for textile machinery:Capital subsidy eligibility for zero-liquid-discharge installations is redirecting investment toward closed-loop pad and jet systems in Surat and Ludhiana.
Industry Challenges
- Skill gap in mechatronics maintenance:Automated jet systems require technicians proficient in both pneumatic controls and dye chemistry, a combination scarce in Bangladesh's emerging clusters.
- Integration complexity with legacy ERP:Digital dyeing platforms demand data architecture upgrades that many Vietnamese and Indonesian mills have deferred due to capital constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyeing Machine Market |
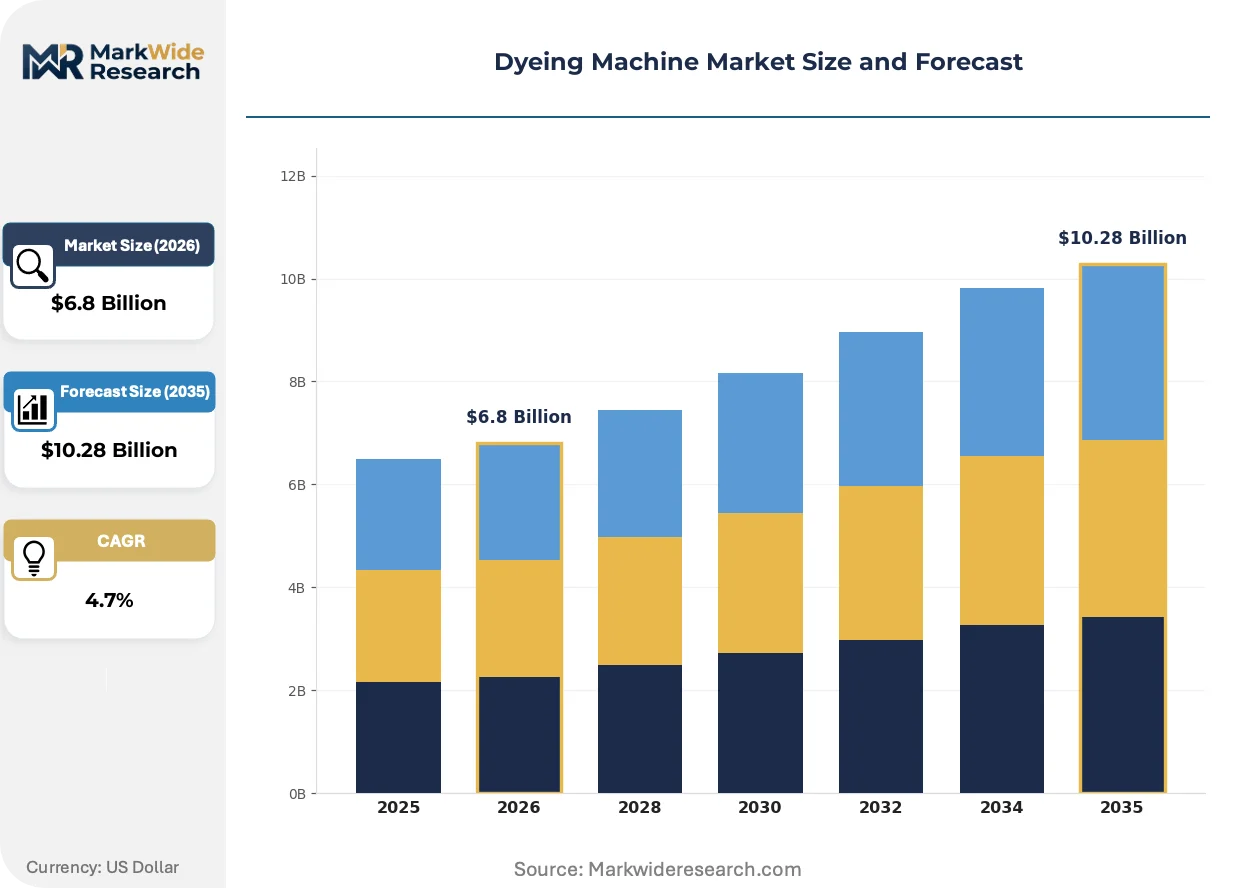
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jet Dyeing Machine, Jigger Dyeing Machine, Pad Dyeing Machine, Beam Dyeing Machine Technology: Air-flow Dyeing, Water Overflow Dyeing, Microwave Dyeing, Ultrasonic Dyeing, Digital Dyeing Application: Textile Mills, Knitting Units, Handloom Facilities, Nonwoven Fabric Production End User: Contract Dyeing Units, Fabric Manufacturers, Garment Producers, Textile Exporters |
| Companies Covered | Thies GmbH & Co. KG, Fong’s National Engineering Co. Ltd., Loris Bellini, Tong Geng, Brazzoli, Sclavos, COSMOTEX, DALAL ENGINEERING, Texfab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyeing Machine Market Trends and Innovations
Electrochemical coloration methods and AI-driven recipe optimization are compressing batch cycle times while regulatory pressure on water chemistry is locking in technology choices for the next equipment replacement cycle.
Supercritical CO₂ dyeing eliminates water entirely by dissolving disperse dyes in pressurized carbon dioxide, penetrating polyester fibers without effluent generation. Technical textile mills in Germany and Japan are piloting these systems for automotive and medical fabric applications. This technology is rendering obsolete conventional thermosol dyeing lines in high-compliance European manufacturing.
REACH authorization requirements for chromium-based mordants are tightening chemical input documentation across European supply chains. Dyeing equipment vendors must now certify compatibility with restricted substance lists before mill qualification. Italian and Spanish wool processors face the steepest compliance burden, accelerating migration to metal-free bio-mordant systems.
Garment producers are consolidating machine procurement through vertically integrated manufacturing groups rather than independent commission dyers. This disintermediation concentrates bargaining power with fewer buyers and shifts service expectations toward guaranteed throughput contracts. The pattern is most pronounced in Bangladesh, where large apparel groups now specify equipment configurations directly for captive dyeing units.
Dyeing Machine Market Segmentation
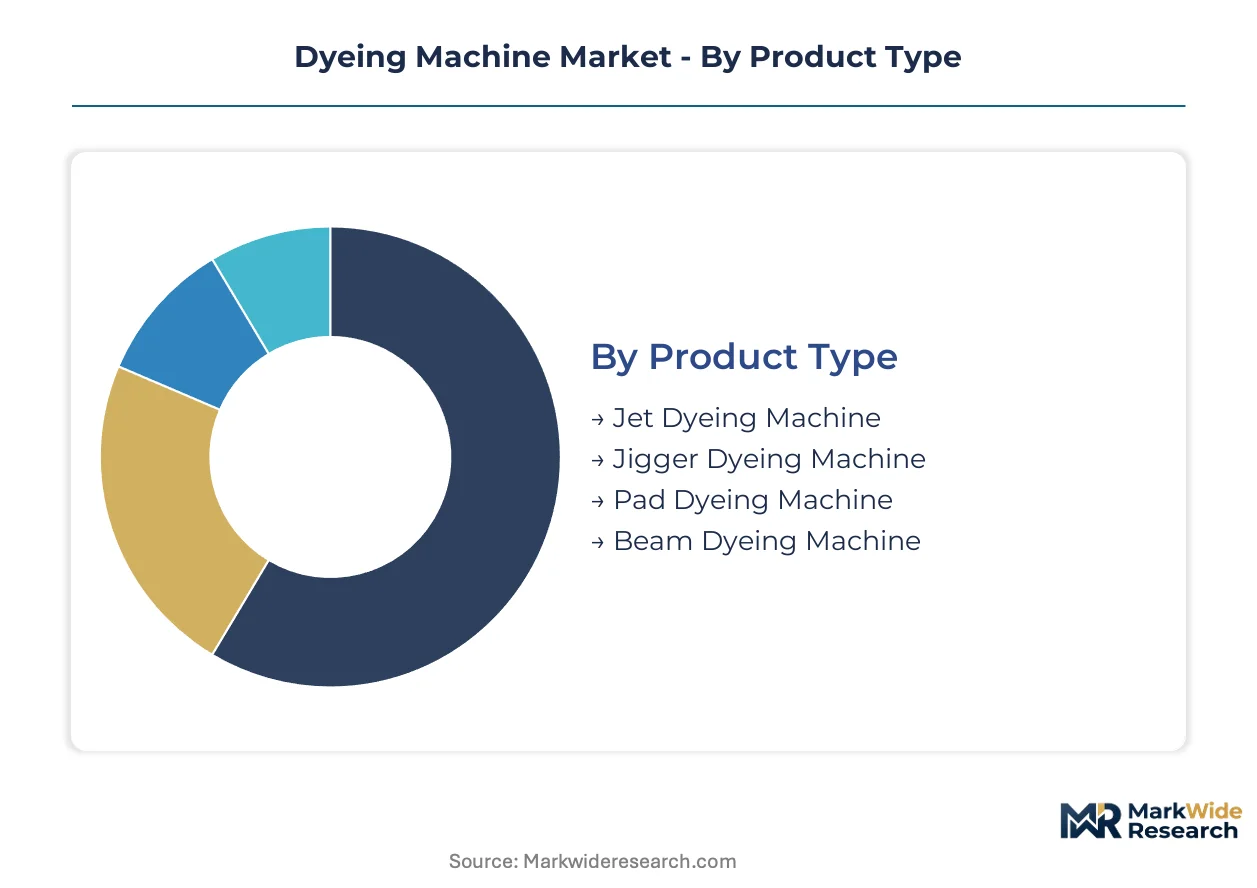
Technology choice in dyeing equipment locks in operational economics for 15-20 year asset lifecycles, making segment alignment with regulatory trajectory and substrate mix critical for capital recovery. Procurement patterns diverge sharply between export-oriented integrated mills and fragmented commission dyers serving domestic garment clusters.
Product Type:
Mature jet architectures dominate Asian polyester corridors while emerging beam configurations capture technical textile specialization.
- Jet Dyeing Machine:Circulates fabric in rope form using pressurized dye liquor at liquor ratios as low as 1:4, achieving uniform penetration on knitted constructions. Tirupur and Surat textile clusters in India are redirecting capital toward closed-loop jet systems to comply with CPCB zero liquid discharge mandates.
- Beam Dyeing Machine:Winds fabric onto perforated beams for axial liquor flow, enabling precise tension control on woven technical fabrics. Automotive airbag and geotextile producers in Germany and South Korea represent expanding demand for precision beam configurations with automated tension monitoring.
- Jigger Dyeing Machine:Batch-wise immersion system for open-width woven fabrics, now rendered uneconomic in China's Jiangsu and Zhejiang provinces under MEE wastewater discharge limits.
- Pad Dyeing Machine:Continuous padding application for woven substrates, favored by large-volume denim and shirting producers seeking throughput over flexibility.
Jet dyeing machines retain volume leadership; beam dyeing configurations hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium waterless systems from standard overflow configurations competing on capital efficiency.
- Digital Dyeing:Drop-on-demand colorant application eliminates batch setup and enables single-garment production runs. Garment producers in Bangladesh and Vietnam are adopting digital platforms to serve fast-fashion export orders with lot-size flexibility and zero discharge compliance.
- Air-flow Dyeing:Uses recirculated hot air rather than water bath to transport fabric, reducing water consumption by approximately half compared to overflow systems. Technical limitation in heavy cotton penetration constrains adoption in denim-focused clusters despite margin premiums.
- Water Overflow Dyeing:Retains the largest installed base across Asian textile mills due to lower capital threshold and technician familiarity.
- Microwave Dyeing:Electromagnetic energy accelerates dye fixation, compressing batch cycle times for time-sensitive synthetic fiber processing.
- Ultrasonic Dyeing:Cavitation-enhanced penetration reduces dye and auxiliary chemical consumption for natural fiber substrates.
Water overflow dyeing commands installed base dominance; digital dyeing platforms are climbing the fastest in new capital allocation.
Application:
Customer type determines specification complexity, with vertically integrated mills demanding automation integration absent from handloom procurement.
- Textile Mills:Large-scale integrated facilities with captive weaving and finishing operations, specifying equipment with ERP connectivity and guaranteed throughput contracts.
- Knitting Units:Process greige knitted fabrics for garment producers, driving demand for jet systems compatible with delicate loop constructions and stretch substrates.
- Handloom Facilities:Small-batch artisanal operations with minimal automation requirements and manual material handling constraints.
- Nonwoven Fabric Production:Industrial fiber mat dyeing for hygiene, filtration, and medical applications requiring specialized pad and spray configurations.
Textile mills anchor equipment volume; nonwoven fabric production represents the most rapid technology upgrade cycle.
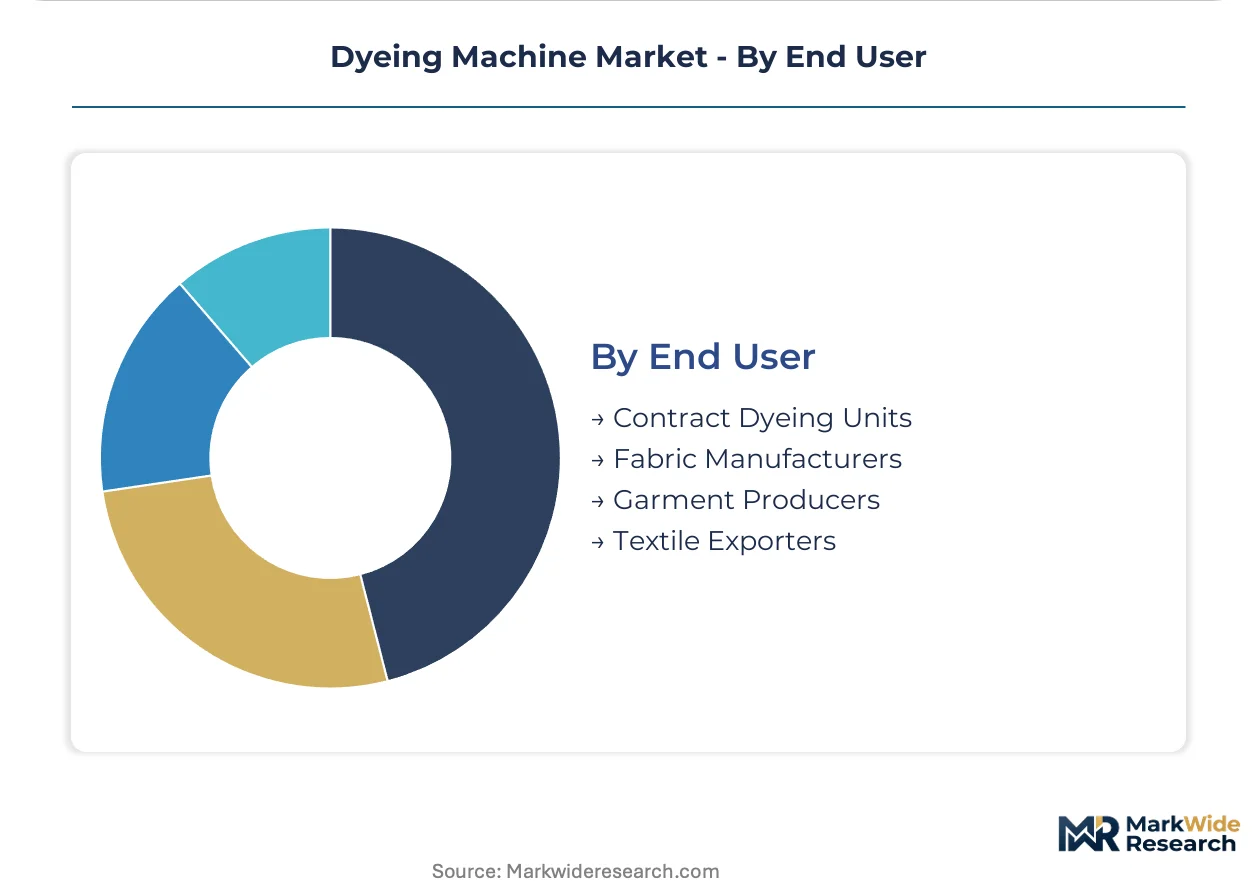
End User:
Supply concentration among vertically integrated garment groups is disintermediating independent commission dyers from equipment procurement decisions.
- Garment Producers:Large apparel groups in Bangladesh now specify equipment configurations directly for captive dyeing units, consolidating bargaining power and shifting service expectations toward guaranteed output contracts.
- Fabric Manufacturers:Vertically integrated mills in Vietnam and Bangladesh expanding automated capacity to meet export order lead time compression.
- Contract Dyeing Units:Independent commission dyers facing margin compression as garment producers internalize dyeing operations to control quality and scheduling.
- Textile Exporters:Export-oriented operations prioritizing certification compliance with EU Green Deal and REACH restrictions for European market access.
Fabric manufacturers retain procurement volume leadership; garment producers are gaining share fastest through captive integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium equipment pricing in Germany extracts threefold margins compared to standardized configurations in Bangladesh. Chinese fabricators dominate volume throughput across the polyester corridor. Indian regulatory mandates are redirecting capital toward closed-loop architectures in Surat and Tirupur.
China
Integrated polyester mills in Jiangsu and Zhejiang provinces drive automated beam dyeing procurement for export-oriented sportswear contracts. MEE wastewater discharge limits have rendered conventional jigger systems uneconomic, forcing capital reallocation toward low-liquor jet configurations. The Shaoxing textile cluster now specifies equipment with guaranteed throughput contracts rather than standalone machine purchases.
Germany
Automotive airbag and technical textile producers in Baden-Württemberg demand precision beam dyeing with automated tension monitoring for industrial geotextile applications. REACH authorization requirements for chromium-based mordants tighten chemical input documentation across Bavarian wool processing centers. Thies GmbH & Co. KG anchors premium positioning through engineering depth in jet systems for European technical textile mills.
India
Zero liquid discharge mandates from CPCB redirect Tirupur and Surat clusters toward closed-loop pad and jet dyeing investments. PLI scheme capital subsidies for textile machinery accelerate procurement of water-recirculating architectures in Ludhiana. Fong's National Engineering Co. Ltd. dominates large-volume installations serving India's integrated polyester corridor.
Bangladesh
Large apparel groups specify equipment configurations directly for captive dyeing units, consolidating bargaining power with machine vendors. Export order lead time compression drives automated capacity expansion across Dhaka and Chittagong manufacturing zones. Skill gaps in mechatronics maintenance constrain adoption of advanced pneumatic control systems despite capital availability.
Vietnam
Vertically integrated fabric manufacturers expand automated dyeing capacity to serve fast-fashion export contracts with shorter delivery windows. ERP integration complexity delays digital dyeing platform adoption despite garment producer demand for lot-size flexibility. The Ho Chi Minh City industrial corridor concentrates procurement decisions among fewer captive dyeing units.
Dyeing Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying pumps, valves, and control modules. The vendor base stratifies between European precision fabricators, Chinese scale producers, and Italian narrow-fabric specialists. Three archetypes dominate: engineering-heavy system integrators, cost-optimized volume manufacturers, and application-specific niche configurators. Competitive moves concentrate on geographic expansion through local assembly partnerships and technology licensing agreements to bypass import tariff exposure.
Among European engineering-centric fabricators, Thies GmbH & Co. KG and Loris Bellini exemplify divergent specialization strategies—Thies anchoring premium jet system positioning while Bellini occupies narrow-fabric beam configuration expertise. Fong's National Engineering Co. Ltd. represents the scale-driven archetype, with Chinese corporate structure enabling integrated supply chain control over polyester corridor installations. These three entities collectively illustrate how geographic origin and organizational form predict competitive positioning across the technology spectrum.
| Leading Market Players |
|---|
| Thies GmbH & Co. KG |
| Fong's National Engineering Co. Ltd. |
| Loris Bellini |
| Tong Geng |
| Brazzoli |
| Sclavos |
| COSMOTEX |
| DALAL ENGINEERING |
| Texfab |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Jiangsu and Zhejiang polyester corridors compresses margin buffers for European and Japanese fabricators while elevating buyer bargaining power across Asian procurement clusters. This utilization dynamic forces equipment vendors toward configured-to-order positioning or volume-driven standardization to defend pricing posture.
Pricing Analysis
Configured-to-order beam dyeing systems for automotive airbag producers command substantial premiums over standardized jet configurations serving Bangladeshi garment groups. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by automation depth and ERP integration capability. Cost compression in economy-tier overflow systems is intensifying because Chinese fabricators leverage integrated stainless steel supply chains. Commission dyers in Surat and Tirupur exhibit highest price sensitivity; German technical textile mills demonstrate lowest sensitivity due to REACH compliance bundling.
Supply Chain Analysis
Stainless steel feedstock draws from Chinese nickel processing hubs, Indian chromium suppliers, and Japanese specialty alloy fabricators. Machine construction rests on pneumatic valve assemblies from Germany, control modules from Japan, and casting components from China's Yangtze River Delta. Single-source vulnerability concentrates in high-precision pump assemblies sourced from Italian engineering specialists. Distribution runs through mill-direct procurement channels anchored by vertically integrated garment groups in Bangladesh and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from regulatory divergence across textile clusters, as zero-liquid-discharge mandates in India, MEE restrictions in China, and REACH evolution in Europe create incompatible equipment specifications that niche configurators can exploit.
For Market Incumbents: Build regulatory-certification moats by pre-qualifying jet and beam systems with India's CPCB, China's MEE, and ECHA simultaneously. Anchor premium positioning through guaranteed throughput contracts with German automotive airbag producers. Deepen backward integration into stainless steel component forging to offset nickel price volatility squeezing margin buffers. For New Entrants and Emerging Players: Vietnam's ERP-integration gap presents fertile terrain for digital dyeing platform specialists offering turnkey data architecture upgrades. Target captive dyeing units in Ho Chi Minh City industrial corridor seeking lot-size flexibility for fast-fashion export contracts. Partner with local mechatronics training institutes to overcome Bangladesh's technician scarcity constraining advanced pneumatic system adoption. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-technology play because water-scarcity trajectory and discharge mandates lock in 15-20 year replacement cycles favoring closed-loop architectures. Pursue acquisition targets with validated zero-liquid-discharge installations in Tirupur and Surat clusters. Monitor India's PLI scheme disbursement velocity as inflection signal for capital reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Enables European jet system specialists to bypass tariff exposure in Bangladesh through local assembly partnerships. |
| Backward Integration | Captive stainless steel component production insulates margin buffers from nickel price volatility in machine construction. |
| Green Manufacturing Transition | Supercritical CO₂ dyeing pilot investments position vendors for REACH authorization requirements tightening across Bavarian wool processing. |
| Joint Venture | Local assembly partnerships in Vietnam and Indonesia address ERP integration complexity delaying digital platform adoption. |
| Long-term Supply Agreement | Guaranteed throughput contracts with Shaoxing textile cluster shift procurement from standalone machines to output-based arrangements. |
Research Methodology
Initial hypotheses were tested against primary input from textile mill engineering directors, garment group procurement heads, dyeing equipment maintenance supervisors, and aftermarket service technicians and refined through secondary validation against customs trade records, textile machinery association shipment databases, CPCB zero-liquid-discharge compliance filings, and SEC 10-K disclosures from publicly listed fabricators. Bottom-up unit economics from individual cluster installations were triangulated against top-down market sizing derived from regional production capacity estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling technology type, liquor ratio efficiency tier, end-use application, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from installed base replacement cycles overlaid with regulatory mandate enforcement timelines. Forecast inputs incorporated water scarcity indices for South Asian textile clusters and EU Green Deal implementation trajectory for discharge compliance.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed fabricators or accelerated REACH substance restrictions would shift outcomes beyond modeled ranges. Cross-checking against machinery import data from Bangladesh's EPB and Vietnam's customs authority is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Embroidery Machine Market
Textile Machinery and Equipment
Textile Winding Machine Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market