
 Textile Printer Market | 2026-2036
Textile Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Printer Market Insights
A capital-intensity divergence between single-pass inkjet pioneers and multi-pass retrofit specialists is rotating competitive dynamics in textile printing. Kornit Digital leverages vertically integrated pigment chemistry and pre-treatment systems to sustain premium positioning in on-demand fashion workflows. Mimaki Engineering anchors mid-volume flexible production with hybrid UV-textile platforms across Japanese and Southeast Asian install bases. Durst Group AG dominates the European industrial segment with high-throughput single-pass architectures for home textile converters.
A textile printer is an industrial imaging system that deposits colorant onto woven, knitted, or non-woven substrates through piezoelectric, thermal, or rotary screen mechanisms, typically achieving resolutions between 600 and 2400 DPI with throughput rates from 50 to 1000+ square meters per hour depending on architecture. Its primary purpose is to replace analog screen and rotary printing with digitally addressable, lot-size-flexible production that eliminates engraved cylinder costs and reduces water consumption by 50-90% in pigment-based workflows. Inkjet technology leads installed value due to its compatibility with reactive, acid, disperse, and pigment chemistries across natural and synthetic fibers, while single-pass printer types capture the fastest expansion as fashion brands demand same-day sample-to-production turnaround. Digital transfer applications concentrate margin pools in promotional items and soft signage, where short runs and photographic detail command pricing premiums over screen-printed alternatives.
REACH chemical restrictions enforced by ECHA limit azo dyes and heavy metal formulations in European textile supply chains, directly shaping R&D priorities for ink developers and OEM compliance roadmaps. The EU Green Deal's textile strategy and emerging digital product passport requirements are forcing printer manufacturers to document energy consumption, chemical inputs, and substrate compatibility across equipment lifecycles. In the United States, EPA effluent guidelines for textile mills are accelerating interest in waterless pigment systems that bypass conventional dyehouse infrastructure. Stakeholders must monitor how regulatory timelines for per- and polyfluoroalkyl substance restrictions in technical fabrics will reshape ink formulation investments and create certification barriers for non-compliant equipment portfolios.
Market Dynamics
Single-pass inkjet architectures are compressing design-to-production timelines from weeks to hours, forcing converters to choose between capital-intensive newbuilds and obsolescence of multi-pass retrofit fleets.
Growth Catalysts
- EU REACH chemical restrictions:ECHA enforcement against azo dyes and heavy metal formulations is pushing European converters toward waterless pigment inkjet platforms that bypass conventional dyehouse infrastructure.
- India PLI scheme:Government production-linked incentives for textile manufacturing are pulling installed printer capacity expansion into export-oriented garment hubs around Tiruppur and Surat.
- Reactive ink chemistry advances:Improved fixation rates on cellulosic fibers are extending digital compatibility to cotton-dominant fashion supply chains previously locked to screen printing.
Market Restraints
- Piezoelectric printhead supply concentration:Japanese and German MEMS foundries control critical nozzle plate manufacturing, creating single-source vulnerability for OEMs scaling production.
- Pretreatment chemical cost volatility:Polymer binders and cationic agents for pigment systems fluctuate with petrochemical feedstock prices, compressing converter margins on short runs.
- Rotary screen residual capacity:Existing analog infrastructure in Bangladesh and Vietnam continues to underbid digital on volume orders above 5,000 meters.
Strategic Opportunities
- Technical textile applications:Automotive interior panels and medical soft goods remain underpenetrated by digital printing, offering margin premiums over commoditized apparel.
- Digital transfer sublimation:Soft signage and promotional merchandise channels are consolidating demand for photographic-detail output on polyester substrates.
- EU Green Deal textile strategy:Emerging digital product passport requirements will favor OEMs with documented energy and chemical input transparency across equipment lifecycles.
Industry Challenges
- Color management specialist scarcity:ICC profiling and RIP calibration expertise concentrates among veteran screen printers approaching retirement, creating knowledge transfer gaps.
- Legacy ERP integration:Converter MRP systems built for batch dyeing workflows require costly middleware development to sync with digital job queuing and ink consumption tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Printer Market |
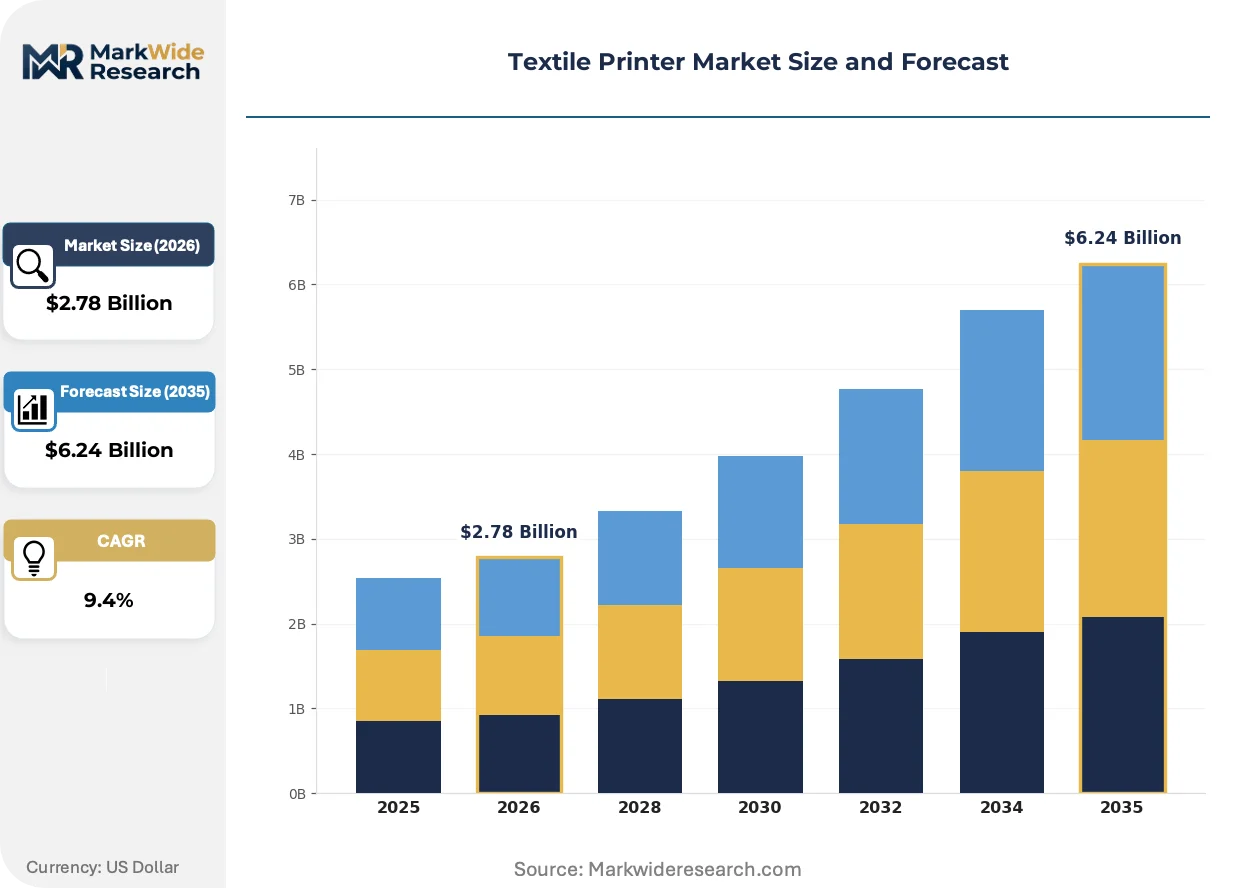
| Market Size in 2026 | $2.78 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Inkjet, Sublimation, Screen, Digital Transfer, Reactive Dye, Discharge Printer Type: Single-Pass, Multi-Pass, Hybrid, Continuous Roll, Flatbed, Modular Application: Fashion Apparel, Home Textiles, Technical Fabrics, Promotional Items, Soft Signage, Automotive Interiors End User: Textile Manufacturers, Print Service Providers, Designers, OEMs, Contract Printers, Custom Tailors |
| Companies Covered | Seiko Epson Corporation, Mimaki Engineering Co., Ltd., Kornit Digital Ltd., EFI Reggiani, HP Inc., Durst Group AG, Brother Industries, Ltd., Ricoh Company, Ltd., SPGPrints B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Printer Market Trends and Innovations
Hardware-ink-substrate convergence is collapsing the traditional separation between printer OEMs and chemical suppliers, reshaping how converters source and service production systems.
Drop-on-demand piezoelectric printhead arrays are miniaturizing nozzle pitches below 20 microns while maintaining industrial duty cycles. High-fashion sampling studios in Milan and New York are adopting these heads for same-day strike-off production. The technology is miniaturizing the minimum viable production unit from factory floor to design studio, enabling distributed micro-factories.
EPA effluent guidelines for textile mills are tightening discharge limits on color and salinity in the United States. Waterless pigment workflows that eliminate wash-off stages are capturing interest from mid-volume converters in North Carolina and Los Angeles. California's Safer Consumer Products regulations are accelerating R&D into bio-based binder chemistries that maintain rub-fastness without perfluorinated compounds.
Converter purchasing committees now unbundle hardware acquisition from ongoing ink supply agreements, treating pretreatment fluids and color management as separately negotiable spend categories. This behavior is fragmenting vendor relationships that previously locked converters into single-source ecosystems. The shift is most visible among vertically integrated fashion brands building captive print capacity in Portugal and Turkey.
Textile Printer Market Segmentation
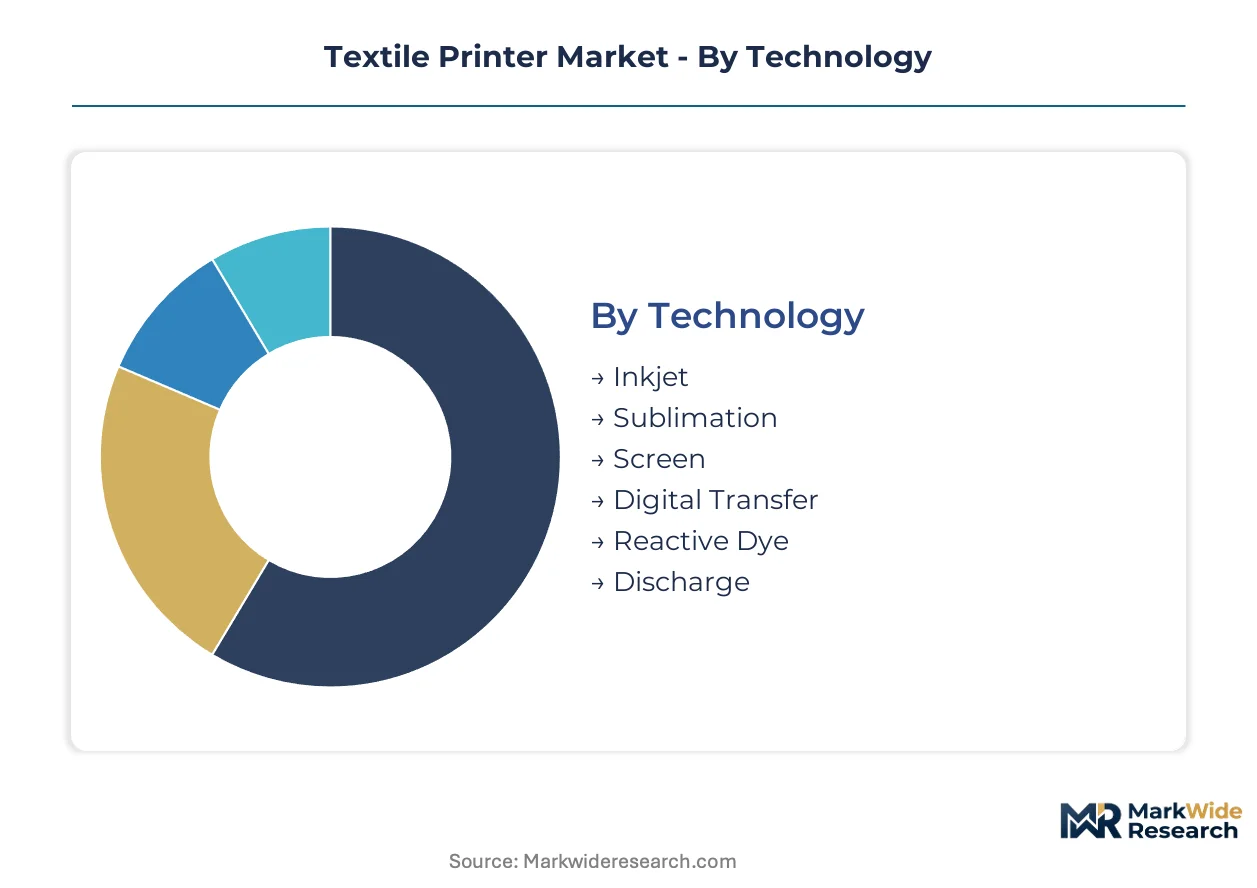
Technology and printer architecture choices determine water consumption, chemical compliance, and minimum efficient scale for textile converters navigating ECHA restrictions and fast-fashion timelines. Segment selection locks converters into specific ink chemistries, pretreatment workflows, and capital depreciation schedules that resist mid-life switching.
Technology:
Substitution pressure from waterless pigment systems is displacing conventional dyeing methods fastest in regions with strict effluent enforcement.
- Inkjet:Piezoelectric drop-on-demand systems deposit reactive, acid, disperse, or pigment inks onto natural and synthetic fibers at resolutions between 600 and 2400 DPI. European converters facing REACH azo dye restrictions are consolidating demand for pigment-compatible inkjet platforms that bypass wash-off stages entirely.
- Sublimation:Heat-activated dye transfer bonds disperse inks to polyester substrates through solid-to-gas phase transition without liquid water. Soft signage producers in Italy and Turkey are expanding sublimation capacity for photographic-detail output on polyester-based promotional merchandise.
- Screen:Mesh-based stencil printing pushes thick-film pastes through photo-emulsion patterns for high-opacity deposits on dark cottons. Bangladeshi and Vietnamese volume manufacturers retain screen capacity for orders exceeding 5,000 linear meters where digital cost structures fail.
- Digital Transfer:Intermediate paper-based imaging enables pre-printed designs to bond with fabric through heat press activation. Custom tailors in Portugal are adopting digital transfer for short-run sampling workflows requiring rapid design iteration.
- Reactive Dye:Cellulosic fiber-specific chemistry forms covalent bonds with cotton and viscose through alkaline fixation and steam processing. Indian garment hubs around Tiruppur are retrofitting reactive digital systems to serve export-oriented cotton fashion supply chains.
- Discharge:Bleach-based ink formulations remove existing dye from dark substrates to create tonal effects without additional colorant layers. Niche denim finishers in Los Angeles maintain discharge capability for vintage-wash replication on limited production runs.
Screen retains volume leadership in developing Asian manufacturing centers; inkjet holds the steepest expansion curve.
Printer Type:
Cost tier stratification separates capital-intensive single-pass installations from retrofit-friendly multi-pass architectures serving mid-volume converters.
- Single-Pass:Stationary print bar architectures with fixed nozzle arrays achieve throughput exceeding 1000 square meters per hour on continuous roll feeds. German and Italian home textile converters are deploying single-pass systems for same-day sample-to-production turnaround on duvet and curtain substrates.
- Multi-Pass:Scanning carriage systems traverse substrate beds repeatedly to build image density through multiple pass sequences. Japanese flexible manufacturers favor multi-pass platforms for hybrid UV-textile workflows accommodating variable lot sizes across nylon, cotton, and blended stocks.
- Hybrid:Dual-mode architectures switch between direct-to-fabric and transfer paper imaging without mechanical reconfiguration. Southeast Asian print service providers are specifying hybrid systems to capture both fashion apparel and soft signage contracts from common installed bases.
- Continuous Roll:Unwinding-rewinding material handling systems maintain tension control across thousands of meters of knitted or woven goods. Large-scale Turkish textile manufacturers deploy continuous roll configurations for uninterrupted production of bed linen and tablecloth exports.
- Flatbed:Rigid platen systems secure cut-piece goods or pre-sewn garments for precise registration on dimensional substrates. Contract printers in North Carolina operate flatbed units for sampling and pre-production strike-offs on irregular or padded textile forms.
- Modular:Field-upgradable chassis designs accept additional print bars, drying modules, or color stations as volume requirements expand. Emerging micro-factories in Milan and New York are selecting modular architectures to scale capacity without full equipment replacement.
Multi-pass systems dominate installed base counts; single-pass configurations are gaining share fastest among industrial converters.
Application:
Margin concentration varies sharply across applications, with technical and automotive segments commanding pricing premiums over commoditized apparel production.
- Fashion Apparel:Garment and accessory printing encompasses dresses, shirts, activewear, and outerwear across natural and synthetic fiber bases. Design studios in Paris and London are compressing design-to-shelf timelines through captive digital printing capacity for trend-responsive collections.
- Home Textiles:Bedding, upholstery, and decorative fabric applications require rub-fastness and lightfastness certification for residential use. Portuguese and Turkish converters serving European retailers are expanding pigment inkjet capacity for curtain and cushion cover production.
- Technical Fabrics:Performance-oriented substrates include geotextiles, filtration media, and industrial belting with specified tensile properties. Medical soft goods and automotive interior panels remain underpenetrated by digital methods, offering margin premiums over standard apparel.
- Promotional Items:Branded merchandise including bags, towels, and event apparel demands photographic detail on polyester and cotton blends. Print service providers in Germany are consolidating demand for digital transfer sublimation on promotional polyester substrates.
- Soft Signage:Display graphics, banners, and exhibition textiles require dye-sub output on lightweight, wrinkle-resistant polyester fabrics. Italian and Spanish visual communication specialists are displacing screen printing on short-run exhibition and retail signage contracts.
- Automotive Interiors:Seat covers, headliners, and trim panels demand flame-retardant and abrasion-resistant finishes meeting OEM specifications. Tier-1 suppliers in Germany and the United States are qualifying digital pigment systems for just-in-sequence interior component production.
Fashion apparel commands the largest addressable volume; technical fabrics are climbing the fastest as digital penetration advances.
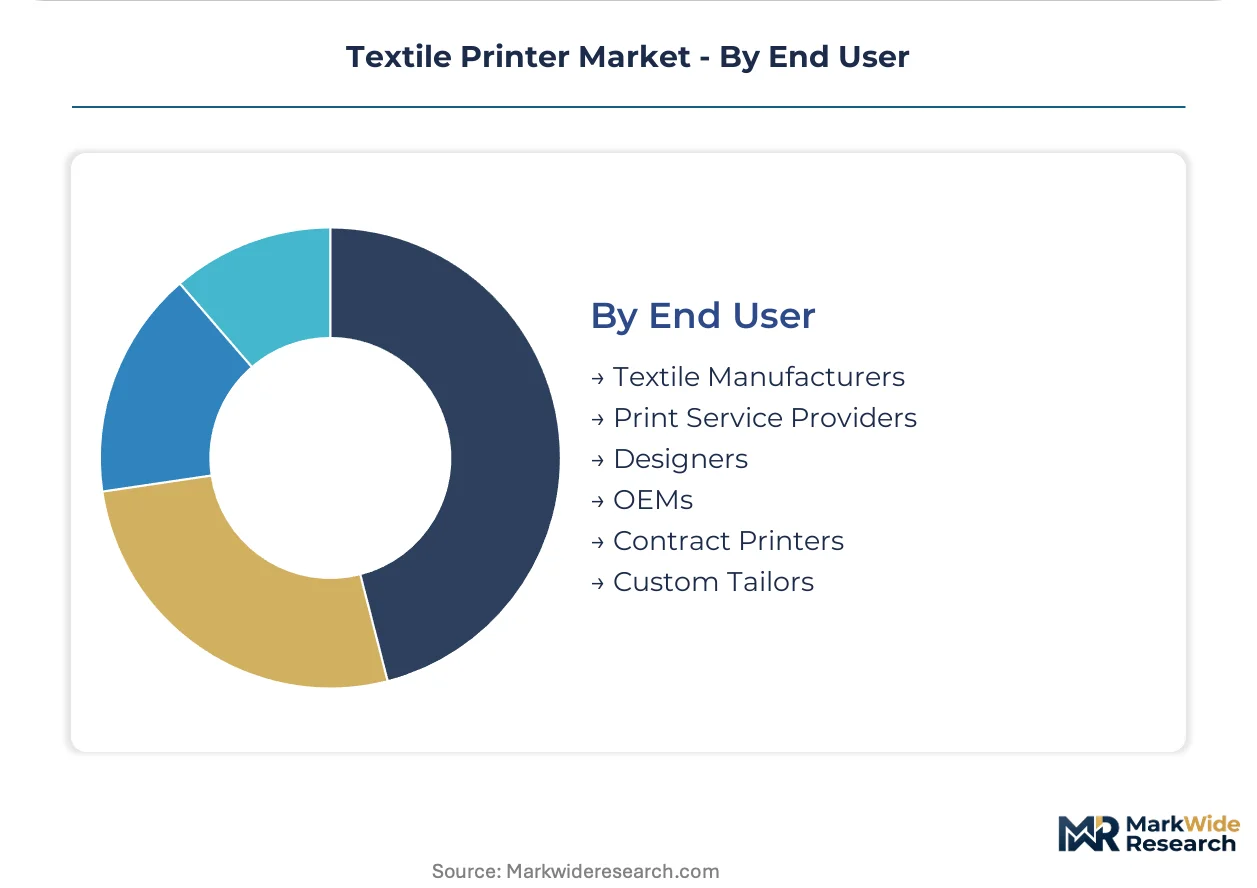
End User:
Customer type determines equipment specification, service contract structure, and ink procurement economics across the installed base.
- Textile Manufacturers:Vertically integrated mills with in-house weaving or knitting operations deploy printing as a finishing stage within continuous production lines. Indian export-oriented garment hubs are expanding captive digital capacity under PLI scheme incentives for integrated textile manufacturing.
- Print Service Providers:Independent converters without upstream textile production source greige goods from multiple mills and sell printed output to brand owners. Contract printers in Los Angeles and North Carolina are specializing in waterless pigment workflows for EPA-compliant mid-volume production.
- Designers:Independent creative studios and fashion houses operate sampling equipment for strike-off development and limited capsule collections. High-fashion ateliers in Milan and New York are miniaturizing production units for same-day sample realization.
- OEMs:Original equipment manufacturers of finished goods including automotive suppliers and furniture producers integrate printing into component manufacturing. Automotive interior specialists in Germany are qualifying digital systems for seat cover and headliner production.
- Contract Printers:Third-party production specialists execute overflow and peak-demand printing for brand owners without captive capacity. Turkish and Portuguese contract operations are capturing nearshoring demand from European fashion brands seeking compressed lead times.
- Custom Tailors:Bespoke garment producers and made-to-measure services offer personalized textile design as a value-added client service. Small-scale operations in London and Tokyo are deploying compact flatbed systems for one-off and small-batch custom production.
Textile manufacturers retain the deepest installed value; print service providers are expanding most quickly as brands outsource non-core printing functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Italy show low price elasticity for waterless pigment systems meeting ECHA compliance, while volume manufacturers in India and Vietnam remain highly sensitive to per-meter operating costs above rotary screen benchmarks.
United States
Mid-volume converters in North Carolina and Los Angeles drive demand for EPA-compliant pigment workflows. EPA effluent guidelines tightening discharge limits on color and salinity push mills toward waterless systems. California's Safer Consumer Products regulations accelerate bio-based binder R&D among Los Angeles-area finishers.
Germany
Home textile converters prioritize single-pass architectures for same-day sample-to-production turnaround. ECHA REACH enforcement against azo dyes and heavy metal formulations shapes ink developer compliance roadmaps. Industrial clusters around Stuttgart and Mönchengladbach deploy high-throughput systems for duvet and curtain exports.
India
Export-oriented garment hubs around Tiruppur and Surat expand installed capacity under government production-linked incentives. DGFT export promotion schemes and PLI scheme disbursements pull capital investment into integrated textile manufacturing. Cotton-dominant supply chains in Tamil Nadu retrofit reactive digital systems for European fashion brand contracts.
Italy
Soft signage and high-fashion sampling studios drive demand for photographic-detail output. EU Green Deal textile strategy and emerging digital product passport requirements favor OEMs with documented energy transparency. Visual communication specialists in Milan and Como displace screen printing on short-run exhibition and retail signage.
Turkey
Nearshoring demand from European fashion brands compresses lead times for contract printers. REACH-aligned chemical compliance requirements penetrate supplier audits for EU-bound exports. Large-scale manufacturers in Bursa and Istanbul deploy continuous roll configurations for uninterrupted bed linen and tablecloth production.
Textile Printer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated pigment chemistry specialists commanding premium positioning while multi-pass retrofit fabricators compete on capital accessibility. The vendor base stratifies across three tiers: single-pass pioneers with proprietary ink ecosystems, hybrid-platform generalists serving mid-volume flexible production, and regional retrofit specialists extending legacy fleet life. Consolidation pressure concentrates among inkjet printhead OEMs and pretreatment chemical suppliers as hardware-ink-substrate convergence accelerates. Dominant competitive moves include strategic partnerships between printer manufacturers and regional chemical distributors, plus geographic expansion into Indian and Southeast Asian garment hubs under government incentive schemes.
Within the vertically integrated tier, Kornit Digital Ltd. and Durst Group AG exemplify archetypes combining proprietary chemistry with system architecture control. Mimaki Engineering Co., Ltd. occupies a position bridging mid-volume flexibility and hybrid workflow compatibility across Japanese and Southeast Asian install bases. These three anchors illustrate how competitive positioning increasingly depends on captive supply of consumables rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Seiko Epson Corporation |
| Mimaki Engineering Co., Ltd. |
| Kornit Digital Ltd. |
| EFI Reggiani |
| HP Inc. |
| Durst Group AG |
| Brother Industries, Ltd. |
| Ricoh Company, Ltd. |
| SPGPrints B.V. |
| Others |
Pricing and Supply Chain Analysis
Take-or-pay ink supply agreements lock European converters into multi-year pretreatment chemical commitments that guarantee ECHA-compliant pigment access while capping per-meter cost exposure against volatile petrochemical feedstock swings.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value for OEMs, with three-tier pricing structure across premium, standard, and economy levels separating single-pass pioneers from multi-pass retrofit fabricators. Price differentiation rests on REACH certification grade and captive ink chemistry integration, with premium positioning commanding maintenance-inclusive bundles. Cost compression in mid-volume segments is intensifying because converter purchasing committees now unbundle hardware from consumables procurement. Print service providers in North Carolina and Los Angeles show highest price sensitivity to per-meter operating costs, while German home textile converters demonstrate lowest elasticity for ECHA-compliant waterless systems.
Supply Chain Analysis
Inventory lead times for piezoelectric printhead nozzle plates extend 16-24 weeks due to MEMS foundry concentration in Japan and Germany. Geographic supply concentration centers on Japanese MEMS fabrication, German precision engineering, and Indian garment hub assembly for regional retrofit specialists. Raw material dependencies draw from silicon wafer substrates, polymer binder chemistries, and cationic pretreatment agents. Single-source vulnerability in nozzle plate manufacturing creates structural supply chain risk. Distribution runs through regional chemical distributors partnered with printer OEMs, plus direct OEM channels for large-scale textile manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of ICC profiling and RIP calibration expertise among retiring veteran screen printers creates a capability bottleneck that will determine which OEMs capture converter loyalty over the next decade.
For Market Incumbents: Compound defensive positioning through captive supply of pretreatment chemicals and printhead refurbishment services to lock converters into ecosystem dependency. Kornit Digital's vertically integrated pigment chemistry model demonstrates how ink formulation control neutralizes price erosion from Asian retrofit competitors. Prioritize certification investment for EU Green Deal digital product passport compliance before 2027 enforcement windows. For New Entrants and Emerging Players: Remote color management and cloud-based RIP calibration services represent a service-layer gap where incumbents under-serve mid-volume converters lacking in-house expertise. Technical textile applications in automotive interiors and medical soft goods offer the most penetrable white-space with margin premiums 40-60% above commoditized apparel. Pursue partnership-based go-to-market angles with regional chemical distributors in Indian PLI scheme beneficiary hubs around Tiruppur and Surat. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated pigment chemistry specialists with documented ECHA compliance roadmaps and established OEM distribution partnerships. Long-term viability over a 5-10 year window favors players controlling both printhead architecture and consumables formulation rather than hardware-only fabricators. Watch for inflection signals in EPA effluent guideline enforcement tightening that would accelerate waterless pigment system replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Chemistry | Captive ink formulation control neutralizes price erosion from Asian retrofit competitors and locks converter loyalty. |
| EU Green Deal Certification Program | Documented energy and chemical transparency qualifies OEMs for emerging digital product passport requirements. |
| Remote Color Management Service Launch | Cloud-based ICC profiling addresses capability scarcity among mid-volume converters lacking in-house expertise. |
| Joint Venture in Indian Garment Hubs | PLI scheme beneficiary locations around Tiruppur offer government-incentivized capacity expansion for export-oriented production. |
| Technical Textile Application Development | Automotive interior and medical soft goods segments command margin premiums over commoditized fashion apparel printing. |
Research Methodology
A spread of perspectives from textile converter operations directors, ink formulation chemists, OEM regional sales managers, and ECHA regulatory compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC equipment manufacturer filings, and EU textile machinery import statistics. Bottom-up triangulation across installed base counts and top-down cross-checks against regional production capacity estimates anchored volume assumptions.
Segmentation dimensions modeled span technology architecture, printer type configuration, application end-use, and end-user customer category across the projection horizon. Analytical framework approach incorporates technology substitution curves, regulatory compliance cost differentials, and regional incentive scheme disbursement timelines throughout the forecast period. CAGRs were derived from S-curve adoption modeling calibrated to historical analogs in industrial digital printing transitions.
Underlying assumptions cover ECHA enforcement continuity, PLI scheme disbursement schedules, and MEMS foundry capacity expansion, with deviation risk concentrated in EPA effluent guideline acceleration and perfluorinated compound restriction timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Embroidery Machine Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
Textile Winding Machine Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Cloth Cutting Machines Market