
 Linen Supply and Management Services Market | 2026-2036
Linen Supply and Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Linen Supply and Management Services Market Foresight
The capital-intensity divergence between industrial-scale tunnel washers and smaller batch operations is collapsing as mid-tier providers face equipment replacement cycles that favor automated continuous-batch systems. Cintas Corporation leverages its captive uniform rental network to cross-sell managed linen programs to manufacturing clients. UniFirst Corporation anchors its position through vertically integrated garment production that reduces supplier dependency for core uniform categories. Elis SA dominates European healthcare linen contracts through ISO-certified processing plants that meet stringent hygiene protocols.
Linen supply and management services encompass the commercial provisioning, laundering, tracking, and replacement of textile goods used in institutional and hospitality settings, typically processed through high-temperature tunnel washing systems exceeding 71 degrees Celsius to achieve hygienically clean certification. The primary purpose centers on ensuring consistent quality, inventory availability, and compliance with hygiene standards while eliminating capital tie-up in textile assets for end users. Rental services command the largest revenue share by absorbing capital expenditure burdens from healthcare and hospitality operators, while managed services represent the fastest-expanding segment as facilities outsource inventory tracking, par-level optimization, and compliance documentation to specialized providers. Bedding and table linens generate the steadiest demand flows from acute-care hospitals and full-service hotels, whereas uniforms present higher margin pools due to customized sizing, logo application, and replacement cycle management.
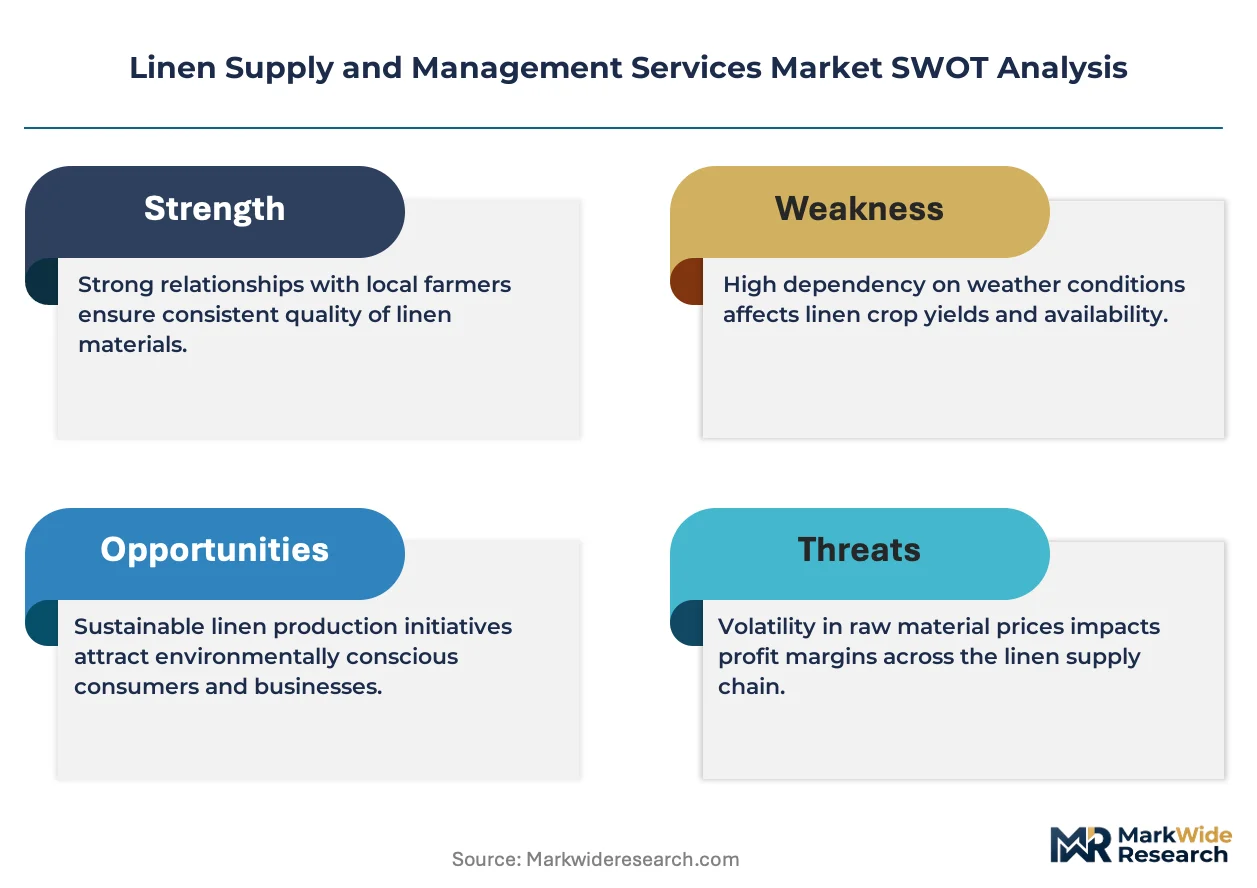
OSHA bloodborne pathogen standards and EPA Clean Water Act discharge limits shape processing facility investments, while FDA guidance on medical device textiles influences barrier fabric selection for surgical linens. Healthcare Facilities Group, a major hospitality and healthcare end user segment, faces Joint Commission audit requirements that mandate documented linen handling protocols from soiled collection through clean delivery. Stakeholders must monitor how state-level water scarcity regulations and energy cost trajectories reshape the economics of centralized versus distributed processing network configurations.
Market Dynamics
Hospital consolidation and hotel chain standardization are compressing procurement timelines and favoring national account contracts that centralize linen management under fewer, larger service providers with multi-state processing networks.
Growth Catalysts
- OSHA Bloodborne Pathogen Standards:Healthcare facilities outsource linen handling to eliminate liability exposure from staff exposure incidents during soiled linen collection and transport.
- Tunnel Washing Automation:Continuous-batch tunnel systems processing 1,000+ pounds per hour cut water consumption by 40 percent versus conventional washers, attracting sustainability-focused hospital systems.
- Joint Commission Audit Requirements:Documented chain-of-custody protocols from soiled pickup through hygienically clean delivery drive demand for specialized compliance tracking services.
Market Restraints
- Natural Gas Price Volatility:Industrial laundries consume 30-50 percent of operating costs in thermal energy for water heating and drying, exposing margins to commodity swings.
- EPA Clean Water Act Discharge Limits:Wastewater treatment upgrades for phosphorus and surfactant removal require seven-figure capital investments that strain mid-tier operators.
- Regional Water Scarcity Mandates:State-level reuse requirements in drought-prone US states force processing plant relocations or expensive closed-loop recycling systems.
Strategic Opportunities
- RFID-Enabled Inventory Tracking:Real-time textile monitoring reduces par-level overstock by 20 percent while generating compliance documentation for Joint Commission surveys.
- Extended Stay Hospitality:Apartment-style hotels with weekly linen exchanges create predictable volume contracts with lower delivery frequency costs than daily-change properties.
- US Inflation Reduction Act Energy Credits:Heat recovery and solar thermal installations qualify for federal incentives that improve project returns on processing facility retrofits.
Industry Challenges
- Hygienically Clean Certification Timelines:Third-party validation through the Textile Rental Services Association requires 90-day audit cycles that delay new contract launches.
- Route Density Optimization:Last-mile delivery to dispersed rural hospitals and independent hotels strains fleet efficiency compared to urban health system clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linen Supply and Management Services Market |
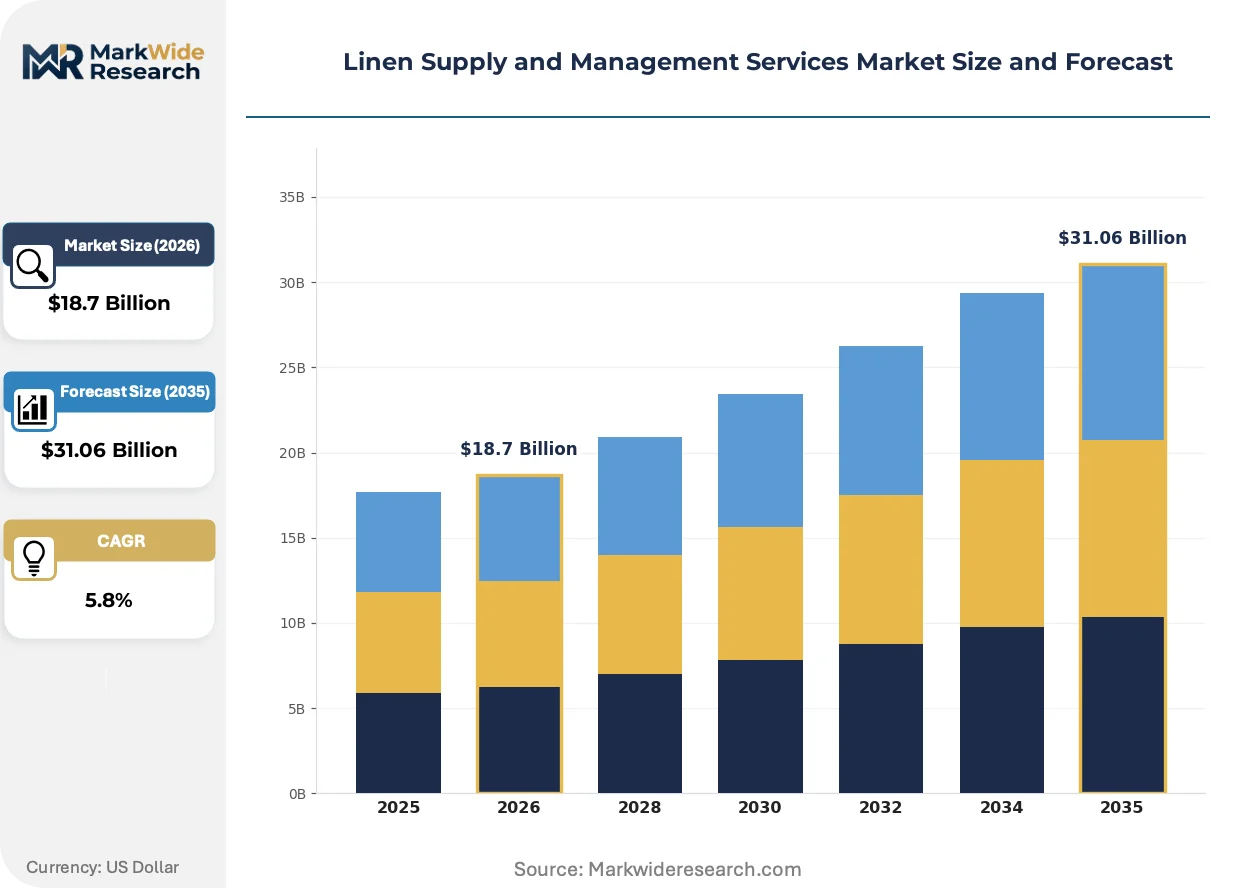
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rental, Leasing, Direct Sale, Managed Services End User: Healthcare Facilities, Hospitality, Restaurants, Industrial Product Type: Table Linens, Bedding, Towels, Uniforms Delivery Model: On-demand, Scheduled, Subscription, Hybrid |
| Companies Covered | Aramark Corporation, Cintas Corporation, ImageFIRST Healthcare Laundry Specialists, Unitex Textile Rental Services, Elis SA, Alsco Inc., Angelica Corporation, Healthcare Services Group, UniFirst Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linen Supply and Management Services Market Shifts & Advancements
Automation and sensor technology are compressing the labor component of linen processing while regulatory pressure on water and energy use forces equipment replacement cycles toward continuous-batch systems.
Radio-frequency identification chips sewn into individual textile items are displacing manual barcode scanning and par-level estimation across acute-care hospital networks. Materials management departments at multi-facility health systems are adopting item-level tracking to reduce linen loss and automate reorder triggers. This visibility is displacing traditional rental contract structures based on poundage estimates with usage-verified pricing that aligns service costs to actual consumption.
EPA effluent limitation guidelines for industrial laundries are tightening phosphorus and nitrogen discharge thresholds in watersheds with impaired water quality. Processing facilities in the Chesapeake Bay and Great Lakes basins face retrofit deadlines for advanced biological treatment systems. Healthcare linen contracts in these catchment areas now specify certified wastewater compliance as a mandatory qualification, filtering out smaller operators lacking capital for environmental upgrades.
Buying committees at consolidated hospital systems are unbundling linen supply from facility management contracts to negotiate directly with specialized providers. This disintermediation strips purchasing leverage from general service contractors and exposes linen specialists to direct price competition on quality tiers. The shift is most visible in the southeastern United States, where hospital acquisition activity has concentrated decision-making at regional corporate offices.
Linen Supply and Management Services Market Segmentation
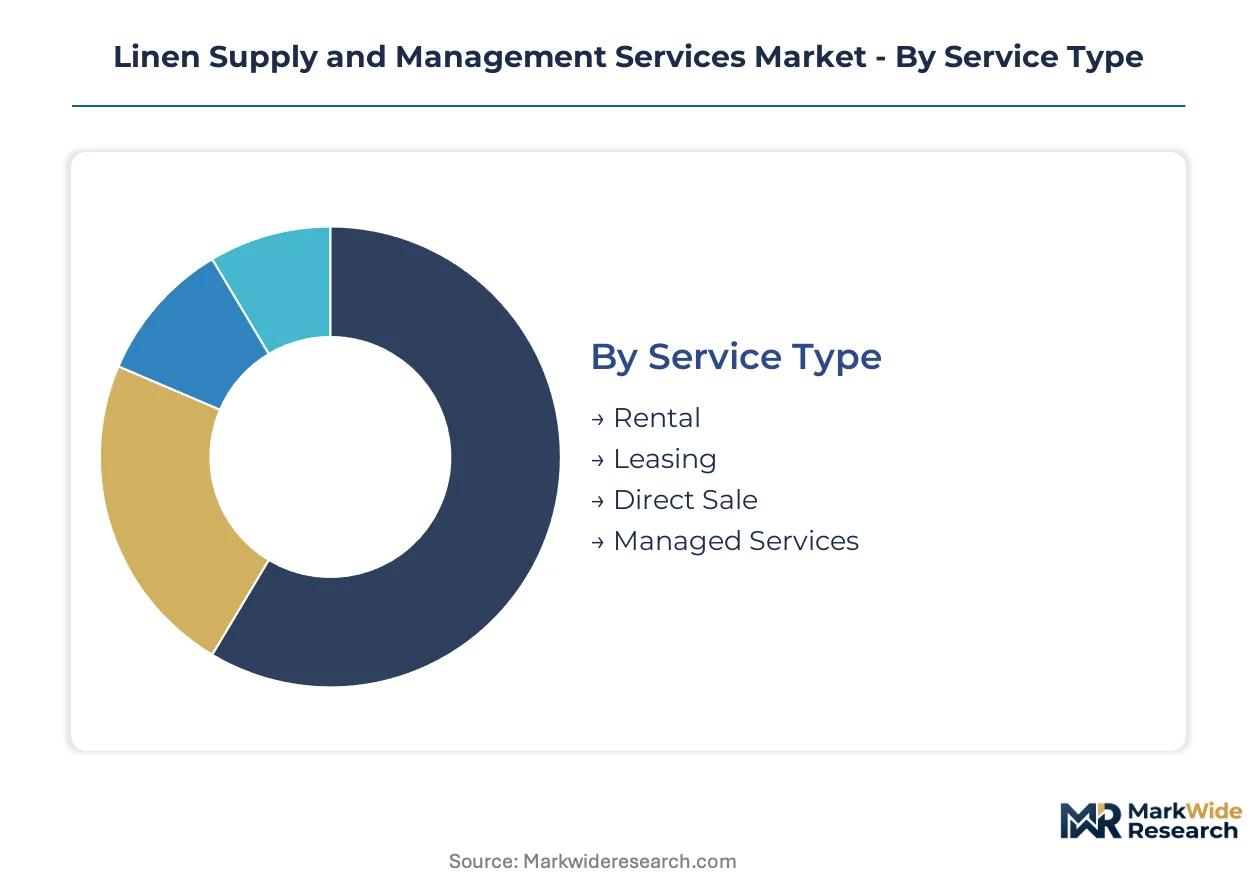
Segmentation in linen supply and management services determines capital allocation, route density economics, and regulatory compliance pathways. Service providers structure operations around delivery frequency, hygiene certification tiers, and end-use concentration to optimize processing network utilization.
Service Type:
Substitution pressure from in-house laundering and disposable alternatives varies sharply across contract structures, with capital-light arrangements facing the strongest competitive threat from single-use products.
- Rental:Full-service contracts absorb textile asset ownership, processing, and replacement cycles. US hospital consolidation drives demand toward national rental agreements with standardized hygienically clean certification across multi-state networks.
- Managed Services:Inventory tracking, par-level optimization, and compliance documentation outsourced while facilities retain textile ownership. Healthcare Facilities Group procurement committees favor this model to maintain brand-specific linen quality without operational burden.
- Leasing:Fixed-term textile asset contracts without processing services. Independent restaurants and boutique hotels use leasing to preserve capital for property renovations.
- Direct Sale:One-time textile procurement with no ongoing service relationship. Industrial laundries and institutional kitchens source direct sale for standardized, high-durability items.
Rental retains volume leadership; managed services holds the steepest expansion curve.
End User:
Cost tier differentiation separates acute-care hospitals requiring barrier-grade surgical linens from budget hospitality operators prioritizing replacement velocity over fabric longevity.
- Healthcare Facilities:Acute-care hospitals, ambulatory surgery centers, and long-term care facilities. Joint Commission audit requirements mandate documented chain-of-custody protocols from soiled collection through hygienically clean delivery.
- Hospitality:Full-service hotels, resorts, and extended-stay properties. Weekly linen exchange programs at apartment-style hotels generate predictable volume contracts with lower delivery frequency costs.
- Restaurants:Fine-dining establishments and institutional foodservice operations. Table linen quality signals brand positioning, driving premium fabric specifications and rapid replacement cycles.
- Industrial:Manufacturing plants, automotive facilities, and cleanroom operations. Flame-resistant and static-dissipative uniform programs require specialized processing equipment and compliance documentation.
Healthcare facilities command the highest service margins; hospitality delivers the most scalable volume base.
Product Type:
Volume concentration in bedding and towels creates route density advantages, while specialized uniform programs generate margin premiums through customization and regulatory compliance requirements.
- Bedding:Sheets, pillowcases, blankets, and mattress pads processed through tunnel washing systems exceeding 71 degrees Celsius. US hospital systems standardize bedding specifications across consolidated networks to simplify procurement.
- Uniforms:Custom-sized garments with logo application, reflective striping, or barrier fabric construction. OSHA bloodborne pathogen standards drive healthcare outsourcing to eliminate staff exposure liability.
- Table Linens:Napkins, tablecloths, and placemats for hospitality and foodservice. High soil loads and starch finishing requirements favor centralized processing over on-premise alternatives.
- Towels:Bath, hand, and surgical towels with distinct absorbency and durability specifications. Extended-stay hospitality contracts emphasize towel longevity to reduce replacement frequency.
Bedding retains volume leadership; uniforms hold the steepest expansion curve.
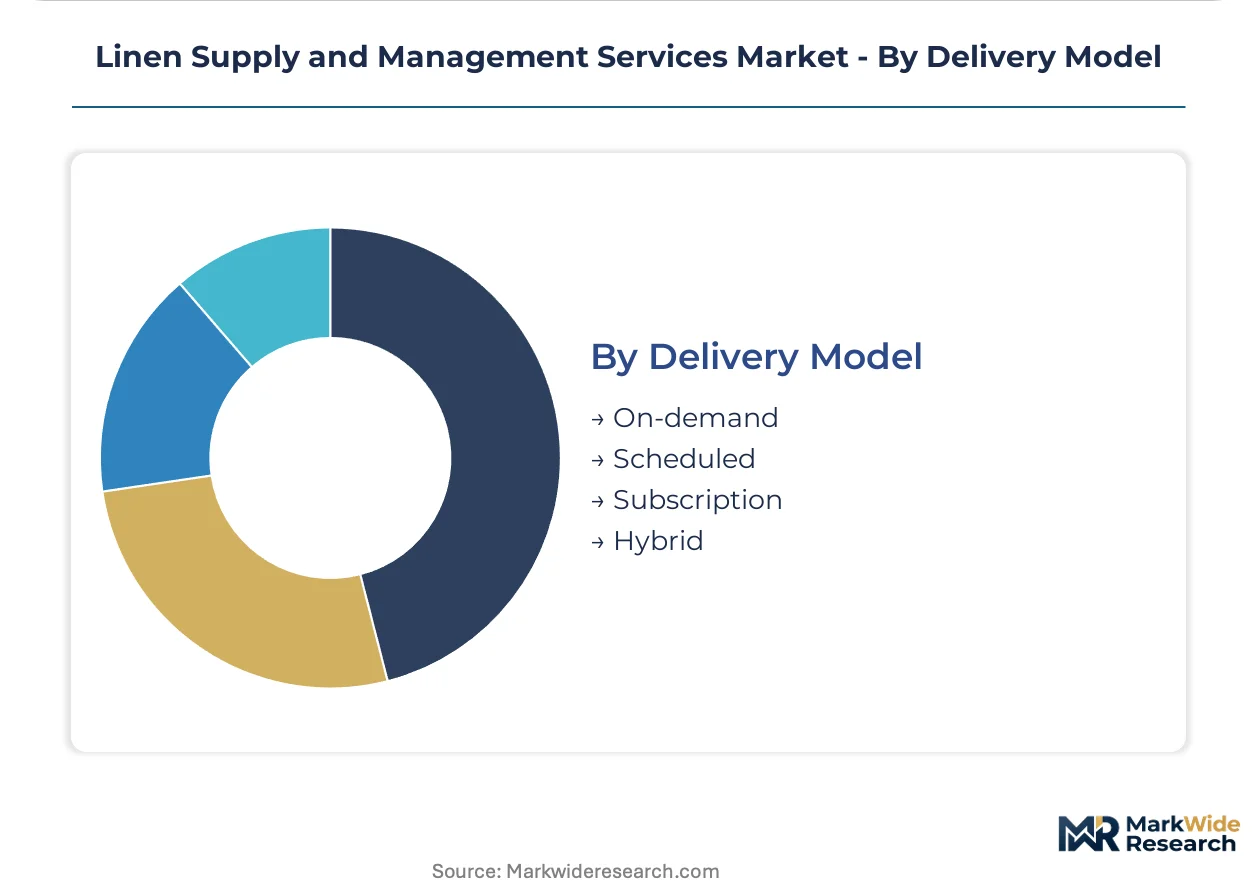
Delivery Model:
Customer type segmentation separates large health systems with predictable par-level requirements from independent operators needing flexibility, shaping fleet deployment and inventory positioning strategies.
- Scheduled:Fixed-route, fixed-frequency delivery with pre-established par levels. National hospital contracts rely on scheduled service to ensure inventory availability for Joint Commission surveys.
- Subscription:Flat-rate pricing for predictable textile consumption with automatic replenishment. Extended-stay hospitality operators favor subscriptions to simplify budgeting and reduce administrative overhead.
- On-demand:Emergency and surge capacity delivery without contractual minimums. Rural hospitals and independent restaurants use on-demand service for seasonal peaks or equipment failures.
- Hybrid:Scheduled base service with on-demand surge options. Regional health systems deploy hybrid models to balance cost predictability with emergency flexibility.
Scheduled service retains volume leadership; subscription models hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where hospital consolidation and EPA discharge mandates squeeze mid-tier operators, while European providers face margin compression from energy cost volatility and REACH chemical compliance burdens.
United States
Hospital system consolidation across the Southeast and Midwest is compressing procurement timelines toward national account contracts. EPA Clean Water Act discharge limits for phosphorus and nitrogen in the Chesapeake Bay and Great Lakes basins force seven-figure wastewater treatment upgrades. Dallas-Fort Worth and Atlanta processing clusters concentrate tunnel washing capacity to serve multi-state health networks.
Germany
Industrial laundries near Stuttgart and Munich process barrier-grade surgical linens for cross-border hospital networks. REACH chemical regulations restrict surfactant formulations used in high-temperature tunnel systems. The Ruhr Valley hosts automated continuous-batch facilities serving automotive uniform programs with ISO-certified hygiene protocols.
France
Elis SA anchors European healthcare linen contracts through processing plants meeting stringent ANSM hygiene requirements. EU Green Deal energy efficiency mandates accelerate heat recovery system retrofits in Lyon and Marseille facilities. The Paris basin concentrates hospitality linen volume from international hotel chains standardizing procurement.
United Kingdom
NHS procurement frameworks favor rental contracts with documented chain-of-custody compliance for Joint Commission-equivalent audits. England's water scarcity regulations in the Southeast force closed-loop recycling investments at Thames Valley processing sites. Manchester and Birmingham industrial laundries specialize in extended-stay hospitality contracts with weekly exchange programs.
Canada
Provincial health authorities in Ontario and British Columbia outsource linen management to eliminate capital tie-up in textile assets. Health Canada guidance on medical device textiles influences barrier fabric selection for surgical programs. Toronto and Vancouver processing clusters serve cross-border hospital networks with harmonized hygiene certification.
Linen Supply and Management Services Market Competitive Landscape
Concentration sits with diversified textile rental conglomerates and vertically integrated hygiene specialists. Three to five national-scale providers control multi-state processing networks in North America, while European competition fragments across country-specific certification regimes. Strategic archetypes include: (1) captive uniform rental networks cross-selling managed linen programs, (2) ISO-certified healthcare specialists with barrier-fabric processing capabilities, and (3) hospitality-focused volume operators optimizing route density. Dominant competitive moves encompass M&A to consolidate regional processing footprints and capacity expansion toward automated tunnel washing systems.
Within the diversified rental conglomerate tier, Cintas Corporation and UniFirst Corporation exemplify scale-driven positioning through captive garment production and cross-segment service bundling. Elis SA occupies a specialist position in European healthcare hygiene certification. ImageFIRST Healthcare Laundry Specialists and Angelica Corporation represent the healthcare-dedicated archetype with processing infrastructure purpose-built for Joint Commission audit requirements. Alsco Inc. and Unitex Textile Rental Services anchor mid-market regional coverage with hybrid service models spanning rental and managed service contracts.
| Leading Market Players |
|---|
| Aramark Corporation |
| Cintas Corporation |
| ImageFIRST Healthcare Laundry Specialists |
| Unitex Textile Rental Services |
| Elis SA |
| Alsco Inc. |
| Angelica Corporation |
| Healthcare Services Group |
| UniFirst Corporation |
| Others |
Supply & Pricing Matrix
Seventy-two-hour par-level replenishment cycles concentrate pricing power with national-scale providers operating multi-plant tunnel washing networks, while regional operators absorb margin compression from EPA-mandated wastewater retrofits. Contract structures reward route density and certification tier, compressing procurement timelines for consolidated hospital systems.
Pricing Analysis
The customization-premium spread between logo-embroidered healthcare uniforms and standard hospitality bedding runs three-to-one, with barrier-grade surgical linens commanding additional certification premiums. Subscription-based rental contracts dominate healthcare procurement, while managed services with usage-verified pricing displace poundage estimates in multi-facility health systems. Price differentiation rests on ISO-certified hygienically clean validation and Joint Commission audit documentation. Pricing pressure stems from natural gas volatility exposing thermal energy costs. Budget hospitality operators exhibit highest price sensitivity; acute-care surgical programs prioritize compliance over cost.
Supply Chain Analysis
Natural gas pipeline capacity through the Permian Basin and Appalachian shale regions anchors thermal energy supply for tunnel washing operations, creating regional cost disparities that reshape processing network economics. Cotton textile production concentrates in India, Pakistan, and Turkey, with barrier fabric sourcing tethered to specialized mills in Germany and the United States. Polyester fiber supply draws from petrochemical complexes along the US Gulf Coast and Chinese manufacturing zones. Single-source vulnerability sits with flame-resistant fabric treatments for industrial uniform programs. Distribution runs through hub-and-spoke logistics networks serving consolidated health system clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID-enabled inventory tracking platforms are displacing manual par-level estimation, creating ecosystem interoperability requirements that favor providers with integrated software-hardware stacks over pure processing competitors.
For Market Incumbents: Shield route density advantages in consolidated health system corridors by locking in multi-year national account contracts before EPA discharge mandates force mid-tier competitor exits. Prioritize heat recovery system retrofits qualifying for US Inflation Reduction Act energy credits. Vertical integration into captive garment production reduces supplier dependency for core uniform categories threatened by Asian textile cost compression.
For New Entrants and Emerging Players: Lead with RFID-enabled compliance documentation targeting independent ambulatory surgery centers and rural hospitals bypassed by national provider networks. Extended-stay hospitality weekly exchange programs offer the most penetrable volume base with lower delivery frequency barriers. Position through managed services contracts that absorb inventory tracking burden without requiring capital-intensive tunnel washing infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital procurement centralization and environmental compliance costs are structurally eliminating sub-scale regional operators. Target acquisition archetypes include ISO-certified healthcare specialists with barrier-fabric processing capabilities in EPA-impaired watersheds. Watch state-level water scarcity mandate expansion as the signal for forced seller dynamics among capital-constrained mid-tier processors.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID Platform Integration | Item-level tracking reduces linen loss while automating Joint Commission compliance documentation for hospital audits. |
| Heat Recovery System Retrofit | Solar thermal and exhaust heat capture installations qualify for federal energy credits that improve facility project returns. |
| Barrier Fabric Certification Investment | FDA-aligned medical device textile validation opens surgical linen contracts with highest margin tiers in acute-care networks. |
| Multi-State Processing Network Expansion | Tunnel washing capacity clustering in Dallas-Fort Worth and Atlanta serves consolidated Southeast health system procurement. |
| Managed Service Contract Launch | Inventory tracking and par-level optimization outsourcing captures facilities seeking operational burden relief without asset transfer. |
Research Methodology
A standing panel of hospital materials management directors, hospitality procurement officers, industrial laundry plant managers, and EPA compliance specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from OSHA bloodborne pathogen guidance documents, EPA Clean Water Act effluent limitation guidelines, Textile Rental Services Association certification protocols, and hospital GPO contract databases. Bottom-up facility capacity modeling triangulated against top-down national account contract value analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled service type segmentation, end-user concentration, product category mix, and delivery frequency tier as primary demand dimensions. CAGRs were derived from processing capacity utilization trajectories and national account contract renewal rates. Forecast inputs included natural gas price band assumptions and state-level water reuse mandate adoption curves.
Underlying assumptions cover EPA enforcement continuity and hospital consolidation velocity, with deviation risk concentrated in energy commodity volatility and textile fiber import tariff shifts. Practitioners should keep alternative scenarios live as state environmental regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Global Industrial Fabric Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Fabric Reversing Machines Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Portable Fabric Canopies Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market