
 Saddle Stitching Machine Market | 2026-2036
Saddle Stitching Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Saddle Stitching Machine Market Analytics
Commercial publishers and packaging converters are rotating toward fully automatic saddle stitching systems as print run lengths shrink and turnaround times compress. Muller Martini leverages its vertical integration into feeder and delivery modules to command premium positioning in high-speed commercial lines. Heidelberg Druckmaschinen AG anchors European demand through its established service network and retrofit capabilities for legacy presses. BOBST competes aggressively in folding carton applications where stitching replaces gluing for recyclable packaging formats.
A saddle stitching machine drives wire through folded signatures at the spine, then clinches the wire flat against the center fold to create booklets, catalogs, or mailers without adhesive curing time. Industrial-grade units process up to 18,000 cycles per hour with automatic signature recognition and reject sorting. Fully automatic machines lead unit shipments as labor costs and throughput requirements push mid-volume printers toward hands-free operation. Electric technology dominates new installations for energy efficiency and programmable setup, while pneumatic systems retain share in heavy-duty textile and leather applications where piercing force demands exceed servo motor torque curves.
CE marking and the EU Machinery Directive govern safety interlocks and emergency stop protocols for European installations, while OSHA lockout/tagout standards shape guard design and maintenance access for US-bound equipment. ISO 12648 provides harmonized safety specifications for printing and binding machinery that manufacturers reference for cross-border certification. Stakeholders must monitor how extended producer responsibility frameworks in France and Germany alter material recovery obligations for worn wire stitching heads and electronic control modules.
Market Dynamics
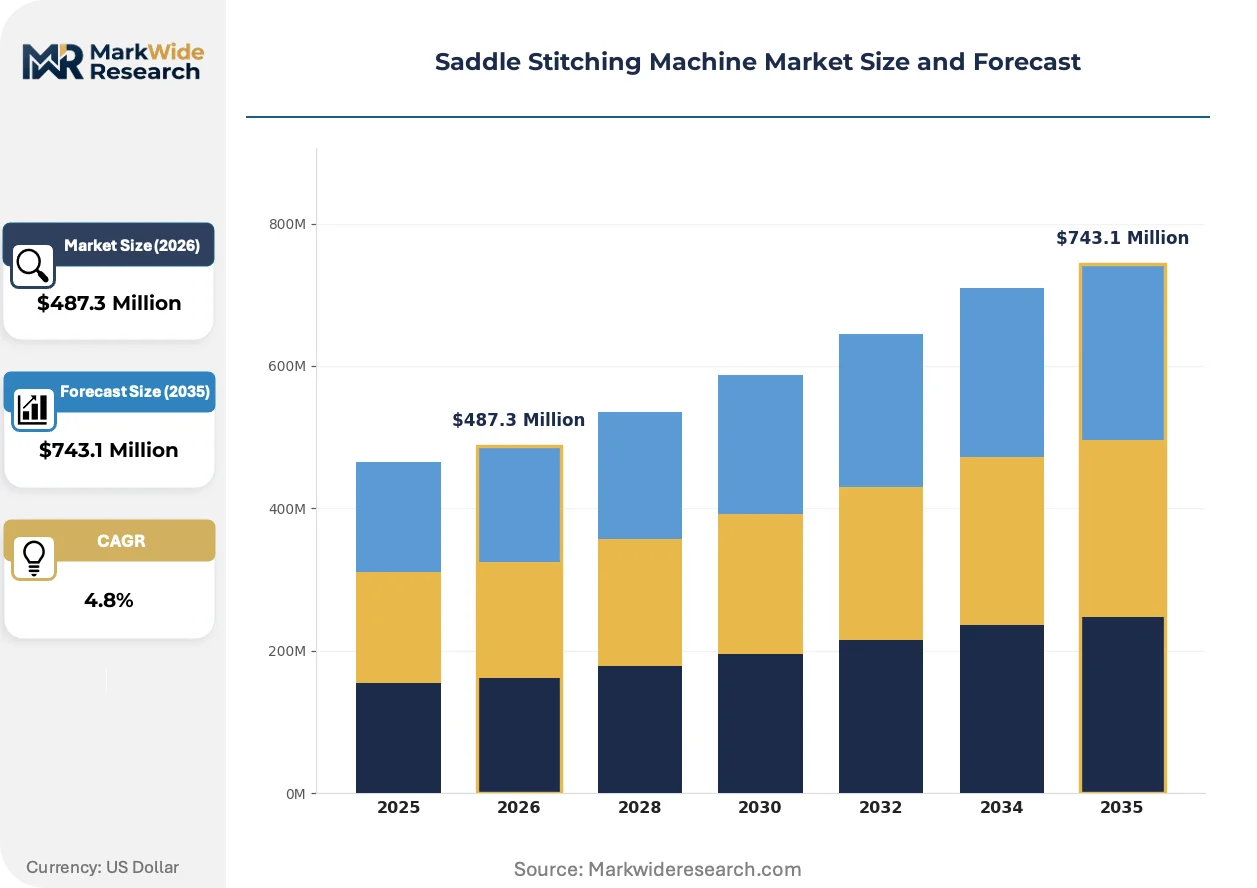
The Saddle Stitching Machine Market is compressing print run economics as automated binding lines replace manual collation, with shorter turnaround demands forcing capital redeployment toward servo-driven, quick-changeover systems.
Growth Catalysts
- REACH compliance in Europe:Tightened material specifications for adhesives and coatings are accelerating replacement cycles for legacy finishing equipment, driving demand for compliant new installations.
- Commercial printing houses:Expansion of automated binding lines to handle shorter print runs is pulling throughput upgrades across mid-volume operations.
- Recyclable packaging formats:Folding carton converters are substituting wire stitching for gluing to meet circular economy mandates, opening incremental capacity demand.
Market Restraints
- Copper and steel wire volatility:Raw material input costs for stitching wire fluctuate with commodity cycles, squeezing margin predictability for equipment financed on fixed-price contracts.
- Precision engineering cluster concentration:Stuttgart and Dresden supply critical high-speed stitching heads, creating geographic supply vulnerability for non-European OEMs.
- Pneumatic system retention:Heavy-duty textile and leather applications where piercing force exceeds servo torque curves lock in legacy technology, fragmenting R&D focus.
Strategic Opportunities
- Extended producer responsibility frameworks:France and Germany are altering material recovery obligations for worn wire stitching heads, creating aftermarket service and remanufacturing revenue pools.
- Electric technology convergence:Servo motor advancement combined with programmable logic controllers is enabling energy-efficient retrofits of pneumatic legacy lines.
- Packaging converter channel:Direct OEM relationships with folding carton specialists bypass traditional distributor markups in North American markets.
Industry Challenges
- ISO 12648 certification timelines:Harmonized safety specifications for printing and binding machinery require extensive third-party validation, delaying product launches by six to twelve months.
- Legacy press integration:Retrofit compatibility with Heidelberg and Muller Martini feeder modules demands proprietary interface engineering, complicating multi-vendor line configurations.
- OSHA lockout/tagout compliance:Guard design and maintenance access modifications for US-bound equipment require dedicated engineering teams, fragmenting product architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saddle Stitching Machine Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Machines, Semi-Automatic Machines, Fully Automatic Machines, Industrial Machines Application: Bookbinding, Leather Goods, Textile, Packaging End User: Manufacturers, Craft Shops, Publishers, Retailers Technology: Electric, Pneumatic, Hydraulic, Mechanical |
| Companies Covered | Muller Martini, Heidelberg Druckmaschinen AG, Kolbus, BOBST, JUKI Corporation, Brother, PFAFF, Seiko Sewing Machine Co. Ltd., Horizon International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saddle Stitching Machine Market Evolving Landscape
Automation architecture is migrating from centralized control cabinets to distributed servo nodes, collapsing setup times and enabling real-time quality feedback loops across binding lines.
Vision-based signature recognition systems are miniaturizing from standalone units to embedded camera arrays integrated directly into stitching heads. Commercial printers with run lengths below five thousand copies are adopting these systems fastest. The technology is miniaturizing quality control infrastructure, allowing smaller footprint lines in urban print centers where real estate costs constrain floor space.
CE marking under the EU Machinery Directive is tightening safety interlock requirements for European installations, mandating redundant emergency stop protocols and documented risk assessments. Manufacturers are redesigning guard systems to accommodate both European and OSHA standards within single product platforms. German precision engineering clusters are responding by pre-certifying modular stitching heads for cross-border deployment.
Service contract unbundling is separating hardware sales from maintenance agreements, with end-users purchasing stitching heads while sourcing technical support through independent service providers. This fragmentation is pressuring OEM margins on aftermarket revenue. The shift is most visible in North American commercial printing, where buyer consolidation into multi-site groups creates procurement leverage for disaggregated sourcing.
Saddle Stitching Machine Market Segmentation
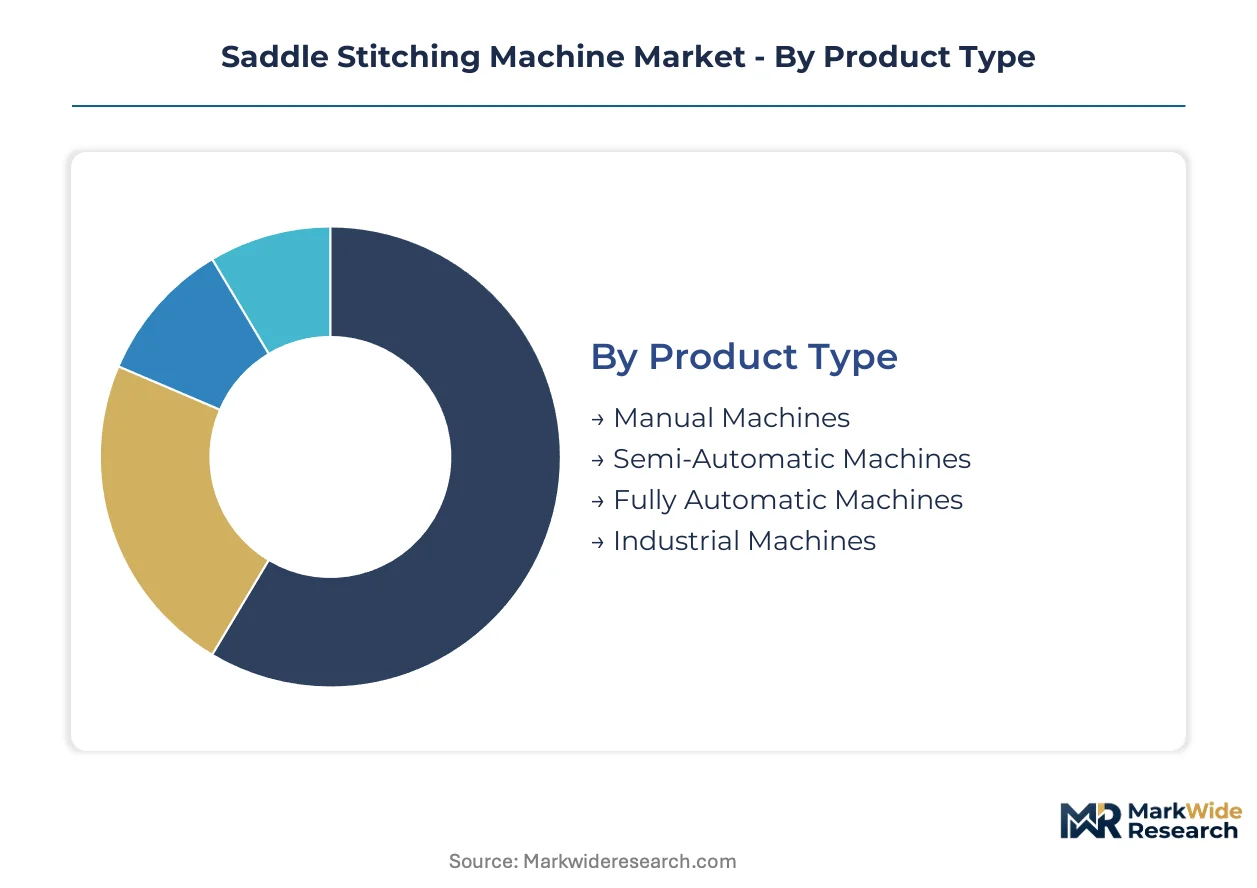
Segmentation in saddle stitching machinery reveals how capital deployment varies across operational scales and binding requirements. Equipment specifications diverge sharply between high-volume commercial lines and artisan production environments, creating distinct procurement channels and service ecosystems.
Product Type:
Channel distribution for saddle stitching equipment splits between distributor networks serving small operations and direct OEM relationships governing industrial-scale installations. Manual and semi-automatic units move through regional equipment dealers with localized technical support, while fully automatic and industrial systems sell direct with embedded service contracts.
- Fully Automatic Machines:These systems integrate automatic signature feeders, wire stitching heads, and delivery modules with programmable logic controllers enabling sub-five-minute changeovers. German precision engineering clusters around Stuttgart supply the high-speed stitching heads that anchor these lines, with demand concentrating among commercial publishers compressing turnaround times on shorter print runs.
- Industrial Machines:Built for continuous operation exceeding 15,000 cycles per hour, these units feature hardened stitching heads and reinforced frames for 24/7 production environments. REACH compliance in Europe is accelerating replacement of legacy pneumatic systems in this tier, as tightened material specifications for coatings and adhesives render older equipment non-compliant.
- Semi-Automatic Machines:Hybrid units requiring manual signature loading while automating wire feed and clinching operations, positioned for mid-volume print shops transitioning from hand-fed systems.
- Manual Machines:Foot-pedal or hand-lever operated units for craft production and prototyping applications, distributed through specialty binding supply channels with minimal technical support requirements.
By volume, semi-automatic machines lead unit shipments. By growth pace, fully automatic systems are expanding most quickly as labor costs and throughput requirements reshape capital allocation.
Application:
Margin structures across applications correlate with finishing complexity and regulatory exposure, with packaging converters commanding premium pricing for recyclable-format compliance while textile applications compete on piercing force specifications.
- Packaging:Folding carton converters deploy wire stitching to replace adhesive bonding in recyclable packaging formats, meeting circular economy mandates from EU Green Deal implementation. BOBST and Heidelberg anchor this segment with integrated lines that combine die-cutting, folding, and stitching in single-pass operations.
- Bookbinding:Commercial publishers drive specification toward quick-changeover servo systems as print runs fragment below 5,000 copies. Muller Martini's vertical integration into feeder modules captures premium positioning here, though legacy pneumatic installations retain substantial installed base.
- Textile:Heavy-duty applications including tarpaulin, canvas, and industrial fabric binding require piercing force exceeding standard servo motor torque curves, preserving pneumatic and hydraulic system demand.
- Leather Goods:Artisan and luxury goods manufacturers utilize specialized stitching heads with adjustable penetration depth for varying material thickness, typically sourcing through craft equipment distributors.
By installed base, bookbinding dominates. By value expansion, packaging is gaining share fastest as sustainability mandates reconfigure converter capital plans.
End User:
Procurement authority and technical sophistication vary dramatically across buyer categories, with consolidated multi-site publishers exercising procurement leverage that fragments OEM aftermarket revenue.
- Publishers:Commercial and educational publishers with centralized procurement functions negotiate enterprise service agreements separate from hardware acquisition, pressuring OEM margins on maintenance contracts.
- Manufacturers:Packaging converters and commercial print houses with dedicated finishing departments specify integrated binding lines as capital projects with multi-year depreciation schedules.
- Craft Shops:Independent binderies and specialty print operations purchase through regional distributors with financing packages and trade-in allowances for equipment upgrades.
- Retailers:In-house print operations at large retail chains for catalog and promotional material production, typically sourcing mid-tier semi-automatic systems with standardized maintenance protocols.
By absolute spend, manufacturers lead capital deployment. By contract fragmentation, publishers are restructuring procurement fastest through unbundled hardware and service sourcing.
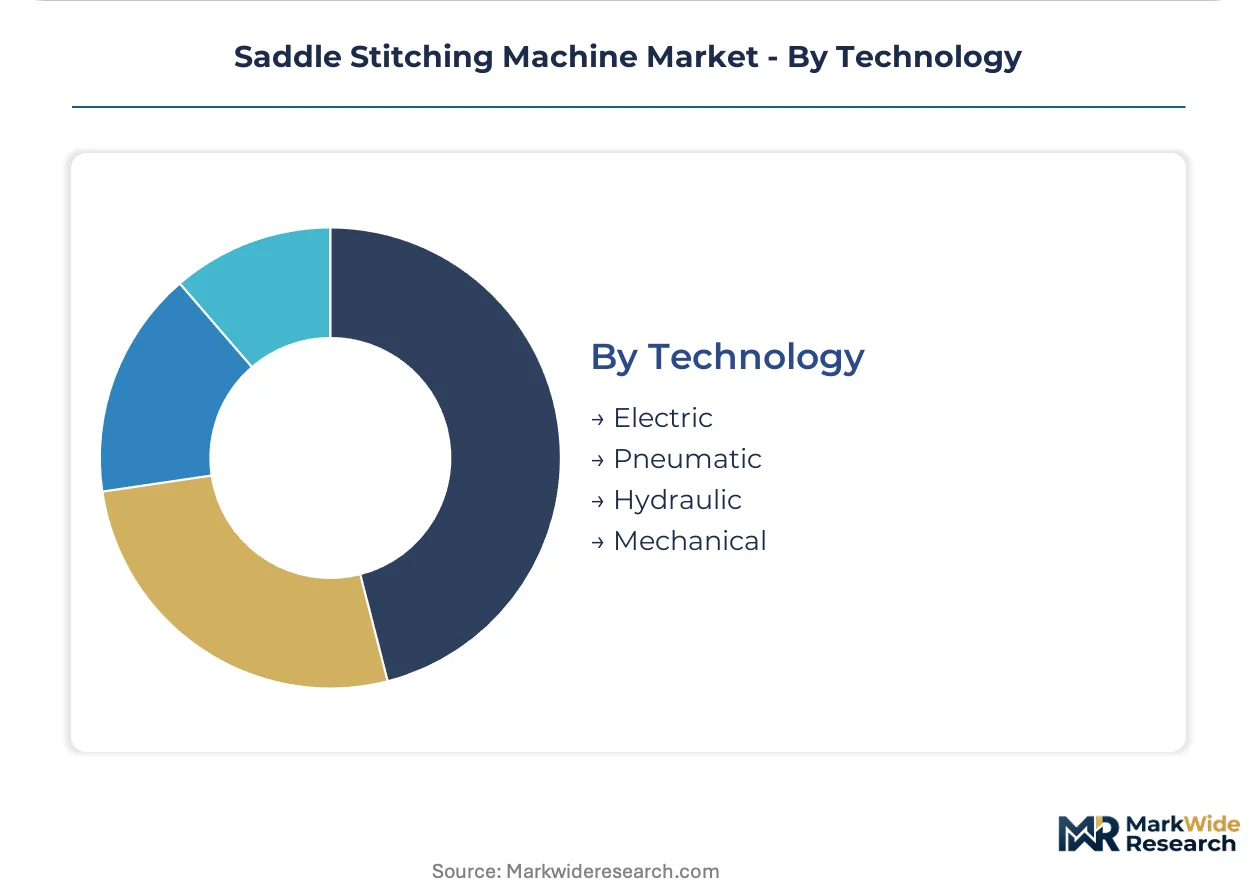
Technology:
Energy efficiency regulations and programmable setup requirements are reconfiguring the technology mix, with electric systems capturing new installation share while legacy pneumatic and hydraulic units retain defendable positions in force-intensive applications.
- Electric:Servo motor-driven stitching heads with programmable penetration depth, clinch pressure, and wire feed timing enable energy-efficient operation with sub-kilowatt power draw during standby. ISO 12648 safety certification timelines for these systems typically extend six to twelve months due to third-party validation requirements for programmable safety interlocks.
- Pneumatic:Compressed air systems delivering piercing force up to 800 Newtons retain installed base in textile and leather applications where material density exceeds electric motor torque specifications. CE marking and OSHA lockout/tagout compliance requirements are fragmenting product architecture for this technology as manufacturers redesign guard systems for dual-standard certification.
- Hydraulic:High-force systems for specialty industrial applications including heavy canvas and reinforced materials, with limited new installation volume concentrated in custom-engineered lines.
- Mechanical:Cam-driven and gear-train systems with fixed operating parameters, retained primarily in legacy installations and developing markets with limited technical support infrastructure.
By new installation share, electric systems lead. By retention in force-intensive niches, pneumatic technology maintains the steepest defensive position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-speed stitching head manufacturing clusters in southwestern Germany, with precision engineering capabilities concentrated around Stuttgart and Dresden supplying binding systems to publishers and packaging converters worldwide.
Germany
Commercial publishers and packaging converters drive specification toward quick-changeover servo systems as print runs fragment below five thousand copies. REACH compliance under ECHA tightens material specifications for adhesives and coatings, accelerating replacement cycles for legacy finishing equipment. Precision engineering clusters around Stuttgart and Dresden supply critical high-speed stitching heads to global OEMs.
United States
Mid-volume commercial print houses expand automated binding lines to handle shorter turnaround times on shrinking print runs. OSHA lockout/tagout standards shape guard design and maintenance access modifications for equipment installations. Buyer consolidation into multi-site publishing groups creates procurement leverage for disaggregated hardware and service sourcing across metropolitan print centers.
China
Domestic packaging converters deploy wire stitching systems to replace adhesive bonding in export-oriented recyclable carton formats. GB standards and MIIT regulations govern machinery safety certification for industrial binding equipment. Manufacturing capacity concentrates in the Yangtze River Delta for mid-tier semi-automatic systems serving regional print operations.
Japan
Specialized industrial applications including heavy textile and canvas binding preserve demand for pneumatic piercing systems exceeding standard servo torque specifications. METI energy efficiency guidelines push electric technology adoption in new commercial installations. Industrial machinery fabricators in the Nagoya-Chubu corridor engineer custom-engineered lines for specialty material processing.
France
Folding carton converters substitute wire stitching for gluing to meet circular economy mandates from EU Green Deal implementation. Extended producer responsibility frameworks alter material recovery obligations for worn wire stitching heads and electronic control modules. Print finishing operations in the Île-de-France region pilot remanufacturing service models for aftermarket revenue capture.
Saddle Stitching Machine Market Competitive Landscape
Concentration sits with vertically integrated European machinery builders and diversified Asian industrial conglomerates. German precision engineering specialists and Swiss packaging equipment manufacturers command premium positioning in high-speed commercial lines. Japanese sewing machinery specialists and Chinese fabricators occupy distinct tiers based on force specification and automation depth. Competitive moves center on retrofit compatibility engineering for legacy press integration and modular pre-certification for cross-border safety standard compliance.
Among German-origin precision engineering specialists, Muller Martini GmbH and Heidelberg Druckmaschinen AG exemplify the vertically integrated archetype controlling feeder and delivery module production. BOBST S.A. represents the Swiss packaging equipment anchor competing in folding carton applications. These three entities occupy positions shaped by proprietary interface ecosystems and established service networks rather than pure hardware specification.
| Leading Market Players |
|---|
| Muller Martini |
| Heidelberg Druckmaschinen AG |
| Kolbus |
| BOBST |
| JUKI Corporation |
| Brother |
| PFAFF |
| Seiko Sewing Machine Co. Ltd. |
| Horizon International |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with German precision engineering clusters lock in supply access for high-speed stitching heads while fixing wire input costs against copper and steel commodity cycles. These arrangements give commercial publishers and packaging converters price visibility across multi-year depreciation schedules, though pneumatic system retention in textile applications fragments procurement leverage.
Pricing Analysis
Volume-discount tiering structures separate enterprise publishers purchasing fully automatic lines from craft shops sourcing manual units through regional distributors. Pricing stratifies across premium servo-driven systems with ISO 12648 pre-certification, standard electric configurations for mid-volume operations, and economy pneumatic units for developing markets. Cost compression in the economy tier is intensifying because Chinese fabricators in the Yangtze River Delta scale semi-automatic production. Publishers with consolidated multi-site procurement exercise lowest price sensitivity, while independent craft shops negotiate trade-in allowances aggressively.
Supply Chain Analysis
Stuttgart-Dresden precision engineering clusters in Germany underwrite global availability of high-speed stitching heads with sub-five-minute changeover capability. Component sourcing draws from Japanese servo motor specialists, Chinese steel wire producers, and Swiss control module fabricators. Single-source vulnerability concentrates in German stitching head manufacturing, where REACH compliance and CE marking requirements create regulatory moats. Distribution runs through direct OEM relationships for industrial-scale installations and regional equipment dealers serving small operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saddle Stitching Machine Market is entering a cyclical recovery phase as REACH-driven replacement cycles in Europe and packaging converter sustainability mandates reactivate capital deployment. Copper and steel wire commodity stabilization supports margin predictability for equipment financed on fixed-price contracts.
For Market Incumbents: Fortify aftermarket revenue streams by unbundling service contracts and establishing remanufacturing operations for worn stitching heads under extended producer responsibility frameworks in France and Germany. Backward integration into feeder module production captures proprietary interface control against emerging Asian competitors, while pre-certifying modular stitching heads for dual CE-OSHA compliance accelerates cross-border deployment timelines.
For New Entrants and Emerging Players: Anchor in the North American packaging converter channel where direct OEM relationships bypass traditional distributor markups and buyer consolidation creates procurement leverage for disaggregated sourcing. Target mid-tier semi-automatic systems for metropolitan print centers with real estate constraints, offering vision-based signature recognition as a retrofit upgrade path rather than integrated premium positioning.
For Investors and Strategic Acquirers: Specialized aftermarket service providers with established technician networks and remanufacturing capabilities represent the most attractive acquisition targets as OEM margins fragment. Long-term viability hinges on circular economy mandate durability across EU member states. Monitor ECHA regulatory enforcement intensity as the primary inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feeder Modules | Proprietary interface control locks in retrofit compatibility with Heidelberg and Muller Martini legacy lines. |
| Remanufacturing Service Launch | Extended producer responsibility frameworks in France and Germany create captive aftermarket revenue pools. |
| Dual-Standard Certification Investment | Simultaneous CE marking and OSHA lockout/tagout compliance collapses product launch delays from twelve to six months. |
| Direct OEM Channel Development | Bypassing distributor markups in North American packaging converter markets captures margin expansion. |
| Vision-Based Retrofit Integration | Embedded camera arrays miniaturize quality control infrastructure for urban print centers with floor space constraints. |
Research Methodology
Cross-validation between primary interviews with finishing department managers at commercial print houses and secondary analysis of ECHA regulatory filings anchors the qualitative findings on REACH compliance impacts. Plant engineers at packaging converters, aftermarket service technicians, and procurement leads at multi-site publishing groups provided operational perspective. Trade data from German mechanical engineering associations, SEC filings from diversified industrial conglomerates, and customs records for stitching wire imports furnished quantitative grounding. Bottom-up unit shipment estimates triangulate against top-down capital expenditure patterns across the analysis window.
Sensitivity analysis on copper and steel wire price trajectories shapes the forecast framework across product type, application, technology, and end-user segments. The modeling period incorporates electric technology convergence in commercial printing, pneumatic system retention in textile applications, and packaging converter channel dynamics. CAGRs derive from installed base replacement cycles, sustainability mandate implementation timelines, and servo motor advancement curves. Wire commodity volatility and precision engineering cluster capacity constraints represent key forecast inputs.
Material uncertainties — ECHA regulatory enforcement intensity, extended producer responsibility framework expansion, and copper-steel commodity cycles — sit outside the modeled envelope. Forecasts reflect assumptions on REACH compliance acceleration and circular economy mandate durability. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and OSHA standard revision schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market
Textile Machinery and Equipment
Braiding Machine Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market