
 Gel Dryer Market | 2026-2036
Gel Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Dryer Market Foresight
Buyer concentration among professional nail technician channels is realigning procurement volumes toward salon chains and franchise networks. Bio-Rad Laboratories leverages its laboratory equipment heritage to compete in adjacent professional beauty segments. Cleaver Scientific specializes in compact benchtop designs that anchor its position in European training institutes. Major Science controls distribution through direct-to-salon platforms in East Asian markets.
A gel dryer is an electro-mechanical device that emits ultraviolet or light-emitting diode radiation to polymerize photoinitiator-containing nail coatings, typically operating at wavelengths between 365 and 405 nanometers with timer-controlled exposure cycles. Its primary commercial purpose is to harden gel polish layers in cosmetic service settings within sixty to one hundred twenty seconds per coat. LED gel dryer units command premium placement in professional channels where throughput and energy efficiency determine equipment selection, while portable gel dryer formats are gaining traction among home enthusiasts seeking salon-equivalent results. Conventional UV lamp technology retains residual share in budget-sensitive beauty institutes where capital replacement cycles extend beyond five years.
FDA oversees radiation-emitting device safety classifications for UV and LED gel dryers marketed in the United States, requiring compliance reports that shape product labeling and exposure limit claims. ECHA REACH restrictions on mercury content are accelerating LED lamp substitution across European professional supply chains. South Korea's MFDS maintains electromagnetic compatibility standards that influence import certification timelines for dual light source models. Stakeholders must monitor divergence between regional photobiological safety thresholds and emerging state-level salon ventilation mandates that could reshape equipment placement requirements.
Market Dynamics
LED wavelength migration from 365nm to 405nm is compressing cure times and forcing equipment replacement cycles across professional nail service channels. This photoinitiator chemistry shift is reconfiguring supplier relationships and procurement specifications simultaneously.
Growth Catalysts
- EU RoHS mercury restrictions:The ban on mercury-containing UV lamps is mandating LED conversion across European professional supply chains. Salon operators in Germany and France are accelerating equipment refresh timelines to maintain compliance.
- Metropolitan salon clustering:Nail technician density in Seoul, Los Angeles, and London is creating concentrated demand nodes. Equipment manufacturers are deploying direct-to-salon distribution platforms to capture these volume pools.
- Photoinitiator formulation advances:New gel polish chemistries optimized for 405nm LED output are reducing cure times to forty-five seconds per coat. Professional channels are prioritizing throughput gains over capital preservation.
Market Restraints
- LED chip supply concentration:High-efficiency 405nm diode production centers on East Asian semiconductor foundries. Equipment assemblers face input cost volatility and allocation constraints during demand surges.
- Legacy UV lamp installed base:Budget-sensitive beauty institutes operate mercury-lamp equipment with replacement cycles exceeding seven years. Capital inertia delays technology migration in price-conscious segments.
- Photobiological safety compliance costs:FDA radiation-emitting device classifications require extensive testing documentation. Small equipment manufacturers face disproportionate regulatory burden relative to revenue scale.
Strategic Opportunities
- Home enthusiast channel expansion:Portable gel dryer formats are penetrating consumer markets in the United States and Germany. E-commerce platforms are enabling direct brand relationships previously restricted to professional distributors.
- South Korean MFDS electromagnetic compatibility certification:Streamlined import pathways for dual light source models are accelerating market entry timelines. First-mover advantage is consolidating among compliant suppliers.
- Salon chain procurement centralization:Franchise networks are consolidating equipment purchasing across fifty-plus location footprints. Volume contracting is displacing individual salon discretionary procurement.
Industry Challenges
- Technician training on multi-wavelength equipment:Nail professionals require instruction on optimal exposure settings across 365nm and 405nm outputs. Certification program development lags hardware deployment.
- Ventilation mandate compliance integration:Emerging state-level salon air quality regulations in California and New York are reshaping equipment placement requirements. Manufacturers must redesign housing configurations without compromising optical performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Dryer Market |
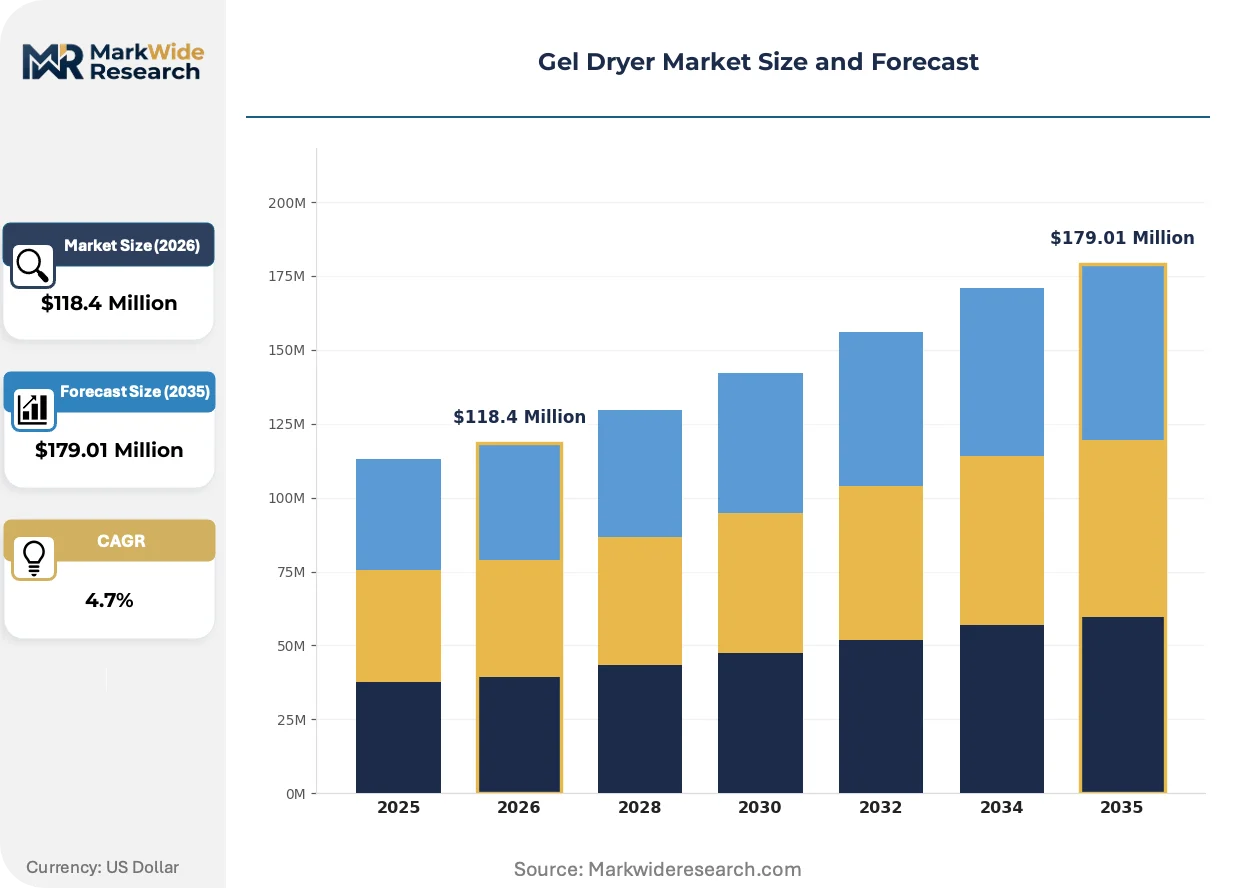
| Market Size in 2026 | $118.4 Million |
| Market Size in 2035 | $179.01 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: UV Gel Dryer, LED Gel Dryer, Portable Gel Dryer, Conventional Gel Dryer Application: Salon Use, Home Use, Spa Centers, Nail Art Studios, Beauty Institutes Technology: LED Lamp, UV Lamp, Dual Light Source, LCD Display End User: Professional Nail Technicians, Home Enthusiasts, Cosmetic Retailers, Nail Salons |
| Companies Covered | Bio-Rad Laboratories, Cleaver Scientific, Labconco, Harvard Bioscience, Major Science, Consort bvba, BIOTEK ENGINEERS, Fisher Biotec, Hoefer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Dryer Market Shifts & Advancements
Wavelength-optimized LED arrays are compressing service delivery times while regulatory pressure on mercury content is eliminating legacy technology pathways. Equipment form factors are simultaneously shrinking for portability and expanding for salon throughput.
Dual-chip LED modules operating at 365nm and 405nm simultaneously are electrifying professional channel equipment specifications. Nail salon chains in Seoul and Los Angeles are adopting these systems to accommodate legacy and next-generation gel polish formulations on single platforms. The technology is compressing equipment replacement decisions by unifying previously separate lamp inventories.
ECHA REACH Annex XVII mercury restrictions are eliminating UV lamp import pathways into European professional supply chains. Equipment distributors are liquidating remaining mercury-lamp inventory through secondary markets while redirecting procurement toward LED-only catalogs. German salon supply cooperatives are negotiating collective LED conversion financing to smooth capital transition.
Salon chain procurement officers are consolidating vendor relationships into single-source equipment contracts with preventive maintenance riders. Independent distributors are losing share to manufacturer-direct platforms that bundle training certification with hardware shipments. This concentration is most visible in United States franchise networks operating standardized service protocols across multi-state footprints.
Gel Dryer Market Segmentation
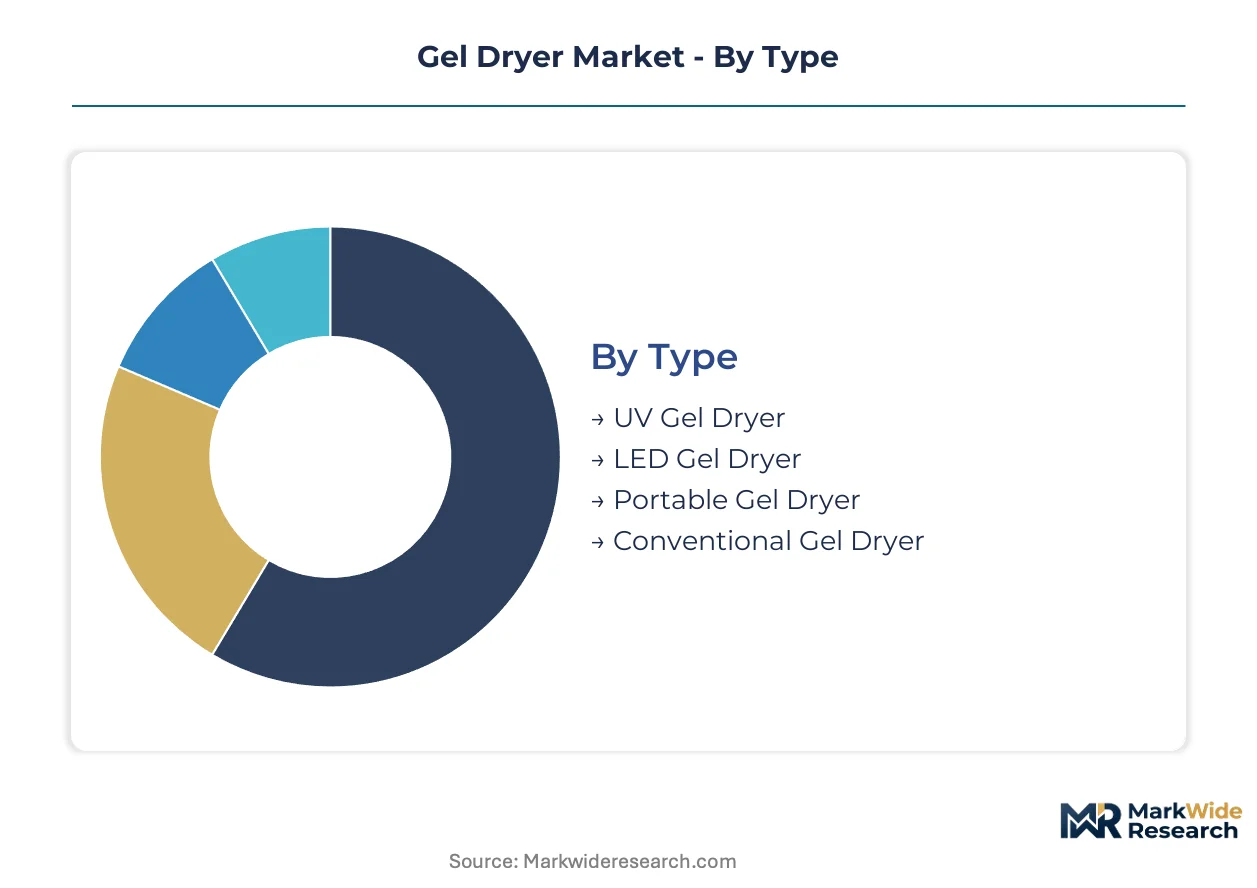
Equipment procurement patterns across gel dryer channels diverge sharply by technical specification, usage intensity, and regulatory exposure. Segmentation reveals how wavelength technology and end-user professionalization reshape vendor priorities and distribution economics.
Type:
Cost tier separates buyers between capital-preservation instincts and throughput-maximization strategies.
- UV Gel Dryer:Mercury-vapor lamp architecture emits broadband ultraviolet radiation across 320-400nm wavelengths. Budget-conscious beauty institutes in Germany and France extend replacement cycles beyond seven years to defer LED conversion capital outlays.
- LED Gel Dryer:Narrow-spectrum diode arrays concentrate output at 365nm or 405nm with instant-on capability and 50,000-hour operational lifespans. Professional nail salon chains in Seoul and Los Angeles prioritize forty-five-second cure times to maximize station turnover.
- Portable Gel Dryer:Battery-powered compact formats target home enthusiasts seeking salon-equivalent results without fixed installation requirements.
- Conventional Gel Dryer:Legacy bulb-based designs persist in secondary markets and training environments where optical precision demands remain minimal.
Volume sits with LED Gel Dryer; growth tilts toward Portable Gel Dryer.
Application:
Usage intensity and service protocol standardization determine equipment durability specifications and warranty expectations.
- Salon Use:High-throughput commercial environments demand continuous-duty cycle ratings and modular lamp replacement architectures. Metropolitan clustering in London and New York creates concentrated procurement nodes where franchise networks negotiate preventive maintenance riders.
- Home Use:Consumer-grade formats prioritize plug-and-play simplicity over professional calibration controls. E-commerce platforms in the United States and Germany enable direct manufacturer relationships that bypass traditional distributor markups.
- Spa Centers:Wellness-integrated service models require whisper-quiet operation and aesthetic housing designs that complement ambient environments.
- Nail Art Studios:Precision-focused operations demand uniform irradiance distribution for intricate multi-layer gel applications.
- Beauty Institutes:Educational settings balance cost minimization against curriculum requirements for exposure to multiple technology generations.
Procurement concentrates in Salon Use; Home Use climbs the fastest as consumer sophistication deepens.
Technology:
Photoinitiator chemistry compatibility and regulatory compliance timelines reconfigure supplier relationships across professional supply chains.
- LED Lamp:Solid-state semiconductor emitters eliminate warm-up latency and mercury disposal liabilities. ECHA REACH Annex XVII restrictions are mandating wholesale substitution across European professional channels.
- UV Lamp:Mercury-dependent broadband sources face accelerating obsolescence as RoHS compliance deadlines approach. Remaining inventory liquidates through secondary markets in price-sensitive segments.
- Dual Light Source:Simultaneous 365nm and 405nm output accommodates legacy and next-generation gel polish formulations on single platforms. South Korea's MFDS electromagnetic compatibility certification streamlines import pathways for compliant suppliers.
- LCD Display:Digital timer interfaces and preset cure programs reduce technician training burden in high-turnover salon environments.
Deployment favors Dual Light Source; LED Lamp gains share fastest as formulation chemistry standardizes.
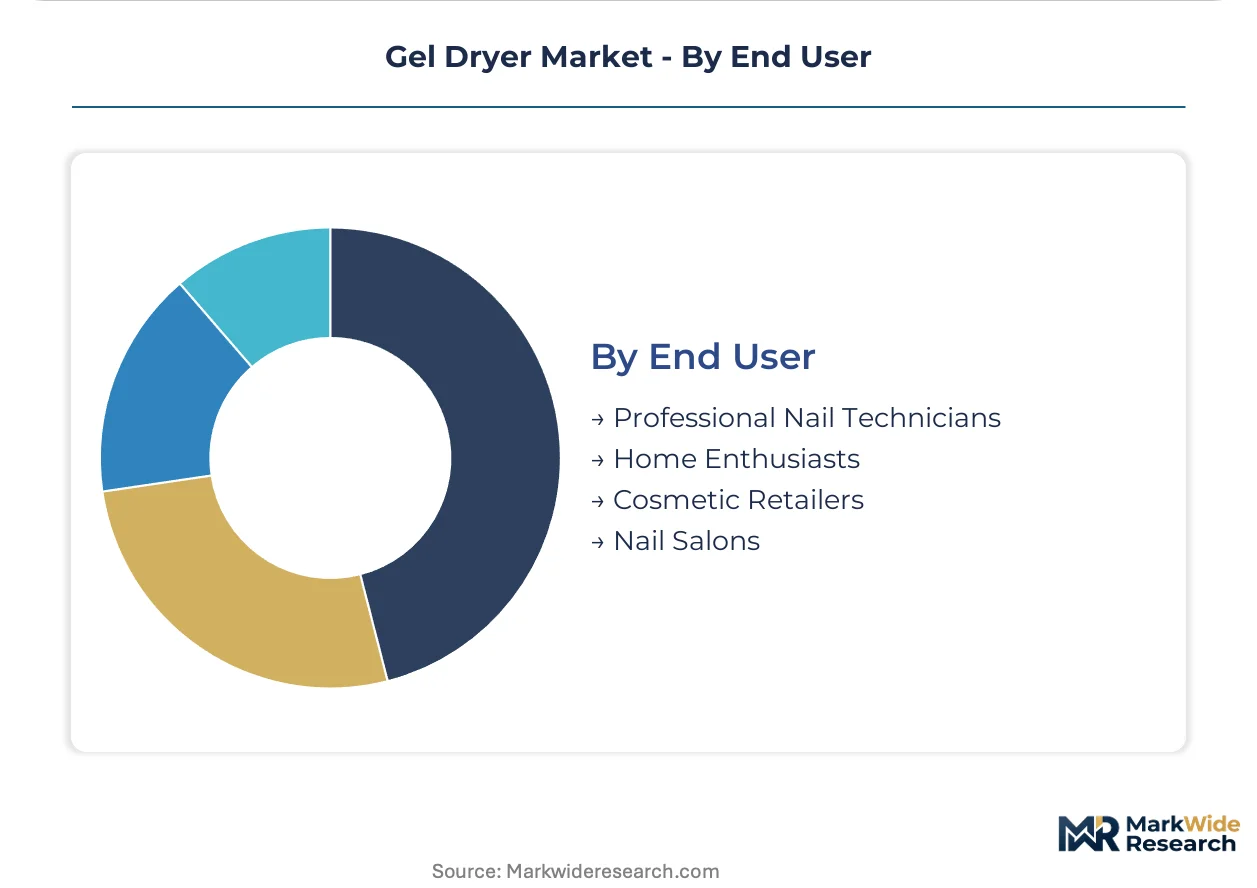
End User:
Technical proficiency and volume scale separate buyers between standardized equipment protocols and discretionary feature selection.
- Professional Nail Technicians:Individual practitioners prioritize reliability and manufacturer-direct support relationships. Certification program bundling influences hardware selection in competitive labor markets.
- Home Enthusiasts:Consumer segments respond to social media-driven brand awareness and portable form factor innovation. Direct-to-consumer platforms capture margin previously allocated to distributor networks.
- Cosmetic Retailers:Multi-category beauty suppliers require cross-merchandising compatibility and minimal staff training overhead for in-store demonstration units.
- Nail Salons:Franchise and independent operators consolidate vendor relationships into single-source contracts with volume pricing tiers and standardized service protocols across multi-location footprints.
Revenue concentrates with Nail Salons; expansion tilts toward Home Enthusiasts as consumer-grade performance converges with professional specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional nail technician channels concentrate procurement volumes in metropolitan clusters across three continents, with regulatory pressure on mercury-containing equipment accelerating technology substitution timelines in major commercial markets.
United States
FDA radiation-emitting device classifications govern UV and LED gel dryer safety labeling and exposure limit claims for equipment marketed domestically. Nail salon chains in Los Angeles negotiate centralized procurement contracts across multi-state franchise footprints. Metropolitan clustering in New York creates concentrated demand nodes where volume contracting displaces individual salon discretionary purchasing.
Germany
ECHA REACH Annex XVII mercury restrictions mandate LED conversion across professional supply chains, compressing equipment refresh cycles. Salon supply cooperatives negotiate collective LED conversion financing to smooth capital transitions. Equipment distributors in Berlin and Munich liquidate remaining mercury-lamp inventory through secondary markets while redirecting procurement toward LED-only catalogs.
South Korea
MFDS electromagnetic compatibility standards influence import certification timelines for dual light source models entering the market. Nail technician density in Seoul creates concentrated demand nodes where equipment manufacturers deploy direct-to-salon distribution platforms. Domestic suppliers leverage streamlined regulatory pathways to consolidate first-mover advantage in compliant dual-wavelength systems.
United Kingdom
EU RoHS compliance requirements on mercury-containing UV lamps redirect procurement specifications toward LED-only equipment in professional channels. Nail salon clustering in London generates volume pools where franchise networks standardize service protocols across multi-location operations. Training institutes in Manchester and Birmingham balance cost minimization against curriculum requirements for exposure to multiple technology generations.
France
ECHA REACH restrictions accelerate LED lamp substitution across European professional supply chains, eliminating legacy import pathways. Beauty institutes in Paris extend replacement cycles on budget-sensitive equipment while metropolitan salons prioritize throughput-maximizing LED systems. Regional supply cooperatives coordinate collective procurement to capture volume pricing tiers from manufacturer-direct platforms.
Gel Dryer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent professional beauty and laboratory equipment segments with specialized form factors. The vendor base spans laboratory equipment heritage brands, compact design specialists, and regional distribution platforms with direct-to-salon capabilities. Three archetypes dominate: heritage laboratory equipment suppliers repurposing technical credibility, compact-format specialists targeting training and portable channels, and East Asian distribution platforms controlling import certification pathways. Competitive moves concentrate on technology licensing for dual-wavelength modules and preventive maintenance bundling to secure multi-year salon chain contracts.
Within the heritage laboratory tier, Bio-Rad Laboratories leverages its equipment manufacturing background to compete across adjacent professional segments. Cleaver Scientific, a compact-format specialist, anchors its market position through benchtop designs targeting European training institutes. Major Science occupies the distribution-platform archetype, controlling direct-to-salon channels in East Asian markets where MFDS certification creates regulatory moats.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Cleaver Scientific |
| Labconco |
| Harvard Bioscience |
| Major Science |
| Consort bvba |
| BIOTEK ENGINEERS |
| Fisher Biotec |
| Hoefer |
| Others |
Supply & Pricing Matrix
Backward integration into 405nm LED diode sourcing anchors competitive positioning for equipment assemblers facing East Asian semiconductor foundry concentration. Captive supply relationships with South Korean and Taiwanese chip manufacturers simultaneously secure allocation priority during demand surges and compress input cost volatility for tier-one gel dryer producers.
Pricing Analysis
Volume concentrates with LED Gel Dryer units while margins favor Dual Light Source systems commanding premium placement. Pricing stratifies across premium, standard, and economy tiers where certification grade and after-sales service bundling drive differentiation. Cost compression in economy-tier UV equipment is intensifying because mercury-lamp inventory liquidation accelerates through secondary markets. Budget-sensitive beauty institutes exhibit highest price sensitivity; franchise networks with preventive maintenance riders demonstrate lowest sensitivity.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Zhejiang provinces are compressing assembly capacity expansion timelines for portable gel dryer formats. High-efficiency 405nm diode production centers on South Korean and Taiwanese foundries; equipment housings and optical-grade plastics draw from Chinese injection molding clusters. Single-source vulnerability in LED chip allocation creates exposure during demand surges. Distribution runs through manufacturer-direct platforms consolidating share from independent salon supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gel Dryer Market sits in a technology-transition phase where 405nm LED systems displace mercury-containing UV lamps across professional channels. This wavelength migration is compressing equipment replacement cycles and reconfiguring procurement specifications simultaneously.
For Market Incumbents: Lock in multi-year preventive maintenance contracts with franchise networks to secure recurring revenue streams against emerging compact-format specialists. Deepen backward integration into LED diode sourcing to defend margin position against East Asian semiconductor allocation constraints. Prioritize MFDS electromagnetic compatibility certification investment to maintain first-mover advantage in South Korean direct-to-salon channels.
For New Entrants and Emerging Players: ECHA REACH Annex XVII mercury restrictions in Europe open a window for LED-only equipment catalogs displacing legacy UV distributor relationships. Target German salon supply cooperatives seeking collective LED conversion financing as the most penetrable buyer archetype. Pursue e-commerce direct-to-consumer platforms in the United States and Germany for home enthusiast segment entry.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by laboratory equipment heritage brands seeking adjacent professional beauty segment expansion. Five-to-ten year viability hinges on dual-wavelength technology licensing portfolios and regulatory compliance infrastructure. Watch LED chip supply allocation volatility as the inflection indicator for equipment assembler margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Wavelength Technology Licensing | Unified 365nm and 405nm output consolidates previously separate lamp inventories for salon chains. |
| Preventive Maintenance Contract Bundling | Multi-year service riders secure recurring revenue and displace independent distributor relationships. |
| MFDS Certification Investment | Streamlined South Korean import pathways accelerate market entry timelines for compliant suppliers. |
| Direct-to-Salon Distribution Platform | Manufacturer-direct relationships capture margin previously allocated to professional supply cooperatives. |
| Home Enthusiast E-Commerce Launch | Portable format penetration enables direct brand relationships bypassing traditional distributor markups. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with salon chain procurement officers, nail technician training institute directors, and professional beauty supply distributors validated demand patterns. FDA radiation-emitting device classification databases, ECHA REACH restriction notices, and South Korean MFDS electromagnetic compatibility filings supplemented equipment shipment tracking. Bottom-up equipment unit estimates triangulated against top-down professional nail service channel revenue analysis.
Granularity-level modeling deployed wavelength technology, end-user professionalization tier, and regional regulatory cluster as primary segmentation dimensions across the analysis window. CAGRs derived from equipment replacement cycle compression rates and photoinitiator chemistry migration timelines. Forecast inputs incorporated LED chip supply allocation constraints and salon chain procurement centralization trajectories without year-specific anchoring.
Caveats apply where LED semiconductor foundry capacity expansion or state-level salon ventilation mandate implementation could materially shift the outlook. Forecasts reflect assumptions on wavelength standardization velocity and franchise network contract consolidation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Cloth Measuring Machine Market