
 Industrial Sewing Machines Market | 2026-2036
Industrial Sewing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Sewing Machines Market Analysis
Multi-source component procurement is pivoting toward vertically integrated supply chains as lead times for servo motors and precision castings destabilize. Juki Corp. leverages captive manufacturing in Japan to sustain delivery reliability for high-speed lockstitch platforms. Brother Industries Ltd. anchors its position through dense distribution networks across Southeast Asian garment hubs. Durkopp Adler specializes in long-arm cylinder-bed configurations for technical textile producers.
An industrial sewing machine is a motorized, mechanically or electronically governed stitching apparatus engineered for continuous operation at speeds exceeding 4,000 stitches per minute, built with reinforced needle bars, feed mechanisms, and industrial-grade motors to process heavy-duty materials across production cycles. Flat-bed configurations dominate volume sales for standard apparel assembly, while cylinder-bed units command premium positioning in leather goods and automotive upholstery where curved seam access proves critical. Electronic technology segments are displacing manual and semi-automatic equipment as manufacturers prioritize programmable stitch patterns and real-time tension monitoring.
FCC electromagnetic compatibility standards govern electronic control module certification for machines sold in the United States, while REACH chemical restrictions in Europe limit certain lubricants and surface treatments used in casting production. China's GB standards and MIIT equipment safety directives shape import requirements and domestic manufacturing protocols. ISO 4915 stitch classification standards provide the technical baseline for cross-border quality arbitration. Stakeholders must monitor how dual carbon goals in China and extended producer responsibility frameworks in Europe will reshape material sourcing and end-of-life equipment recovery obligations.
Market Dynamics
Electronic control systems are compressing replacement cycles as REACH chemical compliance in Europe forces solvent reduction across casting and lubrication operations. Servo motor integration now determines competitive positioning between Japanese captive manufacturers and distributed Asian assemblers.
Growth Catalysts
- Automotive upholstery expansion:Synthetic fabric assemblies for electric vehicle interiors are requiring specialized long-arm cylinder-bed configurations. Tier-1 seating suppliers in Vietnam's export zones are expanding machine fleets to capture contract manufacturing volumes.
- REACH solvent restrictions:European chemical compliance mandates are accelerating electronic control module adoption to eliminate high-VOC lubricants from production floors. Casting suppliers are reformulating surface treatments to meet ECHA substance limitations.
- Flat-bed standardization:Volume apparel assembly in Bangladesh and Cambodia is consolidating around programmable lockstitch platforms with real-time tension monitoring. Factory automation consultants are specifying ISO 4915 stitch classification as a procurement baseline.
Market Restraints
- Precision casting supply concentration:Japanese and German foundries control critical servo motor housing production. Lead time volatility for these components is destabilizing assembly schedules for mid-tier equipment manufacturers.
- Copper and rare earth input costs:Permanent magnet materials for high-torque motors face price pressure from mining concentration in specific geographies. Machine OEMs lack hedging mechanisms against these commodity swings.
- Manual-semi-automatic substitution ceiling:Low-complexity garment operations in frontier markets retain cost advantages with mechanically governed equipment. Electronic premium pricing fails to amortize across short production runs.
Strategic Opportunities
- Technical textile penetration:Medical and aerospace composite stitching requires specialized cylinder-bed configurations with extended throat depth. Equipment specialists can capture margin premiums absent in standard apparel segments.
- EU Green Deal remanufacturing:Extended producer responsibility frameworks are creating certified refurbishment channels for end-of-life electronic modules. Service revenue models are displacing pure equipment sales in German and French markets.
- Industrial IoT convergence:Stitch-level data analytics combined with predictive maintenance algorithms are enabling outcome-based service contracts. Vietnamese and Indonesian factory groups are piloting subscription pricing for uptime guarantees.
Industry Challenges
- Mechatronics technician scarcity:Servo calibration and electronic control troubleshooting require skills absent in legacy mechanical repair networks. Training program development lags equipment complexity advances.
- FCC certification timelines:Electromagnetic compatibility testing for US-bound electronic modules extends product launch schedules. Smaller manufacturers lack dedicated regulatory affairs capacity to parallel-track approvals.
- Legacy mechanical integration:Hybrid production floors combining electronic and mechanical equipment create maintenance protocol fragmentation. Factory managers face operational complexity without unified monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Sewing Machines Market |
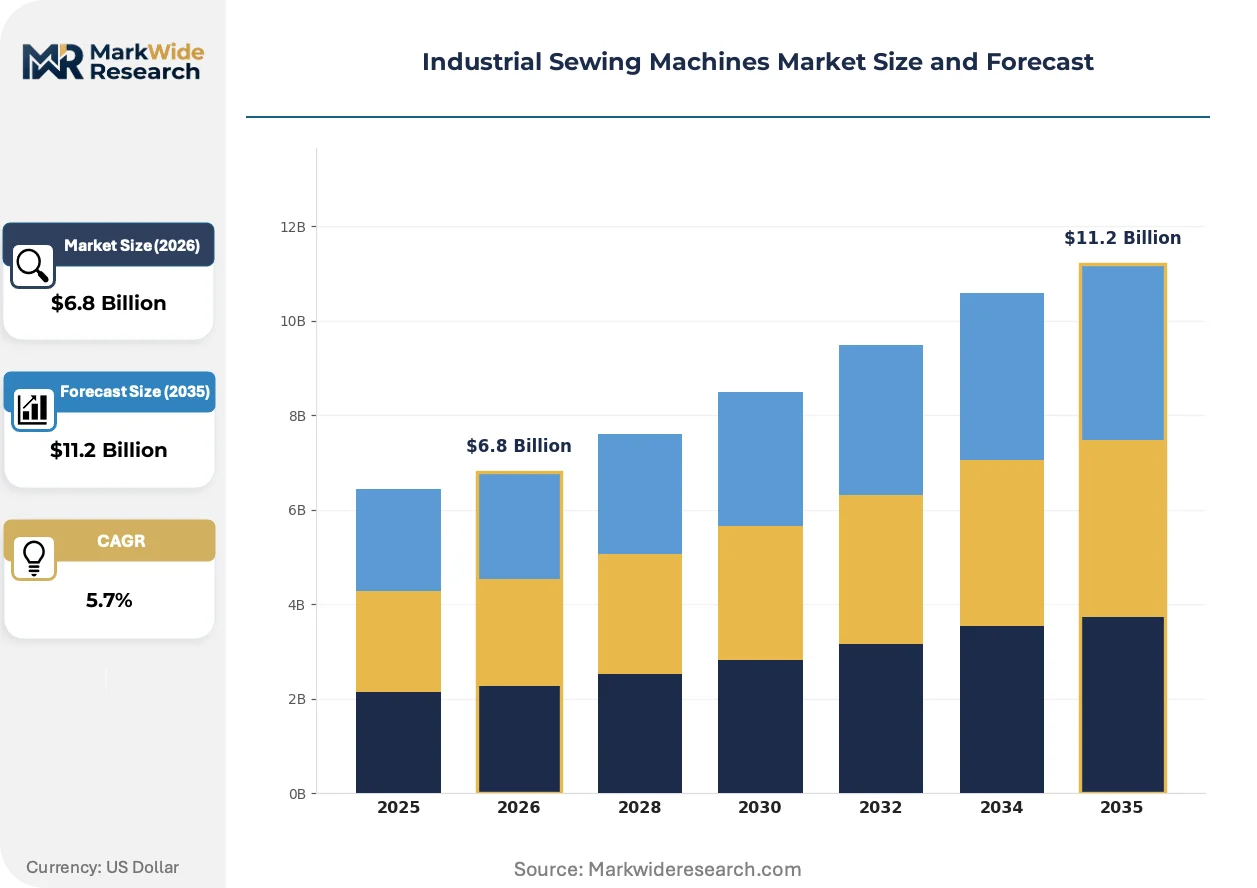
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bed, Cylinder Bed, Overlock, Coverstitch End User: Apparel Manufacturers, Automotive Industry, Upholstery Services, Marine Applications Technology: Manual, Computerized, Electronic, Semi-Automatic Application: Clothing Production, Leather Goods, Home Textiles, Technical Textiles |
| Companies Covered | Pegasus Sewing Machine Mfg, Zoje Sewing Machine Co. Ltd., Juki Corp., Bernina International AG, Durkopp Adler, Brother Industries Ltd., Jack Sewing Machine Co. Ltd., Seiko Sewing Machine Co., Ltd., Yamato Sewing Machine Mfg Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Sewing Machines Market Emerging Trajectories
Real-time stitch analytics and predictive maintenance algorithms are compressing equipment replacement cycles while opening subscription revenue models. Regulatory chemical restrictions and electromagnetic compatibility mandates are reshaping control module architecture.
Direct-drive servo motor technology is automating needle positioning and feed mechanism synchronization previously requiring mechanical linkages. Automotive upholstery producers in Vietnam and Mexico are specifying these platforms for synthetic fabric handling precision. The technology is automating quality consistency checks that previously required manual seam inspection, reducing rework rates in high-volume contract manufacturing.
REACH chemical restrictions are eliminating certain lubricant formulations and surface treatment processes from European supply chains. Casting producers are migrating to water-based coating systems and reformulated bearing greases to maintain market access. Electronic control module manufacturers with captive Japanese foundry relationships are capturing margin premiums as competitors face reformulation delays.
Factory procurement teams are consolidating vendor relationships around equipment suppliers offering integrated maintenance telemetry. Large garment groups in Bangladesh and Cambodia are displacing spot-buying of standalone machines with fleet management contracts bundling hardware, software, and service. This consolidation is most visible among vertically integrated apparel exporters seeking ISO 4915 certification arbitrage across multiple buyer audits.
Industrial Sewing Machines Market Segmentation
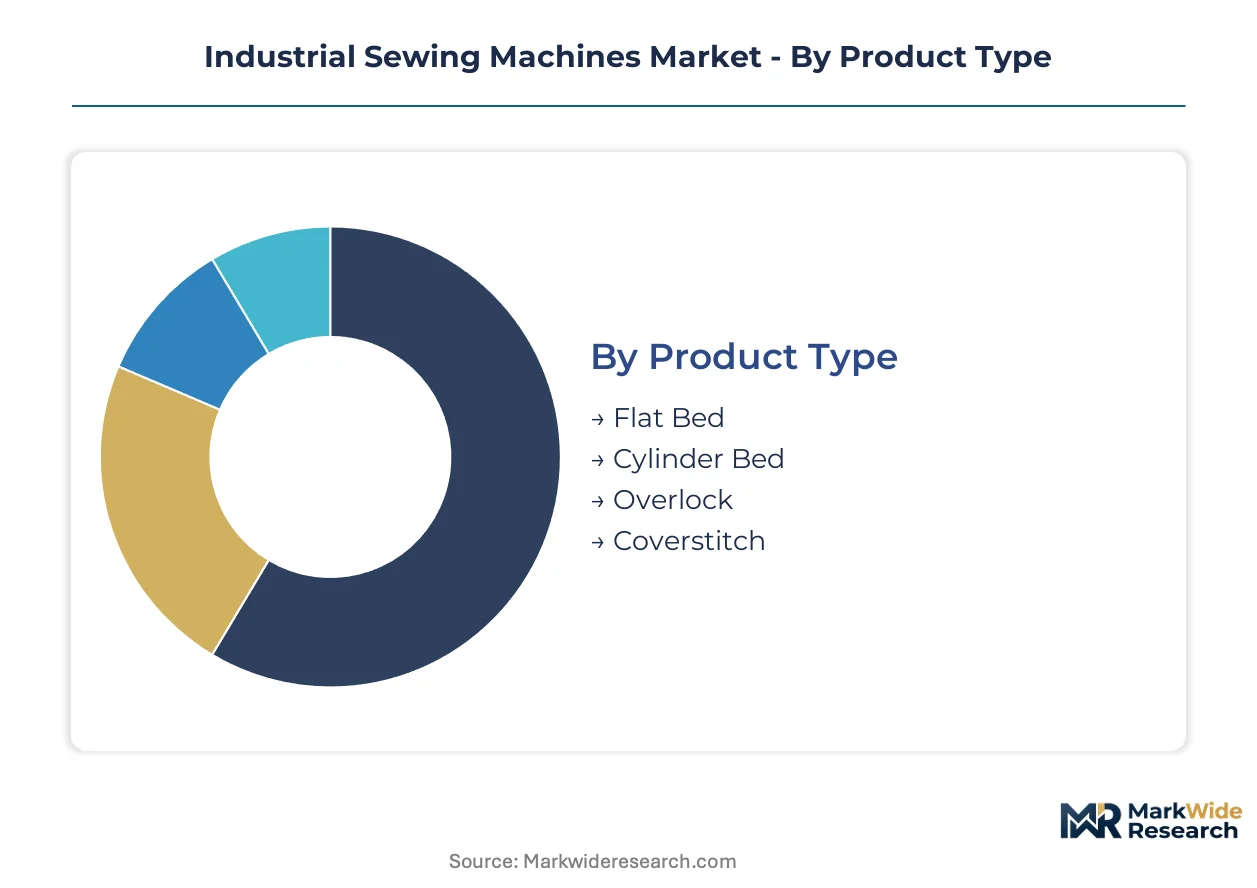
Segmentation in industrial sewing equipment reflects divergent capital deployment strategies across volume apparel contractors and specialized technical textile producers. Equipment specifications vary sharply between standardized lockstitch platforms and precision-engineered cylinder-bed systems for curved seam access.
Product Type:
Customization intensity spans from commodity flat-bed platforms to application-specific long-arm configurations engineered for dimensional material handling.
- Flat Bed:Standardized work surface configurations dominate volume apparel assembly across Bangladesh and Vietnamese export zones. Tier-1 garment contractors specify programmable lockstitch variants with ISO 4915 stitch classification for buyer audit compliance. Most installed capacity flows through Flat Bed. Expansion is steepest in Cylinder Bed.
- Cylinder Bed:Curved seam access capabilities command premium positioning in automotive upholstery and leather goods manufacturing. Long-arm throat depth specifications enable synthetic fabric assembly for electric vehicle interior components. Tier-1 seating suppliers in Mexico and Vietnam are expanding dedicated cylinder-bed fleets.
- Overlock:Edge-finishing configurations secure seam integrity in knitwear production lines across Cambodian factory clusters.
- Coverstitch:Hemming and decorative seam platforms serve activewear manufacturers requiring stretch recovery performance.
Flat Bed equipment carries the highest installed base. Cylinder Bed configurations are gaining share fastest in technical textile penetration.
End User:
Customer sophistication ranges from price-sensitive contract manufacturers to specification-driven automotive tier-1 suppliers with captive maintenance protocols.
- Apparel Manufacturers:Volume-driven procurement concentrates in Bangladesh, Vietnam, and Cambodia where factory automation consultants specify electronic control platforms with real-time tension monitoring. Fleet standardization around programmable lockstitch equipment reduces spare parts inventory complexity. Procurement volume concentrates here. Margin capture is strongest in Automotive Industry.
- Automotive Industry:Synthetic fabric assemblies for electric vehicle interiors require specialized cylinder-bed configurations with extended throat depth. REACH chemical compliance mandates are accelerating electronic module adoption across European seating suppliers. Tier-1 manufacturers in Germany and France specify integrated maintenance telemetry.
- Upholstery Services:Custom furniture and interior refurbishment operations favor semi-automatic equipment for short production runs.
- Marine Applications:Heavy-duty canvas and sail production requires reinforced feed mechanisms for coated fabric assemblies.
Apparel Manufacturers deploy the largest machine fleets. Automotive Industry end-users are expanding most quickly.
Technology:
Control sophistication determines competitive positioning between mechanical legacy systems and servo-driven electronic platforms with predictive maintenance capability.
- Electronic:Direct-drive servo motor integration automates needle positioning and feed synchronization previously requiring mechanical linkages. FCC electromagnetic compatibility certification governs US-bound control module shipments. REACH solvent restrictions are eliminating high-VOC lubricants from European production floors. Electronic platforms are displacing mechanical alternatives fastest.
- Computerized:Programmable stitch pattern libraries enable rapid style changeover in multi-product contract manufacturing environments.
- Semi-Automatic:Mechanically governed systems with limited electronic assistance retain cost advantages in low-complexity garment operations.
- Manual:Purely mechanical control persists in frontier markets with intermittent power infrastructure and limited technical service access.
Electronic technology carries the highest replacement velocity. Computerized platforms are climbing the fastest in technical textile segments.
Application:
Material characteristics dictate machine specification from lightweight woven apparel to multi-layer composite assemblies.
- Clothing Production:Standardized woven and knit assembly drives volume demand for flat-bed lockstitch and overlock configurations across Southeast Asian export zones.
- Leather Goods:Dense material penetration requires cylinder-bed access and specialized presser foot configurations for curved seam execution.
- Home Textiles:Bedding and curtain manufacturers favor long-arm flat-bed variants for extended material handling capacity.
- Technical Textiles:Medical and aerospace composite stitching demands precision cylinder-bed systems with stitch-level data analytics for quality traceability.
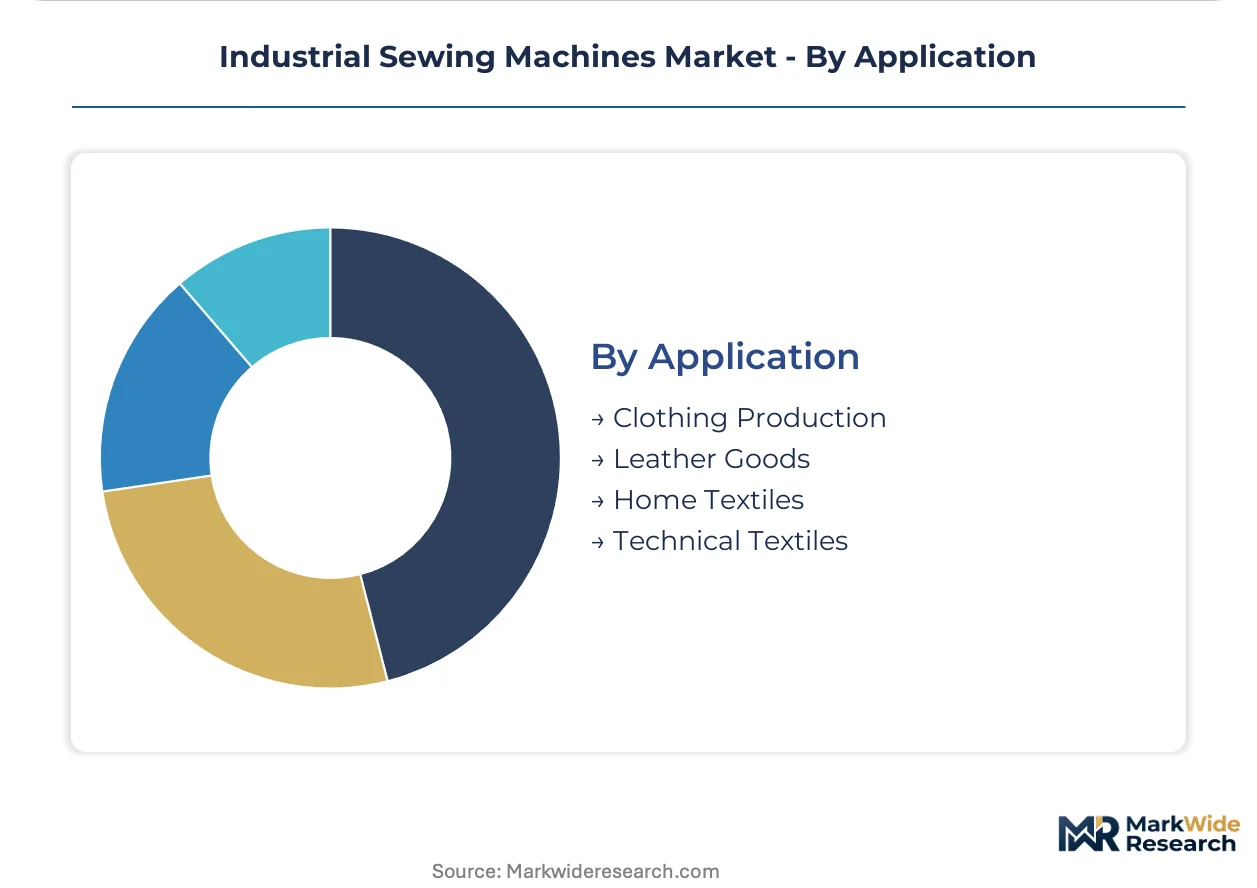
Clothing Production represents the largest application volume. Technical Textiles are expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production capacity toward jurisdictions with lower compliance costs for electronic control module certification, while REACH chemical restrictions in Europe accelerate equipment replacement cycles among continental manufacturers seeking solvent-free casting alternatives.
China
MIIT equipment safety directives and GB standards govern domestic manufacturing protocols while shaping import requirements for foreign OEMs. Dual carbon goals are pressuring foundries to reformulate surface treatments and adopt water-based coating systems. Yangtze River Delta garment clusters around Shanghai are consolidating procurement around fleet management contracts bundling hardware with predictive maintenance telemetry.
Germany
Extended producer responsibility frameworks under the EU Green Deal are creating certified refurbishment channels for end-of-life electronic modules. KBA and ECHA enforcement of REACH solvent restrictions is eliminating high-VOC lubricants from production floors. Baden-Württemberg automotive seating suppliers are specifying integrated maintenance telemetry for synthetic fabric assembly lines serving electric vehicle interior programs.
Vietnam
Export-oriented garment zones in Ho Chi Minh City and surrounding provinces are expanding machine fleets to capture contract manufacturing volumes from relocating Chinese capacity. The country's national equipment safety regulator aligns import protocols with international standards to facilitate technology transfer. Tier-1 seating suppliers in Binh Duong province are piloting subscription pricing models for uptime guarantees on direct-drive servo platforms.
United States
FCC electromagnetic compatibility certification governs control module shipments and extends product launch schedules for smaller manufacturers lacking dedicated regulatory affairs capacity. EPA and OSHA workplace standards influence lubricant selection and casting surface treatment specifications. Southeastern apparel clusters in Georgia and the Carolinas are consolidating vendor relationships around suppliers offering ISO 4915 stitch classification compliance for buyer audit arbitrage.
Japan
METI industrial policy supports captive manufacturing strategies that sustain delivery reliability for high-speed lockstitch platforms amid precision casting supply volatility. JIS standards provide technical baselines for quality arbitration in cross-border equipment transactions. Chubu region foundries maintain critical servo motor housing production that Japanese OEMs leverage for vertical supply chain control.
Industrial Sewing Machines Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue technical textile specialization and IoT-enabled service models. Market structure consolidates around three tiers: Japanese captive manufacturers with foundry relationships, distributed Asian assemblers with dense regional distribution, and European specialists in application-specific configurations. Dominant competitive moves include backward integration into precision casting supply and geographic expansion through fleet management contracts replacing standalone equipment sales.
Within the premium-tier vector, Juki Corp. and Brother Industries Ltd. exemplify Japanese manufacturers leveraging captive foundry relationships to secure servo motor housing supply. Durkopp Adler occupies a position among European specialists focused on long-arm cylinder-bed configurations. Zoje Sewing Machine Co. Ltd. and Jack Sewing Machine Co. Ltd. represent Chinese fabricators competing on scale-driven flat-bed standardization for volume apparel assembly across Southeast Asian export zones.
| Leading Market Players |
|---|
| Pegasus Sewing Machine Mfg |
| Zoje Sewing Machine Co. Ltd. |
| Juki Corp. |
| Bernina International AG |
| Durkopp Adler |
| Brother Industries Ltd. |
| Jack Sewing Machine Co. Ltd. |
| Seiko Sewing Machine Co., Ltd. |
| Yamato Sewing Machine Mfg Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Direct-drive servo motor adoption simultaneously compresses unit economics and concentrates supply relationships around Japanese foundries with captive casting capabilities. Electronic control module integration raises bill-of-material costs while REACH chemical compliance in Europe eliminates lower-priced mechanical alternatives from continental procurement portfolios. Factory automation consultants in Vietnam and Bangladesh now specify programmable platforms with real-time tension monitoring as baseline requirements, narrowing the viable supplier set.
Pricing Analysis
Distributor margins of 15-25% separate factory gate pricing from landed equipment costs across Southeast Asian garment hubs. Three-tier pricing structure across premium electronic, standard semi-automatic, and economy mechanical levels tracks certification grade and after-sales service bundling. Cost compression in the mechanical tier is intensifying because Vietnamese and Cambodian contract manufacturers prioritize volume scale over precision specifications. Price sensitivity concentrates among frontier-market apparel contractors; automotive seating suppliers in Germany and Mexico exhibit lowest sensitivity due to specification-driven procurement protocols.
Supply Chain Analysis
MIIT equipment safety directives and GB standards in China are reshaping sourcing toward domestic foundries with certified surface treatment capabilities. Critical servo motor housing production draws from Japan, Germany, and China's Yangtze River Delta region. Permanent magnet materials and precision castings for high-torque motors rest on mining concentration in specific geographies, creating single-source vulnerability for mid-tier assemblers without captive supply relationships. Distribution runs through dense regional networks anchored by factory automation consultants specifying ISO 4915 stitch classification compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic control module standardization creates margin expansion through premium-tier displacement of mechanical equipment and recurring service revenue from predictive maintenance telemetry. Servo motor integration costs are falling with scale economies in Japanese foundry operations.
For Market Incumbents: Deploy fleet management contracts bundling hardware, software, and predictive maintenance to lock out emerging IoT-enabled competitors. Capture backward integration into precision casting supply to insulate against Japanese and German foundry lead time volatility. Defend against Chinese scale players by certifying ISO 4915 stitch classification as a procurement baseline for buyer audit arbitrage. For New Entrants and Emerging Players: Begin with technical textile specialization in medical and aerospace composite stitching, where cylinder-bed configurations with extended throat depth command premium positioning absent in commoditized apparel segments. Target Vietnamese and Indonesian factory groups piloting subscription pricing models for uptime guarantees. Pursue regulatory arbitrage by certifying electronic control modules under FCC electromagnetic compatibility standards ahead of US market entry. For Investors and Strategic Acquirers: Valuations sit cheapest among distributed Asian assemblers lacking captive foundry relationships yet possessing dense regional distribution networks suitable for acquisition and capability overlay. Long-term viability favors equipment suppliers with integrated maintenance telemetry and refurbishment channel access under EU Green Deal extended producer responsibility frameworks. Monitor REACH chemical enforcement intensity in Europe as an inflection indicator for electronic platform replacement velocity against mechanical legacy stock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive servo motor housing production insulates Juki and Brother from German-Japanese foundry lead time volatility. |
| Fleet Management Contract Rollout | Bundled hardware-software-service pricing displaces spot-buying among Bangladeshi and Cambodian garment exporters. |
| EU Green Deal Refurbishment Channel | Certified electronic module remanufacturing creates service revenue models in German and French markets. |
| Technical Textile Cylinder-Bed Specialization | Medical and aerospace composite stitching requirements enable margin premiums absent in standard apparel segments. |
| Industrial IoT Predictive Maintenance Platform | Stitch-level data analytics enable subscription pricing for uptime guarantees among Vietnamese factory groups. |
Methodological Framework
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs records and MIIT equipment safety filings, and technical specification analysis of GB standards and FCC certification databases — were reconciled through bottom-up and top-down triangulation. Conversations with maintenance directors at tier-1 automotive seating suppliers, aftermarket service heads at Japanese manufacturers, and factory automation consultants across Vietnamese export zones informed competitive positioning assessments. SEC 10-K filings, trade flow data, and ISO 4915 certification registries provided secondary anchor points.
Data-stream reconciliation across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from equipment shipment trajectories, replacement cycle compression rates, and electronic platform penetration curves. Forecast inputs incorporated REACH chemical compliance enforcement intensity in Europe, dual carbon goal implementation timelines in China, and fleet management contract adoption rates among Southeast Asian garment exporters.
Caveats apply where REACH solvent restriction enforcement delays, precision casting supply disruptions, or copper and rare earth commodity price spikes could materially shift the outlook. Forecasts reflect assumptions regarding electronic platform cost curves and regulatory compliance timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market