
 Asia Pacific Fabric Shavers Market | 2026-2036
Asia Pacific Fabric Shavers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Fabric Shavers Market Insights
Subscription-based blade replacement programs is broadening the recurring revenue model for fabric shaver vendors beyond one-time hardware sales. Philips leverages its service network to sustain repeat purchases across Southeast Asian markets. Xiaomi anchors its position through ecosystem bundling with smart home platforms. Panasonic differentiates via specialized blade technology for delicate fabric types.
Asia Pacific fabric shavers are motorized or hand-held devices employing rotary or mesh cutting heads to remove lint, pilling, and loose fibers from textile surfaces, typically operating at speeds between 3,000 and 10,000 RPM with stainless steel or titanium-coated blades. These tools serve both consumer garment maintenance and commercial textile finishing applications where surface quality directly influences product valuation. Electric and rechargeable units dominate volume flows as lithium-ion power sources displace alkaline batteries across mid-tier and premium positioning. The apparel manufacturers and textile maintenance services end-user segment captures concentrated margin pools due to bulk procurement and durability requirements that exceed household replacement cycles.
China's SAMR enforces GB standards for small appliance electrical safety and electromagnetic compatibility, while India's BIS mandates compulsory certification for domestic sale of motorized grooming tools. Japan's METI administers PSE marking requirements that constrain import pathways for uncertified equipment. Australia's TGA and Electrical Safety Office coordinate product recalls that shape brand liability exposure across Oceania. Stakeholders must monitor divergent certification timelines and harmonization gaps between national standards bodies when scaling multi-country distribution.
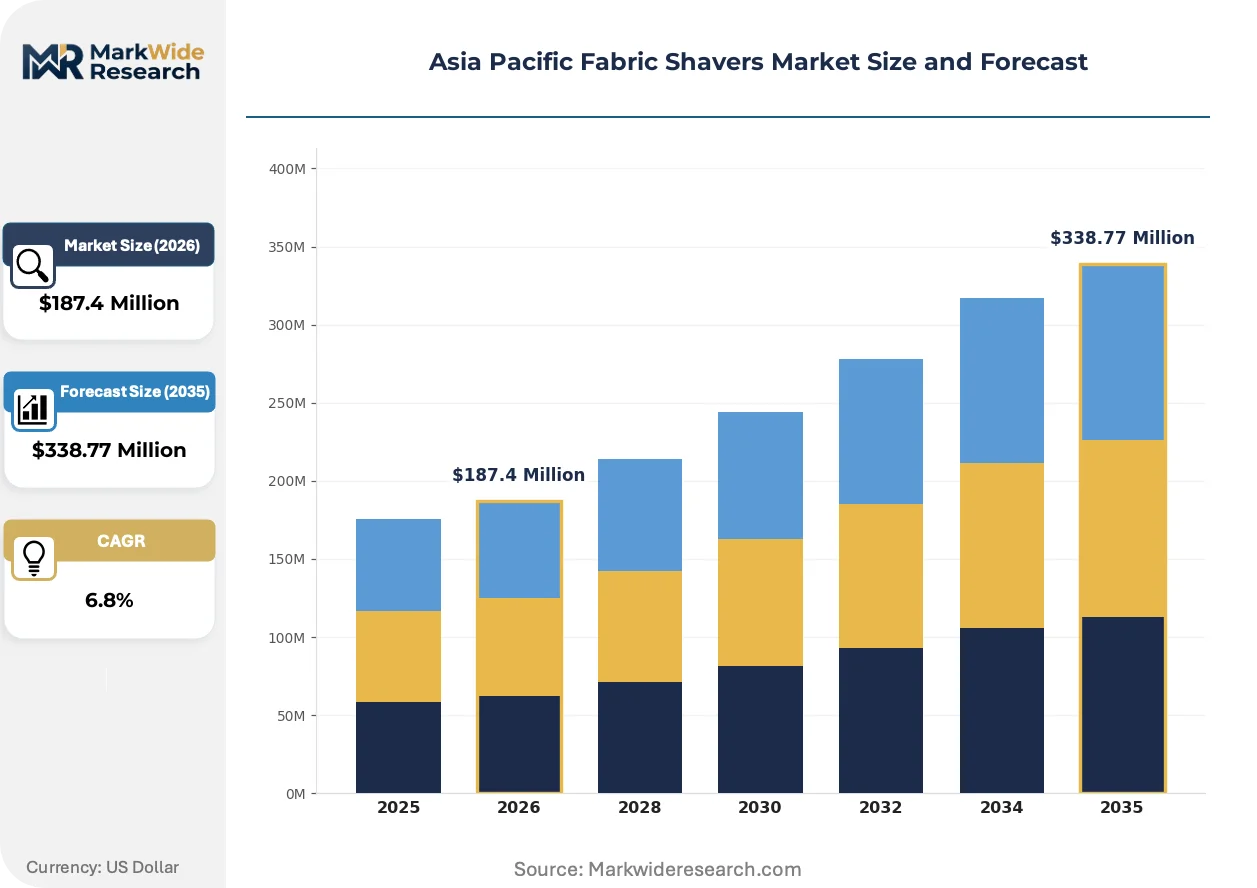
Market Dynamics
Subscription-based blade replacement programs are restructuring revenue architecture across the Asia Pacific fabric shavers market, converting hardware vendors into recurring-revenue service providers and tightening customer lock-in through consumable dependency.
Growth Catalysts
- India's BIS certification tightening:Compulsory safety benchmarks for motorized grooming tools are filtering substandard imports and elevating trust in certified domestic and international brands.
- Mesh cutting head technology:Precision blade geometries originally developed for delicate silk and cashmere maintenance are migrating downmarket into mid-tier household units.
- Tier-two city e-commerce deepening:China's lower-tier urban centers are experiencing accelerated penetration of home care appliance digital distribution channels.
Market Restraints
- Lithium-ion cell cost volatility:Rechargeable power source price fluctuations compress margin structures for mid-tier electric fabric shaver assemblers.
- Hand-crank manual substitute persistence:Low-cost mechanical lint removers retain significant household share in price-sensitive Southeast Asian markets.
- Japan's PSE marking timeline:METI electromagnetic compatibility certification delays create inventory hold-ups for uncertified import batches.
Strategic Opportunities
- Vietnam's underpenetrated garment manufacturing belt:Industrial textile finishing operations outside Ho Chi Minh City represent concentrated bulk procurement potential for commercial-grade units.
- Smart home ecosystem convergence:Integration with connected appliance platforms enables data-driven maintenance scheduling and predictive blade replacement alerts.
- Australia's TGA recall coordination:Stringent post-market surveillance creates competitive openings for brands with superior traceability systems.
Industry Challenges
- Cross-border certification fragmentation:Divergent GB standards, BIS mandates, and PSE requirements force parallel testing runs that extend product launch timelines.
- Legacy alkaline battery inventory obsolescence:Retail channel stockpiles of non-rechargeable units face write-down pressure as lithium-ion preference hardens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Fabric Shavers Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Rechargeable, Battery-operated End User: Households, Retailers, Apparel Manufacturers, Textile Maintenance Services Distribution Channel: Online, Offline, Specialty Stores, Department Stores Power Source: Plug-in, Cordless, Solar-powered, Lithium-ion |
| Companies Covered | Philips, Xiaomi, Panasonic, Conair, Flyco, Sencor, Steamery, Evercare, Electrolux, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Fabric Shavers Market Trends and Innovations
Titanium-coated blade metallurgy and connected service platforms are converging to redefine performance benchmarks and customer relationship economics across Asia Pacific fabric shaver supply chains.
Brushless DC motor architectures are absorbing efficiency gains previously reserved for premium grooming appliances. Garment care specialists in Japan and South Korea are adopting these systems for reduced heat generation during extended commercial use. The technology is absorbing market share from conventional brushed motors by enabling sustained 10,000 RPM operation without thermal degradation.
China's SAMR is intensifying GB standard enforcement for small appliance electrical safety and electromagnetic compatibility. Factory audits and spot-testing protocols are tightening across Guangdong and Zhejiang manufacturing clusters. Exporters targeting multiple Asia Pacific jurisdictions are consolidating compliance testing to reduce redundant certification cycles.
After-sales service unbundling is separating blade replacement from hardware warranty coverage. Direct-to-consumer subscription channels in China's tier-one cities are displacing traditional retail accessory sales. This behavioral shift is most visible among millennial households in Shanghai and Beijing who prioritize convenience over upfront hardware cost minimization.
Asia Pacific Fabric Shavers Market Segmentation
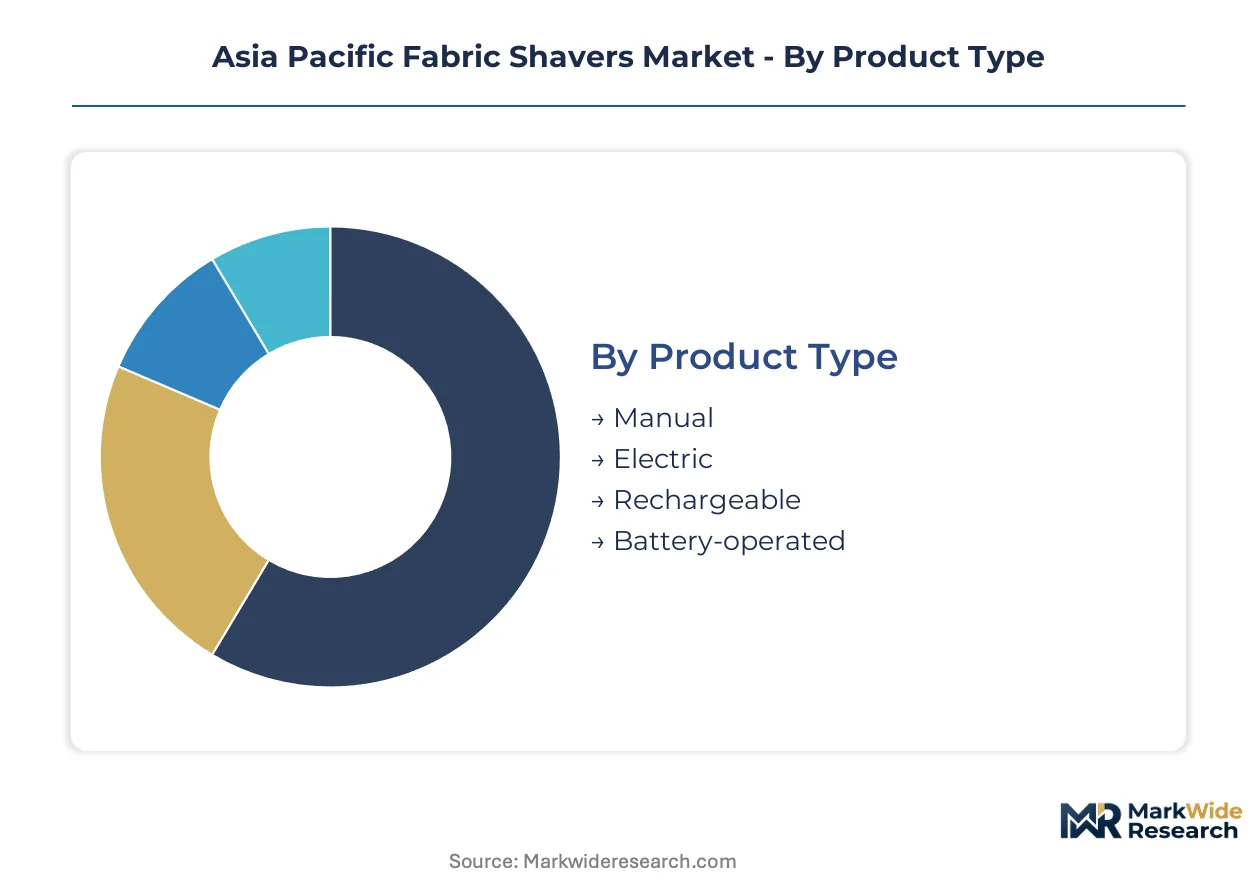
Fabric shaver segmentation in Asia Pacific reveals distinct capital requirements across product architectures, with rechargeable and electric units demanding heavier upfront tooling investment than manual alternatives. Distribution channel and end-user stratification further separates volume-scale household markets from margin-rich commercial procurement.
Product Type:
Capital intensity varies sharply across product architectures, with motorized systems requiring precision tooling and safety certification investments that manual formats avoid entirely.
- Electric:Mains-powered units with brushed or brushless DC motors deliver sustained 3,000-10,000 RPM operation for commercial textile finishing. Demand concentrates in Japan's garment care specialists and South Korean dry-cleaning chains where thermal stability during extended use justifies premium positioning.
- Rechargeable:Lithium-ion powered cordless designs with USB-C charging ports dominate China's tier-one and tier-two city e-commerce channels. Xiaomi and Philips anchor this segment through ecosystem bundling and service network density.
- Manual:Hand-crank lint removers with rotary blade heads retain household share in Vietnam and Indonesia price-sensitive markets.
- Battery-operated:Alkaline-cell units face inventory obsolescence pressure as lithium-ion preference hardens across mid-tier positioning.
Electric units absorb the bulk of installed capacity in commercial applications; rechargeable designs are expanding most quickly through digital distribution channels.
End User:
Procurement scale and replacement cycle length separate fragmented household demand from concentrated bulk purchasing by industrial operators.
- Households:Individual consumers purchasing single units through e-commerce platforms or retail channels, with replacement driven by blade dulling rather than motor failure.
- Apparel Manufacturers:Bulk procurement of commercial-grade units for final garment finishing operations, particularly in Vietnam's manufacturing belt outside Ho Chi Minh City where surface quality directly influences export valuation.
- Textile Maintenance Services:Professional dry-cleaning and garment care operators in Japan and South Korea specifying brushless motor architectures for reduced heat generation.
- Retailers:Corporate procurement for customer service stations and in-store garment maintenance, concentrated in Australia's department store chains and Japan's specialty retail formats.
Households generate the highest unit volumes; apparel manufacturers capture the steepest expansion trajectory as Vietnam's textile finishing capacity scales.
Distribution Channel:
Channel economics reflect divergent customer acquisition costs and post-sale service attachment rates across physical and digital touchpoints.
- Online:Tmall, JD.com, and Shopee platforms dominate China's tier-two city penetration, with subscription blade replacement programs displacing traditional accessory sales among millennial households in Shanghai and Beijing.
- Offline:Electronics retailers and home appliance chains sustain significant share in Japan and South Korea where tactile evaluation precedes purchase.
- Specialty Stores:Garment care boutiques and fabric maintenance suppliers serving professional end-users with technical specification guidance.
- Department Stores:Premium positioning through curated home appliance sections in Australia's David Jones and Japan's Isetan formats.
Online channels command the dominant share of volume growth; specialty stores retain the highest margin capture through service bundling.
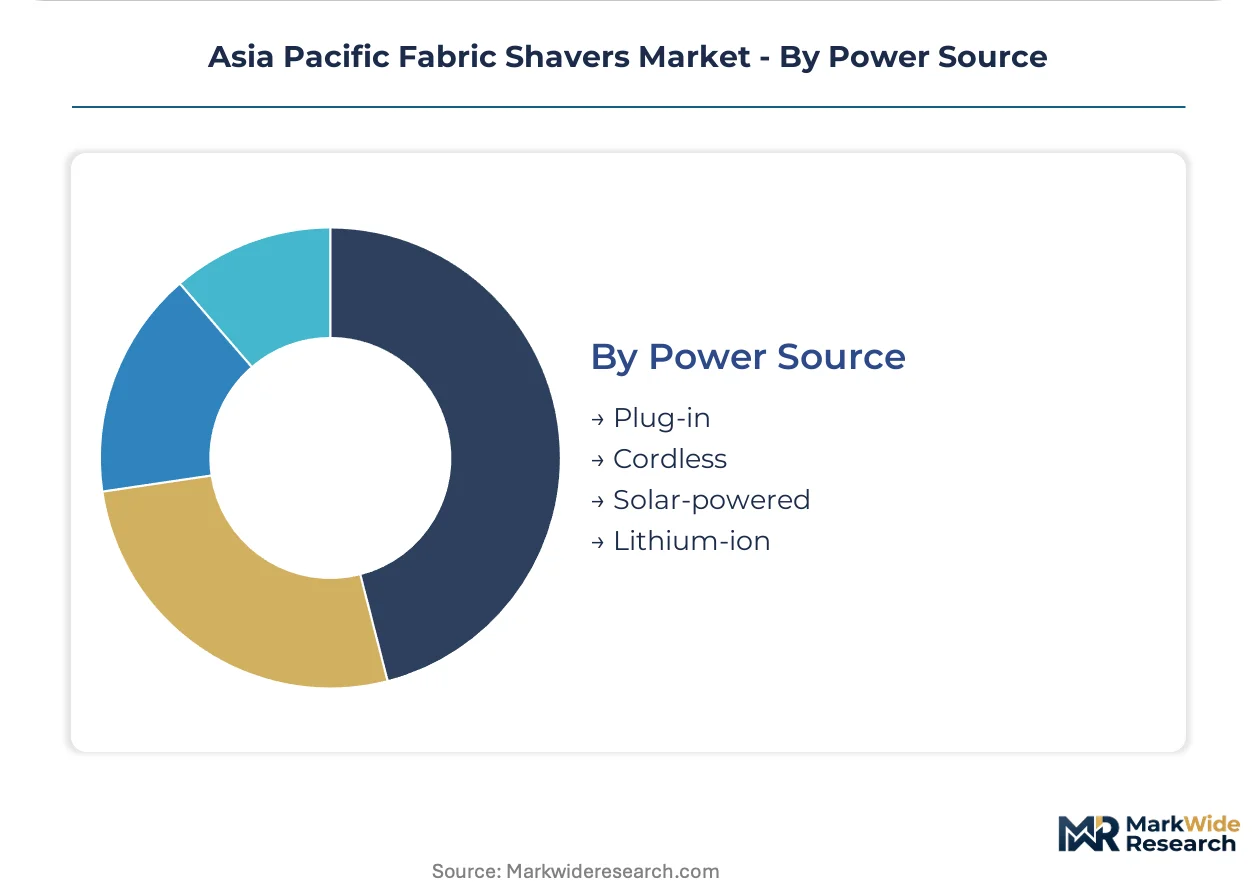
Power Source:
Energy storage chemistry and charging infrastructure compatibility create tiered performance and price positioning across the power architecture spectrum.
- Lithium-ion:Rechargeable cells with 2,000+ cycle life and USB-C compatibility anchor mid-tier and premium product positioning, displacing alkaline alternatives across China's manufacturing output.
- Cordless:Battery-powered portability for travel and household convenience, with demand clustering in Southeast Asian urban centers where outlet access varies.
- Plug-in:Continuous mains power for commercial-grade sustained operation, specified by Japan's METI-compliant professional equipment.
- Solar-powered:Photovoltaic cell integration for off-grid and outdoor applications, with niche adoption in Australia's remote regional markets.
Lithium-ion configurations absorb the majority of new product development investment; cordless formats are gaining share fastest through lifestyle portability marketing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing clusters dominate supply-side output while consumption concentrates in Japan's professional garment care networks and India's expanding urban households. This production-consumption asymmetry shapes certification requirements and channel strategies across the region.
China
Tier-two cities drive rechargeable unit adoption through Tmall and JD.com penetration. SAMR enforces GB standards for electrical safety and electromagnetic compatibility across Guangdong and Zhejiang factory zones. Shenzhen and Dongguan manufacturing hubs supply lithium-ion powered designs for domestic distribution and Vietnam re-export.
Japan
Professional dry-cleaning chains specify brushless DC motors for thermal stability during extended operation. METI administers PSE marking requirements that constrain import pathways for uncertified equipment. Tokyo and Osaka garment care specialists absorb premium-tier electric units through specialty retail channels.
India
Urban households in Mumbai and Delhi accelerate motorized grooming tool adoption as garment maintenance awareness spreads. BIS mandates compulsory certification for domestic sale, filtering substandard imports and elevating trust in certified brands. Tamil Nadu and Gujarat textile finishing operations represent emerging commercial procurement pockets.
Vietnam
Garment manufacturing belts outside Ho Chi Minh City generate concentrated bulk demand for commercial-grade finishing equipment. The country's national standards body aligns electrical safety protocols with export market requirements. Binh Duong and Dong Nai industrial zones house textile exporters specifying surface quality tools for final garment preparation.
Australia
Department store chains and specialty retailers sustain premium positioning through curated home appliance sections. TGA and Electrical Safety Office coordinate product recalls that shape brand liability exposure across Oceania. Sydney and Melbourne urban centers drive online subscription blade replacement program adoption among millennial households.
Asia Pacific Fabric Shavers Market Competitive Landscape
Top-tier vendors anchor premium positioning through service network density and ecosystem integration, while mid-tier specialists compete on blade metallurgy and price accessibility. The vendor base stratifies across three tiers: multinational appliance conglomerates with regional service infrastructure, Chinese ecosystem players bundling smart home connectivity, and European design-focused specialists targeting premium garment care. Two dominant competitive moves are reshaping positioning: subscription-based consumable programs converting hardware vendors into recurring-revenue operators, and certification consolidation to reduce multi-country compliance redundancy.
Within the multinational conglomerate tier, Philips and Panasonic exemplify divergent specialization strategies—one leveraging service network density for repeat purchase capture, the other anchoring premium positioning through blade technology differentiation. Xiaomi occupies a distinct ecosystem-driven position, bundling fabric shavers with smart home platforms to reduce customer acquisition costs. These three players collectively represent the strategic archetypes—service infrastructure, technology specialization, and platform integration—competing for household and commercial share across certification-fragmented Asia Pacific markets.
| Leading Market Players |
|---|
| Philips |
| Xiaomi |
| Panasonic |
| Conair |
| Flyco |
| Sencor |
| Steamery |
| Evercare |
| Electrolux |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery chemistry migration simultaneously compresses unit economics and concentrates procurement leverage among Shenzhen and Dongguan assemblers with captive cell sourcing relationships. Brushless DC motor adoption reshapes cost structures across premium tiers while certification fragmentation in India and Japan extends supplier qualification timelines.
Pricing Analysis
Margin tightening in mid-tier rechargeable units reflects lithium-ion cell cost volatility and parallel certification runs for BIS and PSE compliance. Three-tier pricing structure across premium brushless systems, standard rechargeable designs, and economy manual alternatives separates procurement by thermal stability requirements and warranty bundling. Cost-down pressure accelerates as Vietnam's garment manufacturers consolidate bulk orders and extract volume discounts. Household buyers in Indonesia and Philippines exhibit highest price sensitivity; Japanese dry-cleaning chains show lowest sensitivity due to thermal degradation avoidance priorities.
Supply Chain Analysis
Workforce availability in Guangdong and Zhejiang manufacturing clusters anchors precision tooling capacity for stainless steel blade stamping and motor assembly operations. Supply draws from China's lithium-ion cell producers, Japanese brushless motor specialists, and German precision bearing suppliers. Single-source vulnerability concentrates in titanium coating equipment where European vendors dominate. Distribution runs through Tmall and JD.com fulfillment centers for domestic China consumption, with Shopee and Lazada handling Southeast Asian cross-border flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into blade metallurgy and lithium-ion cell sourcing represents the decisive competitive race, with downstream subscription service platforms emerging as the second control point.
For Market Incumbents: To counter Xiaomi's ecosystem bundling and Philips' service network density, Panasonic should deepen captive supply of titanium-coated blade substrates and expand METI-compliant certification consulting for commercial buyers. Certification investment in India's BIS laboratory partnerships creates defensive moats against substandard imports. For New Entrants and Emerging Players: Begin with Vietnam's Binh Duong and Dong Nai industrial zones where garment exporters lack dedicated textile finishing equipment suppliers. Target commercial-grade brushless units with thermal monitoring as the most penetrable segment; anchor go-to-market through direct procurement relationships with export-oriented manufacturers rather than retail channel buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to appliance conglomerates seeking smart home platform completeness. Five-to-ten year viability hinges on recurring blade replacement revenue attachment rates exceeding hardware margin capture. Monitor BIS certification rejection rates for uncertified imports as the inflection signal for domestic brand trust premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blade Metallurgy | Captive titanium coating capacity insulates margin from European equipment supplier pricing power. |
| Smart Home Platform Integration | Xiaomi's Mi Home ecosystem reduces customer acquisition costs through appliance bundling in tier-two cities. |
| Subscription Blade Replacement Program | Direct-to-consumer channels in Shanghai and Beijing convert transactional hardware sales into recurring revenue streams. |
| BIS Certification Pre-Investment | Early laboratory partnerships in Tamil Nadu and Gujarat accelerate market entry ahead of compulsory enforcement tightening. |
| Commercial Thermal Monitoring Specification | Brushless DC architectures with heat sensors capture Japan's dry-cleaning chain procurement specifications from Panasonic. |
Research Methodology
Multi-period observation of lithium-ion cell pricing spreads, BIS certification timeline extensions, and e-commerce penetration rates in China's tier-two cities anchored the trend analysis, supplemented by interviews with appliance category managers at Tmall and JD.com, procurement directors at Vietnam's garment export manufacturers, blade metallurgy specialists at Shenzhen tooling facilities, and after-sales service heads at Philips and Panasonic regional operations. Secondary validation drew from SAMR GB standard enforcement bulletins, BIS compulsory registration orders, METI PSE marking directives, and customs trade data for small appliance imports. Bottom-up unit shipment estimates triangulated against top-down household appliance spending patterns.
Segment-weighting applied product type, end-user procurement scale, distribution channel economics, and power source chemistry as the four primary stratification dimensions across the projection horizon. CAGRs derived from fitted growth curves calibrated to historical e-commerce penetration velocities and certification regime implementation lags. Forecast inputs incorporated brushless motor cost-down trajectories and lithium-ion cell commodity price volatility bands.
Regulatory enforcement acceleration, lithium supply contract renegotiations, and smart home platform consolidation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding BIS laboratory capacity expansion and METI electromagnetic compatibility testing throughput. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Textile Winding Machine Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
Sewing Machine Component Market