
 Automatic Fabric Folding Machines Market | 2026-2036
Automatic Fabric Folding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Fabric Folding Machines Market Insights
China's Jiangsu and Zhejiang provinces is reconfiguring regional supply patterns for automatic fabric folding machines as domestic manufacturers scale precision engineering capabilities. Herbert Kannegiesser GmbH anchors German engineering reputation in high-throughput industrial folder machines for commercial laundries. Suntech Industrial leverages vertical manufacturing depth to compete on cost across conveyor folding systems in Asian markets. Dekken Machinery specializes in compact tabletop configurations for upholstery workshops with limited floor space.
Automatic fabric folding machines integrate servo-controlled actuators, programmable logic controllers, and sensor-guided alignment systems to transform continuous textile webs into precisely dimensioned folds for downstream packaging or finishing. These systems operate at speeds ranging from 800 to 4,000 folds per hour depending on fabric weight and fold complexity, serving industrial laundries and garment finishing operations where manual folding creates throughput bottlenecks. Industrial folder machines dominate installed capacity across commercial laundries and large textile mills where batch volumes justify capital deployment. Robotic folding solutions represent the fastest-expanding technology tier as garment manufacturers seek programmable flexibility for mixed-SKU production runs. Servo motor driven architectures command margin premiums over pneumatic alternatives due to precision repeatability and reduced compressed air infrastructure.
CE marking requirements under EU machinery directives enforce safety interlocks and emergency stop protocols that elevate engineering costs for European-bound equipment. China's GB standards and MIIT technical regulations mandate energy efficiency benchmarks that favor servo-electric architectures over hydraulic folding systems in domestic procurement. India's BIS certification for industrial machinery creates compliance thresholds that shape vendor qualification for government-backed textile modernization schemes. Stakeholders must monitor how divergent efficiency and safety standards across these jurisdictions influence platform standardization versus market-specific product development tradeoffs.
Market Dynamics
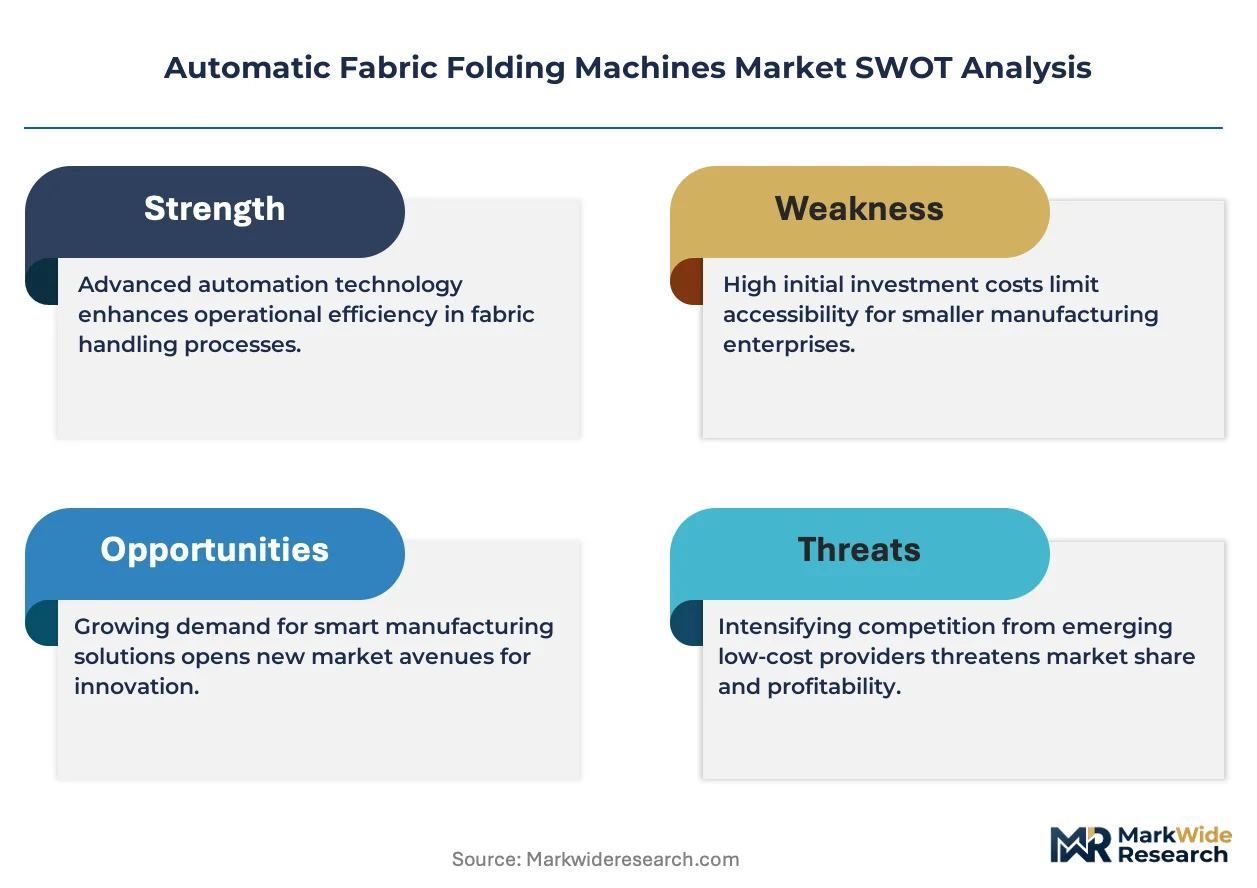
Servo motor driven architectures are displacing pneumatic folding systems as energy efficiency mandates tighten across industrialized economies, compressing operating cost differentials between established and emerging equipment suppliers.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants in industrial processes accelerates electric servo adoption over pneumatic actuation in European textile finishing facilities.
- Garment manufacturing automation:Vietnam's export-oriented textile zones deploy automatic folding machines to offset wage inflation in cut-make-trim operations serving fast-fashion brands.
- India PLI scheme:Production-linked incentives for technical textiles expand capital equipment budgets across integrated apparel clusters in Tamil Nadu and Gujarat.
Market Restraints
- Precision component concentration:High-torque servo motors and harmonic drives concentrate supply among Japanese and German component specialists, creating input vulnerability.
- CE marking cost escalation:EU machinery directive compliance for safety interlocks and emergency stop protocols elevates engineering costs for equipment bound for European markets.
- Manual folding substitution:Low-complexity garment categories in price-sensitive markets retain manual folding due to minimal throughput requirements and abundant labor.
Strategic Opportunities
- Robotic folding convergence:Integration of collaborative robot arms with vision-guided alignment systems enables mixed-SKU production runs for on-demand apparel manufacturing.
- Indonesia textile modernization:Government-backed industrial zone development in Central Java creates first-mover advantage for servo-electric folder deployments.
- Equipment-as-a-service models:Subscription-based financing spreads capital burden for mid-scale laundries and garment finishers seeking automation without ownership risk.
Industry Challenges
- Mechatronics talent scarcity:Servo system commissioning and predictive maintenance require specialized technicians in short supply across Southeast Asian manufacturing hubs.
- Legacy pneumatic integration:Retrofitting existing compressed air infrastructure with electric architectures demands production downtime that export-contract manufacturers resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Fabric Folding Machines Market |
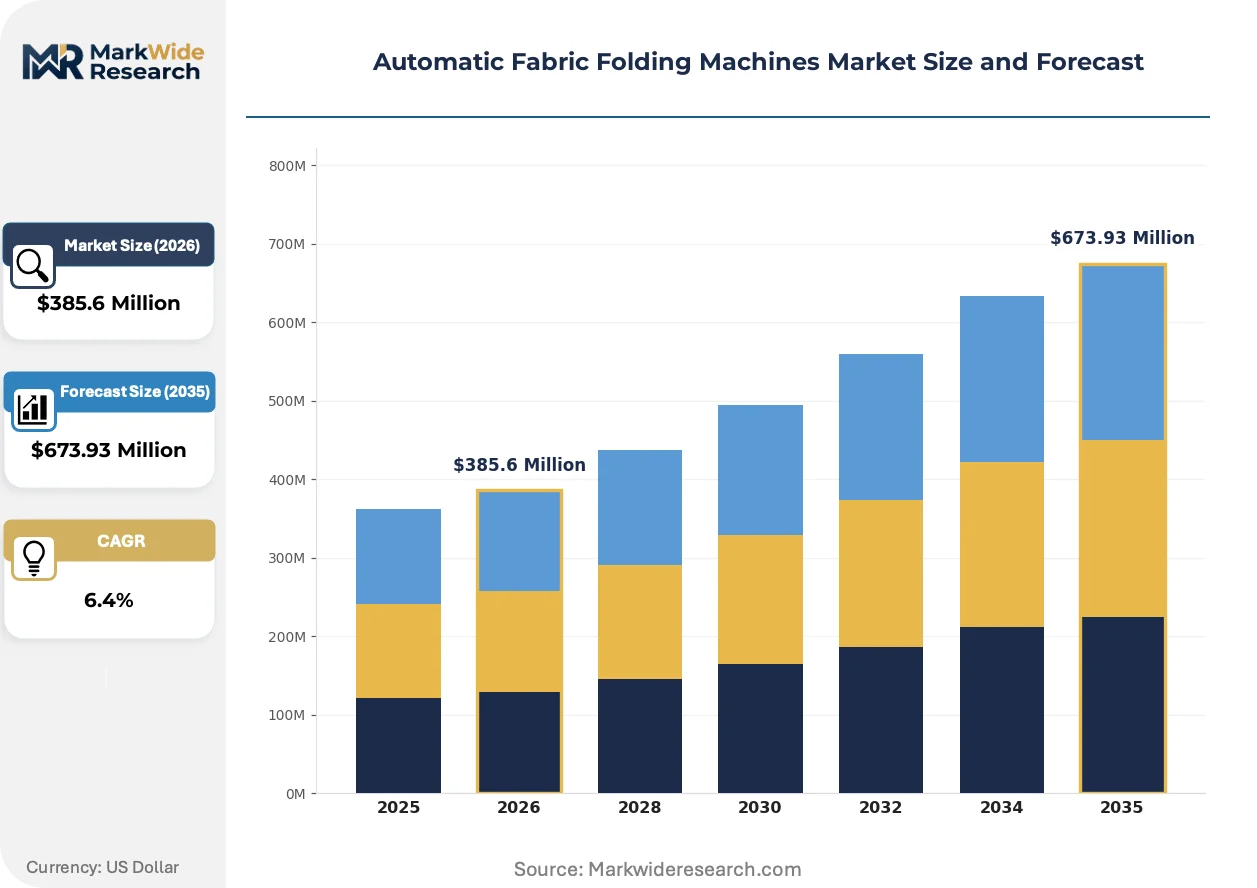
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Fabric Folders, Industrial Folder Machines, Conveyor Folding Systems, Robotic Folding Solutions Technology: Servo Motor Driven, Pneumatic Folding, Hydraulic Systems, Electro-Mechanical Folding Application: Garment Manufacturing, Textile Processing, Linen Services, Home Textile Production, Upholstery Production End User: Clothing Manufacturers, Textile Mills, Commercial Laundries, Upholstery Workshops |
| Companies Covered | Dekken Machinery, Herbert Kannegiesser GmbH, Suntech Industrial, Automatex Inc., Unitex, Suzhou Shengda, Shanghai Youngsun, Veyron, Indemac Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Fabric Folding Machines Market Trends and Innovations
Digital twin technology is virtualizing machine commissioning and fold pattern optimization, compressing deployment timelines for complex multi-station folding configurations.
Vision-guided alignment systems using machine learning algorithms are virtualizing manual fabric positioning tasks previously requiring skilled operator intervention. Industrial laundries serving hospitality chains adopt these systems fastest, driven by overnight turnaround requirements. This virtualization is compressing labor cost differentials between automated and semi-automated folding operations.
China's MIIT technical regulations mandate energy efficiency benchmarks that favor servo-electric architectures over hydraulic folding systems in domestic procurement. Manufacturers must redesign hydraulic platforms or exit the Chinese market entirely. Tier-1 textile mills in Jiangsu and Zhejiang provinces now specify servo-electric folders exclusively in capital tenders.
Buyer preference is consolidating around certified refurbishment programs that extend equipment life cycles while meeting original performance specifications. Second-tier laundries and regional garment finishers increasingly source factory-rebuilt folders with warranty coverage rather than new capital purchases. This rotation is most visible in India's BIS-certified equipment resale channels serving government textile modernization schemes.
Automatic Fabric Folding Machines Market Segmentation
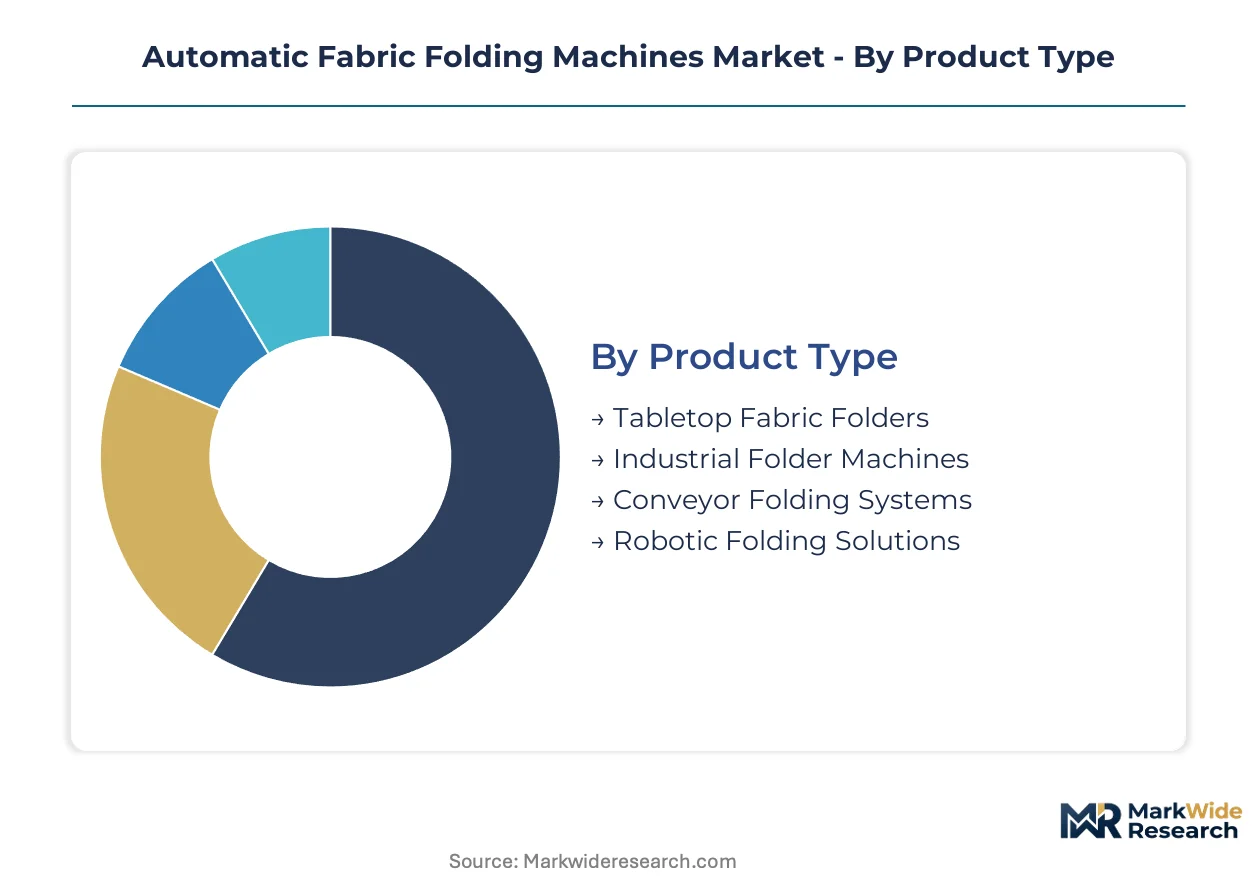
Automatic fabric folding machines serve heterogeneous operational environments where throughput requirements, floor space constraints, and energy infrastructure vary dramatically. Segmentation reveals how equipment specifications align with capital intensity tiers and regulatory compliance burdens across end-use verticals.
Product Type:
After-sales service intensity escalates with system complexity, creating divergent margin structures across equipment tiers.
- Industrial Folder Machines:High-throughput batch processing systems handle continuous textile webs at 2,000-4,000 folds per hour. Commercial laundries in Vietnam's export zones deploy these units to meet hospitality chain turnaround contracts where downtime penalties exceed maintenance premiums.
- Robotic Folding Solutions:Collaborative robot arms with vision-guided alignment enable programmable flexibility for mixed-SKU production runs. Garment manufacturers in India's Tamil Nadu apparel clusters adopt these fastest as fast-fashion brands demand smaller batch sizes with rapid changeover.
- Conveyor Folding Systems:Integrated line configurations synchronize with upstream cutting and downstream packaging equipment. Suntech Industrial dominates Asian procurement through captive manufacturing of conveyor subsystems.
- Tabletop Fabric Folders:Compact units serve upholstery workshops and small garment finishers with limited capital budgets. Dekken Machinery specializes in CE-marked configurations for European craft producers.
Industrial folder machines hold the largest share; momentum sits with robotic folding solutions.
Technology:
Energy efficiency regulations are reconfiguring technology adoption curves across procurement jurisdictions.
- Servo Motor Driven:Electric actuators deliver precision repeatability with 30-40% lower energy consumption versus pneumatic alternatives. EU F-Gas Regulation accelerates displacement of compressed air systems in German and Italian textile finishing facilities.
- Pneumatic Folding:Legacy compressed air infrastructure persists in Southeast Asian plants where capital replacement cycles extend 10-15 years. Vietnam's cut-make-trim operations retain pneumatic folders due to abundant low-cost compressed air capacity.
- Electro-Mechanical Folding:Hybrid architectures combine electric precision with mechanical simplicity for mid-tier throughput requirements. China's MIIT energy benchmarks favor these configurations in Jiangsu province tenders.
- Hydraulic Systems:High-force actuation for heavy fabric weights in technical textile processing. GB standards compliance costs are forcing domestic Chinese manufacturers to abandon hydraulic platforms entirely.
Servo motor driven systems command the premium tier; electro-mechanical folding is climbing the fastest as a cost-optimized bridge technology.
Application:
Volume concentration and margin structure diverge sharply across textile subsectors.
- Garment Manufacturing:Cut-make-trim operations require programmable folding for diverse SKU portfolios. India's PLI scheme for technical textiles is expanding capital equipment budgets in integrated apparel clusters.
- Linen Services:Hospitality and healthcare laundry chains prioritize throughput reliability over flexibility. Overnight turnaround requirements in European hotel supply chains drive fastest adoption of vision-guided alignment systems.
- Textile Processing:Mill-scale operations handling continuous fabric webs demand synchronization with finishing equipment. Zhejiang province's tier-1 mills specify servo-electric architectures exclusively in capital tenders.
- Home Textile Production:Bedding and towel manufacturers balance batch size flexibility with energy costs. Indonesian government-backed industrial zones in Central Java are creating first-mover opportunities for automated folding deployment.
- Upholstery Production:Small-batch craft operations with irregular fabric dimensions and limited floor space. European upholstery workshops favor compact tabletop configurations with CE marking compliance.
Garment manufacturing absorbs the highest equipment volume; linen services show steepest expansion trajectory as hospitality automation accelerates.
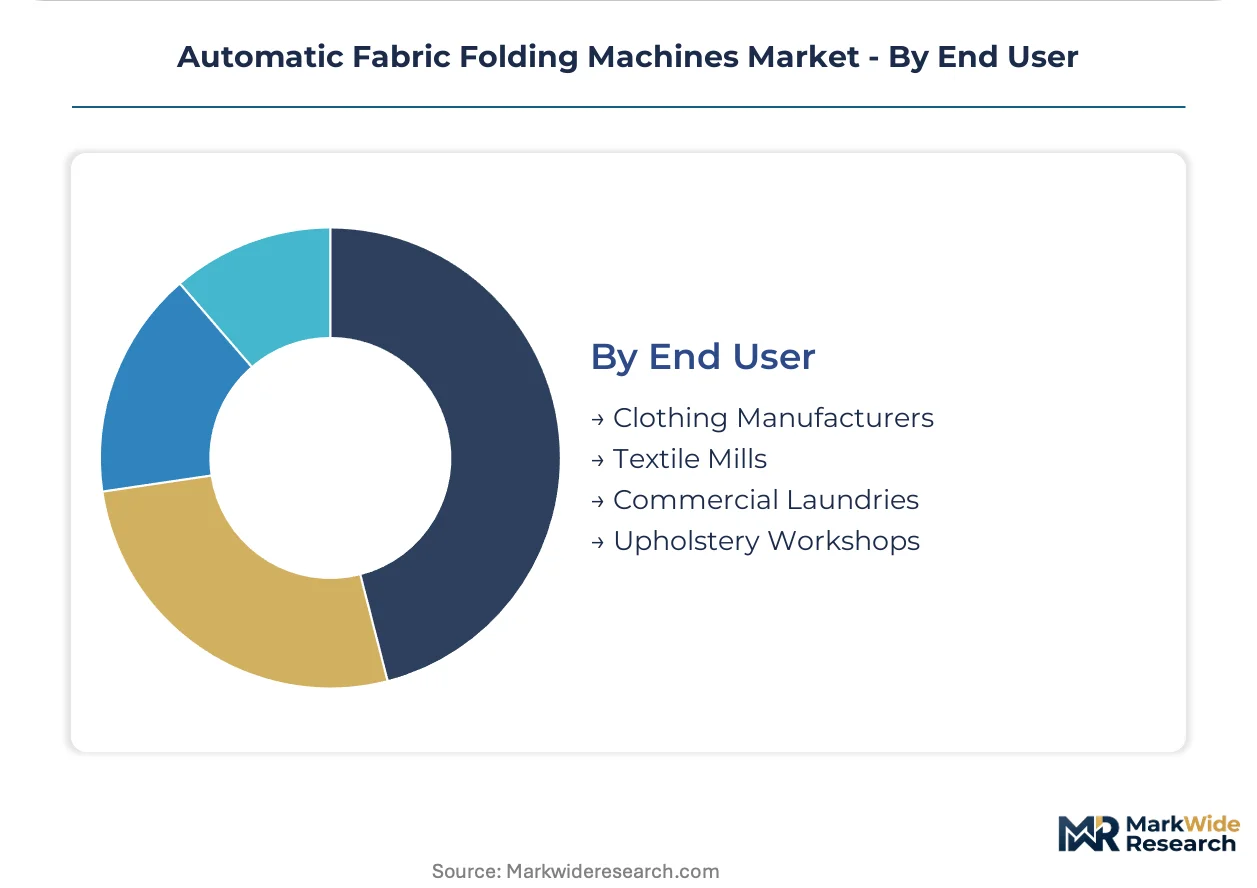
End User:
Procurement authority and financing capacity shape equipment specification decisions.
- Commercial Laundries:Centralized processing facilities serving hospitality and healthcare chains. Equipment-as-a-service financing models are spreading capital burden for mid-scale operators seeking automation without ownership risk.
- Clothing Manufacturers:Export-oriented garment finishers in Vietnam and Bangladesh face wage inflation pressures. These operators prioritize robotic folding for mixed-SKU flexibility demanded by fast-fashion brand contracts.
- Textile Mills:Integrated producers from fiber through finished fabric. China's Jiangsu and Zhejiang provinces are reconfiguring regional supply patterns as domestic manufacturers scale precision engineering capabilities.
- Upholstery Workshops:Small craft producers with irregular batch sizes and severe floor space constraints. India's BIS certification requirements shape vendor qualification for government-backed textile modernization schemes.
Commercial laundries represent the most mature installed base; clothing manufacturers are gaining share fastest as automation offsets labor cost pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CE marking requirements under EU machinery directives anchor the regulatory framework shaping equipment specifications across Western Europe, while MIIT technical regulations in China and BIS certification in India create divergent compliance thresholds that fragment procurement standards.
China
MIIT energy efficiency benchmarks favor servo-electric architectures over hydraulic systems in domestic procurement. Tier-1 textile mills in Jiangsu and Zhejiang provinces now specify servo-electric folders exclusively in capital tenders. Domestic manufacturers in these provinces are scaling precision engineering capabilities to capture share previously held by imported equipment.
Germany
EU F-Gas Regulation accelerates displacement of compressed air systems in textile finishing facilities. CE marking requirements enforce safety interlocks and emergency stop protocols that elevate engineering costs for European-bound equipment. Herbert Kannegiesser GmbH anchors German engineering reputation in high-throughput industrial folder machines for commercial laundries.
India
Production-linked incentives for technical textiles expand capital equipment budgets across integrated apparel clusters in Tamil Nadu and Gujarat. BIS certification for industrial machinery creates compliance thresholds that shape vendor qualification for government-backed textile modernization schemes. Regional garment finishers in these states prioritize automation to offset wage inflation pressures.
Vietnam
Export-oriented textile zones deploy automatic folding machines to offset wage inflation in cut-make-trim operations serving fast-fashion brands. Cut-make-trim operations retain pneumatic folders due to abundant low-cost compressed air capacity. Ho Chi Minh City and surrounding industrial provinces concentrate garment manufacturing automation investment.
United States
Commercial laundries serving hospitality chains adopt vision-guided alignment systems fastest, driven by overnight turnaround requirements. OSHA workplace safety standards influence equipment specification decisions in industrial laundry facilities. Equipment-as-a-service financing models spread capital burden for mid-scale operators seeking automation without ownership risk.
Automatic Fabric Folding Machines Market Competitive Landscape
Precision-engineering specialists and scale-driven Asian fabricators split the market along technology-tier lines. The vendor base concentrates around three strategic archetypes: German engineering houses commanding premium positioning through CE-marked industrial systems, Chinese manufacturers leveraging vertical manufacturing depth for cost-optimized conveyor configurations, and Italian compact-equipment specialists serving craft producers with limited floor space. Competitive dynamics center on M&A activity consolidating component supply chains and strategic partnerships integrating vision-guided alignment systems with legacy folding platforms.
Within the German engineering tier, Herbert Kannegiesser GmbH exemplifies the high-throughput industrial folder machine archetype anchored in commercial laundry applications. Suntech Industrial occupies a position representing scale-driven Asian fabrication, competing across conveyor folding systems through manufacturing depth. Dekken Machinery sits within the compact-equipment specialist archetype, serving upholstery workshops and craft producers with tabletop configurations designed for space-constrained environments.
| Leading Market Players |
|---|
| Dekken Machinery |
| Herbert Kannegiesser GmbH |
| Suntech Industrial |
| Automatex Inc. |
| Unitex |
| Suzhou Shengda |
| Shanghai Youngsun |
| Veyron |
| Indemac Srl |
| Others |
Pricing and Supply Chain Analysis
Jiangsu province's precision engineering cluster shapes downstream pricing power as domestic Chinese manufacturers scale servo-electric architectures and compress import premiums previously commanded by German engineering houses. Tier-1 textile mills in Zhejiang now source exclusively from this regional base, forcing incumbent European suppliers to rebundle after-sales service intensity to defend margin position.
Pricing Analysis
Price spreads between German CE-marked industrial folders and Chinese electro-mechanical alternatives span three performance tiers. Certification grade and after-sales service bundling drive differentiation, with EU F-Gas Regulation compliance adding engineering cost premiums for European-bound equipment. Pricing pressure stems from Vietnamese cut-make-trim operators prioritizing capital efficiency over precision specifications. Small upholstery workshops exhibit highest price sensitivity, while commercial laundries serving hospitality chains absorb premium positioning for reliability guarantees.
Supply Chain Analysis
Export control regimes restricting high-torque servo motor and harmonic drive shipments from Japan and Germany concentrate supply risk for precision motion components. Component sourcing draws from Chinese domestic foundries for structural frames, Taiwanese PLC suppliers for control systems, and German sensor specialists for alignment modules. Single-source vulnerability sits with Japanese harmonic drive manufacturers serving the robotic folding tier. Distribution runs through OEM direct sales for large textile mills, regional equipment distributors for mid-tier laundries, and certified refurbishment channels for price-sensitive garment finishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service contracts and predictive maintenance subscriptions expand faster than hardware shipments as servo system complexity extends equipment life cycles and locks in recurring revenue streams.
For Market Incumbents: Pre-empt component supply consolidation by securing long-term agreements with Japanese harmonic drive specialists before capacity allocation tightens. Anchor backward integration into servo motor assembly within Jiangsu province to neutralize Chinese domestic challengers scaling precision capabilities. CE marking cost escalation for safety interlocks threatens margin compression unless absorbed through service attach rates. For New Entrants and Emerging Players: Pursue certified refurbishment program accreditation as India's BIS-certified resale channels expand under government textile modernization schemes. Indonesia's Central Java industrial zones offer lowest competitive density for first-mover servo-electric deployments. Equipment-as-a-service financing models reduce customer capital barriers and accelerate market entry velocity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because precision mechatronics talent scarcity and component supply concentration favor scaled platforms with captive technical capabilities. Acquisition targets cluster around Italian compact-equipment specialists with CE-marked tabletop configurations and established upholstery workshop distribution. Watch for inflection when Vietnamese export zones mandate servo-electric replacement of pneumatic infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Assembly | Jiangsu province manufacturing depth neutralizes import dependency for precision motion systems. |
| Certified Refurbishment Program Launch | India's BIS certification requirements create compliant secondary market capture for mid-tier operators. |
| Equipment-as-a-Service Financing Model | Subscription structures spread capital burden across Vietnam's wage-pressured garment finishers. |
| Vision-Guided Alignment System Partnership | Machine learning integration enables mixed-SKU flexibility demanded by Tamil Nadu fast-fashion clusters. |
| CE Marking Fast-Track Investment | EU machinery directive compliance accelerates hospitality laundry automation in German and Italian markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, MIIT technical regulation filings, and EU machinery directive compliance databases to anchor market sizing. Primary interviews engaged plant engineers at commercial laundries, OEM procurement teams at textile mills, and aftermarket service heads at equipment distributors. Secondary validation drew from BIS certification registries, Vietnam's export zone investment disclosures, and SEC filings of listed textile automation suppliers. Bottom-up unit economics triangulate against top-down industry absorption capacity estimates.
Forecast inputs incorporate technology substitution curves, regulatory compliance cost trajectories, and regional wage inflation differentials across the projection horizon. Segmentation dimensions span product type, actuation technology, application vertical, and end-user procurement authority. CAGRs derive from installed base replacement cycles and greenfield capacity additions in prioritized textile clusters. Industry-specific inputs include EU F-Gas Regulation phase-down schedules and India's PLI scheme disbursement patterns for technical textiles.
Sensitivities concentrate around Japanese-German component supply restrictions and Indonesian industrial zone development timelines. Forecasts reflect assumptions on servo-electric displacement velocity and refurbishment market formalization. Material shifts in EU machinery directive enforcement stringency or Chinese MIIT energy benchmark revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Embroidery Machine Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market