
 Middle East and Africa Textile Films Market | 2026-2036
Middle East and Africa Textile Films Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Textile Films Market Foresight
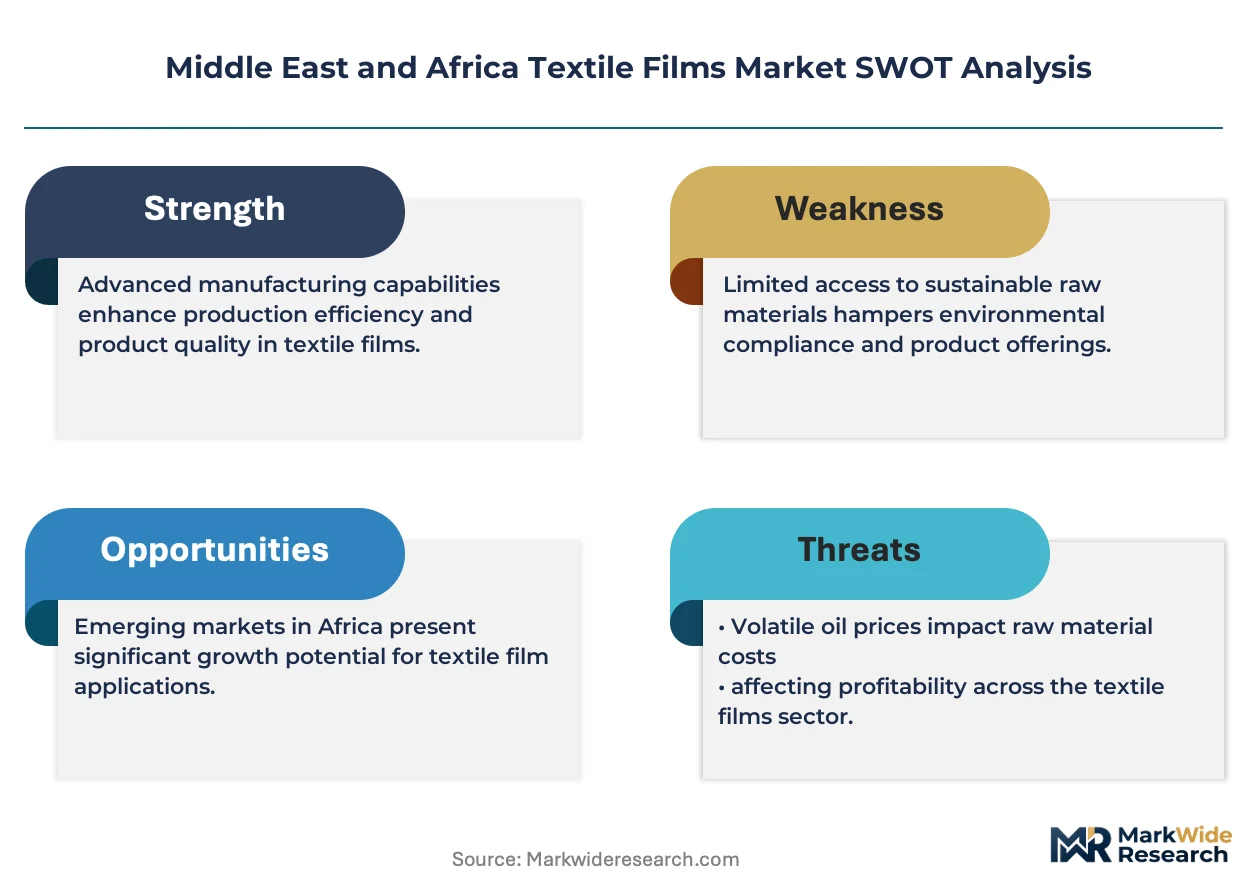
REACH compliance certification is unwinding the competitive landscape for European-origin suppliers serving North African converters. Covestro AG leverages its polyurethane film expertise to anchor premium breathable membrane contracts with Moroccan automotive seat producers. Berry Global Group sustains volume leadership through backward integration into blown polyethylene operations in South Africa's KwaZulu-Natal industrial zone. DuPont de Nemours differentiates via fluoropolymer barrier films for Saudi Arabian protective textile applications.
Textile films are thin-gauge polymer membranes, typically 12-250 microns in caliper, manufactured through cast extrusion or blown film processes with optional biaxial orientation to control tensile strength and moisture vapor transmission rates; they function as protective laminates, adhesive carriers, and functional barriers in fabric assembly systems. Polyethylene dominates volume across the region due to cost efficiency in Egyptian and Nigerian packaging-to-textile conversion lines, while polyester films command margin premiums in South African automotive interior lamination where thermal stability requirements exceed 150°C service temperatures. Biodegradable feature grades are gaining fastest traction among East African exporters responding to EU Green Deal-aligned procurement standards.
South Africa's Department of Forestry, Fisheries and Environment enforces Extended Producer Responsibility regulations that mandate recycled content thresholds in plastic films, while Egypt's Egyptian Organization for Standardization and Quality implements GB-harmonized testing protocols for textile-contact polymer safety. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations for building material films indirectly shape construction textile film specifications across Gulf Cooperation Council supply chains. Stakeholders must monitor divergence between EU REACH-aligned import requirements and emerging local content rules as North African governments negotiate trade facilitation terms.
Market Dynamics
Egyptian garment exporters are consolidating film procurement around REACH-aligned European suppliers as EU Green Deal procurement standards penetrate North African supply chains, compressing margins for non-certified converters.
Growth Catalysts
- EU Green Deal procurement standards:East African farming cooperatives are accelerating biodegradable mulch film adoption to maintain export access to European agricultural markets.
- Automotive interior lamination:South African seat producers are expanding polyester film specifications for thermal stability above 150°C in premium vehicle programs.
- Nile Delta farming corridor:Egyptian agricultural cooperatives are scaling greenhouse cover installations across Alexandria-Damietta production zones.
Market Restraints
- Ethylene feedstock volatility:Nigerian and Egyptian blown film operations face margin compression from naphtha-linked polyethylene resin cost swings.
- Single-source fluoropolymer supply:Saudi Arabian protective textile producers depend on limited import channels for high-barrier membrane grades.
- Biodegradable degradation rates:East African mulch films exhibit inconsistent soil-breakdown performance across variable rainfall zones.
Strategic Opportunities
- Moroccan automotive seat production:Premium breathable membrane contracts remain underpenetrated relative to European tier-1 supplier presence.
- KwaZulu-Natal backward integration:Blown polyethylene captive supply creates margin capture potential for regional packaging-to-textile converters.
- SASO technical regulations:Gulf Cooperation Council building material film standards are redirecting construction textile specifications toward certified regional producers.
Industry Challenges
- REACH certification timelines:Egyptian converters face 12-18 month approval cycles for European-origin chemical compliance documentation.
- Blown-to-cast extrusion retooling:Nigerian film producers require significant capex to shift from commodity packaging toward precision textile laminate grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Textile Films Market |
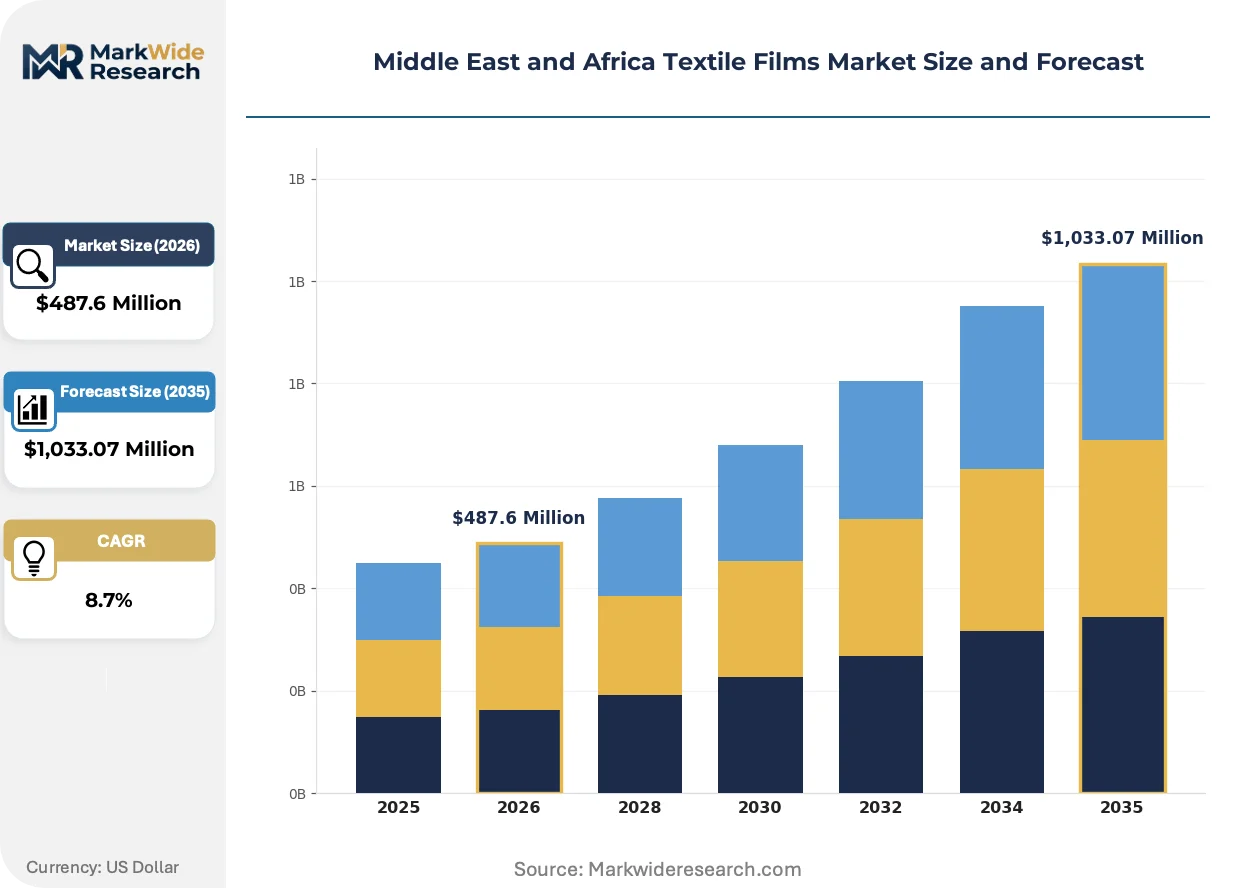
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyester, Nylon Application: Agriculture, Packaging, Construction, Automotive End User: Textile Manufacturers, Retailers, Wholesalers, Exporters Feature: Biodegradable, Waterproof, UV Resistant, Stretchable |
| Companies Covered | Covestro AG, Arkema SA, RKW Group, Toray Industries, Mitsui Chemicals, Berry Global Group, DuPont de Nemours, Schweitzer-Mauduit, Polifilm Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Textile Films Market Shifts & Advancements
Polymer film functionality is bifurcating between commodity polyethylene volume plays and engineered barrier membranes commanding technical premiums in automotive and protective textile segments.
Bio-based polyethylene films manufactured from sugarcane ethanol feedstock are displacing fossil-derived grades in East African export-oriented agricultural applications. Kenyan and Tanzanian farming cooperatives are specifying certified biodegradable mulch films to preempt EU import compliance audits. This displacement is compressing conventional polyethylene margins while creating dual-certification requirements for regional distributors.
South Africa's Extended Producer Responsibility regulations are mandating recycled content thresholds in plastic films across all packaging-to-textile conversion lines. The country's Department of Forestry, Fisheries and Environment enforcement is redirecting procurement toward post-consumer recycled polyethylene grades. Automotive interior lamination segments in Gauteng and Eastern Cape manufacturing zones are responding with closed-loop collection partnerships.
Direct mill-to-garment-producer contracting is eroding traditional distributor networks in Egypt's Alexandria-Damietta textile corridor. Export-oriented garment producers are negotiating volume commitments with certified European film suppliers to lock in REACH documentation continuity. This channel compression is most visible among mid-scale converters previously dependent on Cairo-based chemical traders for spot polyethylene purchases.
Middle East and Africa Textile Films Market Segmentation
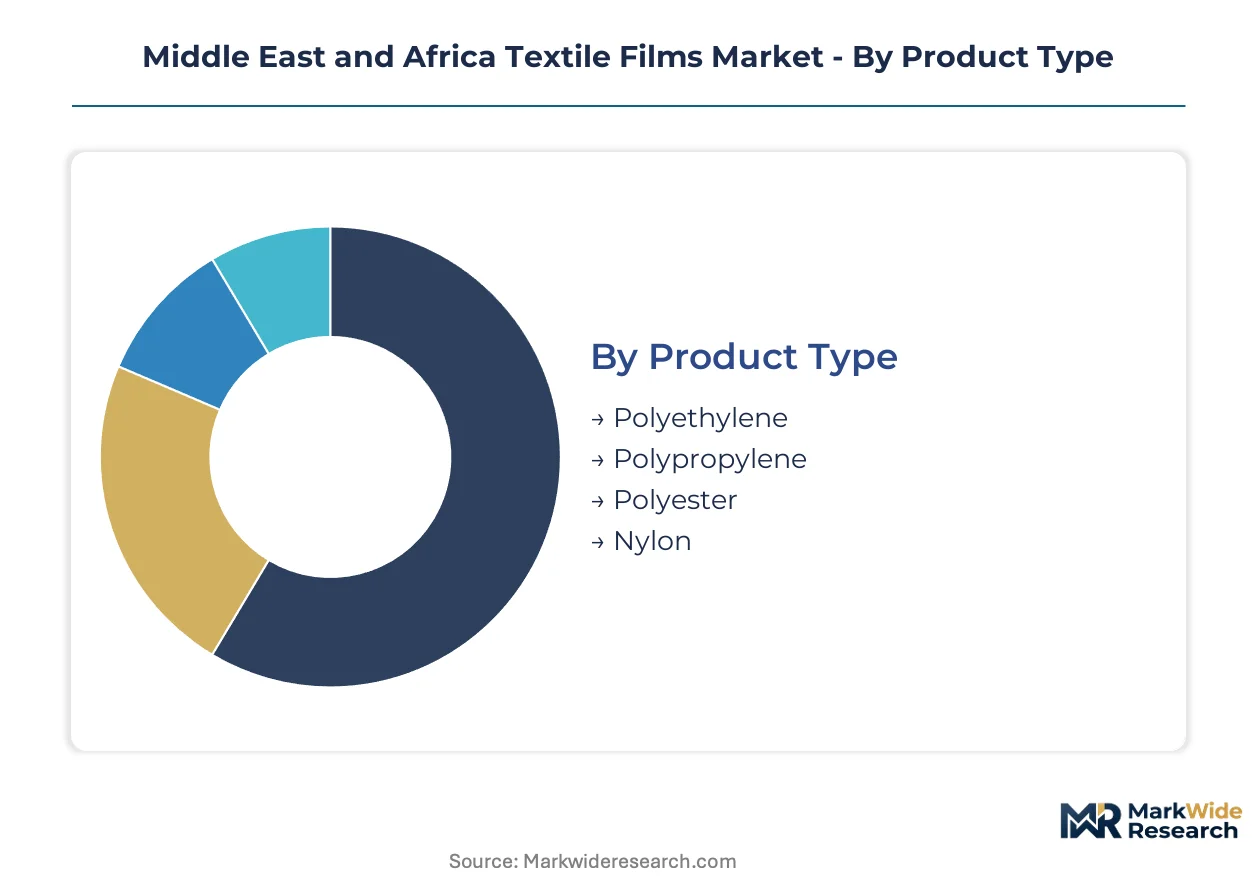
Segmentation in Middle East and Africa textile films reveals how resin chemistry, end-use performance requirements, and regulatory compliance layers interact to determine pricing power. Buyers in Egyptian garment export corridors and South African automotive lamination zones source from distinct specification tiers with limited substitutability.
Product Type:
Margin pools concentrate in specialty grades where thermal stability and barrier specifications command technical premiums over commodity blown film.
- Polyethylene:Blown and cast extrusion grades dominate Egyptian packaging-to-textile conversion corridors, with linear low-density variants preferred for agricultural mulch films across the Nile Delta. Nigerian processors rely on naphtha-linked feedstock for cost-sensitive garment interlining applications.
- Polyester:Biaxially oriented films serve South African automotive interior lamination where service temperatures exceed 150°C, with Gauteng seat producers specifying crystalline grades for thermal dimensional stability. Premium vehicle programs in Morocco's Tangier Automotive City are accelerating biaxial polyester adoption for dashboard and door panel substrates.
- Polypropylene:Cast film lines in Tunisia supply breathable medical textile laminates with controlled moisture vapor transmission rates.
- Nylon:High-barrier coextruded grades protect Saudi Arabian industrial protective textiles from hydrocarbon penetration.
Polyethylene holds installed capacity across Alexandria-Damietta conversion corridors. Polyester is rotating up the share rankings in automotive specification tenders.
Application:
Application-driven procurement separates agricultural volume plays from construction and automotive technical premiums.
- Agriculture:Greenhouse covers and biodegradable mulch films concentrate demand among East African farming cooperatives responding to EU Green Deal procurement standards. Kenyan and Tanzanian exporters specify certified soil-degradable grades to preempt import compliance audits, compressing conventional polyethylene margins.
- Automotive:Interior lamination specifications in South Africa's Eastern Cape and Morocco's Casablanca-Rabat industrial zones require thermal stability certification above 150°C. Berry Global's KwaZulu-Natal backward integration into blown polyethylene operations supplies captive feedstock for seat producer contracts.
- Packaging:Garment export corridors from Alexandria to Damietta source breathable polyethylene films for moisture-managed retail packaging.
- Construction:SASO technical regulations for Gulf Cooperation Council building materials redirect procurement toward certified regional producers of weatherproof membrane substrates.
Agriculture maintains volume leadership across Nile Delta and East African highland farming zones. Automotive is climbing the fastest as Moroccan and South African vehicle assembly expands technical film specifications.
End User:
Customer type determines whether procurement flows through distributor networks or direct mill-to-garment-producer contracting.
- Textile Manufacturers:Egyptian export-oriented garment producers in the Alexandria-Damietta corridor negotiate volume commitments directly with REACH-certified European film suppliers. Direct contracting erodes traditional Cairo-based chemical trader networks.
- Exporters:East African farming cooperatives specify dual-certified biodegradable grades to maintain EU market access.
- Retailers:South African mass-market apparel chains source commodity polyethylene laminates through consolidated distributor arrangements.
- Wholesalers:Nigerian converters aggregate spot purchases for domestic garment interlining applications.
Textile Manufacturers hold established procurement relationships with certified suppliers. Exporters are rotating up the share rankings as compliance documentation becomes a competitive gate.
Feature:
Functional differentiation separates price-competitive commodity grades from specification-driven premium tiers.
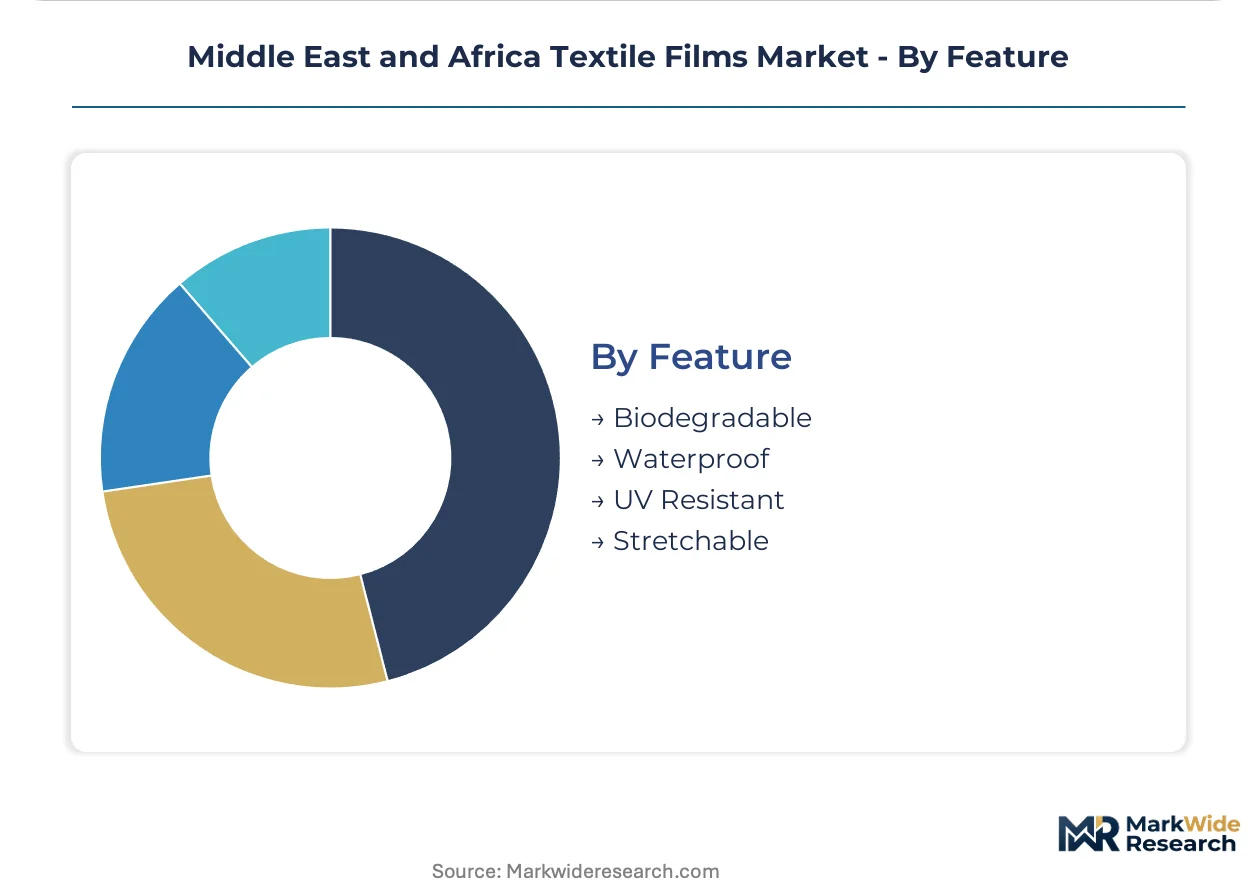
- Biodegradable:Certified soil-degradable polyethylene films manufactured from sugarcane ethanol feedstock displace fossil-derived grades in Kenyan and Tanzanian export agriculture. South Africa's Extended Producer Responsibility regulations mandate recycled content thresholds that redirect procurement toward post-consumer recycled and bio-based alternatives.
- Waterproof:Fluoropolymer barrier films for Saudi Arabian protective textile applications depend on limited import channels, creating supply concentration risk.
- UV Resistant:Stabilized greenhouse cover grades extend service life across variable East African rainfall zones.
- Stretchable:Elastic recovery specifications serve Moroccan automotive seat producers requiring conformable membrane substrates.
Biodegradable holds installed certification capacity among EU-export-oriented agricultural suppliers. Waterproof is rotating up the share rankings as Saudi industrial protective textile specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented garment producers and automotive seat manufacturers concentrate procurement across distinct national corridors, with compliance documentation and thermal specification requirements determining supplier access.
Egypt
Alexandria-Damietta textile exporters source REACH-certified breathable films for EU-bound garment shipments. The Egyptian Organization for Standardization and Quality enforces GB-harmonized polymer safety testing. Cairo-based chemical traders are losing share to direct mill-to-producer contracting as documentation requirements tighten.
South Africa
Gauteng and Eastern Cape automotive plants specify polyester films exceeding 150°C thermal stability for interior lamination. The Department of Forestry, Fisheries and Environment mandates recycled content thresholds under Extended Producer Responsibility regulations. Berry Global's KwaZulu-Natal blown polyethylene operations supply captive feedstock to regional seat producers.
Saudi Arabia
Industrial protective textile manufacturers import fluoropolymer barrier films for hydrocarbon-resistant applications. SASO technical regulations for building materials indirectly shape construction textile film specifications. Riyadh-based converters face limited supply channels for high-barrier membrane grades.
Morocco
Tangier Automotive City and Casablanca-Rabat zones are expanding biaxial polyester adoption for dashboard and door panel substrates. Premium breathable membrane contracts for automotive seating remain underpenetrated relative to European tier-1 presence. Local converters are positioning for technical specification upgrades.
Kenya and Tanzania
Farming cooperatives specify sugarcane ethanol-derived biodegradable mulch films to maintain EU agricultural export access. EU Green Deal procurement standards drive dual-certification requirements for soil-degradable grades. Nairobi and Dar es Salaam distributors face margin compression from certified-grade displacement of conventional polyethylene.
Middle East and Africa Textile Films Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with film divisions alongside specialized polymer membrane producers. Market structure shows moderate consolidation around resin-integrated operations and technical-grade specialists. Strategic archetypes include backward-integrated volume leaders, premium barrier membrane licensors, and regional conversion specialists. Competitive moves center on REACH certification alignment and captive resin supply security.
Among European-origin chemical conglomerates, Covestro AG and Arkema SA exemplify premium breathable membrane and barrier film positioning. Berry Global Group represents the backward-integrated archetype with captive polyethylene supply. DuPont de Nemours occupies the high-performance fluoropolymer tier for protective textile applications. These anchors illustrate how technical specification depth and regulatory certification capacity determine contract access across Egyptian automotive and Saudi industrial segments.
| Leading Market Players |
|---|
| Covestro AG |
| Arkema SA |
| RKW Group |
| Toray Industries |
| Mitsui Chemicals |
| Berry Global Group |
| DuPont de Nemours |
| Schweitzer-Mauduit |
| Polifilm Group |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Egyptian garment exporters and REACH-certified European suppliers lock in both resin access and price visibility, insulating procurement teams from naphtha-linked polyethylene volatility while compressing margins for Cairo-based spot traders. These arrangements concentrate purchasing power among documentation-compliant buyers across the Alexandria-Damietta corridor.
Pricing Analysis
Cost-plus contracts with naphtha indexation dominate Egyptian and Nigerian blown film procurement, passing through feedstock swings to garment interlining and agricultural mulch film buyers. Price differentiation separates REACH-certified premium grades from uncertified commodity polyethylene, with South African automotive seat producers least sensitive due to thermal stability specifications above 150°C. Cost compression in East African biodegradable grades is intensifying because sugarcane ethanol feedstock premiums face EU Green Deal compliance audits. Nigerian domestic converters exhibit highest price sensitivity, aggregating spot purchases for cost-sensitive garment applications.
Supply Chain Analysis
Strategic stockpiling of polyethylene resin prevails among Egyptian converters buffering against naphtha volatility, while South African automotive laminators favor just-in-time polyester film deliveries from Gauteng distributors. Supply concentrates in Egypt, South Africa, and Saudi Arabia for regional conversion, with raw material dependencies on naphtha-derived ethylene, biaxial orientation equipment, and fluoropolymer barrier resins. Single-source vulnerability runs through Saudi Arabian high-barrier membrane channels. Distribution runs through direct mill-to-producer contracting eroding traditional Cairo chemical trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical certification services and compliance documentation layers expand faster than base resin supply in this market, creating recurring-revenue attachment opportunities for accredited testing bodies and regulatory consultancies serving Egyptian export corridors.
For Market Incumbents: Fortify backward integration into blown polyethylene operations following Berry Global's KwaZulu-Natal captive supply model, while deepening REACH certification investment to defend against emerging bio-based polyethylene specialists from East Asia. Channel control through direct contracting with Alexandria-Damietta garment producers blocks trader-network erosion. For New Entrants and Emerging Players: Differentiate on dual-certified biodegradable grades combining EU Green Deal alignment with SASO technical compliance for Gulf Cooperation Council construction textile specifications. Moroccan automotive seat production presents the most penetrable white-space, with premium breathable membrane contracts underrepresented relative to European tier-1 presence. A technical specification partnership with Tangier Automotive City seat producers offers credible go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward resin-integrated regional specialists with captive polyethylene supply and established REACH documentation workflows, as these assets compound procurement advantages across the analysis window. Acquisition targets should display backward integration into Egyptian or South African conversion corridors. The signal to watch is divergence between EU import requirements and emerging North African local content rules during trade facilitation negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive polyethylene supply in KwaZulu-Natal secures margin capture for South African automotive contracts. |
| REACH Certification Investment | Twelve-to-eighteen month approval cycles create defensive moats for Egyptian garment corridor suppliers. |
| Bio-based Feedstock Transition | Sugarcane ethanol-derived grades preempt EU Green Deal compliance audits for East African farming cooperatives. |
| Direct Mill Contracting | Volume commitments with Alexandria-Damietta producers displace Cairo-based chemical trader networks. |
| Automotive Specification Partnership | Tangier Automotive City relationships unlock premium breathable membrane penetration in Moroccan seat production. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with polymer film procurement managers at Egyptian garment exporters, technical specification leads at South African automotive seat producers, plant managers at Nigerian blown film operations, and distribution channel partners in Nairobi and Dar es Salaam. Secondary validation drew from Egyptian Organization for Standardization and Quality testing protocols, South African Department of Forestry, Fisheries and Environment EPR enforcement records, SASO technical regulations, customs trade data for polyethylene resin imports, and SEC filings from diversified chemical conglomerates. Bottom-up volume modeling triangulated against top-down resin consumption estimates.
Across the projection horizon, the analytical framework segmented volume and value outputs by resin chemistry tier, end-use application intensity, certification compliance level, and regional production hub concentration. CAGRs were derived from trend extrapolation of segment-specific adoption curves calibrated to regulatory enforcement timelines and automotive program launch cycles. Forecast inputs incorporated naphtha-to-polyethylene spread assumptions, EU Green Deal procurement standard penetration rates, and biodegradable degradation performance variability across East African rainfall zones.
The analysis sits within stated boundaries; outcomes outside sustained REACH alignment enforcement or stable naphtha feedstock pricing would require recalibration. Forecasts reflect documented assumptions regarding regulatory continuity, resin capacity expansion schedules, and automotive platform thermal specification stability. Revision becomes warranted when biodegradable certification audit failure rates cross thresholds that trigger EU import restriction protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Global Textile Machinery Market