
 Sewing Machine Component Market | 2026-2036
Sewing Machine Component Market Size, Share, and Industry Trends Forecast 2026-2036
Sewing Machine Component Market Insights
Asset-light leasing models for industrial sewing equipment is reconfiguring how component suppliers secure long-term contracts. Brother Industries leverages captive production of electronic control modules to sustain margin pools in computerized segments. JUKI Corporation anchors its position through vertical integration into precision needle bar manufacturing. Jack Sewing Machine Co., Ltd. competes aggressively on direct drive motor cost structures across Asian assembly plants.
Sewing machine components comprise precision-machined metal and polymer subsystems including needle bars, presser feet, feed dogs, tension assemblies, and bobbin cases, typically manufactured to tolerances within 0.01 millimeters to ensure stitch consistency at speeds exceeding 5,000 revolutions per minute. These components translate rotary motor motion into controlled fabric transport and thread interlocking for industrial and consumer textile assembly. Computerized and direct drive technology segments command premium positioning as garment manufacturers replace mechanical clutch motors with servo-controlled systems that reduce energy consumption and enable programmable stitch patterns. Needle bar and feed dog component categories absorb disproportionate replacement demand due to mechanical wear in high-cycle industrial environments.
China's GB standards for industrial sewing machinery and the EU's CE marking requirements for electronic equipment shape component design rules across export supply chains, with REACH compliance adding material constraints on metal alloys and surface coatings. The US FDA does not directly regulate sewing components, but OSHA workplace safety standards influence guarding and emergency-stop integration on industrial machines. Stakeholders must monitor how evolving energy-efficiency mandates in Asian manufacturing hubs alter motor and drive system specifications before committing to multi-year component supply agreements.
Market Dynamics
Direct drive motor adoption in Bangladesh and Vietnam garment factories is compressing mechanical clutch motor demand, forcing component suppliers to retool feed dog and tension assembly production lines for servo-compatible architectures.
Growth Catalysts
- China's GB Standards Tightening:Precision tolerance mandates for industrial feed dogs and needle bars are accelerating replacement cycles in export-oriented assembly plants.
- Energy Efficiency Mandates:Asian manufacturing hubs are phasing out mechanical clutch motors, creating pull-through demand for servo control modules and compatible tension assemblies.
- Automated Stitching Lines:Apparel manufacturers in Bangladesh and Vietnam are expanding computerized sewing floors that require precision-machined components rated for 5,000+ RPM operation.
Market Restraints
- Specialized Alloy Input Costs:High-grade tool steel and surface-hardened alloys for needle bars face price volatility tied to specialty metal markets.
- East Asian Supply Concentration:Precision machining capacity clusters in China's Zhejiang and Guangdong provinces, creating geographic risk for OEMs.
- REACH Material Constraints:EU coating and surface treatment restrictions limit alloy composition options for components bound for European textile machinery.
Strategic Opportunities
- Underpenetrated African Assembly:Ethiopia and Kenya garment export zones lack localized component supply chains for direct drive retrofits.
- Leasing Model Penetration:Asset-light equipment financing in Southeast Asia creates recurring component replacement revenue streams.
- PLI Scheme Alignment:India's production-linked incentive schemes for textile machinery offer cost offsets for precision component manufacturing investments.
Industry Challenges
- Servo Calibration Expertise Gap:Industrial maintenance technicians lack training for direct drive motor and computerized control module diagnostics.
- Legacy Mechanical Integration:Garment factories running mixed fleets face compatibility friction between new servo components and existing clutch motor frames.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sewing Machine Component Market |
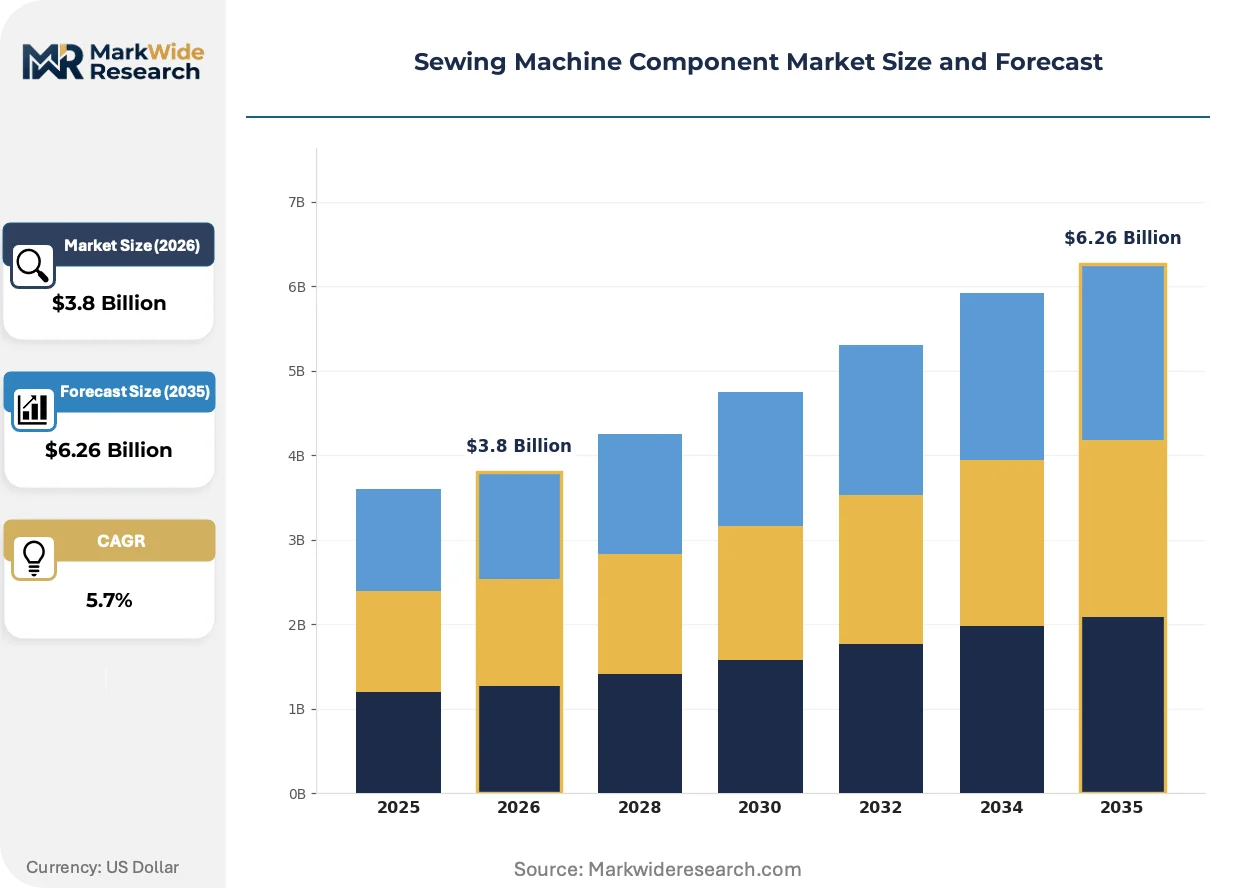
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Needle Bar, Presser Foot, Feed Dog, Tension Assembly, Bobbin Case Technology: Mechanical, Electronic, Computerized, Programmable, Direct Drive Application: Garment Manufacturing, Upholstery, Footwear Production, Embroidery Creation, Leatherwork End User: Tailoring Workshops, Textile Manufacturers, Craft Hobbyists, Industrial Apparel Producers, Custom Outfitters |
| Companies Covered | Brother Industries, JUKI Corporation, Janome Sewing Machine Co., Ltd., SVP Worldwide, BERNINA International AG, Jack Sewing Machine Co., Ltd., Pegasus Sewing Machine Mfg. Co., Ltd., Seiko Sewing Machine Co., Ltd., Dürkopp Adler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sewing Machine Component Market Trends and Innovations
Component architectures are converging around mechatronic integration, with precision metal subsystems increasingly co-designed with electronic control modules rather than specified separately.
Direct drive servo technology is hybridizing mechanical power transmission with programmable motion control. High-volume garment exporters in Vietnam are retrofitting existing mechanical frames with servo motor kits at accelerating pace. This convergence is compressing the traditional boundary between motor suppliers and precision machined component vendors.
China's GB standards for industrial sewing machinery are mandating tighter dimensional tolerances on feed dogs and needle bars. The regulatory pressure is forcing smaller machining shops to upgrade CNC capability or exit the supply chain. Component categories bound for EU markets face additional REACH compliance layers on surface coatings and metal alloys.
After-sales service unbundling is separating component replacement from original equipment vendor relationships. Large Bangladeshi garment groups are establishing direct procurement channels with precision machining specialists, bypassing traditional distributor networks. This channel compression is most visible in high-wear categories like bobbin cases and tension assemblies where replacement frequency creates volume leverage.
Sewing Machine Component Market Segmentation
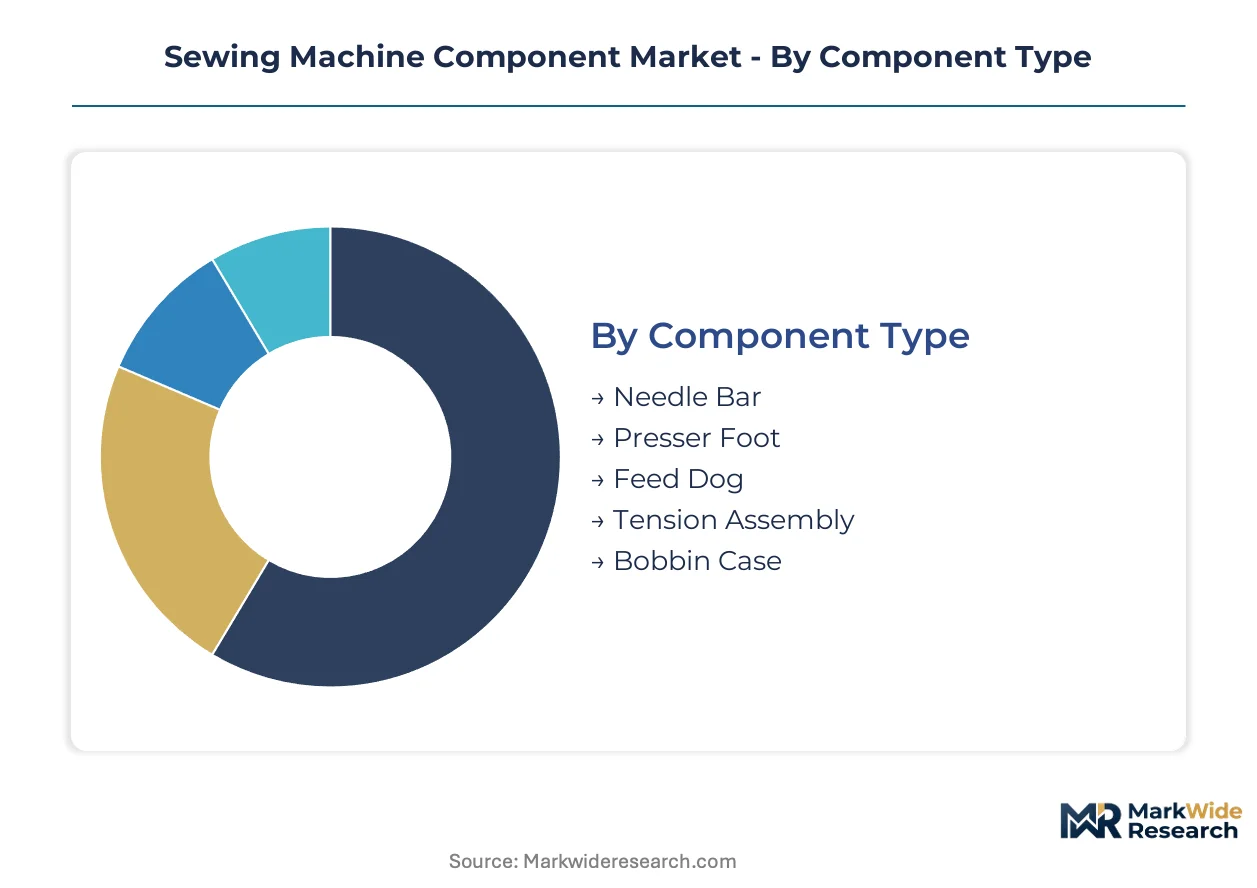
Precision component suppliers must align machining capacity with distinct wear profiles and technology migration paths. Each segmentation dimension reveals diverging margin structures and replacement cycle dynamics across industrial and consumer end-uses.
Component Type:
Cost tier differentiation separates high-wear consumables from precision-machined subsystems with extended service intervals.
- Needle Bar:Hardened steel shafts with surface treatments withstand reciprocating loads exceeding 5,000 RPM in industrial environments. Bangladeshi garment exporters are accelerating replacement schedules as China's GB standards tighten dimensional tolerances on precision-ground surfaces.
- Feed Dog:Serrated metal transport mechanisms engage fabric layers with calibrated tooth geometry for stitch consistency. Vietnamese assembly plants retrofitting servo systems demand feed dogs redesigned for direct drive motor torque profiles rather than mechanical clutch engagement patterns.
- Presser Foot:Spring-loaded clamping assemblies maintain fabric contact pressure across varying material thicknesses.
- Tension Assembly:Spring-disk mechanisms regulate upper and lower thread balance during stitch formation.
- Bobbin Case:Precision-machined housings secure rotating thread spools in hook-and-bobbin systems.
Needle Bar holds installed capacity. Feed Dog is rotating up the share rankings.
Technology:
Application requirements drive technology selection from basic mechanical systems to integrated mechatronic platforms.
- Direct Drive:Servo motors mounted directly on machine shafts eliminate belt transmission losses and enable programmable speed curves. Bangladesh and Vietnam garment factories are phasing out mechanical clutch motors under energy efficiency mandates, pulling demand for servo-compatible component architectures.
- Computerized:Microprocessor-controlled stitch pattern selection and automated thread trimming require precision-machined mechanical subsystems paired with electronic modules. China's GB standards for industrial sewing machinery are accelerating OEM adoption of computerized control systems in export-oriented assembly plants.
- Mechanical:Clutch motor and cam-driven stitch selection systems dominate legacy installed base.
- Electronic:Solid-state speed control without full programmability occupies mid-tier positioning.
- Programmable:Stored pattern memory with automated sequencing commands premium pricing.
Mechanical retains volume dominance. Direct Drive is expanding most quickly.
Application:
Volume concentration varies sharply across end-use categories with diverging precision and durability requirements.
- Garment Manufacturing:High-speed assembly lines for woven and knit apparel demand components rated for continuous operation with minimal downtime. East Asian textile clusters in Bangladesh and Vietnam are expanding automated stitching floors that require precision-machined subsystems certified for 5,000+ RPM duty cycles.
- Footwear Production:Heavy-duty stitching of leather and synthetic uppers requires reinforced needle bars and presser feet with elevated feed force capacity. Chinese component suppliers are developing specialized alloy formulations to meet durability demands in footwear assembly environments.
- Upholstery:Thick fabric and padding layers require extended presser foot lift and reinforced feed mechanisms.
- Embroidery Creation:Multi-head automated systems demand synchronized component arrays with tight positional tolerance.
- Leatherwork:Dense material penetration requires hardened needle configurations and enhanced presser foot pressure.
Garment Manufacturing commands production scale. Footwear Production is gaining share fastest.
End User:
Customer type determines procurement channel structure and replacement part accessibility.
- Industrial Apparel Producers:Large-scale garment exporters operate dedicated maintenance departments with direct component sourcing relationships. Bangladeshi garment groups are establishing procurement channels with precision machining specialists, bypassing traditional distributor networks for high-wear categories like bobbin cases and tension assemblies.
- Textile Manufacturers:Integrated fabric and garment operations maintain mixed fleets of mechanical and computerized equipment. Vietnam's export-oriented textile mills face compatibility friction when retrofitting servo components onto existing clutch motor frames.
- Tailoring Workshops:Small-batch operations rely on distributor networks for sporadic replacement needs.
- Craft Hobbyists:Consumer-grade machines require lower-precision components with reduced duty ratings.
- Custom Outfitters:Bespoke garment producers balance precision requirements with lower utilization intensity.
Industrial Apparel Producers anchor procurement volume. Textile Manufacturers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes across Asian manufacturing hubs are redirecting component procurement flows toward domestic precision machining capacity. Vietnam and Bangladesh garment exporters face tightening energy-efficiency mandates that accelerate servo motor retrofits. China's GB standards are forcing supplier consolidation in Zhejiang and Guangdong industrial clusters.
China
Zhejiang and Guangdong province machining shops supply feed dogs and needle bars to global OEMs under tightening GB precision tolerance mandates. The country's MIIT dual carbon goals pressure garment factories to phase out mechanical clutch motors. Dongguan and Ningbo industrial districts concentrate CNC capacity upgrades for servo-compatible component architectures.
Vietnam
Ho Chi Minh City and Hanoi garment export zones expand automated stitching floors requiring 5,000+ RPM rated subsystems. The country's Ministry of Industry and Trade enforces energy efficiency codes that pull demand for direct drive motor kits. Binh Duong and Dong Nai provinces host retrofit service clusters for mixed mechanical-servo fleet compatibility.
Bangladesh
Dhaka and Chittagong garment groups establish direct procurement channels with precision machining specialists for high-wear categories. The country's central bank export financing schemes support automated line expansion. Gazipur and Narayanganj industrial zones concentrate tension assembly and bobbin case replacement demand from 24-hour production cycles.
India
Tamil Nadu and Gujarat textile machinery manufacturers align with PLI scheme cost offsets for precision component investments. The country's BIS certification requirements shape feed dog alloy specifications for domestic and export equipment. Surat and Tiruppur clusters drive demand for computerized control module integration in garment assembly.
Germany
Baden-Württemberg and Bavaria industrial sewing equipment OEMs source hardened needle bar alloys under REACH surface coating constraints. The country's KBA-equivalent machinery safety standards influence emergency-stop component integration. Stuttgart and Munich engineering centers co-design mechatronic subsystems with Asian assembly plant specifications.
Sewing Machine Component Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin pools in the sewing machine component market. The structure fragments between captive electronic module producers and independent precision machining houses serving replacement part demand. Three archetypes dominate: vertically integrated sewing equipment OEMs with captive component supply, independent precision metal fabricators focused on high-wear consumables, and mechatronic specialists bridging servo motor and mechanical subsystem integration. Competitive moves concentrate on backward integration into precision machining capacity and geographic expansion into underpenetrated African and South Asian assembly zones.
Among Japanese industrial equipment manufacturers, Brother Industries, JUKI Corporation, and Seiko Sewing Machine Co., Ltd. exemplify divergent strategic positioning within the component supply chain. Brother Industries occupies a position representing captive electronic control module production integrated with downstream equipment assembly. JUKI Corporation anchors a tier characterized by upstream control over precision needle bar manufacturing capacity. Seiko Sewing Machine Co., Ltd. sits within a specialization cluster focused on industrial-grade subsystems for high-cycle garment production environments. These three entities collectively illustrate how geographic origin and corporate structure shape competitive archetype selection in precision component markets.
| Leading Market Players |
|---|
| Brother Industries |
| JUKI Corporation |
| Janome Sewing Machine Co., Ltd. |
| SVP Worldwide |
| BERNINA International AG |
| Jack Sewing Machine Co., Ltd. |
| Pegasus Sewing Machine Mfg. Co., Ltd. |
| Seiko Sewing Machine Co., Ltd. |
| Dürkopp Adler |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Ningbo freight corridors absorb 15-20% cost premiums during peak garment export seasons, concentrating margin pressure on Zhejiang-based precision machining houses serving Bangladeshi OEMs. This logistics cost dynamic amplifies pricing power for captive electronic module producers while squeezing independent metal fabricators competing on standard-grade needle bar and feed dog contracts.
Pricing Analysis
Certification level (GB/CE/REACH-compliant) creates the primary spread between premium and standard tiers in this market. Three-tier pricing structure across precision-certified, export-grade, and domestic-standard levels dominates transactional flows. Pricing pressure stems from Vietnamese garment factories consolidating procurement volumes for direct drive retrofits. Small-scale tailoring workshops exhibit highest price sensitivity, while industrial apparel producers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are becoming standard for Bangladeshi garment groups sourcing feed dogs and tension assemblies from Guangdong suppliers. Raw material supply draws from high-grade tool steel mills in China, specialty alloy processors in Japan, and surface treatment facilities in Taiwan. Single-source vulnerability concentrates in Zhejiang CNC machining clusters serving computerized control module integration. Distribution runs through OEM captive networks for new equipment, with independent channels capturing high-wear replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct drive motor penetration in Bangladesh and Vietnam garment factories sits below 35% of installed base, positioning the market for sustained expansion through the mid-2030s as energy efficiency mandates accelerate replacement cycles.
For Market Incumbents: Pre-empt channel compression by establishing direct procurement relationships with Bangladeshi garment groups before precision machining specialists capture high-wear replacement volume. Deepen backward integration into servo-compatible feed dog manufacturing to defend margin pools against Jack Sewing Machine's aggressive motor cost positioning. Anchor position through certification investments aligning with tightening China's GB standards.
For New Entrants and Emerging Players: Build out precision machining capacity in Ethiopia and Kenya garment export zones where localized component supply chains remain underdeveloped for direct drive retrofits. Target footwear production applications with specialized alloy formulations for leather stitching durability. Penetrate through leasing model partnerships with Southeast Asian equipment financiers creating recurring replacement revenue streams.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mechatronic specialists bridging servo motor integration with precision mechanical subsystems. Long-term viability hinges on exposure to computerized and direct drive technology segments displacing mechanical clutch motor architectures. Acquisition targets should demonstrate captive electronic control module capability or upstream needle bar manufacturing control. Watch for inflection when India's PLI scheme cost offsets trigger precision component manufacturing investments in Tamil Nadu and Gujarat clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | JUKI Corporation's needle bar manufacturing control secures margin pools in high-wear replacement cycles. |
| Servo-Compatible Component Redesign | Vietnamese retrofit demand pulls feed dog architecture changes for direct drive torque profiles. |
| REACH Compliance Investment | EU surface coating restrictions force alloy formulation shifts for European-bound textile machinery. |
| Leasing Model Partnership | Asset-light financing in Southeast Asia creates recurring tension assembly and bobbin case replacement revenue. |
| African Assembly Zone Expansion | Ethiopia and Kenya garment export zones lack localized supply chains for computerized sewing floor components. |
Research Methodology
A standing panel of maintenance directors at Bangladeshi garment groups, precision machining shop owners in Zhejiang and Guangdong, OEM procurement teams at Brother Industries and JUKI Corporation, and aftermarket service heads provided ongoing calibration across the study period. Primary interview findings triangulated against China's GB standards documentation, Vietnam Ministry of Industry and Trade energy efficiency codes, Indian PLI scheme filings, customs records for sewing machinery component trade flows, and SEC 10-K disclosures from listed equipment manufacturers. Bottom-up component demand modeling reconciled with top-down OEM production estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon using sensitivity bands for direct drive adoption velocity, GB standards enforcement timing, and REACH material restriction expansion. Segmentation dimensions modeled include component type (needle bar, feed dog, tension assembly, presser foot, bobbin case), technology tier (mechanical, electronic, direct drive, computerized), and end-use application (garment manufacturing, footwear production, upholstery, embroidery). CAGRs derived from fitted adoption curves for servo motor replacement cycles and industrial capacity expansion in Vietnamese and Bangladeshi textile clusters.
Stress conditions across alloy input cost volatility, logistics corridor disruption, and regulatory compliance timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding energy efficiency mandate implementation schedules and OEM technology migration patterns. Macroeconomic contraction in Asian garment export demand, unilateral tariff escalation on precision machined components, or breakthrough solid-state motor technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Sewing Machine Market