
 Hoarding Tarpaulin Market | 2026-2036
Hoarding Tarpaulin Market Size, Share, and Industry Trends Forecast 2026-2036
Hoarding Tarpaulin Market Foresight
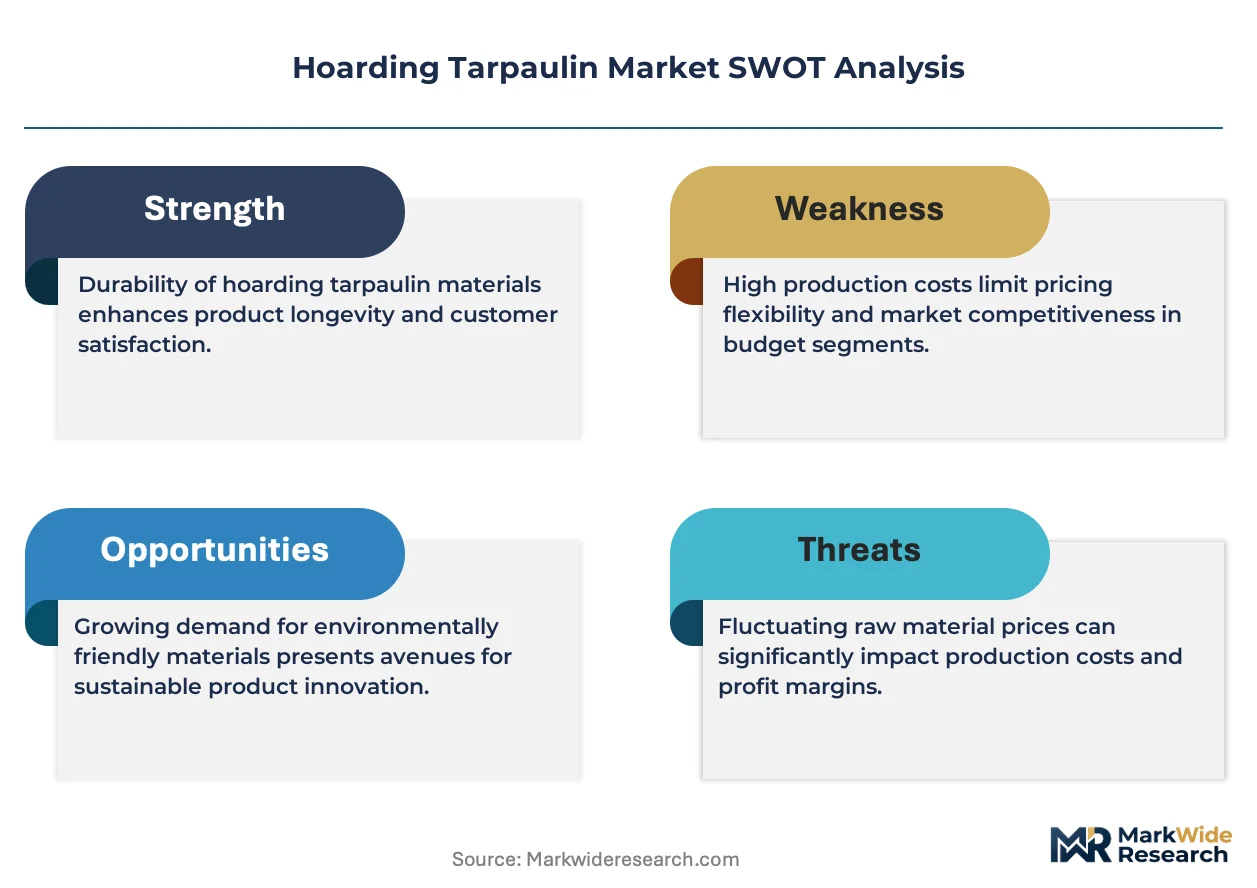
REACH compliance is repositioning the cost-of-entry calculus for European suppliers of PVC-based hoarding tarpaulins, forcing reformulation investments that smaller converters cannot absorb. Zhejiang MSD New Material Co., Ltd. leverages integrated polyethylene extrusion lines to sustain margin control across heavy-duty grades. Cunningham Covers anchors its position through bespoke digital-printing capabilities for event advertising applications. KSA Polymer competes on Gulf-state logistics proximity, dominating contractor supply chains across Middle Eastern construction corridors.
Hoarding tarpaulin denotes a reinforced flexible sheeting, typically woven polyethylene or laminated PVC at 200-600 gsm, manufactured through extrusion-coating or hot-lamination processes and deployed as temporary vertical enclosures for construction sites, event branding, and weather protection. Heavy-duty tarpaulin occupies the dominant volume position due to structural requirements on multi-year infrastructure builds, while UV-resistant grades capture expanding margin pools in sun-intensive geographies. Polyethylene material leads unit economics for short-duration construction hoarding, whereas PVC commands premium positioning where fire-retardant certification and print fidelity matter for event advertising and municipal contracts.
The EU F-Gas Regulation and CE marking directives constrain PVC formulation choices across European supply chains, while India's BIS fire-safety standards for temporary structures redirect contractor procurement toward certified domestic manufacturers. China's GB standards on plastic film tensile strength and the US EPA industrial fabric emissions guidelines add layered compliance obligations for exporters serving multiple jurisdictions. Stakeholders must monitor evolving national building codes for temporary structures and calibrate material portfolios between polyethylene cost efficiency and PVC performance premiums as certification requirements diverge across construction markets.
Market Dynamics
Construction hoarding specifications across India are hardening under BIS fire-safety mandates, forcing polyethylene converters to absorb certification costs while PVC suppliers in Europe absorb REACH reformulation expenses, splitting procurement economics by geography.
Growth Catalysts
- Maharashtra-Gujarat infrastructure corridor:Urban metro and highway projects in these Indian states are pulling heavy-duty tarpaulin volumes as contractors face compressed project timelines requiring durable site enclosures.
- REACH polymer reformulation:European ECHA compliance deadlines are culling PVC converter capacity, concentrating surviving suppliers with certified fire-retardant formulations and tightening supply to premium municipal contracts.
- UV-stabilized polyethylene grades:Gulf-state contractors in Saudi Arabia and UAE are specifying enhanced UV resistance for multi-year desert construction, creating specification premiums that domestic Indian manufacturers are racing to meet.
Market Restraints
- Crude-linked resin volatility:Polyethylene and PVC feedstock costs swing with naphtha and ethylene spot markets, compressing converter margins on fixed-price municipal tenders.
- Zhejiang production cluster concentration:Chinese extrusion capacity dominates Asia-Pacific supply, creating single-source dependency risks for Southeast Asian distributors when shipping lanes congest.
- Recyclability specification gaps:Mixed polymer laminates and fire-retardant additives complicate end-of-life processing, limiting circular economy claims that European public procurement increasingly screens.
Strategic Opportunities
- Digital-print customization for event advertising:Bespoke graphic capabilities on PVC substrates command 40-60% price premiums over plain hoarding, with festival and sports venue contractors driving specification upgrades.
- Saudi Vision 2030 construction pipeline:Giga-project enclosures across Neom and Red Sea developments are importing certified fire-retardant grades that KSA Polymer and regional distributors are positioning to capture.
- EU F-Gas Regulation phase-down:PVC formulation shifts away from high-GWP plasticizers create first-mover advantage for converters with bio-based or low-emission alternative certifications.
Industry Challenges
- BIS certification timeline compression:Indian manufacturers face 8-12 month fire-retardant testing queues at accredited labs, delaying contract eligibility for infrastructure tenders with rigid award schedules.
- Extrusion-coating technician scarcity:Specialized operators who can calibrate hot-lamination lines for 400-600 gsm heavy-duty grades command premium wages in Gujarat and Maharashtra industrial belts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hoarding Tarpaulin Market |
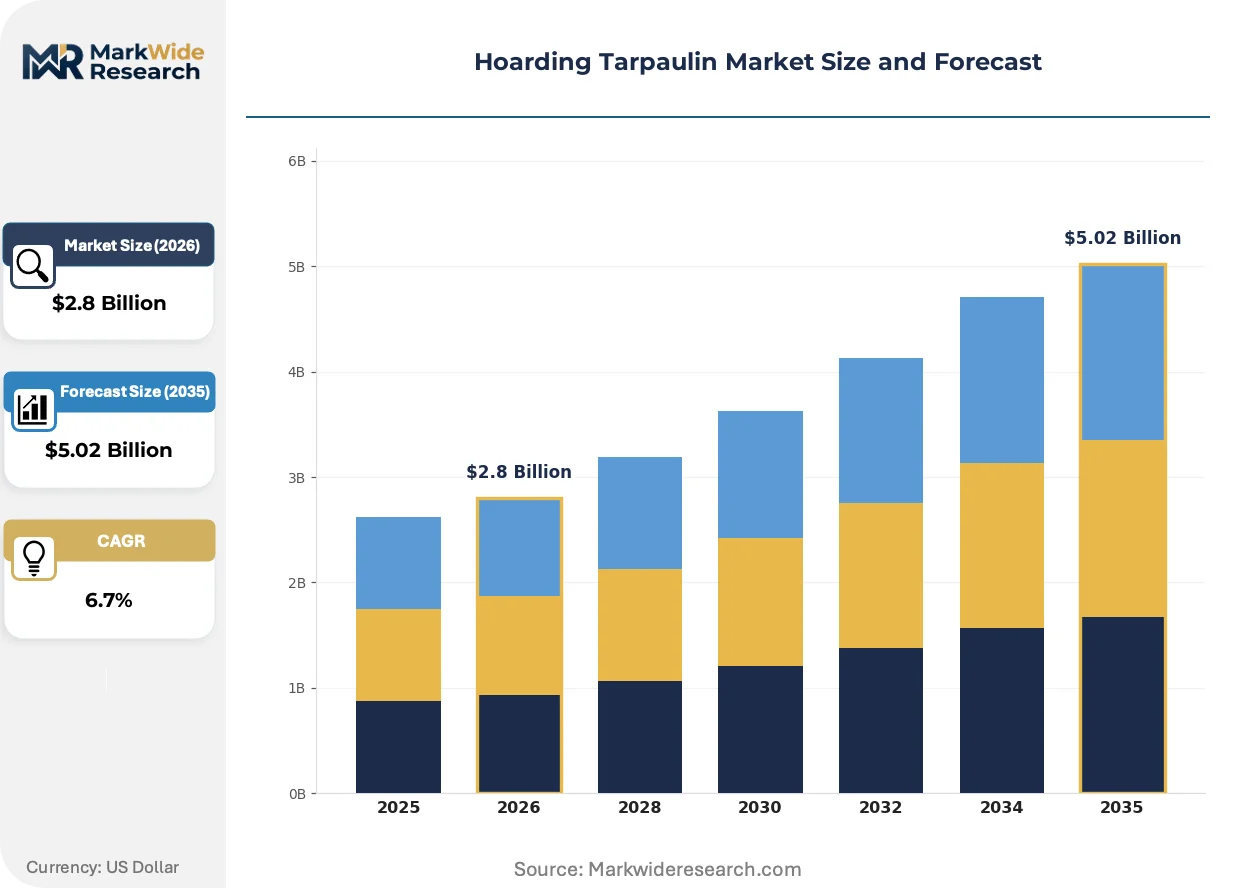
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tarpaulin, Heavy-Duty Tarpaulin, Waterproof Tarpaulin, UV-Resistant Tarpaulin Material: Polyethylene, PVC, Canvas, Polyester Application: Construction Sites, Event Advertising, Outdoor Storage, Transportation End User: Contractors, Event Planners, Transport Companies, Government Agencies |
| Companies Covered | Canadian Tarpaulin Manufacturers LTD., Bag Poly International, Cunningham Covers, Tan Dai Hung Plastic JSC, Tu Phuong Tarpaulin, KSA Polymer, Veer Plastics Private Limited, Puyoung Industrial Corporation Ltd., Zhejiang MSD New Material Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hoarding Tarpaulin Market Shifts & Advancements
Material science and regulatory chemistry are converging to redefine competitive advantage, with fire-safety certification becoming the primary sorting mechanism between commodity polyethylene suppliers and premium PVC converters serving municipal and event markets.
Co-extruded multilayer polyethylene is absorbing UV stabilizer and fire-retardant additives directly into the melt stream rather than as surface coatings, extending service life in sun-intensive geographies. Indian contractors on Rajasthan solar farms and Saudi giga-projects are specifying these grades for 36-month deployment cycles. The technology is absorbing margin pressure from shorter replacement intervals, compressing the addressable market for basic single-layer alternatives.
EU F-Gas Regulation and CE marking directives are forcing PVC compounders to eliminate high-global-warming-potential plasticizers from hoarding formulations by 2027. German and Italian converters with early bio-based phthalate alternatives are securing municipal framework agreements that lock out laggard suppliers. Event advertising segments in France and Netherlands are absorbing the reformulation costs fastest, passing premiums through to festival organizers with sustainability mandates.
Contractor procurement offices in India are consolidating vendor panels from 15-20 regional converters to 3-5 certified suppliers with BIS fire-safety documentation and integrated digital-print capabilities. Maharashtra state infrastructure agencies are piloting two-year framework agreements with volume commitments and penalty clauses for non-compliance. This consolidation is most visible in Mumbai-Pune corridor metro construction, where general contractors face liquidated damages for site enclosure failures.
Hoarding Tarpaulin Market Segmentation
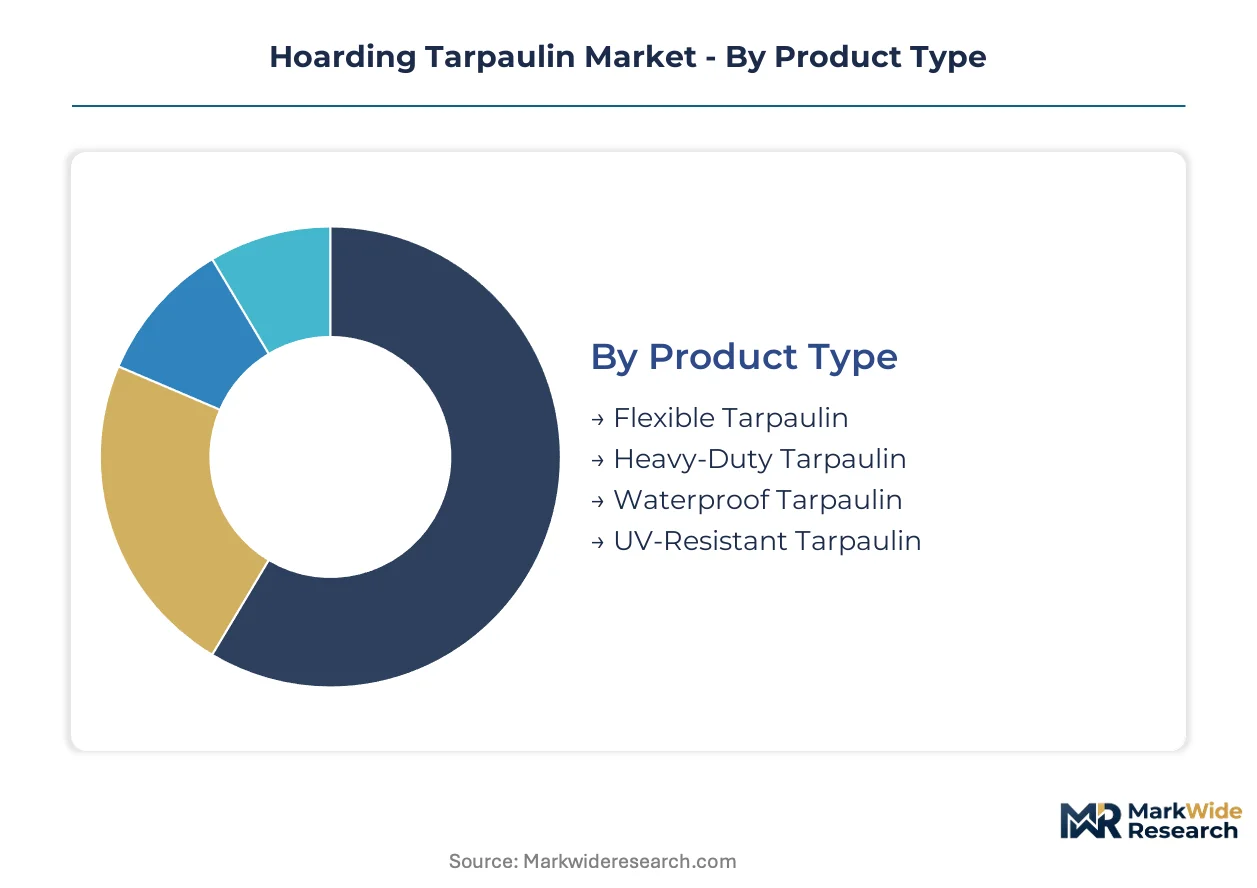
Material composition and duty rating determine procurement economics across hoarding tarpaulin categories, with certification requirements and deployment duration driving specification divergence between commodity and premium tiers.
Product Type:
Supply concentration in heavy-duty extrusion capacity shapes competitive dynamics, with 400-600 gsm calendering lines concentrated among Gujarat and Maharashtra manufacturers serving multi-year infrastructure builds.
- Heavy-Duty Tarpaulin:Woven polyethylene or laminated PVC at 400-600 gsm manufactured through hot-lamination processes for structural load-bearing on multi-year construction enclosures. Demand concentrates in Maharashtra and Gujarat where urban metro projects require 36-month service life under BIS fire-safety mandates.
- UV-Resistant Tarpaulin:Co-extruded multilayer polyethylene with melt-stream UV stabilizers replacing surface coatings for desert and high-altitude deployment. Saudi giga-projects and Rajasthan solar farms specify these grades, creating specification premiums that domestic Indian manufacturers are racing to meet.
- Flexible Tarpaulin:Lightweight 200-300 gsm polyethylene sheeting for short-duration site enclosures and temporary weather protection.
- Waterproof Tarpaulin:Laminated or coated grades prioritizing moisture barrier performance for outdoor storage and transport cover applications.
Today's leader: Heavy-Duty Tarpaulin. Tomorrow's challenger: UV-Resistant Tarpaulin.
Material:
Cost tier differentiation separates commodity polyethylene from performance-graded PVC, with REACH and BIS compliance costs widening the procurement gap between material classes.
- Polyethylene:Woven HDPE or LDPE substrates extrusion-coated for cost-efficient short-duration hoarding, dominating Indian construction procurement where BIS certification timelines compress contract eligibility.
- PVC:Laminated vinyl with fire-retardant plasticizers commanding premium positioning for event advertising and municipal contracts where print fidelity and CE marking compliance matter. EU F-Gas Regulation phase-downs are forcing bio-based plasticizer reformulation investments that concentrate supply among German and Italian compounders.
- Canvas:Cotton or cotton-blend woven substrates with natural breathability for heritage restoration and aesthetic-sensitive applications.
- Polyester:High-tenacity synthetic woven base with PVC or PU coating for specialized tensile structures and extended outdoor exposure.
Polyethylene dominates volume. PVC captures margin. Canvas and polyester occupy niche positioning.
Application:
Application-driven specification divergence creates distinct supply chains, with construction procurement consolidating around certified domestic manufacturers while event advertising rewards digital-print customization capabilities.
- Construction Sites:Temporary vertical enclosures for site security, dust containment, and regulatory compliance on infrastructure builds. Indian contractors in the Mumbai-Pune corridor face liquidated damages for enclosure failures, consolidating vendor panels toward BIS-certified suppliers with integrated extrusion and printing.
- Event Advertising:Bespoke graphic hoarding for festival branding, sports venues, and promotional installations. Cunningham Covers and European converters command 40-60% price premiums through digital-print capabilities on PVC substrates, with sustainability mandates in France and Netherlands absorbing reformulation costs fastest.
- Outdoor Storage:Weather protection for equipment, materials, and inventory in logistics yards and industrial facilities.
- Transportation:Truck and container covers, railcar protection, and cargo securing applications requiring tear resistance and tie-down compatibility.
Construction Sites anchor volume. Event Advertising expands fastest. Outdoor Storage and Transportation follow cyclical industrial activity.
End User:
Customer type determines procurement sophistication, with government agencies and large contractors driving certification consolidation while event planners prioritize creative turnaround speed.
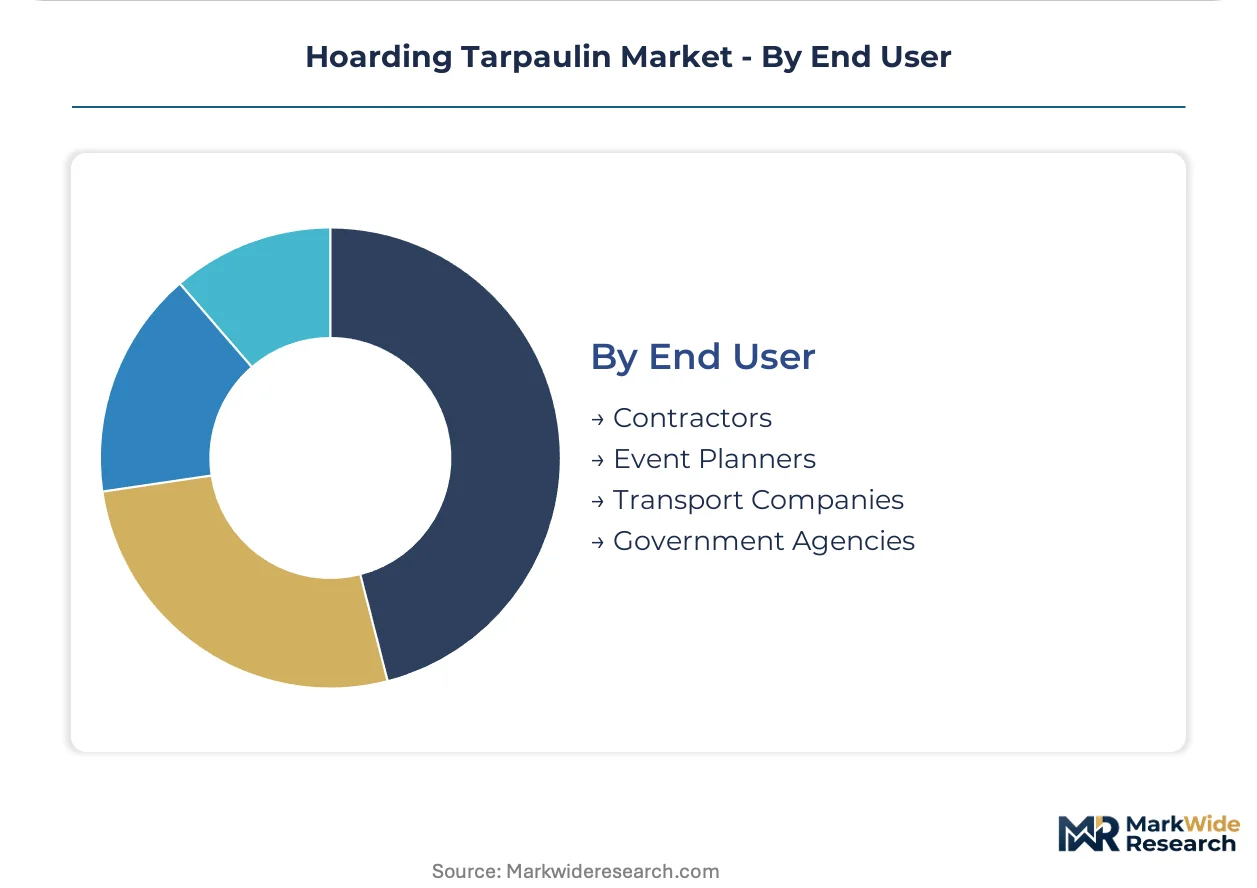
- Contractors:General construction and infrastructure builders procuring through consolidated vendor panels with framework agreements, penalty clauses, and BIS documentation requirements. Maharashtra state agencies pilot two-year volume commitments with strict compliance enforcement.
- Government Agencies:Municipal and state infrastructure authorities specifying fire-retardant certification, CE marking, and sustainability screening in public tenders. EU public procurement increasingly screens circular economy claims, disadvantaging mixed-polymer laminates.
- Event Planners:Festival, sports, and corporate event organizers demanding rapid digital-print turnaround and graphic customization on tight production schedules.
- Transport Companies:Fleet operators and logistics providers procuring standardized covers on replacement cycles tied to vehicle depreciation schedules.
Contractors drive standardization. Government Agencies enforce compliance. Event Planners and Transport Companies follow differentiated procurement logic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene hoarding tarpaulin manufacturing scaled through Zhejiang extrusion clusters before spreading to Gujarat and Maharashtra as Indian infrastructure accelerated. Regional demand now fragments across certification regimes, with fire-safety mandates in India, REACH reformulation in Europe, and UV specifications in Gulf states driving procurement divergence.
India
Maharashtra and Gujarat infrastructure corridors pull heavy-duty polyethylene volumes as metro and highway projects compress timelines. BIS fire-retardant certification mandates for temporary site enclosures redirect contractor procurement toward accredited domestic manufacturers with integrated extrusion lines. Mumbai-Pune industrial belts concentrate converter capacity serving state government framework agreements with strict compliance enforcement.
China
Zhejiang province anchors Asia-Pacific supply through integrated polyethylene extrusion clusters serving export markets and domestic construction. GB standards on plastic film tensile strength layer compliance obligations for manufacturers shipping to multiple jurisdictions. Ningbo and Wenzhou production hubs face shipping lane congestion risks that Southeast Asian distributors increasingly hedge through dual-sourcing arrangements.
Saudi Arabia
Neom and Red Sea giga-projects specify certified fire-retardant grades for multi-year desert deployment, creating import demand that regional distributors race to capture. SFDA and municipal building codes for temporary structures tighten specification requirements on contractor procurement. Eastern Province logistics corridors position Jeddah and Dammam as distribution nodes for Gulf-state construction supply chains.
Germany
REACH reformulation deadlines cull PVC converter capacity as ECHA compliance costs concentrate supply among surviving compounders with bio-based plasticizer alternatives. CE marking directives and F-Gas Regulation phase-downs reshape municipal tender eligibility, locking out laggard suppliers. Bavaria and North Rhine-Westphalia industrial clusters house converters securing framework agreements with sustainability-mandated public procurement offices.
United States
EPA industrial fabric emissions guidelines add compliance layering for imported hoarding materials serving infrastructure and event markets. Construction activity concentrates in Texas and California metro corridors where contractor procurement balances cost efficiency against certification documentation requirements. Regional distributors face margin pressure from fixed-price municipal tenders amid crude-linked resin volatility.
Hoarding Tarpaulin Market Competitive Landscape
The competitive structure tilts toward integrated extrusion specialists with certification depth rather than commodity converters. Market concentration remains moderate, with tiered positioning separating certified premium suppliers from regional price competitors. Two strategic archetypes dominate: integrated manufacturers controlling upstream resin through captive extrusion, and specialized converters commanding premium positioning through digital-print or fire-safety certification. Capacity expansion and geographic licensing represent the dominant competitive moves as players seek defensible positions under diverging regulatory regimes.
Among Asia-Pacific integrated manufacturers, Zhejiang MSD New Material Co., Ltd. exemplifies the scale-driven archetype with polyethylene extrusion line control, while KSA Polymer occupies a position within Gulf-state logistics-proximity tiers. Cunningham Covers represents the specialization vector, sitting within premium-tier positioning through bespoke capabilities. These three anchors illustrate how certification compliance and geographic clustering sort competitive outcomes across material classes and end-use segments.
| Leading Market Players |
|---|
| Canadian Tarpaulin Manufacturers LTD. |
| Bag Poly International |
| Cunningham Covers |
| Tan Dai Hung Plastic JSC |
| Tu Phuong Tarpaulin |
| KSA Polymer |
| Veer Plastics Private Limited |
| Puyoung Industrial Corporation Ltd. |
| Zhejiang MSD New Material Co., Ltd. |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-downs gate qualified PVC supply and premium-tier pricing access for hoarding tarpaulin converters serving municipal and event advertising contracts. REACH reformulation costs concentrate certified compounder capacity among German and Italian manufacturers, while polyethylene suppliers in India absorb BIS fire-retardant testing expenses to retain construction procurement eligibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PVC fire-retardant grades with CE marking from commodity polyethylene sheeting and basic laminates. Certification grade and volume scale drive price differentiation, with BIS-accredited Indian manufacturers commanding premiums over regional converters facing testing queue delays. Cost compression in standard-grade polyethylene intensifies because crude-linked resin volatility squeezes margins on fixed-price state tenders. Municipal contractors in Maharashtra exhibit highest price sensitivity, while festival organizers in France and Netherlands absorb sustainability premiums with least resistance.
Supply Chain Analysis
Regional distribution centers in Jeddah, Mumbai-Pune, and Ningbo anchor hub-and-spoke patterns serving Gulf-state, Indian, and Southeast Asian construction corridors respectively. Manufacturing concentrates in China, India, and Saudi Arabia, with Zhejiang extrusion clusters feeding Asian export demand and Gujarat calendering lines serving domestic infrastructure builds. Raw material supply draws from naphtha-derived polyethylene resin, PVC paste from ethylene feedstock, and UV stabilizer additives from specialty chemical importers. Single-source vulnerability from Zhejiang production concentration threatens Southeast Asian distributors when shipping lanes congest. Distribution runs through contractor vendor panels consolidated under framework agreements with compliance documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hoarding tarpaulin market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed BIS certification expenses in India by multiples, redirecting capital toward integrated South Asian extrusion capacity.
For Market Incumbents: Hedge against resin volatility through backward integration into polyethylene pellet supply or long-term offtake agreements with Gujarat petrochemical complexes. Absorb BIS fire-retardant testing capacity constraints by acquiring accredited lab slots or partnering with Maharashtra state infrastructure agencies on framework agreements. Certification investment represents the critical lever for retaining vendor panel position as procurement offices consolidate from fifteen regional converters to three certified suppliers. For New Entrants and Emerging Players: Begin with UV-stabilized polyethylene grades for Saudi giga-projects and Rajasthan solar farms where domestic Indian manufacturers race to meet specification premiums. Target event advertising segments in France and Netherlands where sustainability mandates absorb reformulation costs fastest and digital-print capabilities command forty-to-sixty percent price premiums. A go-to-market angle through festival organizer direct relationships bypasses consolidated contractor procurement channels. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap Indian extrusion specialists with BIS documentation and integrated printing capabilities because vendor panel consolidation in Maharashtra and Gujarat creates scarcity value for certified supply. Long-term viability hinges on regulatory divergence persisting between REACH reformulation timelines in Europe and BIS fire-safety mandates in India. Acquisition target archetype: Gujarat-based converters with captive calendering lines and state framework agreements. The signal to watch is BIS testing queue compression timelines as infrastructure tender awards accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Gujarat petrochemical proximity secures margin control against naphtha spot volatility for polyethylene converters. |
| BIS Fire-Retardant Certification Investment | Accredited testing capacity unlocks Maharashtra state framework agreements with volume commitment structures. |
| Digital-Print Capability Expansion | Bespoke graphic production captures festival organizer premiums in France and Netherlands sustainability-mandated segments. |
| UV Stabilizer Formulation Development | Co-extruded multilayer grades meet Saudi giga-project specifications for thirty-six-month desert deployment cycles. |
| Gulf-State Distribution Hub Establishment | Jeddah and Dammam nodes position capture of Neom and Red Sea construction corridor import demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Gujarat and Zhejiang extrusion facilities, procurement leads at Maharashtra state infrastructure agencies, distribution channel partners serving Saudi giga-projects, and technical R&D directors at European PVC compounders. Secondary validation drew from customs and trade data, Bureau of Indian Standards certification registries, ECHA REACH submission databases, and SEC filings of listed industrial fabric manufacturers. Bottom-up capacity estimates from extrusion line counts and top-down demand triangulation from construction tender values converged across analytical approaches.
Historical reference periods anchored the projection horizon through comparable infrastructure build cycles and regulatory implementation timelines across multiple jurisdictions. Segmentation dimensions modeled include material composition, duty rating, application vertical, and regional certification regime. CAGRs derived from weighted average growth across these segments, with inputs from resin price elasticity estimates and contractor procurement panel consolidation rates.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Zhejiang export routes, accelerated BIS testing capacity expansion, and breakthrough bio-based plasticizer cost parity in European PVC formulations. Forecasts reflect documented assumptions about regulatory timeline adherence and infrastructure award schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Textile Winding Machine Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Portable Fabric Canopies Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Netted Fabrics Market