
 Home Webcam Market | 2026-2036
Home Webcam Market Size, Share, and Industry Trends Forecast 2026-2036
Home Webcam Market Intelligence
The EU AI Act's biometric data governance framework is expanding the addressable market for privacy-certified home webcams across European households. Logitech leverages its vertical integration in optical sensor sourcing to sustain margin stability amid component volatility. Cisco Systems anchors its enterprise channel strength by bundling webcam hardware with Webex software subscriptions. Canon specializes in large-sensor formats that differentiate its offerings from commodity USB alternatives.
A home webcam is a compact digital video capture device, typically incorporating CMOS or CCD image sensors with resolutions spanning 720p to 4K, designed for real-time audiovisual transmission over USB or wireless protocols to computing endpoints for communication, content creation, or monitoring purposes. USB Webcams dominate unit volume due to plug-and-play interoperability across operating systems, while 4K technology captures disproportionate value share as streaming platforms raise bitrate requirements. Network Cameras and PTZ Cameras serve distinct demand pools where content creators prioritize cinematic control and small businesses require remote pan-tilt-zoom manageability.
FCC equipment authorization mandates in the United States and CE marking requirements under EU Radio Equipment Directive shape electromagnetic compatibility and RF emission standards that determine market access eligibility. The EU AI Act's biometric data classification rules are forcing firmware architecture redesigns for facial recognition-capable devices. Stakeholders must monitor whether emerging national data localization laws fragment cloud-dependent webcam feature sets across jurisdictional boundaries.
Market Dynamics
The home webcam market is being fundamentally restructured by the EU AI Act's biometric data governance framework, which mandates privacy-by-design architecture for facial recognition-capable devices and is forcing firmware redesigns across the entire supply chain.
Growth Catalysts
- EU AI Act compliance mandates:The regulation's biometric data classification rules create procurement pull for privacy-certified devices across European households, expanding the addressable market for manufacturers with certified firmware architectures.
- Remote work institutionalization:Enterprise IT departments are standardizing high-resolution webcam specifications for distributed workforce infrastructure, creating sustained replacement cycles beyond initial pandemic-driven purchases.
- Content creator bitrate escalation:Streaming platforms are raising minimum upload specifications, driving 4K webcam demand from North American creator communities who require cinematic image quality for audience retention.
Market Restraints
- Optical sensor supply concentration:CMOS sensor fabrication concentrates among a limited set of foundries in East Asia, creating vulnerability to geopolitical disruption and capacity allocation decisions.
- Commoditization pressure at 720p-1080p tiers:USB webcam interoperability standards enable rapid manufacturer entry, compressing margins for undifferentiated hardware and limiting R&D recovery windows.
- FCC equipment authorization complexity:United States electromagnetic compatibility testing timelines extend market entry by 8-14 weeks for new RF-emitting designs, delaying revenue recognition.
Strategic Opportunities
- PTZ camera penetration in small business:Remote pan-tilt-zoom manageability remains underdeployed among professional services firms with distributed client presentation needs, offering expansion potential.
- Large-sensor format differentiation:Cinematic image sensors above one-inch diagonal remain scarce in sub-$500 price bands, creating white space for premium positioning against commodity USB alternatives.
- Wireless protocol convergence:Wi-Fi 6E and Thread integration enables battery-powered placement flexibility, opening installation locations inaccessible to tethered USB configurations.
Industry Challenges
- Firmware architecture reconfiguration:Edge-based facial recognition processing requires on-device AI accelerator integration that strains thermal management in compact form factors.
- Cloud feature fragmentation risk:Emerging national data localization laws threaten to bifurcate firmware update streams and AI service availability across jurisdictional boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Webcam Market |
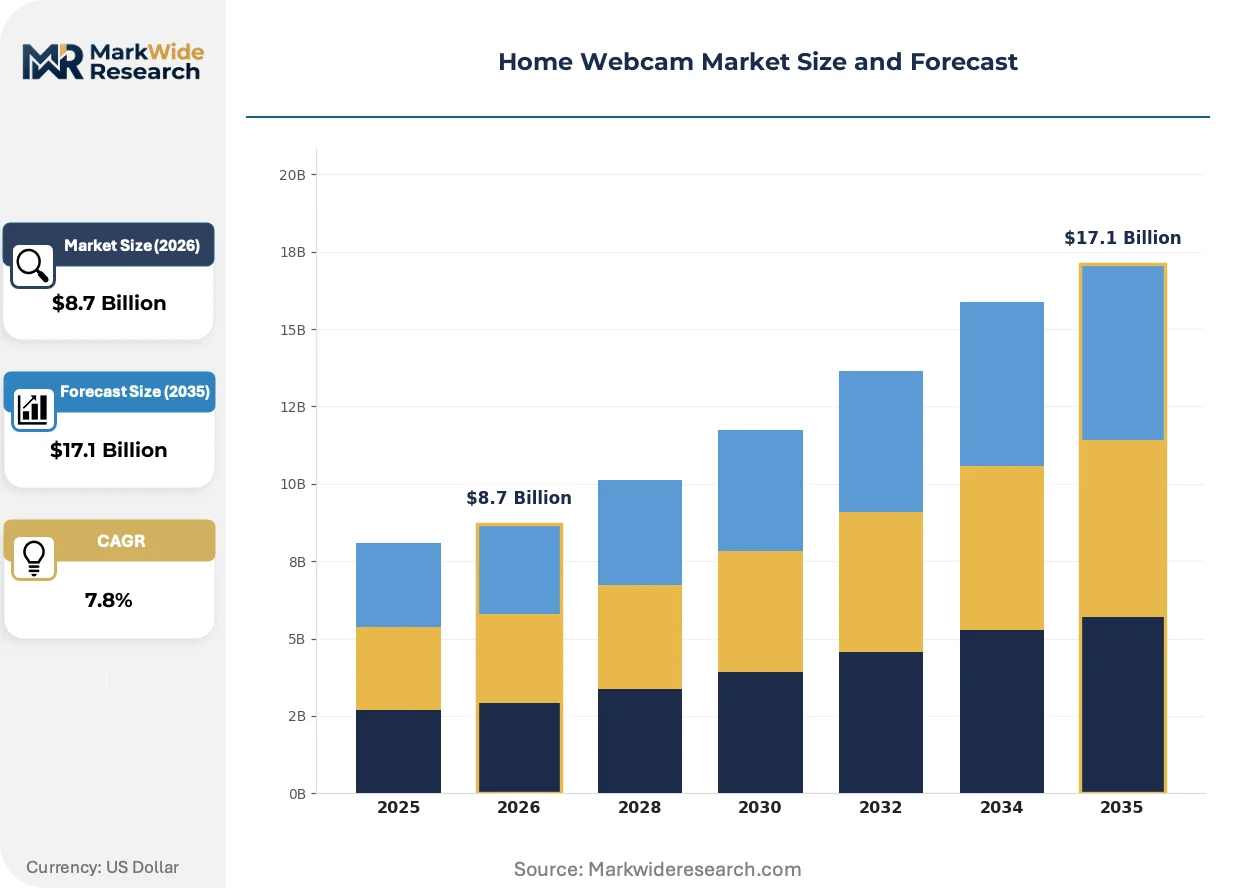
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Webcams, Network Cameras, PTZ Cameras, Wireless Cameras Technology: Analog, Digital, HD, 4K End User: Individuals, Small Businesses, Educational Institutions, Content Creators Use Case: Video Conferencing, Streaming, Surveillance, Online Education |
| Companies Covered | Logitech, Cisco Systems, Inc., Canon, Inc., Sony Corporation, Razer Inc., D-Link Corp., Microsoft, Lenovo, 10Moons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Webcam Market Strategic Shifts & Innovations
Computational photography pipelines and privacy-preserving edge AI are converging to redefine image quality benchmarks and data handling architectures across the home webcam category. These developments are compressing traditional hardware differentiation cycles while opening new compliance-driven segmentation.
Neural network-based image signal processing is rewriting the relationship between sensor size and perceived image quality. Content creators on Twitch and YouTube are adopting devices with onboard AI denoising and HDR fusion at rates exceeding manufacturer forecasts. This compression of hardware requirements is enabling smaller optical formats to challenge traditional large-sensor dominance in studio environments.
The EU AI Act's biometric data governance framework is mandating on-device processing for facial analysis features. Manufacturers serving European households must architect firmware that prevents cloud transmission of identifiable biometric data without explicit consent. This regulatory pressure is accelerating edge AI accelerator adoption across mid-tier product lines that previously relied on cloud-based feature sets.
Enterprise procurement teams are consolidating vendor relationships around bundled hardware-software subscriptions rather than discrete hardware purchases. IT departments at financial services and professional services firms are selecting Webex-integrated or Teams-certified devices through single procurement channels. This behavior shift is most visible in North American enterprise segments where centralized IT governance has reasserted control over peripheral standardization.
Home Webcam Market Segmentation
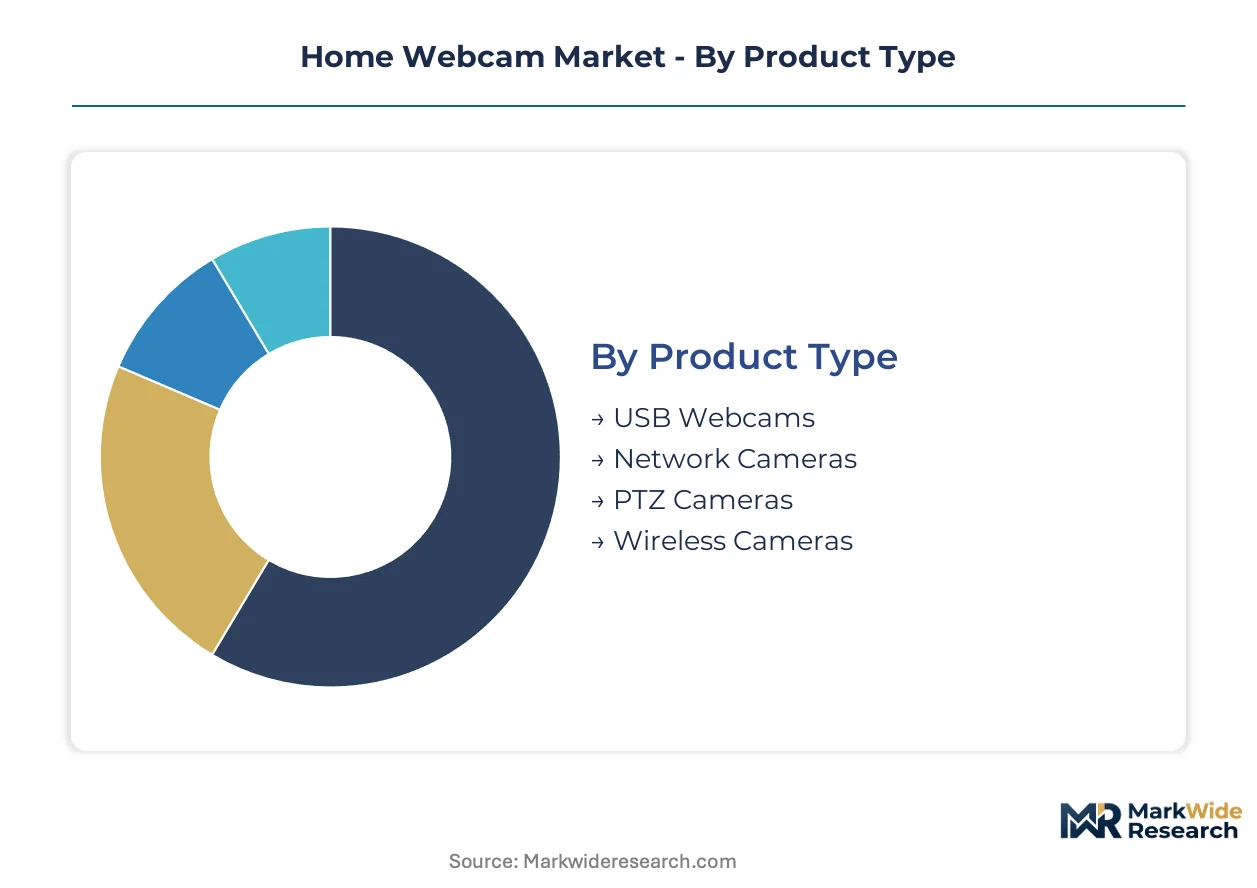
Procurement priorities across the home webcam market diverge sharply between cost-sensitive volume buyers and specification-driven professional users. Understanding these segment boundaries enables manufacturers to align sensor investments, firmware architectures, and channel strategies with buyer willingness to pay for resolution, connectivity, and compliance certifications.
Product Type:
Installation flexibility and power source availability determine which form factor buyers select for their deployment environment.
- USB Webcams:These devices leverage plug-and-play interoperability across Windows, macOS, and Linux endpoints without driver installation. Enterprise IT departments in the United States standardize USB connectivity for fleet deployments where centralized management tools must recognize peripherals automatically. FCC equipment authorization requirements add 8-14 weeks to new RF-emitting designs, reinforcing USB's dominance in rapid procurement cycles.
- Network Cameras:IP-based streaming over Ethernet or Wi-Fi enables placement independent of host computer proximity. Small businesses in Germany deploy these for reception area monitoring where cable routing to desks proves impractical. The EU AI Act's biometric data governance rules mandate on-device processing for facial recognition features, accelerating edge AI integration in this segment.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms serve distributed client presentation needs in professional services firms. Remote manageability remains underdeployed relative to potential addressable market.
- Wireless Cameras:Battery-powered operation with Wi-Fi 6E or Thread protocol support opens installation locations inaccessible to tethered configurations. Thermal management constraints limit sustained 4K streaming duration.
USB Webcams lead on scale; Wireless Cameras lead on momentum as protocol convergence enables new placement scenarios.
Technology:
Image sensor resolution tiers separate commodity procurement from premium positioning based on streaming platform bitrate requirements.
- Analog:Composite video output persists in legacy surveillance installations where coaxial infrastructure replacement costs deter upgrade. Budget-constrained educational institutions in rural India maintain these systems despite limited interoperability with modern endpoints.
- Digital:Native digital signal processing eliminates analog-to-digital conversion artifacts. Small business buyers prioritize this baseline for professional video conferencing where image clarity affects client perception.
- HD:720p to 1080p resolution captures the largest unit volume as streaming platforms maintain backward compatibility with these specifications. Content creators on Twitch and YouTube are adopting devices with onboard AI denoising at rates exceeding manufacturer forecasts.
- 4K:Ultra-high-definition sensors above 8 megapixels command disproportionate value share as bitrate requirements escalate. North American creator communities drive demand for cinematic image quality in audience retention strategies.
HD dominates installed base; 4K captures expanding value share as platform specifications tighten.
End User:
Organizational procurement authority and reimbursement mechanisms shape price sensitivity and feature prioritization across buyer categories.
- Individuals:Direct consumer purchases emphasize price-to-performance ratio and retail availability. Amazon and Best Buy channel dominance concentrates demand for sub-$100 devices with immediate shipping.
- Small Businesses:Owner-operator decision-making balances upfront hardware cost against perceived professionalism in client interactions. Bundled hardware-software subscriptions through Webex or Teams channels are displacing discrete purchases.
- Educational Institutions:District-level IT governance in the United States drives volume tenders with multi-year replacement cycles. E-rate funding eligibility steers procurement toward specific vendor certifications.
- Content Creators:Individual and studio-based producers prioritize sensor size, lens interchangeability, and software ecosystem integration. YouTube Partner Program revenue thresholds justify premium equipment investments.
Individuals represent the deepest volume pool; Content Creators generate the steepest expansion trajectory as platform monetization professionalizes.
Use Case:
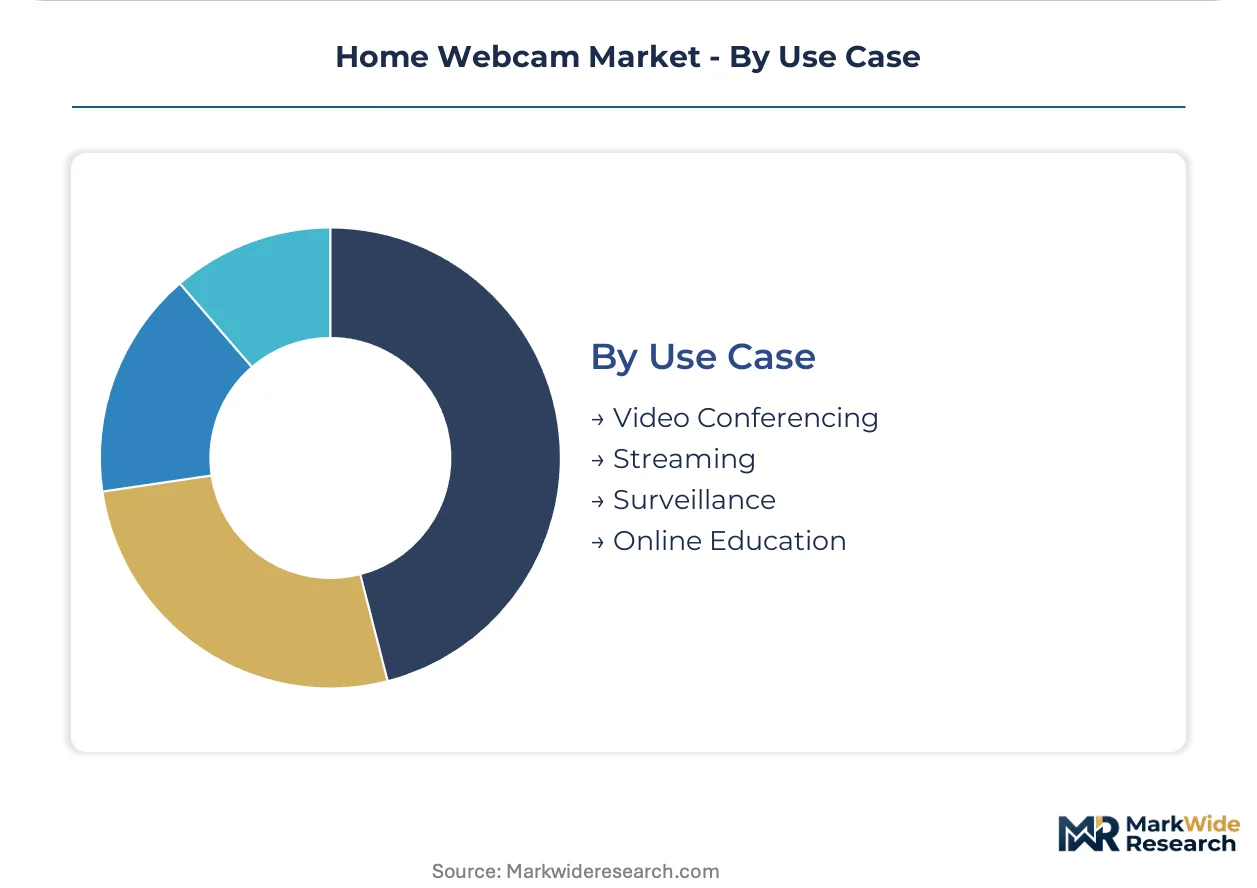
Application-specific performance requirements dictate sensor specifications, processing latency tolerances, and cloud dependency architectures.
- Video Conferencing:Real-time bidirectional communication demands sub-200ms end-to-end latency with automatic exposure compensation for varying office lighting. Enterprise deployments require Teams or Zoom certification for IT department approval.
- Streaming:Unidirectional broadcast tolerates higher latency in exchange for encoding efficiency and bitrate flexibility. OBS Studio and Streamlabs compatibility drives software ecosystem preferences.
- Surveillance:Continuous recording prioritizes storage efficiency through motion-activated encoding and infrared night vision capability. Local network storage options address data localization law uncertainties.
- Online Education:Instructor-facing capture requires document camera compatibility and whiteboard visibility optimization. K-12 districts mandate COPPA-compliant data handling for student privacy protection.
Video Conferencing anchors current revenue; Streaming applications are gaining share fastest as creator economy infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The home webcam industry traces its commercial origins to Silicon Valley's peripheral manufacturing ecosystem, where early USB video device class standardization enabled mass-market adoption. Component fabrication later dispersed across East Asian foundries while software certification requirements anchored final assembly and distribution networks in North American and European logistics hubs.
United States
Enterprise IT standardization drives procurement volume as Fortune 500 firms replace pandemic-era hardware with 4K-certified fleet deployments. FCC equipment authorization mandates add 8-14 weeks to new RF-emitting designs, favoring established vendors with regulatory expertise. Seattle and Austin tech corridors concentrate software-hardware integration labs where Teams and Zoom certification testing occurs.
Germany
Small business demand for PTZ-enabled client presentation systems sustains premium-tier shipments despite broader IT spending caution. EU AI Act biometric data governance rules force firmware architecture redesigns for facial recognition-capable devices entering Bavarian and North Rhine-Westphalia industrial markets. Munich's precision engineering cluster hosts optical assembly operations serving continental distribution networks.
China
CMOS sensor foundry concentration in Yangtze River Delta and Pearl River Delta regions determines global supply availability for downstream webcam manufacturers. MIIT radio transmission equipment certification parallels FCC timelines while GB standards govern electromagnetic compatibility. Shenzhen's electronics assembly ecosystem produces the majority of sub-$100 USB webcam units for export markets.
Japan
Content creator demand for large-sensor cinematic formats supports premium positioning against commodity alternatives. METI industrial standards and JIS certification requirements create technical barriers for non-domestic competitors in broadcast-adjacent segments. Tokyo-Osaka corridor imaging technology specialists supply optical components to multinational assembly operations.
United Kingdom
Educational institution procurement through district-level IT governance sustains volume demand despite fiscal pressures on public spending. GDPR compliance requirements and emerging UK-specific biometric data regulations influence vendor selection criteria for London and Southeast England school districts. Cambridge imaging technology cluster contributes computational photography algorithm development to global supply chains.
Home Webcam Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the home webcam market structure. Vertically integrated optical specialists controlling sensor fabrication and final assembly face pressure from brand marketers outsourcing manufacturing to contract electronics foundries. Three archetypes dominate: multinational technology conglomerates bundling hardware with software ecosystems, imaging heritage companies leveraging optical engineering expertise, and peripheral specialists optimizing for gaming and content creator niches. Competitive moves center on strategic partnerships with streaming platform operators and backward integration into CMOS sensor supply.
Within the multinational technology tier, Cisco Systems, Inc. and Microsoft occupy positions as enterprise channel anchors through bundled hardware-software subscription models. Logitech exemplifies the peripheral specialist archetype with optical sensor sourcing capabilities that support margin stability. Canon, Inc. represents imaging heritage positioning through large-sensor format differentiation strategies targeting content creator segments.
| Leading Market Players |
|---|
| Logitech |
| Cisco Systems, Inc. |
| Canon, Inc. |
| Sony Corporation |
| Razer Inc. |
| D-Link Corp. |
| Microsoft |
| Lenovo |
| 10Moons |
| Others |
Cost & Logistics Intelligence
Optical engineering talent concentration in Shenzhen and Dongguan manufacturing corridors widens labor-cost differentials between premium sensor calibration operations and economy-grade assembly, compressing mid-tier pricing spreads as automated surface-mount technology displaces manual firmware flashing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified firmware architectures from commodity USB alternatives from basic analog legacy units. Price differentiation hinges on edge AI accelerator integration and CE marking tier for biometric data compliance. Cost compression in 720p-1080p tiers is intensifying because rapid manufacturer entry through interoperable standards erodes R&D recovery windows. Educational institutions and individual consumers exhibit highest price sensitivity, while content creators and enterprise IT departments prioritize specification compliance over unit cost.
Supply Chain Analysis
CMOS image sensor fabrication rests on Taiwanese and South Korean foundry capacity, with Japanese precision optics suppliers providing lens assembly components. Raw material dependencies include silicon wafers, rare-earth phosphors for infrared emitters, and copper alloy housings for electromagnetic shielding. Single-source vulnerability concentrates in advanced node sensor lithography equipment subject to export control restrictions. Distribution runs through Shenzhen electronics markets for economy tiers and direct enterprise channels for certified fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home webcam market functions as a stable compounder where remote work institutionalization sustains replacement cycles and regulatory compliance mandates perpetually refresh hardware demand.
For Market Incumbents: Extend firmware certification pipelines to capture EU AI Act-mandated replacement demand before second-tier competitors achieve compliance. Deepen backward integration into optical sensor supply to defend margin stability against foundry allocation volatility. Prioritize Webex and Teams channel control as bundled subscription models displace discrete hardware procurement in North American enterprise segments. For New Entrants and Emerging Players: Enter via PTZ camera penetration in German professional services firms where remote pan-tilt-zoom manageability remains underdeployed relative to addressable need. Target wireless camera momentum in small business reception monitoring where Wi-Fi 6E protocol convergence enables battery-powered placement flexibility unavailable to tethered USB configurations. Pursue direct-to-system-integrator distribution to bypass established retail channel gatekeepers. For Investors and Strategic Acquirers: Enterprise software-hardware bundlers represent the most active acquirer category in this space, seeking peripheral specialists with optical engineering capabilities to complement subscription revenue streams. The five-to-ten-year viability window favors targets with demonstrated EU AI Act compliance architecture and captive relationships with East Asian sensor foundries. Watch for FCC equipment authorization timeline extensions as inflection indicators of regulatory barrier elevation favoring established vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Accelerator Integration | EU AI Act biometric data rules mandate on-device processing, forcing firmware architecture redesigns across mid-tier product lines. |
| CMOS Sensor Backward Integration | Captive supply of optical sensors insulates margin stability from Yangtze River Delta foundry capacity allocation decisions. |
| Enterprise Bundle Subscription Pivot | Webex and Teams certification channels displace discrete hardware procurement in Fortune 500 fleet standardization programs. |
| Wireless Protocol Convergence | Wi-Fi 6E and Thread integration opens installation locations inaccessible to tethered USB configurations in small business environments. |
| Large-Sensor Format Differentiation | Cinematic image sensors above one-inch diagonal create premium positioning white space against commodity USB alternatives for content creators. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with enterprise IT procurement officers, content creator equipment purchasers, optical sensor foundry operations managers, and streaming platform partnership directors with secondary validation from FCC equipment authorization databases, CE marking registries, SEC 10-K peripheral segment disclosures, and hyperscaler hardware certification listings. Triangulation across these sources ensures volume and value estimates reflect actual procurement behavior rather than shipment projections alone.
Input-output matrices map sensor resolution tiers, connectivity protocols, and compliance certification levels against buyer archetype willingness-to-pay across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic drivers including remote work policy persistence and streaming platform bitrate escalation. Industry-specific forecast inputs include foundry capacity utilization reports and enterprise software-hardware bundle adoption curves.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time foundry allocation data introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding EU AI Act implementation timelines and enterprise IT replacement cycle normalization. A small set of triggers—geopolitical disruption to sensor supply, emergent data localization law fragmentation, and streaming platform codec specification shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
North America Secure Access Service Edge Market
Security Software
Security Software Market
Security Software
Geofencing Market
Security Software
Europe Smart Doorbell Market
Security Software
Europe Anti-Money Laundering Software Market
Security Software
Identity Governance and Administration Market
Security Software
Cloud Security Software Market
Security Software
Asia-Pacific Fraud Detection & Prevention Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Patch and Remediation Software Market
Security Software
Data Loss Prevention Market
Security Software
Parental Monitoring Software Market
Security Software
Global Background Screening Market
Security Software
Cloud Encryption Software Market
Security Software
Anomaly Detection Market
Security Software
ATM Security Market