
 Parental Control Software Market | 2026-2036
Parental Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
Parental Control Software Market Intelligence
Market Context with Strategic Players
India is narrowing its gap in affordable parental control solutions through domestic app development and localized content filtering. Microsoft Family Safety leverages its Windows ecosystem to anchor distribution across enterprise-education hybrids. Qustodio specializes in multi-language interfaces that sustain penetration across European households with diverse linguistic needs. Bark differentiates through AI-driven risk detection that competes on alert specificity rather than feature breadth.
Technical Definition and Structural Segments
Parental control software comprises programmable applications that enforce content filtering, time limits, location geofencing, and communication monitoring across connected devices through kernel-level permissions or VPN-based traffic inspection. These systems serve commercial and institutional buyers by reducing legal exposure from minor-accessed harmful content while preserving audit trails for compliance verification. Cloud-based deployment leads in scalability for educational institutions managing thousands of student accounts, while mobile application delivery represents the fastest-expanding channel as smartphone-native guardianship replaces desktop-centric models. Content filtering retains the largest margin pool due to recurring database subscription fees, whereas social media monitoring commands premium pricing from anxious high-income parents.
Regulatory Frame and Forward-Looking Close
The US Children's Online Privacy Protection Act and the EU Digital Services Act impose age-verification and parental consent architectures that reshape product design requirements for vendors seeking transatlantic market access. India's IT Rules mandate traceability and content removal timelines that force localization of filtering engines for compliance. Stakeholders must monitor divergence between US state-level digital safety statutes and federal privacy frameworks to anticipate compliance cost fragmentation.
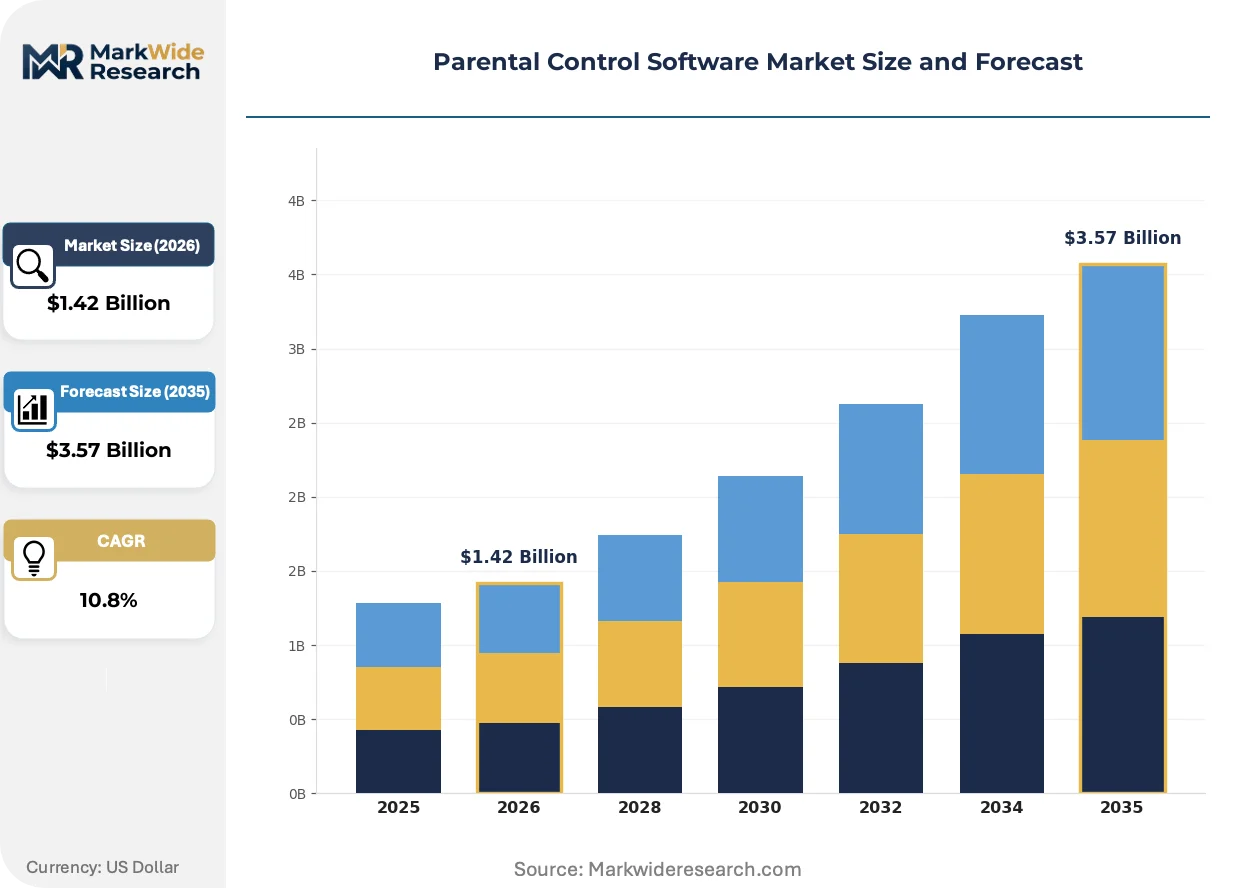
Market Dynamics
State-level digital safety mandates in the United States are compressing procurement cycles for educational institutions, forcing vendors to re-architect products for mass-deployment scalability rather than individual household customization.
Growth Catalysts
- COPPA age-verification requirements:The US Children's Online Privacy Protection Act compels platforms to integrate parental consent workflows, expanding the addressable base for control software vendors serving content providers.
- Smartphone-native guardianship:Mobile-first parenting behaviors in emerging markets are accelerating cloud-based deployment models that bypass legacy desktop installation friction.
- EU Digital Services Act child-protection provisions:The regulation mandates platform-level safety tools, creating compliance-driven procurement from social media and gaming companies seeking transatlantic market access.
Market Restraints
- Kernel-level permission complexity:Operating system vendors in Cupertino and Mountain View are tightening API access for third-party monitoring tools, constraining technical feasibility for cross-platform solutions.
- Localization cost fragmentation:India's IT Rules mandate traceability and content removal timelines that force redundant filtering engine development for single-country compliance.
- VPN-based traffic inspection limitations:Encrypted DNS and TLS 1.3 adoption by browser vendors is degrading the efficacy of network-layer content filtering, threatening the technical foundation of established products.
Strategic Opportunities
- Rural Indian households:Domestic app developers are narrowing the affordability gap through localized content filtering priced below international subscription tiers.
- AI-driven risk detection convergence:Natural language processing and behavioral biometrics are combining to enable predictive intervention before harmful exposure occurs.
- Enterprise-education hybrid channels:Microsoft's Windows ecosystem integration demonstrates how operating system bundling can displace standalone software procurement in institutional settings.
Industry Challenges
- Machine learning engineering scarcity:Vendors competing on alert specificity require talent pools concentrated in San Francisco, London, and Bangalore, inflating R&D cost structures.
- Multi-jurisdiction certification timelines:Divergent age-verification architectures between US state statutes and federal privacy frameworks are fragmenting product roadmaps and delaying release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parental Control Software Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.57 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Content Filtering, Screen Time Management, Location Tracking, App Blocking, Social Media Monitoring Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Application, Browser Extension Application: Home Use, Educational Institutions, Childcare Centers, Public Libraries, Community Centers End User: Parents, Guardians, Educators, Caregivers, Child Safety Organizations |
| Companies Covered | Norton Family, Microsoft Family Safety, Aura Parental Controls, Mobicip, Google Family Link, Qustodio, Net Nanny, mSpy, Bark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parental Control Software Market Strategic Shifts & Innovations
On-device machine learning inference is shifting competitive differentiation from rule-based filtering accuracy toward predictive behavioral modeling, compressing the value of static content databases.
Edge-deployed neural networks for real-time image and text classification are reducing latency in risk detection from seconds to milliseconds. K-12 technology coordinators in Texas and Florida are piloting these systems for district-wide deployment. The migration from cloud-based analysis is rendering obsolete the subscription revenue models tied to server-side processing capacity.
The EU Digital Services Act's transparency reporting requirements are mandating algorithmic accountability disclosures from platforms. Parental control vendors must now document how their filtering decisions align with platform content moderation standards. European households with diverse linguistic needs are driving demand for multi-language interface compliance that exceeds baseline translation requirements.
Educational procurement officers are consolidating vendor relationships through multi-year enterprise agreements that bundle device management with safety software. This consolidation is displacing the fragmented purchasing patterns of individual school principals. District-level contracting in California and New York is most visible, with standardized RFP templates favoring integrated platform providers over specialized point solutions.
Parental Control Software Market Segmentation
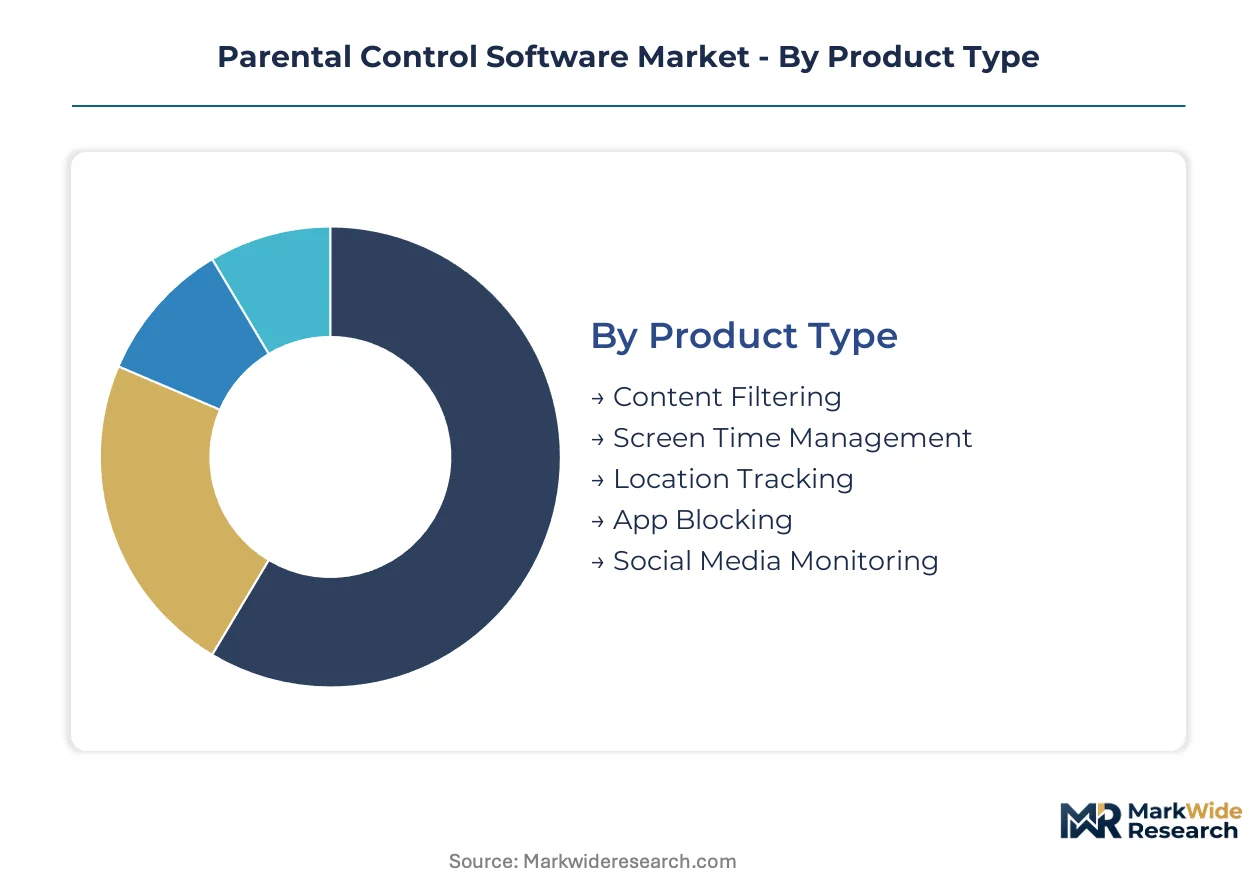
Segmentation in parental control software reveals how procurement authority and technical architecture reshape competitive positioning. Vendors must architect distinct value propositions for household subscribers versus institutional buyers with divergent compliance requirements and deployment scale.
Product Type:
Mature filtering capabilities anchor established revenue streams while emerging AI-driven monitoring functions capture premium pricing from anxious high-income segments.
- Content Filtering:Database-driven URL and keyword blocking operates through kernel-level permissions or VPN-based traffic inspection. K-12 technology coordinators in Texas and Florida prioritize this function for district-wide deployment due to CIPA compliance requirements.
- Social Media Monitoring:Natural language processing engines scan messaging platforms for risk indicators including cyberbullying and self-harm references. High-income households in California and New York drive premium subscription uptake for alert specificity.
- Screen Time Management:Device-level scheduling and usage quotas enforce daily limits across operating systems.
- Location Tracking:GPS geofencing and real-time position monitoring serve caregiver anxiety reduction.
- App Blocking:Whitelist and blacklist controls restrict software installation and execution permissions.
Content Filtering retains volume leadership; Social Media Monitoring holds the steepest expansion curve.
Deployment:
Cost tier differentiation separates enterprise-grade infrastructure from affordable consumer solutions, with hybrid architectures emerging as the compromise for mid-market educational buyers.
- Cloud-Based:Scalable server-side processing enables centralized policy management across thousands of student accounts. Educational procurement officers in California and New York favor this model for multi-campus administration.
- Mobile Application:Native iOS and Android deployment bypasses desktop installation friction for smartphone-native guardianship. Indian households demonstrate accelerating adoption as domestic developers price below international tiers.
- On-Premises:Local server installation meets data residency requirements for privacy-sensitive institutions.
- Hybrid:Mixed cloud-edge architecture balances scalability with latency reduction for real-time intervention.
- Browser Extension:Lightweight plugin deployment offers entry-level filtering without system-level permissions.
Cloud-Based deployment commands the largest institutional contract value; Mobile Application delivery gains share fastest among consumer segments.
Application:
Customer type concentration varies dramatically between subscription-driven household markets and procurement-cycle-dependent institutional sales.
- Home Use:Individual family subscriptions purchased through app stores or direct vendor websites. State-level digital safety mandates in Texas and Florida are compressing procurement cycles for educational institutions, indirectly validating parental purchasing decisions.
- Educational Institutions:K-12 schools and universities require CIPA compliance documentation and audit trail preservation. District-level contracting in California and New York consolidates vendor relationships through multi-year enterprise agreements.
- Childcare Centers:Licensed facilities with shared device pools and liability exposure to minor-accessed content.
- Public Libraries:Municipal funding streams and First Amendment considerations complicate filtering policy design.
- Community Centers:Non-profit and faith-based organizations with limited IT staffing capacity.
Home Use generates the highest unit volume; Educational Institutions produce the steepest contract value expansion.
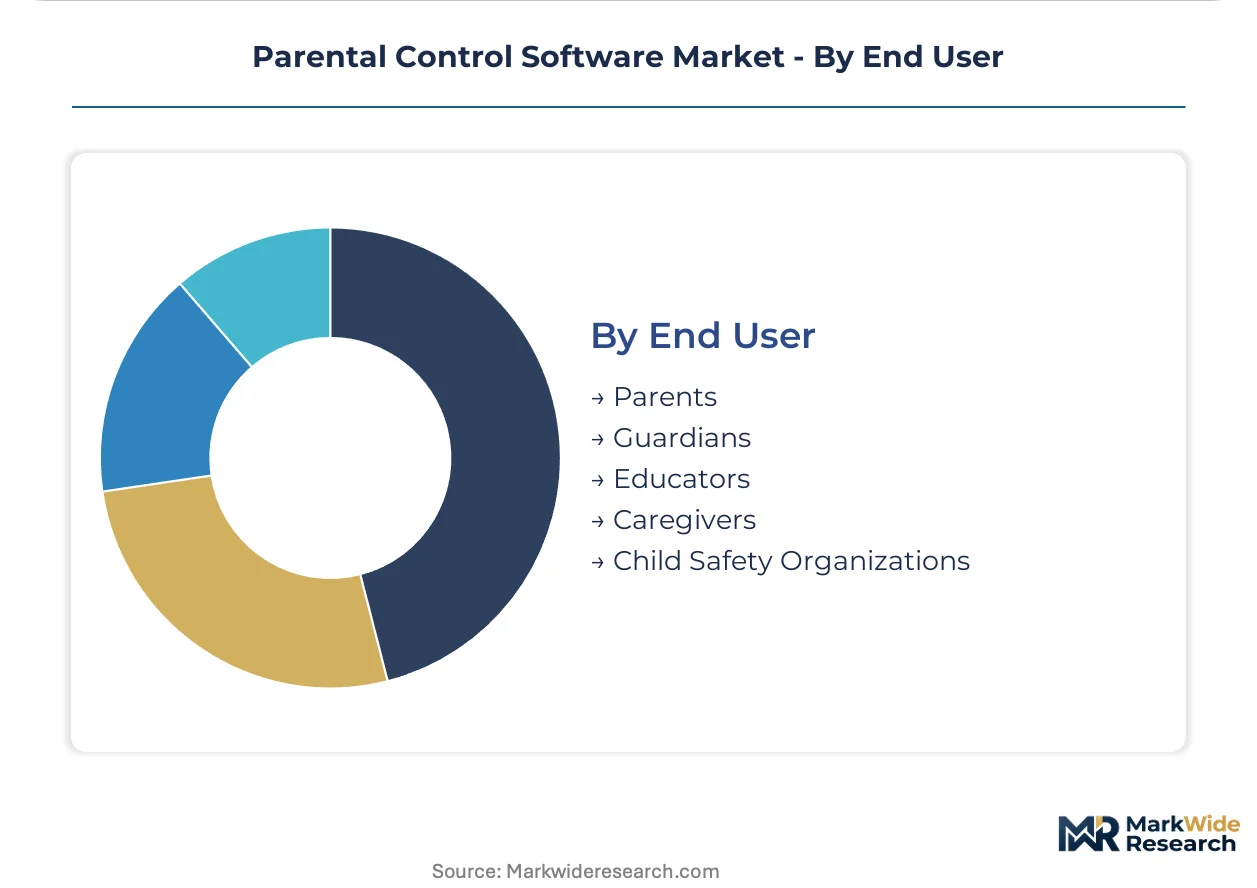
End User:
Margin structure diverges between price-sensitive individual purchasers and compliance-motivated institutional buyers with budget authority.
- Parents:Primary purchasing decision-makers for household subscriptions, motivated by anxiety reduction and convenience. GDPR child-protection provisions in European households with diverse linguistic needs drive demand for multi-language interface compliance.
- Educators:K-12 technology coordinators and administrators with district-level procurement authority. COPPA age-verification requirements compel platform integration of parental consent workflows, expanding the addressable base for control software vendors.
- Guardians:Legal caregivers with custody-based responsibility for minor digital safety.
- Caregivers:Professional childcare providers with employer-mandated monitoring obligations.
- Child Safety Organizations:Non-profit advocacy groups recommending or subsidizing software adoption.
Parents represent the largest addressable population; Educators command the highest per-seat contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development talent concentrates in the United States, India, and Western Europe, creating regional specialization in enterprise-grade solutions versus affordable consumer deployments. Vendors in Bangalore and Hyderabad compete on cost-optimized mobile applications, while California and New York clusters dominate AI-driven risk detection. Regulatory divergence across jurisdictions forces redundant compliance engineering, fragmenting product architectures.
United States
State-level digital safety mandates in Texas and Florida compress procurement cycles for educational institutions. COPPA age-verification requirements compel platform integration of parental consent workflows, expanding vendor addressable markets. Silicon Valley clusters anchor AI engineering talent for behavioral prediction models, while K-12 technology coordinators in California pilot edge-deployed neural networks for district-wide deployment.
India
Domestic app developers in Bangalore and Hyderabad narrow affordability gaps through localized content filtering priced below international tiers. IT Rules mandate traceability and content removal timelines that force redundant filtering engine development for single-country compliance. Mumbai and Delhi-NCR households demonstrate accelerating smartphone-native guardianship adoption as cloud-based deployment models bypass desktop installation friction.
Germany
GDPR child-protection provisions tighten compliance requirements for software vendors seeking European market access. The EU Digital Services Act mandates platform-level safety tools, creating procurement from social media and gaming companies. Berlin and Munich technology clusters develop multi-language interface solutions for European households with diverse linguistic needs, exceeding baseline translation requirements.
United Kingdom
Online Safety Bill provisions impose age-verification and content moderation duties on platforms, reshaping product design requirements. London's fintech and edtech clusters drive enterprise-education hybrid channel development through multi-year vendor agreements. Scottish and Welsh educational authorities consolidate procurement through standardized RFP templates favoring integrated platform providers over specialized point solutions.
Japan
METI guidelines on digital child welfare encourage platform adoption of parental control integrations in mobile ecosystems. Tokyo and Osaka metropolitan areas concentrate demand for screen time management tools as smartphone penetration among minors accelerates. Yokohama-based educational technology coordinators pilot cloud-based deployment for multi-campus administration, favoring centralized policy management architectures.
Parental Control Software Market Key Industry Players
Operating system incumbents and specialized cybersecurity vendors split the market between bundled ecosystem solutions and standalone feature-rich platforms. Microsoft and Google leverage device operating systems to displace independent software procurement through pre-installed family safety tools. Three archetypes dominate: ecosystem-anchored giants with distribution advantages, AI-specialized boutiques competing on alert specificity, and regional cost-optimized developers serving price-sensitive emerging markets. Competitive dynamics center on API access negotiations with mobile operating system vendors and enterprise-education channel consolidation through multi-year district contracts.
Among ecosystem-anchored providers, Microsoft Family Safety and Google Family Link represent the bundling strategy that threatens standalone vendor economics. Qustodio occupies a position within the European specialization tier, exemplifying multi-language interface development for diverse linguistic markets. Bark anchors the AI-driven risk detection archetype, sitting within the premium alert-specificity segment that commands pricing power from anxious high-income households. Norton Family and Net Nanny represent legacy cybersecurity heritage, positioned between ecosystem bundling and specialized feature depth.
| Leading Market Players |
|---|
| Norton Family |
| Microsoft Family Safety |
| Aura Parental Controls |
| Mobicip |
| Google Family Link |
| Qustodio |
| Net Nanny |
| mSpy |
| Bark |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber-optic cable routes carry cloud infrastructure costs that compress margin structures for SaaS vendors serving educational procurement officers in California and New York, while simultaneously enabling price differentiation between latency-sensitive AI monitoring tiers and basic filtering subscriptions.
Pricing Analysis
COPPA age-verification requirements dictate the pricing tier structure by forcing compliance engineering overhead into base subscription costs. Three-tier pricing structure across premium, standard, and economy levels separates AI-driven behavioral prediction from rule-based URL blocking from freemium browser extensions. Price differentiation rests on alert specificity and multi-language interface depth. Cost compression in the economy tier is intensifying because domestic Indian developers undercut international subscription rates. Individual parents in Mumbai and Delhi-NCR demonstrate highest price sensitivity; district-level technology coordinators in Texas and Florida show lowest sensitivity due to CIPA compliance budget authority.
Supply Chain Analysis
Cloud compute infrastructure feeds from hyperscaler data center concentration in the United States, Ireland, and Singapore. Raw material dependencies include GPU clusters for neural network training, encrypted DNS routing hardware, and mobile operating system API access licenses. Supply chain risk centers on single-source vulnerability to Apple and Google kernel-level permission restrictions that degrade cross-platform technical feasibility. Distribution runs through app store marketplaces and direct enterprise sales teams serving K-12 procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operating system pre-installed family safety tools threaten standalone vendor economics, forcing substitution defense through AI differentiation and channel control.
For Market Incumbents: Pre-empt ecosystem bundling by deepening API access negotiations with mobile operating system vendors and anchoring multi-year district contracts before procurement consolidation completes. Vertical integration into on-device machine learning inference reduces cloud infrastructure cost exposure. Threat: Microsoft and Google pre-installation displaces standalone software procurement in institutional settings. For New Entrants and Emerging Players: Establish a beachhead in rural Indian households where domestic developers have proven localized content filtering priced below international tiers. Target childcare centers and community centers with limited IT staffing capacity as the most penetrable segment. Go-to-market angle: employer-mandated monitoring obligations for professional caregivers. For Investors and Strategic Acquirers: Carve-out targets emerge from cybersecurity heritage firms positioned between ecosystem bundling and specialized feature depth, where AI engineering talent scarcity inflates R&D cost structures. Long-term viability favors vendors with enterprise-education hybrid channel control and predictive behavioral modeling capabilities. Signal to watch: district-level RFP template standardization favoring integrated platform providers over point solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Windows ecosystem bundling displaces standalone procurement in California and New York districts. |
| Acquisition of Specialist Firm | AI-driven risk detection boutiques in San Francisco and Bangalore compress development timelines for behavioral prediction. |
| Geographic Expansion | Domestic Indian developers in Bangalore and Hyderabad capture rural household demand through localized pricing. |
| Product Launch | Edge-deployed neural networks in Texas and Florida K-12 pilots reduce latency from seconds to milliseconds. |
| Strategic Partnership | Multi-language interface development with Berlin and Munich clusters serves GDPR-mandated European compliance. |
Research Approach
Initial hypotheses were tested against primary input from K-12 technology coordinators, parental control software product managers, educational procurement officers, and mobile platform engineering leads, and refined through secondary validation against SEC filings, App Annie deployment data, hyperscaler capex disclosures, and EU Digital Services Act transparency reports. Bottom-up triangulation across household subscription volumes and top-down validation against institutional contract values anchored market sizing.
Demand-supply balance framing modeled deployment architecture, organization size, vertical integration complexity, regional regulatory cluster, and AI inference location across the analysis window. CAGRs derived from segment-level adoption curve analysis and compliance-driven procurement cycle compression. Forecast inputs included state-level digital safety mandate implementation timelines and encrypted DNS adoption rates degrading VPN-based filtering efficacy.
Sensitivities concentrate around Apple and Google API access restriction severity, Indian IT Rules traceability compliance cost escalation, and TLS 1.3 browser encryption degradation of network-layer inspection. Cross-checking against district-level RFP award databases and app store download velocity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Log Management Market
Security Software
Video Intercom Devices and Equipment Market
Security Software
Cybersecurity Software Market
Security Software
Digital Risk Protection Software Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Hardware Encryption Market
Security Software
Mobile Identity Management Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Global Mobile Identification Market
Security Software
Data Leakage Prevention Product Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Global Advanced Authentication Market
Security Software
Anomaly Detection Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
VPN Software Market
Security Software
Asia-Pacific Extended Detection and Response Market