
 Spam Blocking Software Market | 2026-2036
Spam Blocking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Spam Blocking Software Market Insights
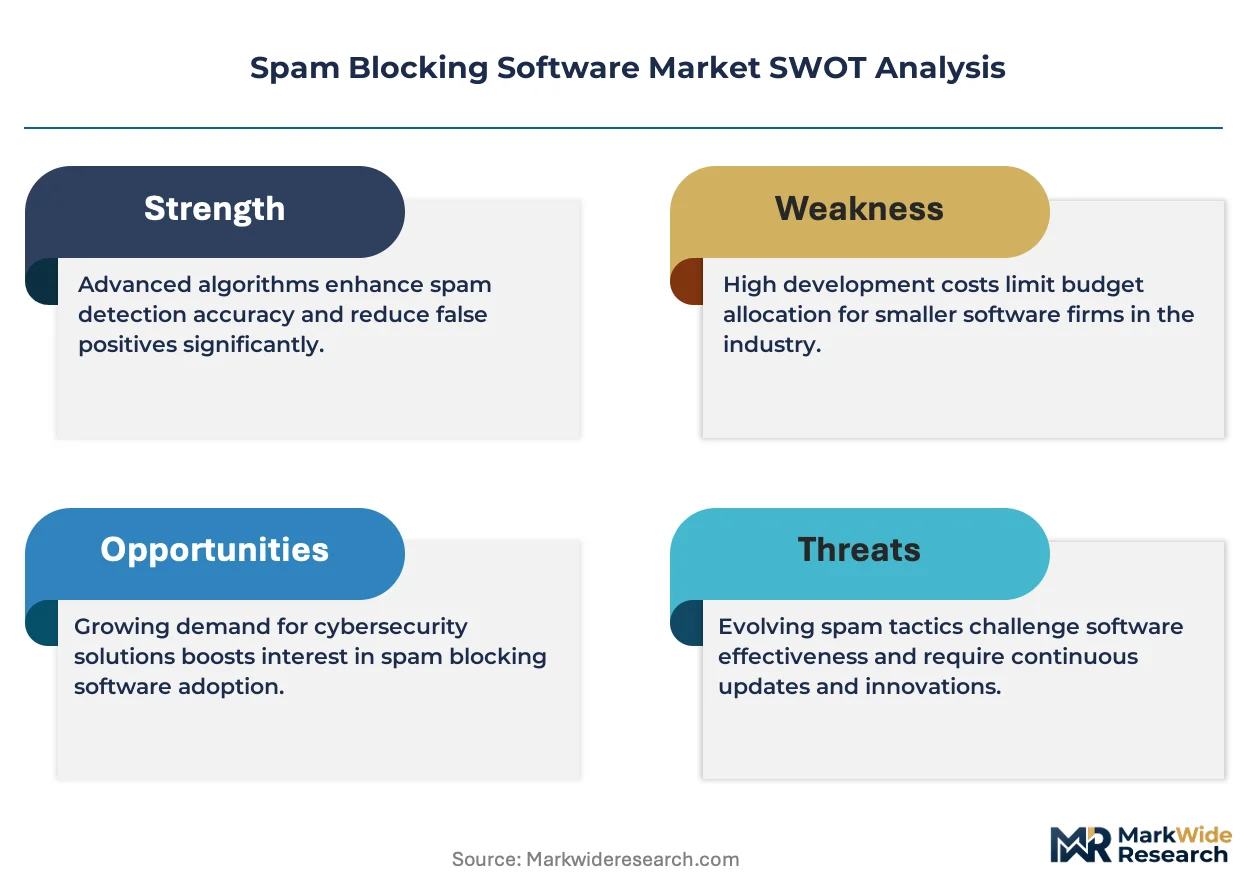
A widening R&D spend gap between hyperscale platforms and point-solution vendors is reorganizing competitive tiers in spam blocking software. Microsoft Corporation leverages its cloud infrastructure to bundle anti-spam capabilities across enterprise productivity suites. Proofpoint anchors its position through specialized email security for regulated industries. Barracuda Networks competes on appliance-to-cloud migration paths for mid-market customers.
Spam blocking software comprises programmatic systems that inspect email headers, content payloads, and sender reputation scores to intercept unsolicited or malicious messages before delivery to user inboxes. These systems employ heuristic analysis, Bayesian filtering, and real-time threat intelligence feeds to achieve detection rates exceeding commercial thresholds for enterprise security. Cloud-based deployment now captures the fastest expansion as organizations retire on-premises gateways. Security suites integrating machine learning features command premium positioning against standalone anti-spam tools. SMEs represent an underpenetrated endpoint segment where channel economics favor simplified subscription packaging over complex enterprise licensing.
FCC guidance on telecommunications security, GDPR enforcement across European jurisdictions, and HIPAA requirements for healthcare communications collectively elevate baseline compliance spending on email protection. Japan's METI cybersecurity frameworks and India's IT Act provisions further fragment certification requirements for vendors operating across multiple geographies. Stakeholders must weigh sovereign data residency rules against the operational efficiency of centralized cloud architectures when selecting deployment models.
Market Dynamics
Cloud migration is compressing deployment timelines while AI-powered detection engines rewrite procurement specifications across enterprise security teams. Vendors must now bundle behavioral analytics and real-time threat intelligence to meet elevated baseline requirements.
Growth Catalysts
- GDPR enforcement:European data protection mandates compel organizations to deploy advanced email filtering systems with audit-ready logging capabilities and data residency controls.
- Financial services compliance:Banks and insurance carriers face intensified supervisory scrutiny over communication security, driving replacement cycles for legacy gateway appliances.
- Machine learning classification:Neural network models trained on billions of labeled messages now detect polymorphic phishing campaigns that signature-based systems miss entirely.
Market Restraints
- Hyperscale platform bundling:Microsoft embeds anti-spam capabilities within Office 365 subscriptions, compressing standalone vendor pricing power and channel margins.
- Technical debt in on-premises estates:Organizations running aging gateway hardware face complex migration paths to cloud-native architectures with feature parity gaps.
- Input cost volatility:GPU and specialized AI accelerator shortages inflate training infrastructure costs for vendors developing proprietary detection models.
Strategic Opportunities
- SME channel expansion:Managed service providers in Germany and Japan now package simplified anti-spam subscriptions for sub-500 employee organizations previously served by consumer-grade tools.
- Healthcare vertical specialization:HIPAA-compliant email security with automated PHI detection opens dedicated procurement channels among hospital systems and telehealth platforms.
- API-first integration:Native connectivity with SIEM and SOAR platforms allows vendors to embed filtering intelligence within broader security orchestration workflows.
Industry Challenges
- Adversarial ML expertise scarcity:Vendors struggle to recruit data scientists capable of hardening detection models against evasion techniques like adversarial perturbations and model inversion attacks.
- Multi-jurisdiction certification complexity:Simultaneous compliance with FCC telecommunications rules, Japan's METI cybersecurity frameworks, and India's IT Act provisions extends product launch timelines by 8-14 months.
- False positive calibration:Overly aggressive filtering damages business-critical communications, forcing security teams to manually tune thresholds that degrade automated protection value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spam Blocking Software Market |
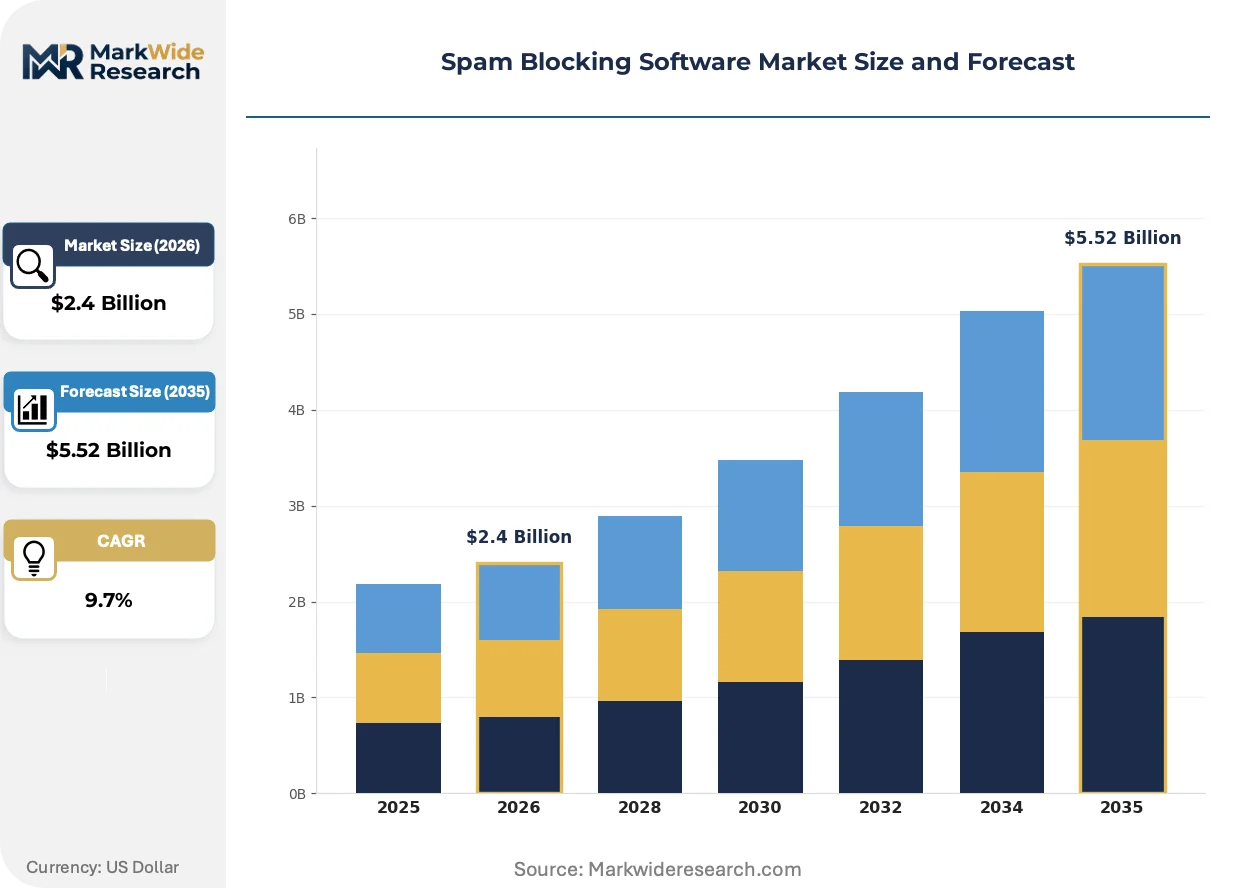
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Email Filters, Firewall Software, Anti-Spam Tools, Security Suites Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Integrated Systems End User: SMEs, Large Enterprises, Government Agencies, Non-Profits Feature: Machine Learning, Real-Time Protection, Reporting, Custom Filters |
| Companies Covered | Microsoft Corporation, Google LLC, Proofpoint, Cisco Systems, Barracuda Networks, Trend Micro, McAfee, Fortinet, SpamTitan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spam Blocking Software Market Trends and Innovations
Detection methodology is splitting between lightweight edge filtering and computationally intensive deep inspection, with deployment architecture choices increasingly determining competitive positioning. Vendors must now engineer for both latency-sensitive gateway deployment and cloud-scale analytics pipelines.
Natural language processing engines are bifurcating spam blocking software into two performance tiers. Transformer-based models analyze semantic intent and contextual anomalies across multilingual corpora. Large enterprises in financial services and healthcare deploy these systems for executive protection and sensitive transaction verification. The technology is bifurcating vendor capabilities, separating platforms with proprietary training data and inference infrastructure from commodity rule-based alternatives.
GDPR Article 32 security requirements and the EU AI Act's risk classification framework now explicitly cover automated communication filtering systems. Organizations processing EU personal data must document algorithmic decision-making logic and maintain human oversight mechanisms for high-risk deployments. German regulators have issued specific guidance on email security logging retention periods, forcing vendors to rearchitect data storage geographies.
Security teams now demand consolidated platforms over point-solution stacking, with email protection evaluated within broader zero-trust access architectures. Chief information security officers in United States healthcare and financial verticals prioritize vendors offering unified identity, endpoint, and messaging security. Japan's enterprise buyers similarly favor integrated suites from domestic system integrators over standalone foreign tools, reshaping competitive dynamics in the Asia-Pacific procurement landscape.
Spam Blocking Software Market Segmentation
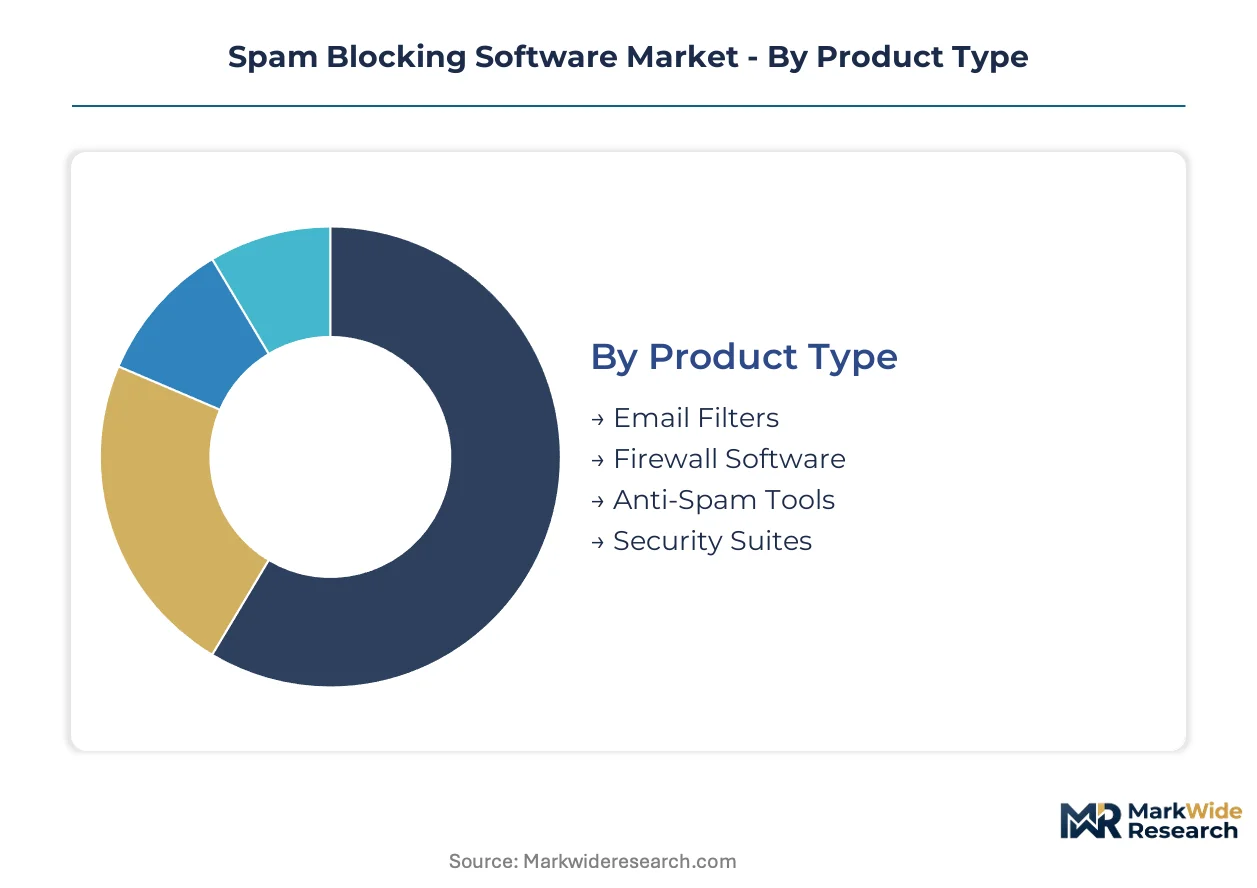
Spam blocking software procurement patterns diverge sharply across organizational scale and technical sophistication. Deployment architecture choices now determine vendor selection more than feature checklists alone.
Product Type:
Email Filters dominate domestic procurement in the United States, Germany, and Japan, while Security Suites capture cross-border enterprise contracts requiring harmonized compliance.
- Email Filters:Standalone header inspection and content analysis engines process message streams at network perimeters. Financial services firms in Frankfurt and Tokyo deploy these for high-volume transaction corridors where latency tolerance sits below 50 milliseconds. GDPR audit logging requirements now mandate encrypted retention architectures that inflate deployment costs by 15-25%.
- Security Suites:Integrated platforms bundle anti-spam with endpoint detection, identity management, and data loss prevention. Large enterprises across United States healthcare systems favor these for unified policy enforcement across Microsoft 365 and Google Workspace estates. Bundled pricing compresses standalone vendor margins while accelerating replacement cycles.
- Firewall Software:Network-layer inspection modules embedded within next-generation firewalls.
- Anti-Spam Tools:Lightweight browser extensions and client-side filtering for individual professionals.
Security Suites hold the largest share; momentum sits with Email Filters.
Deployment:
Cost tier stratification separates capital-intensive on-premises estates from operational-expense cloud subscriptions favored by mid-market buyers.
- Cloud-Based:SaaS delivery models eliminate hardware refresh cycles while enabling real-time threat intelligence ingestion. German Mittelstand firms and Japanese manufacturing SMEs adopt these for rapid deployment without dedicated security operations centers. Sovereign data residency requirements in France and Germany force vendors to maintain in-country processing nodes.
- Hybrid Solutions:Split architectures retain sensitive message inspection on-premises while offloading bulk filtering to cloud infrastructure. United States defense contractors and healthcare systems deploy these for HIPAA and ITAR compliance segmentation. Migration complexity and feature parity gaps slow adoption outside regulated verticals.
- On-Premises:Appliance-based gateways for air-gapped networks and classified environments.
- Integrated Systems:Embedded modules within broader security orchestration platforms.
Cloud-Based deployments command the dominant position; Hybrid Solutions are climbing the fastest.
End User:
Customer type determines pricing architecture, with annual contract values spanning three orders of magnitude across the segment spectrum.
- Large Enterprises:Multi-national organizations with 10,000+ seats negotiate custom SLAs and dedicated threat research support. United States financial services and healthcare verticals drive premium feature development including executive protection tiers and automated business email compromise remediation. Procurement cycles extend 12-18 months with extensive pilot programs.
- SMEs:Organizations below 500 employees previously served by consumer-grade tools now access enterprise-class protection through managed service provider packaging. German and Japanese channel partners bundle simplified subscriptions with Microsoft 365 reselling. Price sensitivity limits attach rates for advanced machine learning features.
- Government Agencies:Federal, state, and municipal entities with classified and unclassified network segmentation.
- Non-Profits:Grant-funded organizations prioritizing discounted or donated security licensing.
Large Enterprises contribute the greatest revenue concentration; SMEs show the steepest expansion trajectory.
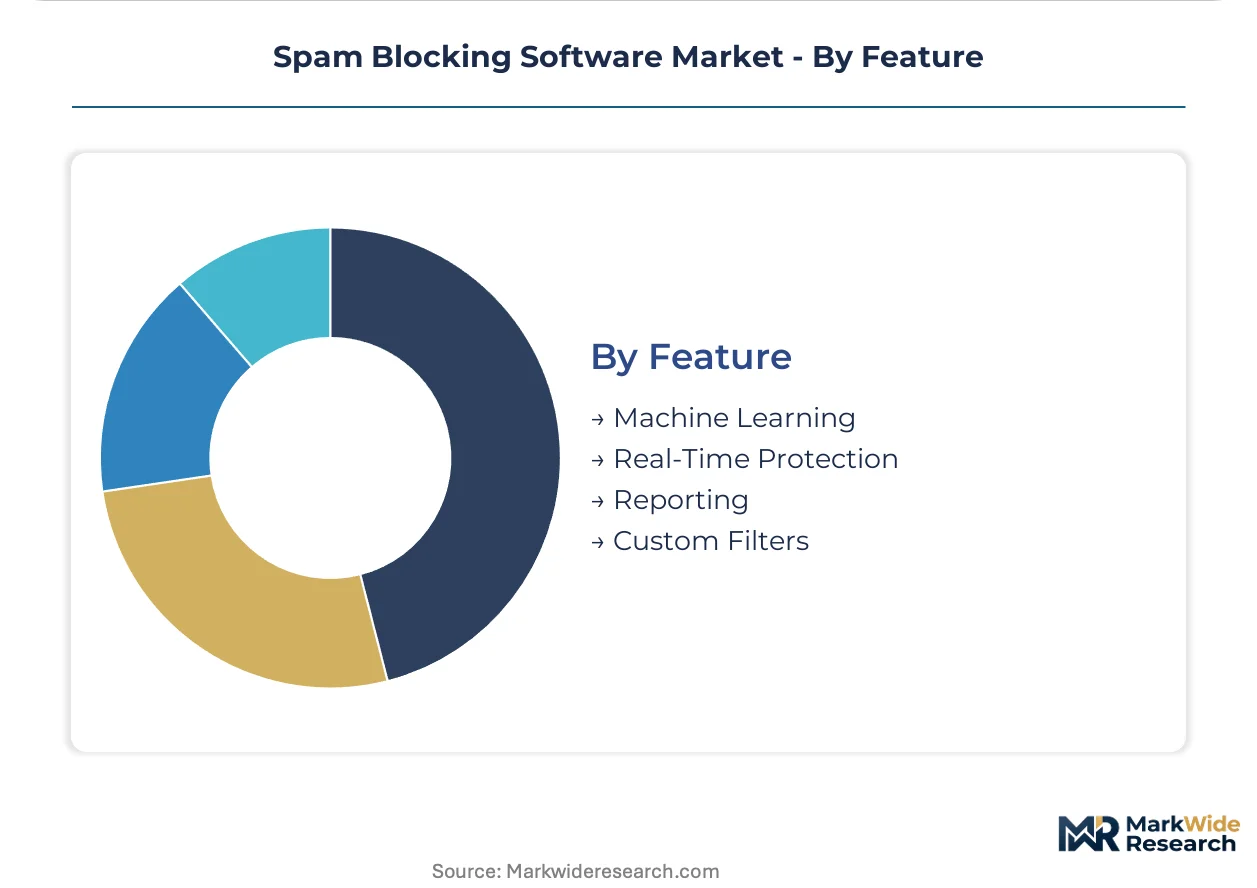
Feature:
Technology maturity separates baseline protection from premium positioning, with neural network capabilities now table stakes for enterprise procurement.
- Machine Learning:Transformer-based classification models trained on multilingual phishing corpora detect semantic anomalies and polymorphic payload evolution. United States and Japanese financial institutions deploy these for real-time wire fraud prevention and executive impersonation detection. Model training infrastructure costs favor hyperscale vendors with proprietary data lakes.
- Real-Time Protection:Sub-second threat intelligence ingestion and automated policy adjustment without administrator intervention. German automotive supply chains and United States healthcare networks prioritize these capabilities for ransomware delivery interception. Latency requirements constrain deployment to cloud-adjacent processing nodes.
- Reporting:Compliance dashboards and forensic message tracing for audit documentation.
- Custom Filters:Administrator-defined rules and allowlist management for specialized workflows.
Machine Learning features anchor premium pricing; Real-Time Protection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by substantial margins, reflecting divergent regulatory enforcement intensity and enterprise security budgets. German procurement teams command premium feature development through stringent compliance mandates. Japanese buyers favor domestic system integrators over foreign point solutions.
United States
Financial services firms in New York and healthcare systems in Boston drive replacement cycles for legacy gateway appliances. FCC telecommunications security guidance and HIPAA requirements elevate baseline spending on audit-ready email protection. Silicon Valley cloud providers anchor real-time threat intelligence development for neural network classification models.
Germany
Automotive supply chains in Stuttgart and Mittelstand manufacturing clusters demand sub-50-millisecond latency filtering for high-volume transaction corridors. GDPR Article 32 security requirements and BSI technical guidelines mandate encrypted retention architectures with sovereign data residency controls. Frankfurt financial institutions negotiate custom SLAs with dedicated threat research support.
Japan
Tokyo-based enterprises and Osaka manufacturing hubs prioritize integrated security suites from domestic system integrators over standalone foreign tools. METI cybersecurity frameworks and JIS standards fragment certification requirements for cloud-native deployments. Nagoya automotive electronics clusters drive demand for hybrid architectures with on-premises sensitive message inspection.
India
Bengaluru IT services exporters and Mumbai financial institutions accelerate cloud migration despite price sensitivity limiting attach rates for advanced machine learning features. IT Act provisions and RBI cybersecurity guidelines for banks compel deployment of automated policy adjustment capabilities. Hyderabad data center clusters host regional processing nodes for sovereign data compliance.
United Kingdom
London financial services firms and Cambridge technology clusters evaluate email protection within broader zero-trust access architectures. UK GDPR enforcement and Financial Conduct Authority operational resilience requirements drive consolidated platform procurement over point-solution stacking. Manchester healthcare networks deploy HIPAA-compliant systems with automated PHI detection for telehealth platforms.
Spam Blocking Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where hyperscale platforms bundle capabilities while specialists command premium positioning in regulated verticals. The vendor base separates into three strategic archetypes: cloud infrastructure owners integrating anti-spam across productivity suites, email security specialists anchoring through compliance expertise, and network security incumbents migrating appliance customers to SaaS delivery. Dominant competitive moves include M&A activity to acquire machine learning talent and strategic partnerships with managed service providers to penetrate SME channels.
Among hyperscale platform providers, Microsoft Corporation exemplifies the bundling archetype through cloud infrastructure integration, while Proofpoint occupies a specialist position serving regulated industries with dedicated compliance features. Barracuda Networks sits within the migration-focused tier, addressing mid-market customers transitioning from on-premises appliances to cloud-native architectures.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Proofpoint |
| Cisco Systems |
| Barracuda Networks |
| Trend Micro |
| McAfee |
| Fortinet |
| SpamTitan |
| Others |
Pricing and Supply Chain Analysis
GDPR Article 32 security requirements and the EU AI Act's risk classification framework gate both vendor qualification and price differentiation simultaneously, forcing compliance investments that stratify offerings across certification tiers while compressing margins for non-compliant entrants. Cloud infrastructure ownership and proprietary AI training data now separate pricing power between hyperscale platforms and point-solution specialists.
Pricing Analysis
Configured-to-order pricing for custom SLAs and dedicated threat research support commands substantial premiums over standard SaaS tiers. The market operates on a subscription-based SaaS model with three-tier pricing structure across premium, standard, and economy levels, where machine learning capabilities and real-time protection features anchor premium positioning. Price differentiation rests on certification grade for HIPAA and GDPR compliance plus vertical specialization depth. Cost compression in the mid-market intensifies because Microsoft bundles anti-spam within Office 365 subscriptions. SMEs exhibit highest price sensitivity, while United States financial services firms show lowest sensitivity due to regulatory penalty exposure.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure and data center operations for real-time threat intelligence processing, while India and Poland host engineering and machine learning development centers. GPU and specialized AI accelerator supply draws from Taiwan Semiconductor Manufacturing and NVIDIA's fabrication networks, with cloud compute capacity sourcing from hyperscaler regions. Firmware and embedded security modules rest on semiconductor supply from South Korea and Japan. Single-source vulnerability in AI accelerator supply creates bottleneck risk for vendors training proprietary detection models. Distribution runs through direct enterprise sales teams, managed service provider channels, and cloud marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adversarial machine learning expertise scarcity constrains product development velocity, with vendors competing for data scientists capable of hardening detection models against evasion techniques. This capability gap favors organizations with captive training data lakes and established research partnerships.
For Market Incumbents: Secure proprietary training data reservoirs and adversarial ML research capabilities to defend against hyperscale platform bundling. Invest in vertical-specific compliance certifications for HIPAA and GDPR to maintain premium positioning in healthcare and financial services. Channel control through managed service provider exclusivity agreements protects SME market share against emerging entrants. For New Entrants and Emerging Players: Differentiate on API-first integration architectures that embed filtering intelligence within SIEM and SOAR orchestration workflows. Target German Mittelstand manufacturing clusters and Japanese automotive electronics hubs with hybrid deployment solutions addressing sovereign data residency requirements. Go-to-market through regional system integrators with existing compliance advisory relationships accelerates trust-building in regulated verticals. For Investors and Strategic Acquirers: The EU AI Act's high-risk system classification reshapes the acquisition landscape by elevating vendors with documented algorithmic decision-making logic and human oversight mechanisms. Long-term viability centers on platforms with sustainable data moats and multi-jurisdiction certification infrastructure. Acquisition target archetypes include specialist firms with healthcare PHI detection capabilities and adversarial ML research teams. Signal to watch: regulatory enforcement actions against non-compliant filtering systems in European jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native SIEM and SOAR connectivity embeds filtering within broader security orchestration workflows at United States healthcare systems. |
| Acquisition of Specialist Firm | Adversarial ML talent and proprietary phishing corpora accelerate detection model hardening against evasion techniques. |
| Geographic Expansion | In-country processing nodes in Frankfurt and Tokyo satisfy GDPR and METI sovereign data residency mandates. |
| Strategic Partnership | Managed service provider alliances in Germany and Japan penetrate SME channels previously served by consumer-grade tools. |
| Product Launch | Healthcare vertical specialization with automated PHI detection opens dedicated procurement channels among hospital systems. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with CISOs, IT procurement officers, channel partners, and compliance directors at financial services and healthcare organizations; and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie integration data, and regulatory enforcement databases. Bottom-up triangulation across deployment model adoption curves and top-down validation against aggregate security software spending produced convergent estimates. Primary fieldwork concentrated on United States, German, and Japanese enterprise buyers with documented replacement cycles.
Across the analysis window, the forecasting framework modeled segmentation dimensions including deployment architecture, organization size tier, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from weighted average growth across these segments with elasticity adjustments for compliance mandate intensity. Industry-specific inputs included cloud migration velocity indices, GPU infrastructure availability curves, and adversarial ML capability diffusion rates.
Decision-makers should treat outputs as directional under assumptions of sustained GDPR enforcement intensity and continued hyperscaler bundling pressure; material deviation in regulatory timelines or AI accelerator supply would warrant model refresh. Specific risks that could revise forecasts include adversarial ML talent availability shocks, sovereign data rule fragmentation, and platform bundling acceleration. Recalibration cycles align with material shifts in compliance enforcement patterns and cloud infrastructure ownership concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Asia-Pacific Smart Doorbell Market
Security Software
Global User Provisioning Market
Security Software
Encryption Software Market
Security Software
Global Secure Access Service Edge Market
Security Software
Secure Digital Card Market
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Software Assurance Market
Security Software
Anomaly Detection Market
Security Software
Endpoint Detection and Response [EDR] Market
Security Software
Security Software for Consumers Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
Cloud Intrusion Protection Software Market
Security Software
BYOD Security Market
Security Software
Software Defined Perimeter (SDP) Market
Security Software
Key Management Service Market