
 Weatherstrip Seal Market | 2026-2036
Weatherstrip Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Weatherstrip Seal Market Analytics
Aftermarket service revenue is reconfiguring competitive economics in the weatherstrip seal industry. Cooper Standard leverages its integrated manufacturing footprint across North America and Europe to sustain pricing power in OEM supply contracts. Toyoda Gosei anchors its position through deep relationships with Japanese automakers, while Hutchinson competes via diversified exposure to both automotive and aerospace sealing applications.
A weatherstrip seal is an elastomeric or thermoplastic closure device installed at the interface between movable and fixed building or vehicle components to block air, moisture, dust, and acoustic transmission, typically manufactured through continuous extrusion of EPDM, PVC, or silicone compounds followed by flocking or coating treatments for reduced friction. EPDM formulations dominate automotive applications due to ozone resistance and temperature stability across underhood environments, while silicone segments command premium positioning in appliance and industrial equipment settings where thermal cycling extremes exceed standard elastomer thresholds. The application dimension splits sharply: automotive channels absorb the majority volume, yet construction end-use is gaining traction as building energy codes tighten across developed markets.
The US EPA regulates volatile organic compound emissions from sealant manufacturing processes, while the EU REACH framework restricts certain phthalate plasticizers in PVC-based weatherstrip formulations. Japan's METI enforces energy-efficiency standards for residential and commercial building envelopes that directly specify seal performance ratings. Stakeholders must monitor evolving chemical substance restrictions and building code harmonization trends to align material portfolios with compliance trajectories.
Market Dynamics
Automotive OEM consolidation toward modular sealing platforms is compressing supplier margins while elevating technical qualification barriers. Tier 1 manufacturers now specify integrated door-sealing modules rather than discrete weatherstrip components, forcing material suppliers to absorb design responsibility and warranty liability previously held by vehicle assemblers.
Growth Catalysts
- EPDM Formulation Advances:Peroxide-cured EPDM compounds with enhanced compression set resistance are extending service intervals in commercial vehicle applications. Fleet operators in Germany and Japan specify these grades for total cost of ownership reduction.
- EU Ecodesign Standards:Building envelope performance mandates under the EU Green Deal are specifying U-value thresholds that require high-performance perimeter sealing. Residential construction channels in France and Italy are converting from PVC to thermoplastic elastomer systems.
- US EPA VOC Regulations:Emission controls on solvent-based flocking adhesives are accelerating waterborne coating adoption. Seal manufacturers serving the US automotive aftermarket are retooling finishing lines to maintain EPA compliance.
Market Restraints
- Petrochemical Feedstock Volatility:EPDM polymer production depends on ethylene and propylene monomer supply from steam cracker operations. Price swings in naphtha-derived feedstocks compress compounder margins during crude oil volatility cycles.
- Japanese Supplier Concentration:Precision extrusion die manufacturing for complex co-extruded profiles concentrates among specialized toolmakers in Osaka and Nagoya. Lead times for custom die sets extend to 16 weeks during capacity constraints.
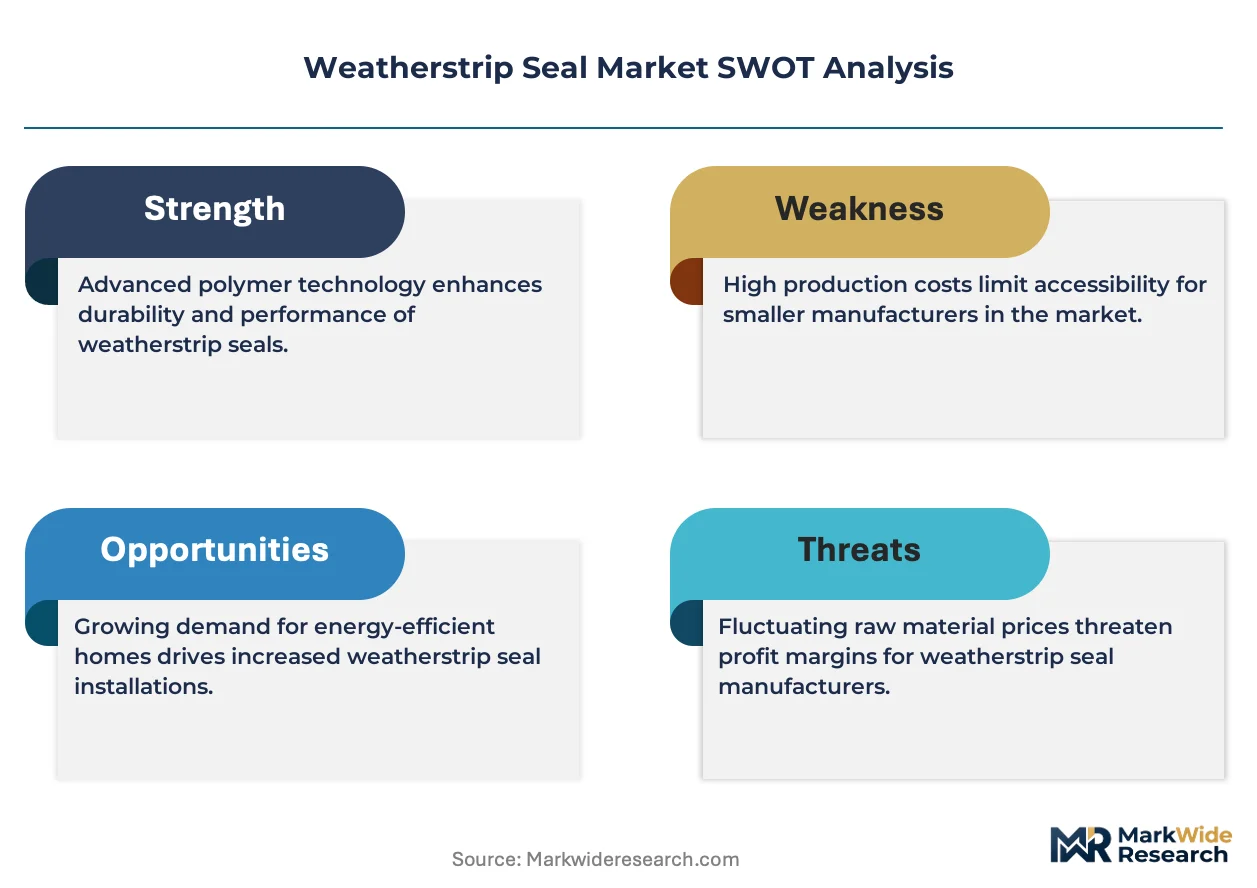
- Silicone Substitution Ceiling:High-temperature appliance applications above 150°C require silicone rubber weatherstrips. EPDM cannot displace silicone in oven door and industrial equipment seals despite significant cost premiums.
Strategic Opportunities
- Indian Building Code Alignment:Bureau of Indian Standards energy-efficiency ratings for commercial envelopes are creating specification pull for EPDM-based window seals. Domestic fenestration manufacturers lack qualified local compound sources.
- EV Battery Pack Sealing:IP67 ingress protection requirements for electric vehicle battery enclosures are expanding addressable market beyond traditional door and glass-run channels. Thermal runaway containment specifications favor intumescent EPDM grades.
- REACH-Compliant Plasticizer Systems:Phthalate restrictions under EU REACH Article 33 are disqualifying legacy PVC formulations. Bio-based plasticizer alternatives in TPE compounds command 15-20% price premiums in specification-driven markets.
Industry Challenges
- Multi-Material Bonding Expertise:Co-extruded profiles combining dense EPDM carriers with sponge rubber bulbs and thermoplastic slide coatings require process engineers with rare cross-polymer processing experience. Technical workforce gaps constrain capacity expansion.
- OEM Validation Timelines:Automotive platform sealing qualifications demand 24-36 month validation cycles including accelerated aging, environmental cycling, and full-vehicle water intrusion testing. Capital commitment precedes revenue realization by multiple fiscal years.
- Legacy Fleet Service Complexity:Aftermarket channels must maintain compound compatibility with 15-20 year vehicle populations spanning multiple EPDM formulation generations. Inventory proliferation strains distributor working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weatherstrip Seal Market |
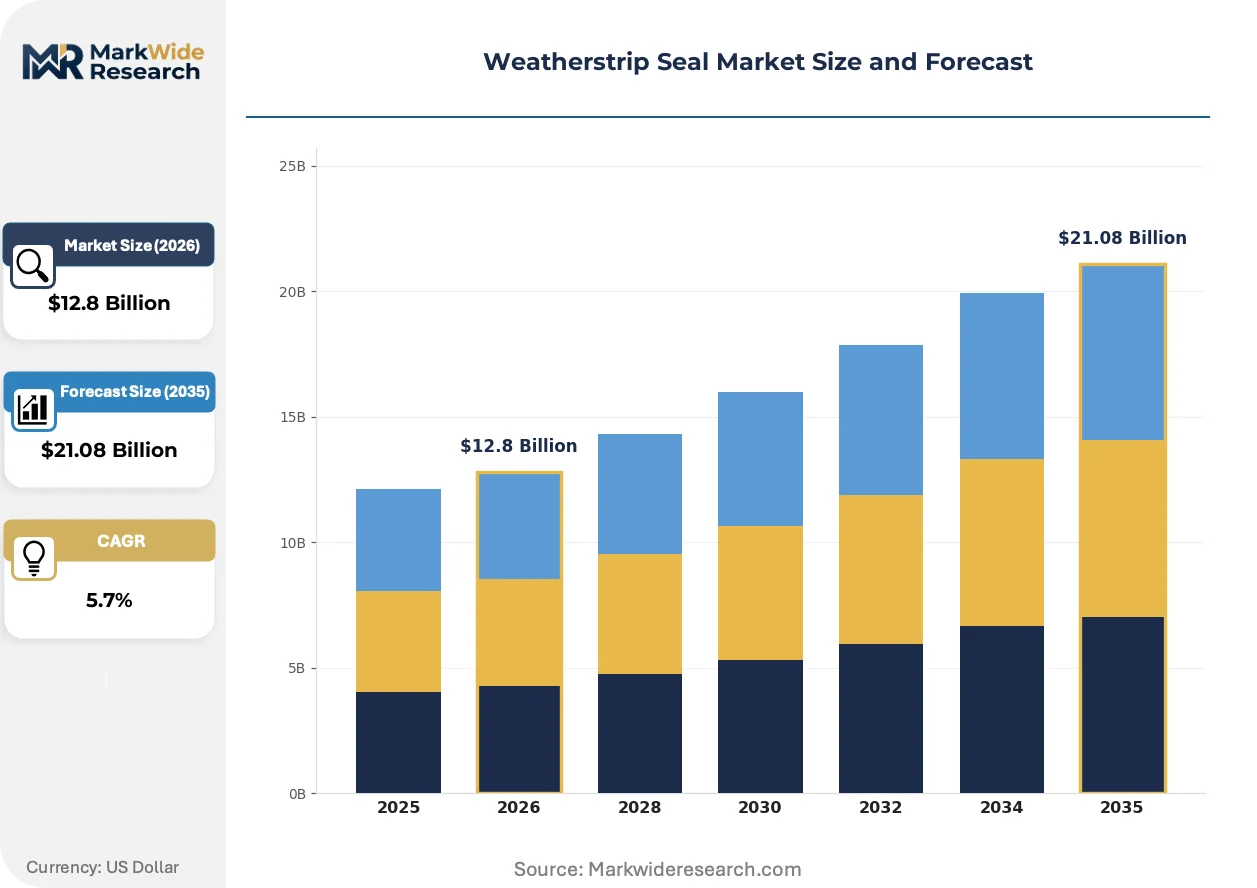
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, PVC, Neoprene, Silicone Application: Automotive, Construction, Appliances, Industrial Equipment End User: OEMs, Retail Customers, Contractors, Manufacturers Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Cooper Standard, Toyoda Gosei, Hutchinson, Henniges, Nishikawa Rubber, SaarGummi, Kinugawa Rubber, Magna, Hwaseung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weatherstrip Seal Market Evolving Landscape
Material science convergence with digital manufacturing is restructuring how weatherstrip seals are designed, validated, and produced. Computational fluid dynamics now predicts compression load deflection before physical prototyping, compressing development cycles and reducing tooling risk.
Thermoplastic vulcanizate injection molding is rendering obsolete traditional rubber extrusion-and-splice fabrication for low-complexity automotive glass-run channels. Korean and Chinese OEMs are adopting TPV systems for A-pillar and B-pillar seals in mass-market vehicle platforms. The shift enables in-line color matching and eliminates post-cure oven requirements, collapsing floor space needs by 40% in greenfield plants.
REACH Annex XVII restrictions on medium-chain chlorinated paraffins are forcing reformulation of EPDM compound flame-retardant packages. Compounders serving the European construction and rail sectors are migrating to phosphorus-based and mineral hydrate alternatives. The regulatory pressure concentrates technical service investment on halogen-free certification pathways, disadvantaging smaller compounders without analytical laboratory infrastructure.
Fleet operators and property managers are consolidating seal procurement into multi-year performance contracts with defined leakage-rate guarantees. Automotive lessors and commercial real estate owners in the United States now specify outcome-based agreements where suppliers bear replacement cost risk for premature seal degradation. The model transfers technical accountability downstream while compressing supplier margins through risk-adjusted pricing.
Weatherstrip Seal Market Segmentation
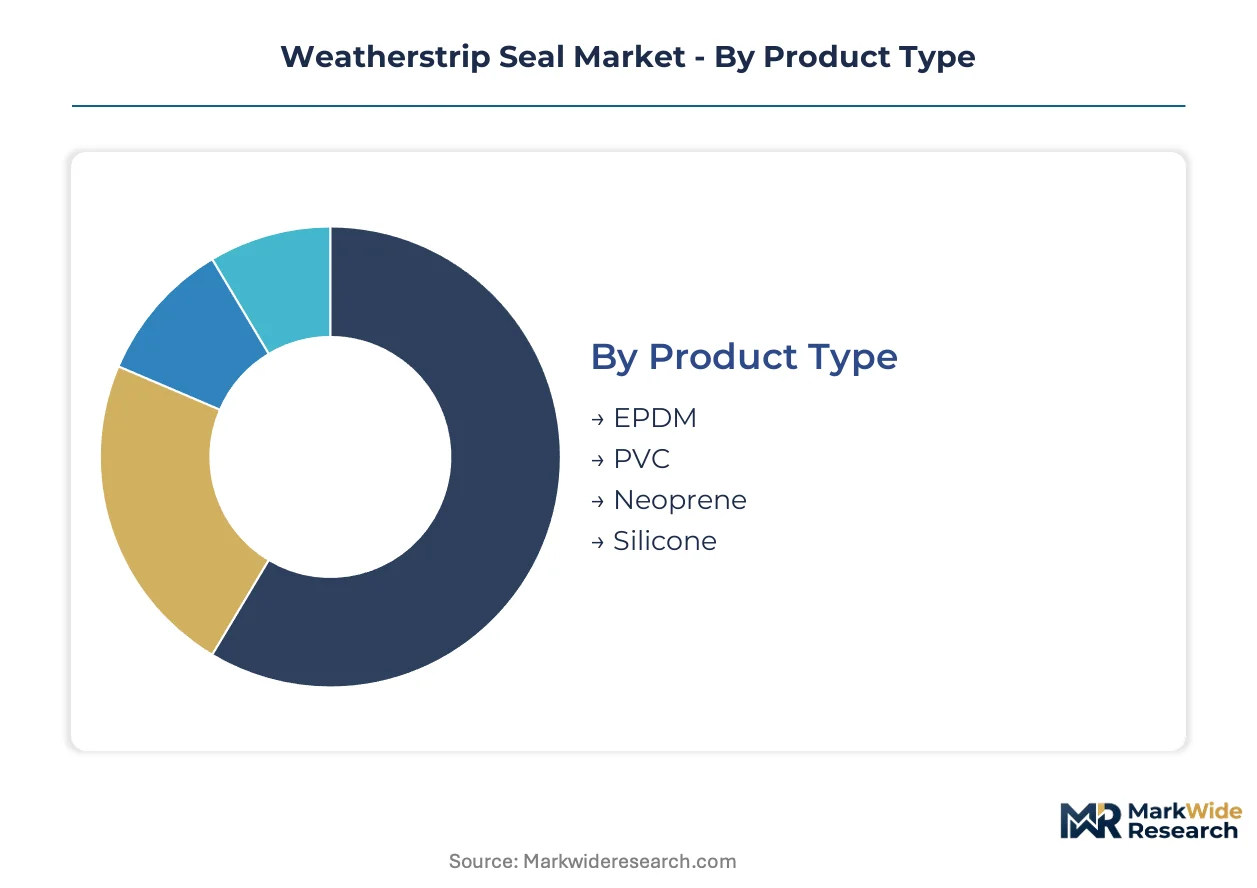
Weatherstrip seal procurement patterns diverge sharply across material chemistry, installation context, and buyer sophistication. Segmentation clarity enables suppliers to align compound development, inventory positioning, and technical service resources with distinct margin and qualification requirements.
Product Type:
Material chemistry determines temperature tolerance, compression set resistance, and regulatory compliance pathways across end-use environments.
- EPDM:Peroxide-cured terpolymer formulations deliver ozone resistance and thermal stability across underhood automotive applications. German and Japanese OEMs specify these grades for door primary seals and glass-run channels where service intervals must exceed 150,000 kilometers.
- Silicone:VMQ compounds maintain elasticity beyond 200°C in appliance oven doors and industrial heat-processing equipment. Premium positioning reflects raw material costs three to four times standard elastomer grades.
- PVC:Plasticized polyvinyl chloride dominates residential window retrofits in price-sensitive construction channels. EU REACH phthalate restrictions are forcing rapid migration to bio-based plasticizer alternatives.
- Neoprene:Chloroprene rubber serves marine and coastal construction where salt spray degradation threatens standard elastomers. Niche positioning limits volume scale.
EPDM holds installed capacity. Silicone is rotating up the share rankings.
Application:
End-use environment dictates performance specifications, validation protocols, and replacement cycle economics.
- Automotive:Modular door-sealing systems integrate dense carriers, sponge bulbs, and low-friction coatings into single-source assemblies. Tier 1 suppliers now assume design responsibility and warranty liability previously retained by vehicle assemblers.
- Construction:Perimeter sealing for commercial fenestration must achieve U-value thresholds under EU Green Deal building envelope mandates. French and Italian residential contractors are converting from PVC to thermoplastic elastomer systems.
- Appliances:Refrigerator door gaskets and dishwasher tub seals require FDA-compliant formulations for food contact surfaces. Replacement part demand concentrates through authorized service networks.
- Industrial Equipment:Dust and acoustic isolation for machinery enclosures favors dense EPDM profiles with metal carrier inserts. Specification authority rests with plant engineering departments rather than procurement.
Automotive commands volume concentration. Construction is expanding most quickly.
End User:
Buyer type determines technical qualification depth, contract structure, and price sensitivity.
- OEMs:Vehicle and appliance manufacturers impose 24-36 month validation cycles including accelerated aging and environmental cycling. Direct supply relationships require dedicated quality engineering staff and statistical process control documentation.
- Contractors:Commercial glazing and building envelope installers purchase cut-to-length profiles through regional distributors. Price transparency pressures compounder margins.
- Retail Customers:DIY homeowners select compression-fit foam tapes and adhesive-backed seals through home improvement retailers. Product differentiation relies on packaging claims rather than technical data sheets.
- Manufacturers:Industrial equipment builders source custom-extruded profiles with integrated fastening systems. Low order quantities relative to automotive favor specialized compounders with flexible production scheduling.
OEMs anchor technical development investment. Contractors are gaining procurement leverage through consolidation.
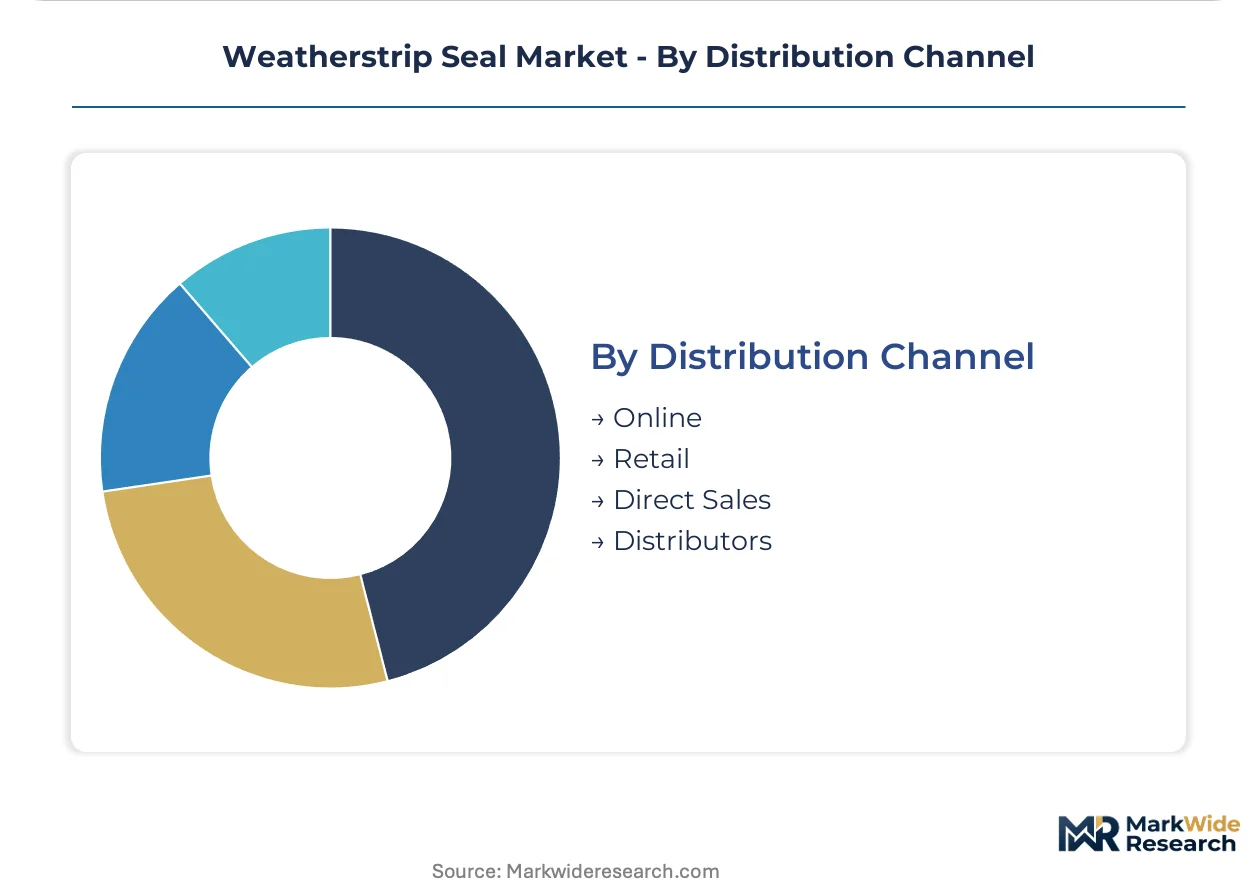
Distribution Channel:
Channel selection reflects order complexity, technical support requirements, and geographic coverage needs.
- Distributors:Regional industrial supply houses maintain cut-to-length inventory and local technical service for construction and MRO segments. Working capital intensity limits participant count.
- Direct Sales:Automotive and appliance OEMs negotiate multi-year supply agreements with compounders holding IATF 16949 certification. Account teams include application engineers resident at customer technical centers.
- Online:E-commerce platforms serve aftermarket replacement demand for standardized profiles. Product photography and dimensional accuracy replace traditional sales engineering.
- Retail:Home improvement chains stock consumer-grade weatherstripping in seasonal assortments. Private label penetration concentrates price competition.
Distributors maintain field coverage density. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion die manufacturing clusters in Osaka and Nagoya concentrate precision tooling capacity for complex co-extruded profiles. German and Japanese automakers drive specification intensity for EPDM-based sealing systems. Regulatory pressure on volatile organic compounds and building envelope performance is reshaping material sourcing patterns across multiple jurisdictions.
United States
Automotive assembly plants in Michigan, Ohio, and Tennessee generate concentrated OEM demand for modular door-sealing systems. The US EPA enforces emission controls on solvent-based flocking adhesives used in finishing operations. Detroit-area Tier 1 suppliers are retooling coating lines to maintain compliance with federal VOC thresholds.
Germany
Commercial vehicle fleet operators specify peroxide-cured EPDM grades for extended service intervals and total cost reduction. The EU Ecodesign framework mandates U-value thresholds for building envelope performance under the Green Deal. Stuttgart and Munich automotive clusters drive precision seal procurement for premium vehicle platforms.
Japan
Domestic automakers anchor demand through deep supply relationships with specialized rubber compounders. METI enforces energy-efficiency standards for residential and commercial building envelopes specifying seal performance ratings. Nagoya and Osaka toolmakers control precision extrusion die manufacturing with lead times extending to 16 weeks during capacity constraints.
China
Mass-market vehicle platforms are adopting thermoplastic vulcanizate injection molding for A-pillar and B-pillar seals. The country's national standards body is aligning commercial building codes with energy-efficiency rating systems. Yangtze River Delta manufacturing zones are expanding TPV compounding capacity to serve domestic OEMs.
India
The Bureau of Indian Standards energy-efficiency ratings for commercial envelopes are creating specification demand for EPDM-based window seals. Domestic fenestration manufacturers lack qualified local compound sources. Maharashtra and Gujarat industrial corridors are attracting technical service investment from multinational seal suppliers.
Weatherstrip Seal Market Competitive Landscape
Vertically integrated multinationals and specialized regional fabricators split the market into distinct capability tiers. Tier 1 automotive suppliers now assume design responsibility and warranty liability for integrated sealing modules, elevating technical qualification barriers. Three archetypes dominate: full-service system integrators with global manufacturing footprints, precision extrusion specialists serving Japanese OEMs, and diversified industrial rubber compounders with aerospace exposure. Consolidation pressure is driving strategic partnerships for die manufacturing access and capacity expansion in high-growth construction channels.
Among North American system integrators, Cooper Standard exemplifies the integrated manufacturing archetype with continental production scale. Toyoda Gosei occupies a position within the Japanese precision specialist tier, anchoring supply relationships with domestic automakers. Hutchinson represents the diversified industrial compounder model, extending rubber expertise across automotive and aerospace sealing applications.
| Leading Market Players |
|---|
| Cooper Standard |
| Toyoda Gosei |
| Hutchinson |
| Henniges |
| Nishikawa Rubber |
| SaarGummi |
| Kinugawa Rubber |
| Magna |
| Hwaseung |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility compresses compounder margins during crude oil cycles and determines both pricing tier spreads and supply chain shape across EPDM and TPE formulations. Tier 1 automotive suppliers absorb design responsibility while facing cost pass-through limitations from OEMs, forcing backward integration into captive compounding capacity to defend margin structures.
Pricing Analysis
EU REACH Article 33 dictates the pricing tier structure across phthalate-restricted PVC and bio-based plasticizer alternatives. Three-tier pricing structure across premium silicone, standard peroxide-cured EPDM, and economy PVC grades reflects certification burden and thermal performance thresholds. Pricing pressure stems from OEM modular platform consolidation transferring warranty liability downstream. Contractors in construction channels exhibit highest price sensitivity, while appliance OEMs accept premiums for FDA-compliant food-contact formulations.
Supply Chain Analysis
Export-control restrictions on precision extrusion die manufacturing concentrate among specialized toolmakers in Osaka and Nagoya, limiting technology transfer for complex co-extruded profiles. Raw material flows draw from ethylene and propylene monomer supply in Germany, Japan, and the United States, with EPDM polymer production anchored in steam cracker operations. Single-source vulnerability runs through Japanese die manufacturing clusters with 16-week lead time constraints during capacity crunches. Distribution runs through regional industrial supply houses maintaining cut-to-length inventory for construction and MRO segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive production cycles and building energy-code implementation timelines position this market for cyclical recovery as fleet replacement demand and commercial construction permitting accelerate through mid-decade.
For Market Incumbents: Entrench position through backward integration into captive EPDM compounding capacity in Germany and Japan to offset feedstock volatility. Invest in IATF 16949 certification maintenance as OEM validation timelines extend to 36 months, raising technical barriers against emerging competitors. Prioritize die manufacturing partnerships with Osaka and Nagoya toolmakers to secure capacity allocation during supply crunches. For New Entrants and Emerging Players: Establish a beachhead in Indian commercial fenestration where Bureau of Indian Standards energy-efficiency ratings create specification demand lacking qualified local compound sources. Target thermoplastic elastomer systems for French and Italian residential construction converting from PVC under EU Green Deal mandates. Pursue technical service partnerships with domestic fenestration manufacturers lacking formulation expertise. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision extrusion specialists with Japanese OEM relationships and aerospace diversification. Long-term viability hinges on multi-material bonding expertise and intumescent EPDM development for EV battery pack sealing. Watch IP67 ingress protection specification adoption across electric vehicle platforms as inflection indicator for thermal runaway containment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Compounding | Captive supply of peroxide-cured formulations insulates margins from naphtha-derived feedstock volatility cycles. |
| Die Manufacturing Partnership | Preferred allocation with Osaka and Nagoya toolmakers secures 16-week lead time capacity for complex co-extruded profiles. |
| Intumescent EPDM Development | Thermal runaway containment grades address IP67 battery pack sealing specifications from EV OEMs. |
| REACH-Compliant Plasticizer Migration | Bio-based alternatives in TPE compounds capture 15-20% price premiums in EU specification-driven markets. |
| TPV Injection Molding Adoption | In-line color matching and eliminated post-cure requirements collapse floor space needs by 40% in greenfield plants. |
Research Methodology
Operator-level perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and commercial glazing contractors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, vehicle production databases, SEC 10-K filings from rubber compounders, and building code regulatory filings. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across material chemistry and application dimensions.
Scenario-bracketing framed analytical outputs across the projection horizon without discrete year anchoring. Segmentation modeling captured material chemistry tiers, automotive versus construction application splits, OEM versus aftermarket channel dynamics, and regional production cluster variations. CAGRs derived from production volume trajectories, content-per-vehicle assumptions, and building envelope efficiency mandate implementation curves. Forecast inputs incorporated fleet replacement cycles, EU Ecodesign compliance deadlines, and EV platform sealing specification adoption rates.
Sensitivities concentrate around crude oil price volatility affecting EPDM monomer costs, Japanese die manufacturing capacity constraints, and REACH regulatory expansion timelines. Forecasts reflect assumptions on OEM modular platform consolidation pace and construction energy-code harmonization across jurisdictions. Material shifts in EV battery pack sealing specifications or chlorinated paraffin restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Metal Heat Treatment Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market