
 Contact Steering Torque Sensor Market | 2026-2036
Contact Steering Torque Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Steering Torque Sensor Market Insights
Asset-light manufacturing partnerships and contract electronics manufacturing (CEM) leasing are rewriting competitive entry barriers for sensor producers. Robert Bosch GmbH leverages captive semiconductor sourcing to sustain margin control across torque sensor modules. Denso Corporation anchors its position through integrated mechatronics production in steering system clusters. TE Connectivity competes via high-reliability connector-sensor bundling for OEM wire-harness reduction.
A contact steering torque sensor measures torsional mechanical load through physical signal transduction, typically employing strain-gauge or resistive element architectures bonded to a torsion bar with output sensitivity calibrated to millivolt-per-volt standards for closed-loop steering feedback. The device converts driver-applied rotational force into electrical signals that power steering control units interpret for assist-motor command generation. Hall Effect Technology dominates volume production due to magnetic immunity and non-contact durability advantages in underhood thermal cycling. Active Sensors command premium positioning where real-time self-diagnostic capability satisfies functional safety architectures. Resistive Technology occupies mature cost-optimized segments in light-commercial steering columns.
NHTSA Federal Motor Vehicle Safety Standards and ECE R79 govern steering system performance thresholds that mandate torque sensor redundancy and diagnostic coverage ratios. Japan's METI vehicle component quality frameworks and JIS standards shape export-competitive sensor calibration protocols for Japanese automotive manufacturers. Stakeholders must monitor functional safety standard evolution from ISO 26262 and emerging cybersecurity annexes that will redefine hardware validation burdens for steering-domain sensors.
Market Dynamics
Electric power steering architectures are displacing hydraulic systems across vehicle segments, concentrating torque sensor demand into high-volume mechatronic platforms where functional safety compliance and thermal resilience determine supplier selection.
Growth Catalysts
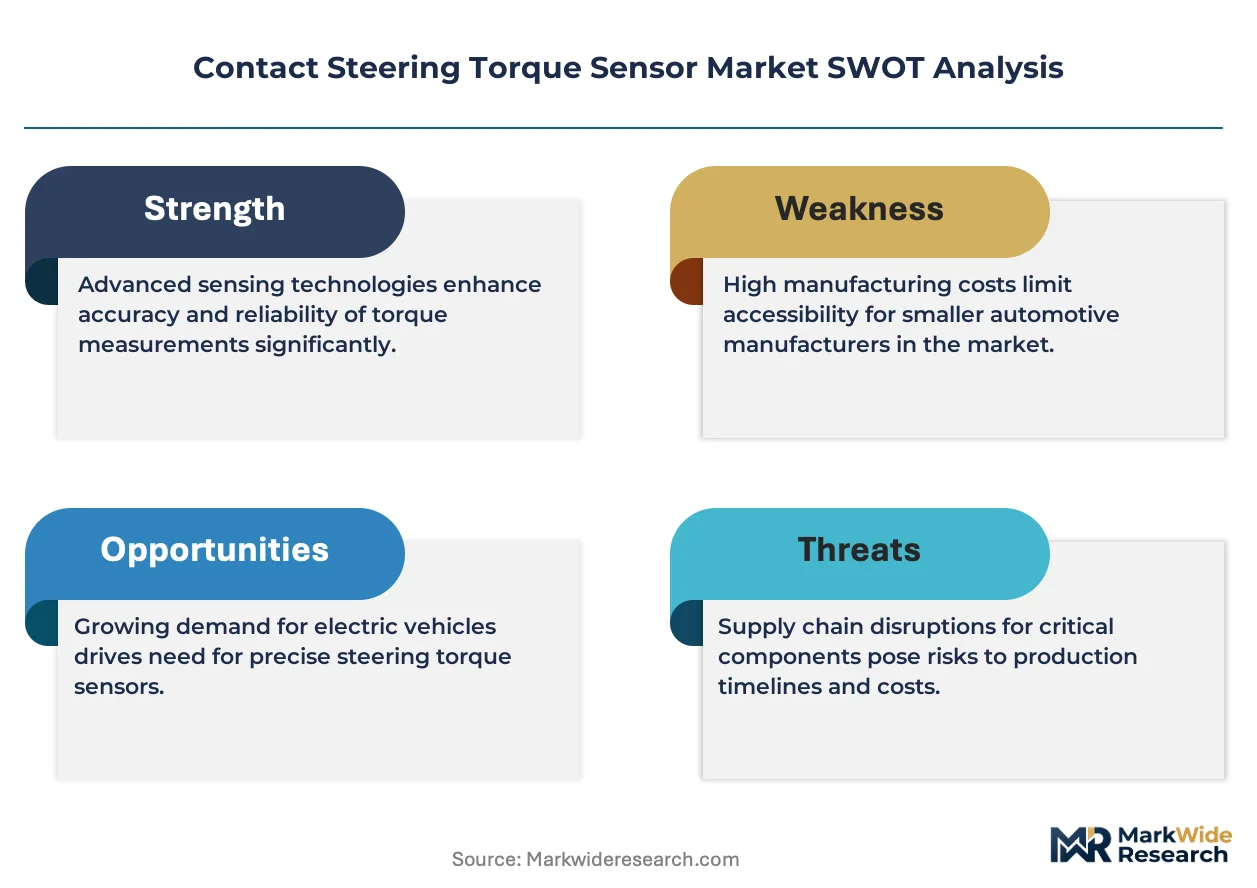
- EU Vehicle Safety Mandates:ECE R79 steering equipment regulations mandate torque sensor redundancy and diagnostic coverage ratios, compelling OEM procurement of fail-safe sensor modules.
- Hall Effect Technology:Magnetic immunity and non-contact durability advantages in underhood thermal cycling accelerate adoption for closed-loop steering feedback systems.
- German Automotive Clusters:Tier-one suppliers co-locating with major vehicle assembly operations in Stuttgart and Munich concentrate demand for precision-calibrated torque sensing.
Market Restraints
- Semiconductor Input Volatility:Captive silicon sourcing requirements for signal conditioning ASICs expose sensor producers to foundry capacity constraints and wafer pricing swings.
- Supply Concentration Risk:Strain-gauge substrate manufacturing concentrates among Japanese specialty metals suppliers, creating single-source vulnerability for resistive element architectures.
- Functional Safety Certification Burden:ISO 26262 ASIL-D validation timelines extend 18-24 months, freezing design iterations and compressing product refresh cycles.
Strategic Opportunities
- ADAS Integration White Space:Lane-keeping assist and automated parking systems require steer-by-wire torque feedback, opening premium sensor positioning in Level 2+ vehicle architectures.
- India Automotive Manufacturing:PLI scheme incentives for electric vehicle component localization create entry paths for sensor producers establishing contract electronics partnerships.
- Cybersecurity Annex Convergence:Emerging ISO 26262 cybersecurity extensions will redefine hardware validation protocols, rewarding early-compliant suppliers with OEM preferred vendor status.
Industry Challenges
- Functional Safety Talent Scarcity:Embedded systems engineers with ASIL-D verification experience command premium compensation, constraining R&D team scaling.
- Legacy Steering Column Integration:Retrofitting torque sensors into existing mechanical architectures without column redesign creates packaging conflicts and calibration drift.
- Patent Licensing Complexity:Hall Effect signal processing IP portfolios held by incumbent automotive electronics suppliers impose royalty burdens on new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Steering Torque Sensor Market |
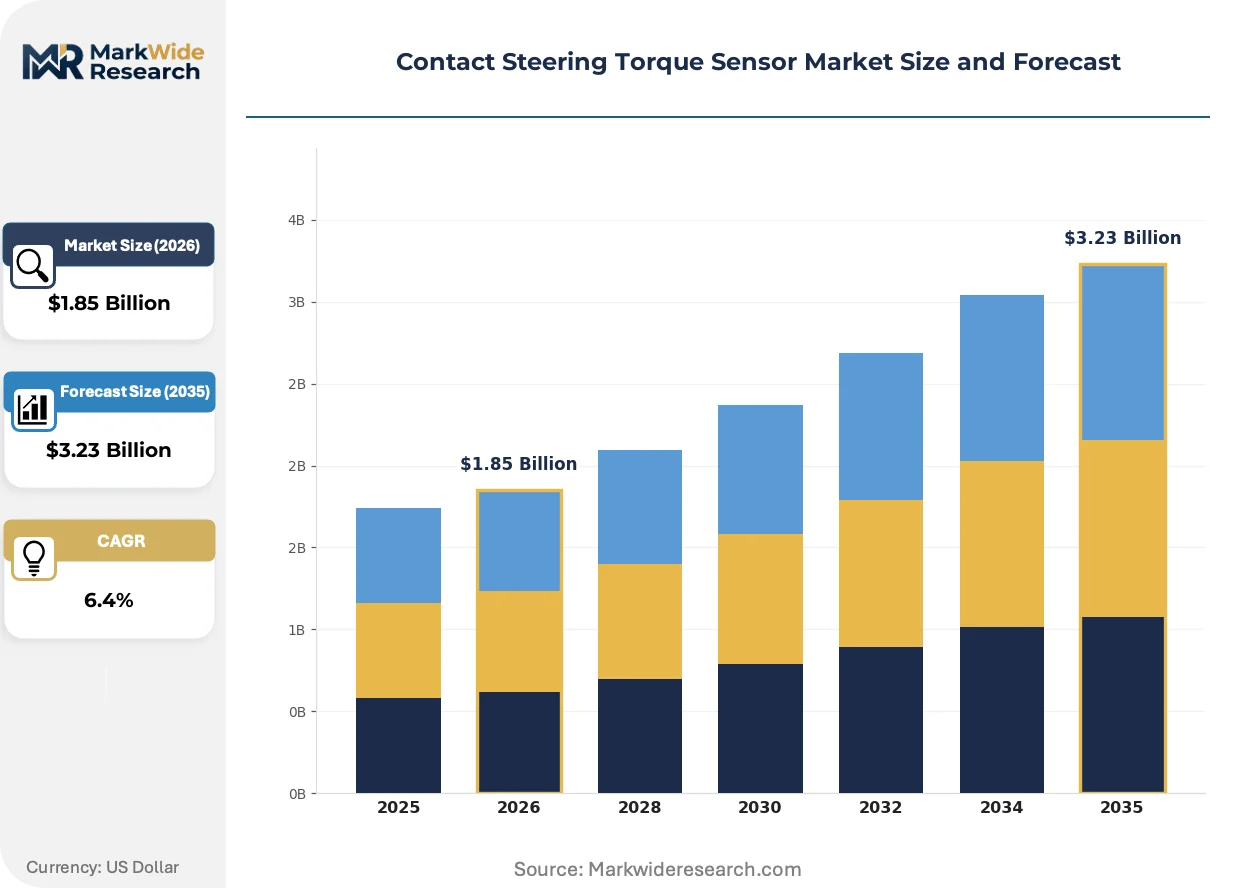
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Sensors, Passive Sensors, Digital Sensors, Analog Sensors Technology: Optical Technology, Hall Effect Technology, Resistive Technology, Capacitive Technology End User: Automotive Manufacturers, Aerospace, Industrial Equipment, Research Institutions Application: Electronic Stability Control, Advanced Driver Assistance Systems, Autonomous Vehicles, Steering Assistance |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, TE Connectivity, Honeywell International, Valeo, Kistler Holding, Crane Electronics, Sensor Technology, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Steering Torque Sensor Market Trends and Innovations
Sensor architectures are converging with domain controller electronics, compressing module counts while elevating real-time diagnostic requirements. Material science advances in magnetic sensing elements and substrate bonding are reshaping durability benchmarks.
Non-contact magnetic torque sensing is migrating from premium electric vehicle platforms to mass-market compact car segments. Tier-one steering system integrators in Germany and Japan are specifying dual-Hall redundant configurations for 2027 model year platforms. This technology migration from resistive strain-gauge architectures is compressing price premiums and forcing incumbent suppliers to reposition on calibration service bundles.
Europe's CSRD sustainability disclosure requirements are extending supply chain due diligence obligations to automotive component suppliers. Sensor producers must now document carbon intensity across bonded strain-gauge substrate production and magnetic element rare earth sourcing. German OEM procurement teams are prioritizing suppliers with validated Scope 3 emissions tracking, shifting competitive weight toward vertically integrated material processors.
Fleet operators and vehicle-as-a-service platforms are unbundling steering system maintenance from traditional dealership service contracts. Independent diagnostic tool providers are capturing torque sensor calibration revenue streams previously held by authorized repair networks. This channel fragmentation is most visible in North American commercial vehicle segments where telematics-enabled predictive maintenance compresses service intervals.
Contact Steering Torque Sensor Market Segmentation
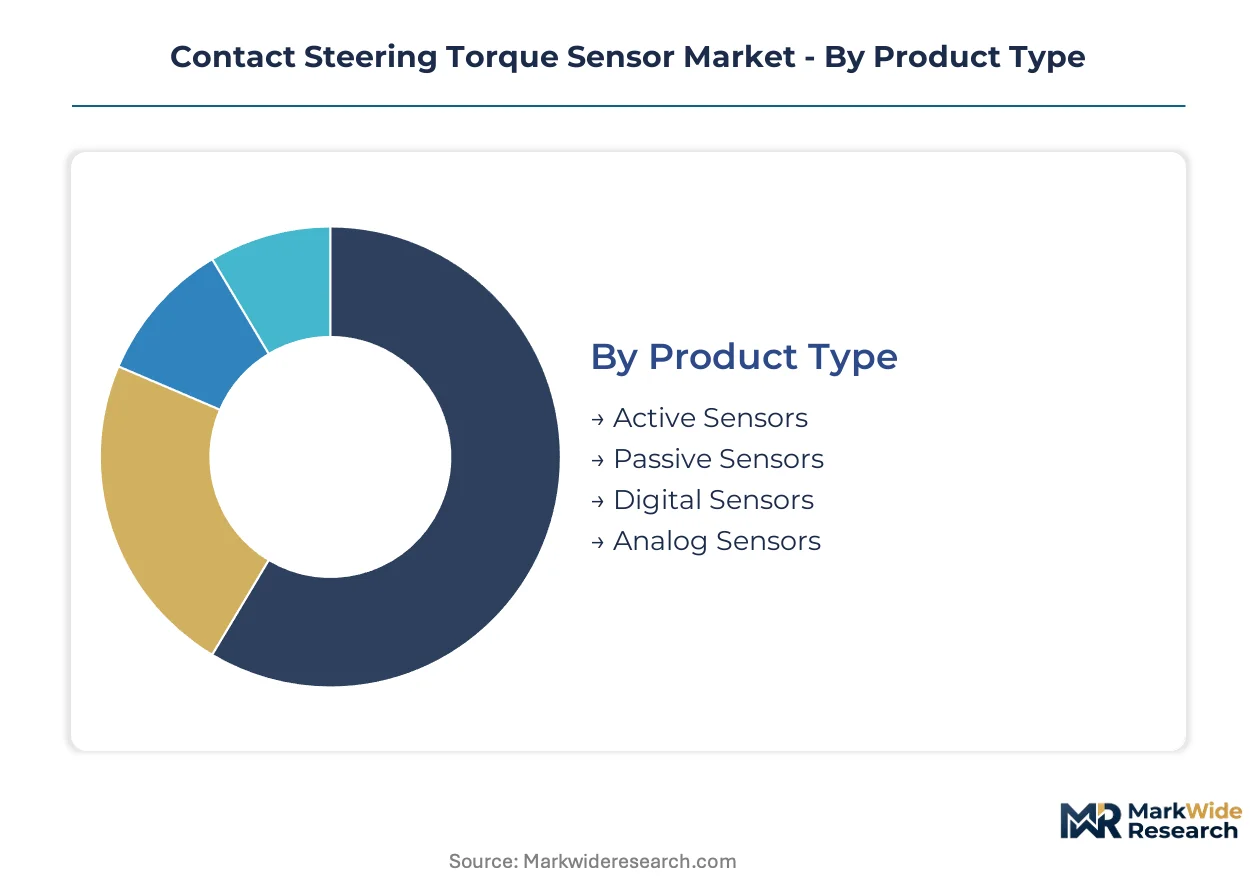
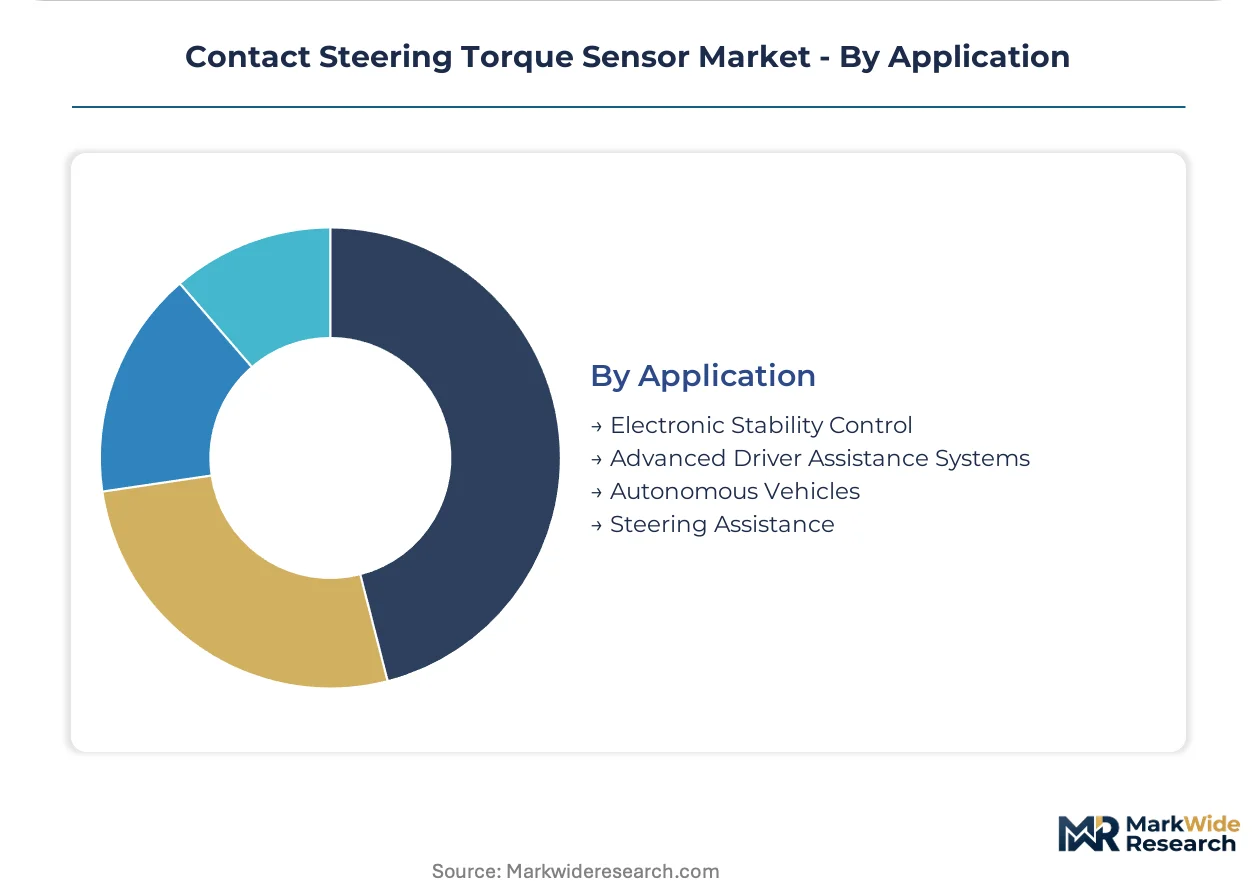
Torque sensor architectures diverge sharply across steering system tiers, with functional safety requirements and signal processing complexity determining procurement patterns. OEMs segment procurement by electrification platform maturity, creating distinct technology adoption curves across vehicle classes.
Product Type:
Active and passive architectures span closed-loop feedback requirements from basic power steering to steer-by-wire redundancy.
- Active Sensors:These modules incorporate built-in signal conditioning and real-time self-diagnostic capability for ASIL-D functional safety compliance. German OEMs specify active sensors for electric vehicle platforms where redundant torque feedback prevents single-point steering failures.
- Passive Sensors:Raw millivolt output devices require external amplification and calibration, occupying cost-optimized hydraulic-to-electric retrofit programs. Japanese tier-one suppliers bundle passive sensors with integrated ECUs to preserve margin in compact vehicle steering columns.
- Digital Sensors:CAN-bus output formats reduce wire harness complexity in domain-controller architectures. These devices streamline calibration protocols for fleet operators deploying predictive maintenance systems.
- Analog Sensors:Voltage-output variants persist in legacy platform extensions where controller hardware refresh cycles lag behind sensor technology roadmaps. Industrial equipment manufacturers favor analog interfaces for compatibility with established PLC ecosystems.
Established volume favors passive sensors; emerging adoption favors active sensors.
Technology:
Signal transduction methods trade magnetic immunity against substrate cost and calibration stability.
- Hall Effect Technology:Non-contact magnetic sensing eliminates mechanical wear in thermal cycling environments. Stuttgart-based steering system integrators specify dual-Hall redundant configurations for premium electric vehicle platforms launching through 2027.
- Resistive Technology:Strain-gauge architectures bonded to torsion bars deliver cost-optimized torque measurement for light-commercial applications. Japanese specialty metals suppliers control substrate manufacturing, creating supply concentration vulnerability for this segment.
- Optical Technology:Photonic encoders provide interference-free signal transduction for research-grade steering validation rigs. These devices command premium positioning where electromagnetic immunity exceeds Hall Effect performance.
- Capacitive Technology:Electric field sensing enables compact packaging in steer-by-wire column modules. Aerospace applications drive qualification investment for capacitive architectures operating across altitude pressure differentials.
Hall Effect dominates production scale; optical sensing gains share fastest in validation-intensive segments.
End User:
Customer procurement patterns split between automotive volume contracts and specialized industrial qualification cycles.
- Automotive Manufacturers:Tier-one steering system suppliers in Germany, Japan, and the United States concentrate demand for precision-calibrated modules. ECE R79 compliance mandates torque sensor redundancy in European vehicle safety certifications.
- Aerospace:Flight control surface actuation requires MIL-STD-810 environmental qualification beyond automotive thermal specifications. These applications sustain premium pricing for extended temperature-range variants.
- Industrial Equipment:Forklift and agricultural steering systems adopt automotive-derivative sensors with simplified diagnostic coverage. METI quality frameworks shape calibration protocols for Japanese industrial machinery exports.
- Research Institutions:Vehicle dynamics laboratories procure high-bandwidth torque sensors for chassis development programs. Academic procurement concentrates in Stuttgart, Munich, and Detroit automotive engineering clusters.
Automotive volume anchors production economics; aerospace qualification sustains margin premiums.
Application:
Function-specific torque feedback requirements stratify across driver-assist automation levels.
- Advanced Driver Assistance Systems:Lane-keeping assist and automated parking demand real-time torque overlay capability with sub-10-millisecond latency. These functions command redundant sensor configurations in Level 2+ architectures.
- Steering Assistance:Conventional electric power steering represents the volume foundation, with Hall Effect modules displacing hydraulic pressure sensors across vehicle segments. NHTSA Federal Motor Vehicle Safety Standards govern performance thresholds for this application.
- Electronic Stability Control:Yaw-rate coordination requires torque signal integration with brake and throttle domains. ESC module suppliers bundle steering angle and torque sensing to reduce harness complexity.
- Autonomous Vehicles:Steer-by-wire architectures eliminate mechanical steering columns, elevating torque sensor reliability to safety-critical status. These platforms specify triple-modular redundancy with diagnostic coverage ratios exceeding standard EPS requirements.
Steering assistance commands current volume; autonomous vehicle architectures represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government vehicle safety mandates and electric power steering procurement incentives are concentrating torque sensor demand in automotive manufacturing clusters across Germany, Japan, the United States, India, and China.
Germany
Stuttgart and Munich host tier-one steering system integrators procuring Hall Effect modules for premium electric vehicle platforms launching through 2027. ECE R79 steering equipment regulations mandate torque sensor redundancy and diagnostic coverage ratios for European vehicle safety certifications. Baden-Württemberg's automotive engineering ecosystem concentrates precision calibration capabilities for OEM supply contracts.
Japan
METI vehicle component quality frameworks shape export-competitive sensor calibration protocols for domestic automotive manufacturers. JIS standards govern signal conditioning specifications for resistive element architectures bonded to torsion bars. Nagoya's Chubu region anchors integrated mechatronics production clusters serving global steering system supply chains.
United States
NHTSA Federal Motor Vehicle Safety Standards govern steering system performance thresholds that mandate torque sensor redundancy for closed-loop feedback systems. Detroit's automotive engineering corridor concentrates research institution procurement of high-bandwidth torque sensors for chassis development programs. Michigan-based tier-one suppliers co-locate with major vehicle assembly operations to reduce logistics costs.
India
PLI scheme incentives for electric vehicle component localization create entry paths for sensor producers establishing contract electronics partnerships. BIS certification requirements shape import substitution strategies for automotive electronics manufacturers. Tamil Nadu and Gujarat automotive manufacturing corridors attract foreign sensor producers seeking duty-advantaged production bases for export markets.
China
MIIT industrial policy directives prioritize domestic sourcing of automotive safety-critical sensors including torque measurement modules. GB standards govern electromagnetic compatibility testing for Hall Effect signal processing circuits. Yangtze River Delta manufacturing clusters concentrate contract electronics capacity serving both domestic OEMs and export-oriented tier-one suppliers.
Contact Steering Torque Sensor Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated automotive electronics conglomerates and specialized sensor fabricators with captive semiconductor sourcing capabilities. Tier-one steering system integrators in Germany and Japan command preferred supplier relationships through co-location with OEM assembly clusters. Three strategic archetypes dominate: integrated mechatronics producers with in-house magnetic sensing element manufacturing, connector-sensor bundling specialists targeting wire-harness reduction, and contract electronics manufacturers serving cost-optimized retrofit programs. Dominant competitive moves include strategic partnerships for foundry capacity reservation and portfolio diversification into steer-by-wire redundant architectures.
Within the integrated tier, Robert Bosch GmbH and Denso Corporation exemplify archetypes combining captive semiconductor sourcing with steering system cluster proximity. TE Connectivity occupies a position representing connector-sensor bundling strategies for OEM harness complexity reduction. These three anchors illustrate how geographic co-location with automotive manufacturing centers and backward integration into signal conditioning ASIC production differentiate competitive positioning in procurement decisions governed by functional safety compliance timelines.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| TE Connectivity |
| Honeywell International |
| Valeo |
| Kistler Holding |
| Crane Electronics |
| Sensor Technology |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's precision manufacturing clusters concentrate Hall Effect magnetic sensing element production, concentrating pricing power among vertically integrated suppliers with captive semiconductor sourcing capabilities. OEM procurement teams in Germany and Japan face asymmetric negotiating positions when strain-gauge substrate supply concentrates among Japanese specialty metals producers.
Pricing Analysis
Certification level (ISO 26262 ASIL-D versus ASIL-B) creates the primary spread between premium active sensor modules and cost-optimized passive architectures. Three-tier pricing structure across premium, standard, and economy levels reflects functional safety compliance depth, with redundant dual-Hall configurations commanding substantial premiums over single-element resistive designs. Cost compression in passive sensor tiers is intensifying because contract electronics manufacturers in India and China are capturing volume from legacy hydraulic-to-electric retrofit programs. Fleet operators deploying predictive maintenance systems exhibit highest price sensitivity, while German premium OEMs prioritize diagnostic coverage ratios over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced magnetic sensing IP and signal conditioning ASICs limit technology transfer to emerging manufacturing hubs. Production gravity centers on Germany, Japan, and China, with Taiwan and South Korea supplying critical foundry capacity for sensor-integrated semiconductors. Raw material dependencies include rare earth elements for Hall Effect magnets, specialty steel alloys for torsion bar substrates, and high-purity silicon for ASIC fabrication. Single-source vulnerability concentrates in Japanese strain-gauge substrate manufacturing. Distribution runs through tier-one steering system integrators co-located with OEM assembly clusters rather than direct component supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steer-by-wire architectures are disrupting established electric power steering supply relationships, with functional safety compliance timelines and cybersecurity validation requirements creating asymmetric advantages for prepared suppliers.
For Market Incumbents: Entrench position through backward integration into magnetic sensing element manufacturing and foundry capacity reservation agreements with Taiwanese semiconductor producers. Patent licensing portfolios for Hall Effect signal processing IP provide defensive moats against emerging entrants from India's PLI-incentivized manufacturing corridors. Prioritize ASIL-D certification maintenance to preserve preferred supplier status with Stuttgart-based tier-one integrators. For New Entrants and Emerging Players: Build out contract electronics partnerships in Tamil Nadu and Gujarat automotive corridors to capture PLI scheme benefits for electric vehicle component localization. India's import substitution strategies for automotive electronics present the most penetrable geography for cost-optimized passive sensor production. Target aftermarket diagnostic tool providers as channel partners to bypass entrenched OEM supply relationships. For Investors and Strategic Acquirers: Long-term, this sits as a functional safety consolidation play because ISO 26262 cybersecurity annex convergence will elevate hardware validation burdens beyond mid-tier engineering capabilities. Acquisition targets should display captive semiconductor sourcing and existing ASIL-D certification pipelines. The signal to monitor is NHTSA rulemaking on steer-by-wire redundancy requirements, which would accelerate tier-one supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Sensing Elements | Captive rare earth sourcing insulates margin from supply concentration risk in Japanese substrate producers. |
| ASIL-D Certification Investment | Preferred vendor status with German OEMs depends on validated functional safety architectures meeting ECE R79 mandates. |
| Contract Electronics Partnership in India | PLI scheme incentives reduce landed cost for export-oriented production serving European and North American OEMs. |
| Cybersecurity Annex Pre-Compliance | Early alignment with emerging ISO 26262 extensions secures positioning ahead of hardware validation requirement shifts. |
| Dual-Hall Redundant Configuration Development | 2027 model year platforms in Stuttgart and Munich specify redundant torque feedback for premium electric vehicle architectures. |
Research Methodology
Desk research of regulatory filings (NHTSA FMVSS documentation, ECE R79 implementation guidelines, METI component quality frameworks), patent databases, and vehicle production statistics preceded structured interviews with tier-one steering system procurement officers, OEM platform engineers, aftermarket diagnostic tool providers, and semiconductor foundry account managers. Primary fieldwork validated strain-gauge substrate supply concentration and Hall Effect magnet sourcing patterns. Secondary sources included customs trade data for automotive electronics, IHS Markit vehicle registration databases, and SEC filings from listed automotive suppliers. Bottom-up sensor unit demand estimates triangulated against top-down OEM platform content projections.
Assumptions held electric power steering penetration rates and ADAS adoption curves fixed at observed trajectories while varying semiconductor input cost volatility and functional safety certification timeline scenarios. The analytical framework modeled segmentation across sensor architecture (active/passive/digital/analog), signal transduction technology (Hall Effect/resistive/optical/capacitive), and vehicle class (premium electric, mass-market electric, light commercial, legacy internal combustion). CAGRs derived from regression analysis of historical procurement patterns against platform launch schedules. Industry-specific inputs included ECE R79 compliance deadline impacts and PLI scheme incentive phase-out assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese contract electronics manufacturers or accelerated steer-by-wire deployment by German OEMs would shift outcomes. Material shifts in rare earth export restrictions, foundry allocation priorities, or NHTSA cybersecurity rulemaking for steering-domain sensors would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Global Light Sensors Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Inertial Sensors Market