
 NB-IoT Smart Meter Market | 2026-2036
NB-IoT Smart Meter Market Size, Share, and Industry Trends Forecast 2026-2036
NB-IoT Smart Meter Market Insights
LPWA-grade certification tiers is bifurcating the competitive landscape between utility-grade precision vendors and cost-optimized connectivity suppliers. Siemens AG leverages its industrial automation heritage to dominate European utility tenders with integrated grid analytics. Huawei Technologies Co., Ltd. anchors its position through captive semiconductor production and aggressive pricing in emerging markets. Kamstrup A/S specializes in ultrasonic metering platforms that differentiate on measurement accuracy for district heating applications.
Narrowband Internet of Things smart meters deploy cellular modules operating in licensed sub-GHz spectrum bands with 20 dBm power class and 200 kHz channel bandwidth to enable decade-long battery life for remote telemetry. These devices serve utilities by automating consumption data collection, leak detection, and demand-response signaling across distributed infrastructure. Electric meter deployments lead volume due to regulatory mandates for interval billing, while multi-utility meter architectures represent the fastest-growing configuration as municipalities consolidate vendor relationships. Cellular technology segments capture premium margins where operators require guaranteed quality-of-service, whereas hybrid connectivity occupies the mid-market by blending NB-IoT fallback with local mesh protocols.
Europe's ETSI standards for M-Bus wireless interoperability and the EU Green Deal metering directives shape product certification requirements for cross-border deployment. China's MIIT enforces GB/T compatible radio specifications and dual carbon tracking mandates that accelerate replacement cycles. The US FCC Part 15 and Part 22 frameworks govern spectrum access and device authorization, with state-level public utility commissions layering additional data privacy obligations. Stakeholders must monitor spectrum reallocation proceedings and cybersecurity certification timelines to secure market access before tender windows close.
Market Dynamics
Utility operators are consolidating vendor relationships around multi-utility meter architectures that combine water, gas, and electric telemetry within single NB-IoT endpoints, compressing procurement cycles and raising switching costs for specialized single-utility suppliers.
Growth Catalysts
- China's MIIT spectrum allocation:Licensed sub-GHz bands in Shenzhen and Shanghai enable dense urban rollouts with guaranteed quality-of-service for interval billing mandates.
- EU Green Deal metering directives:Cross-border interoperability requirements under ETSI M-Bus wireless standards accelerate replacement cycles across municipal utilities.
- Ultrasonic measurement platforms:District heating networks deploy high-accuracy thermal metering that leverages NB-IoT backhaul for real-time leak detection.
Market Restraints
- Licensed spectrum access costs:Cellular module certification under FCC Part 22 and equivalent national frameworks imposes recurring compliance burdens on mid-tier meter manufacturers.
- Semiconductor supply concentration:Captive production of NB-IoT chipsets by vertically integrated East Asian suppliers creates allocation risk for Western meter vendors.
- Battery chemistry limitations:Decade-long service life targets strain lithium thionyl chloride cell capacity in high-transmission-frequency deployments.
Strategic Opportunities
- India's smart city missions:Municipal water utilities in Bangalore and Hyderabad pilot NB-IoT pressure monitoring with CEA technical standards alignment.
- Hybrid connectivity architectures:Mesh protocol fallback integration with cellular backhaul opens mid-market segments between premium cellular and economy unlicensed radio.
- Dual carbon tracking mandates:China's MEE enforcement of consumption visibility requirements creates replacement demand for legacy AMR endpoints.
Industry Challenges
- RF engineering talent scarcity:Sub-GHz antenna design for metal meter enclosures requires specialized expertise concentrated among legacy cellular module suppliers.
- Multi-protocol firmware complexity:Simultaneous support for DLMS/COSEM, M-Bus, and proprietary utility SCADA interfaces extends certification timelines.
- Legacy AMI integration:Backward compatibility with existing head-end systems constrains feature rollout for next-generation demand-response signaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NB-IoT Smart Meter Market |
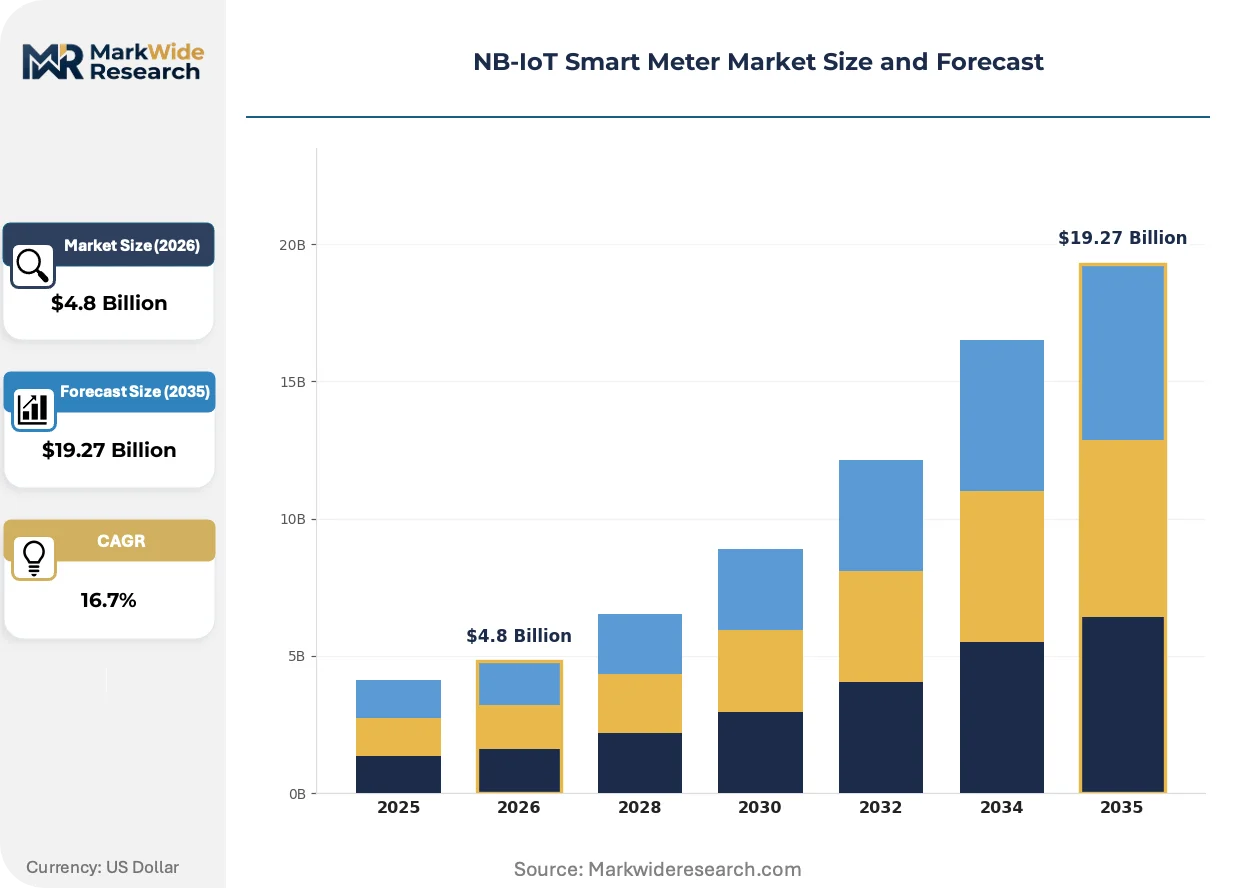
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Meter, Water Meter, Gas Meter, Multi-Utility Meter Technology: Cellular, Wireless, Fixed Line, Hybrid End User: Utilities, Industrial, Residential, Commercial Installation Type: Indoor, Outdoor, Wall-Mounted, Portable |
| Companies Covered | Siemens AG, Landis+Gyr Group AG, Huawei Technologies Co., Ltd., Kamstrup A/S, Itron Inc., Sagemcom, ZTE Corporation, Ericsson AB, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NB-IoT Smart Meter Market Trends and Innovations
NB-IoT module design is converging with system-in-package integration that collapses RF front-end, baseband, and power management into single-die solutions, reshaping cost structures and supplier power dynamics.
Multi-protocol system-on-chip architectures are miniaturizing RF transceiver footprints while maintaining 20 dBm output power class compliance. European meter OEMs in Denmark and Germany adopt these integrated modules for compact ultrasonic form factors. Component consolidation is compressing bill-of-materials differentiation between utility-grade and commercial-grade suppliers.
The EU Green Deal's CSRD disclosure requirements now extend to Scope 3 emissions from smart meter supply chains. Component vendors face enhanced traceability obligations for conflict minerals and carbon-intensive semiconductor fabrication. Electric meter segments with the largest deployment volumes are restructuring procurement specifications to mandate supplier ESG documentation.
Municipal utilities are unbundling hardware acquisition from data platform subscriptions, shifting from capital expenditure models toward meter-as-a-service arrangements. Water distribution operators in the Netherlands and Spain now specify outcome-based contracts linking vendor payments to leak reduction metrics. This procurement evolution is most visible where public-sector budget constraints intersect with aging pipe infrastructure replacement programs.
NB-IoT Smart Meter Market Segmentation
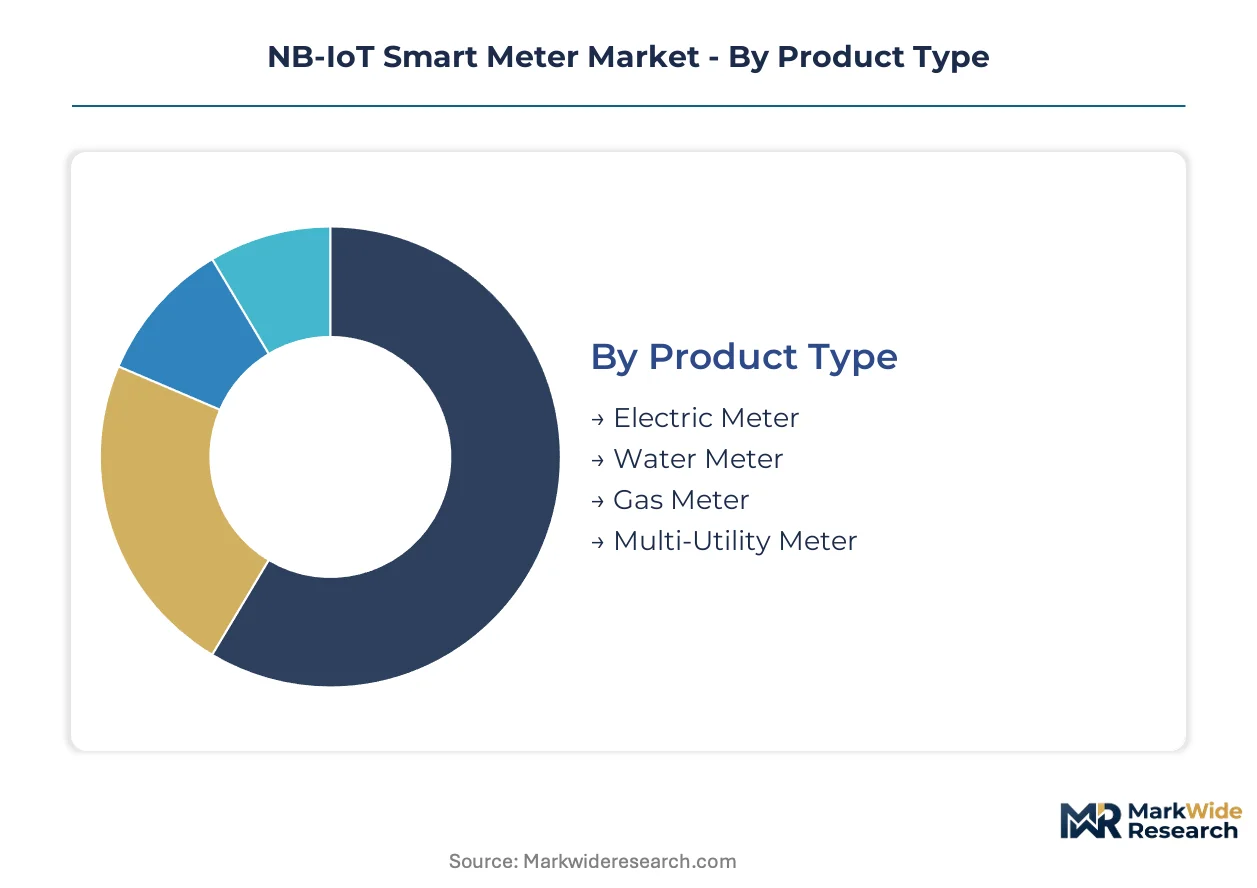
Segmentation in the NB-IoT smart meter market reveals how regulatory mandates and infrastructure economics concentrate demand across utility types and connectivity architectures. Procurement specifications from Shenzhen to Copenhagen diverge sharply on certification tiers, transmission protocols, and meter form factors.
Product Type:
ETSI M-Bus wireless interoperability standards and China's GB/T radio specifications create divergent certification burdens across electric, thermal, and fluid metering categories.
- Electric Meter:Interval billing mandates from EU Green Deal directives and China's dual carbon tracking enforcement drive replacement cycles for legacy electromechanical endpoints. Shenzhen's State Grid tenders specify DLMS/COSEM protocol stacks with 15-minute data granularity. Electric meter deployments handle the majority of throughput; multi-utility meter architectures are gaining share fastest.
- Water Meter:Ultrasonic measurement platforms with NB-IoT backhaul serve leak detection requirements in Dutch and Spanish municipal networks. Aging pipe infrastructure replacement programs in Hyderabad and Bangalore accelerate pilot deployments under CEA technical standards.
- Gas Meter:Safety-critical diaphragm and turbine designs integrate pressure monitoring for distribution network integrity. Metal enclosure RF engineering constraints concentrate procurement among vendors with captive antenna design expertise.
- Multi-Utility Meter:Consolidated endpoints combining water, gas, and electric telemetry raise switching costs for specialized single-utility suppliers. Municipal procurement in Copenhagen and Amsterdam favors unified vendor relationships.
Electric meters dominate deployment volumes where regulatory mandates enforce interval billing; multi-utility configurations expand most quickly as municipalities consolidate procurement.
Technology:
Module cost structures bifurcate between licensed spectrum premiums and unlicensed radio economy tiers, with hybrid architectures occupying the mid-market.
- Cellular:Licensed sub-GHz operation under FCC Part 22 and equivalent national frameworks guarantees quality-of-service for demand-response signaling. Huawei's captive semiconductor production anchors pricing in emerging markets.
- Wireless:Mesh protocol deployments bypass recurring cellular subscription costs but sacrifice guaranteed latency for leak detection applications. European district heating networks in Denmark favor this architecture for localized control loops.
- Fixed Line:Power-line communication persists in legacy AMI integrations where backward compatibility constrains feature rollout. State-level public utility commissions in California and Texas layer additional data privacy obligations on wired deployments.
- Hybrid:NB-IoT fallback with local mesh protocol blending captures mid-market segments between premium cellular and economy unlicensed radio. Dutch water operators specify outcome-based contracts linking vendor payments to leak reduction metrics.
Cellular modules command premium margins where guaranteed latency matters; hybrid configurations climb fastest as procurement shifts toward meter-as-a-service arrangements.
End User:
Customer type determines transmission frequency requirements and battery chemistry specifications, with utilities imposing the most stringent decade-long service life targets.
- Utilities:Municipal water, gas, and electric distribution operators specify LPWA-grade certification tiers with integrated grid analytics. China's MIIT spectrum allocation enables dense urban rollouts with guaranteed quality-of-service.
- Industrial:Manufacturing facilities deploy high-accuracy thermal metering for process optimization with real-time SCADA integration. District heating networks in Germany prioritize ultrasonic measurement precision.
- Residential:Single-family endpoints balance cost optimization with interval billing compliance. Battery chemistry limitations strain lithium thionyl chloride capacity in high-transmission-frequency deployments.
- Commercial:Multi-tenant buildings require sub-metering granularity for tenant billing allocation. Spain's municipal utilities unbundle hardware acquisition from data platform subscriptions.
Utility procurement concentrates the largest deployment volumes; commercial sub-metering shows steepest expansion trajectory as building energy management systems proliferate.
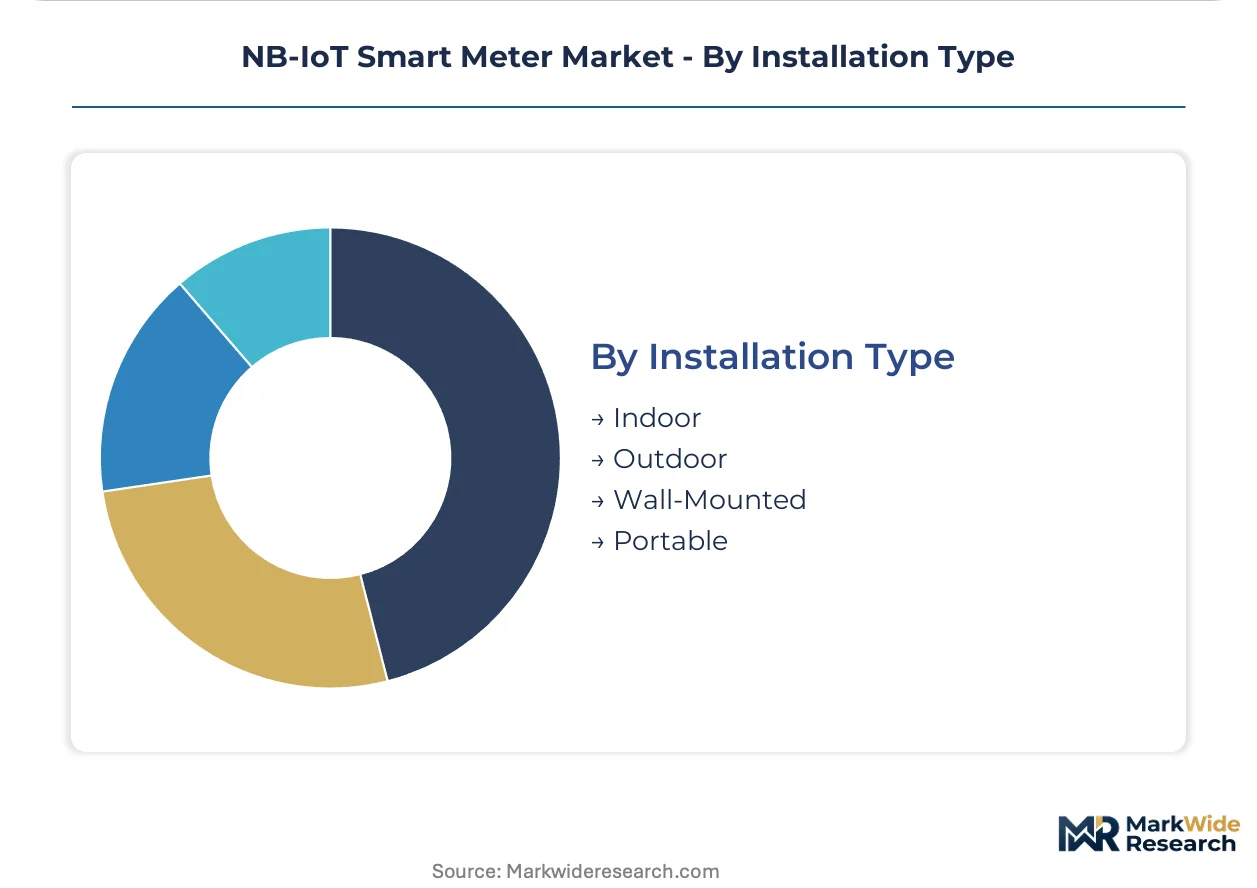
Installation Type:
Physical deployment constraints dictate RF antenna design complexity and enclosure IP ratings, with outdoor specifications demanding specialized sub-GHz engineering talent.
- Indoor:Basement and utility room deployments benefit from reduced metal interference for antenna performance. Residential and small commercial endpoints favor this configuration for maintenance accessibility.
- Outdoor:Pole-mounted and pit-deployed meters require IP68-rated enclosures and corrosion-resistant sub-GHz antenna tuning. RF engineering talent scarcity concentrates among legacy cellular module suppliers.
- Wall-Mounted:Compact form factors for multi-utility endpoints drive system-in-package integration of RF front-end and baseband functions. Danish and German OEMs adopt these modules for ultrasonic metering platforms.
- Portable:Temporary monitoring applications for construction sites and seasonal demand validation use battery-optimized transmission schedules. Pilot programs in Bangalore's smart city missions test this configuration.
Outdoor installations dominate utility-scale deployment; wall-mounted multi-utility configurations are expanding most quickly as form factor miniaturization progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor fabrication clusters supply the majority of NB-IoT chipsets, while European meter OEMs concentrate ultrasonic platform engineering in Denmark and Germany. Municipal procurement patterns diverge sharply between Shenzhen's dense urban rollouts and Amsterdam's outcome-based service contracts.
China
MIIT spectrum allocation for licensed sub-GHz bands has catalyzed replacement cycles across State Grid tenders in Shenzhen and Shanghai. Dual carbon tracking mandates from MEE enforce consumption visibility requirements that accelerate legacy AMR endpoint retirement. Dense manufacturing clusters in the Pearl River Delta produce system-in-package modules for domestic and export markets.
Germany
ETSI M-Bus wireless interoperability standards shape certification requirements for cross-border utility deployment. EU Green Deal metering directives accelerate municipal replacement programs in Berlin and Munich. Industrial automation heritage concentrates in Bavaria, where integrated grid analytics capabilities support premium-tier tender participation.
United States
FCC Part 22 frameworks govern licensed spectrum access for demand-response signaling applications. State-level public utility commissions in California and Texas layer data privacy obligations atop federal device authorization requirements. Pilot programs in the Southwest test hybrid connectivity architectures blending cellular backhaul with mesh protocol fallback.
Netherlands
CEA technical standards alignment supports municipal water utility pilots in Amsterdam and Rotterdam. Outcome-based procurement contracts link vendor payments to leak reduction metrics rather than hardware acquisition costs. Randstad urban density enables dense NB-IoT network topology for district heating telemetry.
India
Smart city missions in Bangalore and Hyderabad pilot pressure monitoring systems with CEA technical standards alignment. Municipal budget constraints favor meter-as-a-service arrangements over capital expenditure procurement. Telangana's utility operators test portable configurations for seasonal demand validation at construction sites.
NB-IoT Smart Meter Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized metering platforms rather than pure-play connectivity vendors. The competitive structure bifurcates between utility-grade precision suppliers and cost-optimized module integrators. Three archetypes dominate: captive semiconductor producers with backward integration into chipset supply, ultrasonic measurement specialists with district heating expertise, and industrial automation conglomerates with integrated grid analytics portfolios. Dominant competitive moves include strategic partnerships for multi-protocol firmware development and geographic expansion through municipal tender participation.
Among diversified industrial technology groups, Siemens AG anchors the premium-tier segment through its German engineering heritage and integrated automation portfolios. Huawei Technologies Co., Ltd. and ZTE Corporation occupy positions within the captive supply archetype, leveraging East Asian semiconductor fabrication clusters for module cost positioning. Kamstrup A/S exemplifies the specialized platform approach, representing Danish ultrasonic metering expertise for thermal and fluid measurement applications. These three archetypes—industrial conglomerate, captive semiconductor supplier, and measurement specialist—collectively shape procurement dynamics across European and Asian utility tenders.
| Leading Market Players |
|---|
| Siemens AG |
| Landis+Gyr Group AG |
| Huawei Technologies Co., Ltd. |
| Kamstrup A/S |
| Itron Inc. |
| Sagemcom |
| ZTE Corporation |
| Ericsson AB |
| Nokia Corporation |
| Others |
Pricing and Supply Chain Analysis
System-in-package module substitution for discrete component stacks simultaneously shifts manufacturing gravity toward East Asian semiconductor clusters and compresses bill-of-materials differentiation between utility-grade and commercial-grade suppliers. This component consolidation dynamics rewards captive producers with pricing leverage while squeezing margin buffers for module integrators dependent on external chipset procurement.
Pricing Analysis
MIIT spectrum allocation dictates the pricing tier structure across Chinese State Grid tenders, where licensed sub-GHz operation commands premium positioning against unlicensed mesh alternatives. Three-tier pricing structure across premium, standard, and economy levels separates DLMS/COSEM-certified electric meters from basic telemetry endpoints and hybrid connectivity configurations. Price differentiation rests on certification grade and volume scale, with municipal procurement consolidation accelerating cost compression in the mid-market. Battery chemistry specifications and RF engineering talent scarcity sustain premium positioning for outdoor-rated outdoor installations, while residential endpoints face acute price sensitivity from budget-constrained utilities.
Supply Chain Analysis
Strategic stockpiling of NB-IoT chipsets dominates procurement behavior among European meter OEMs confronting allocation risk from East Asian semiconductor fabrication clusters. Supply concentrates in China, Taiwan, and South Korea for RF front-end components, with lithium thionyl chloride cells drawing from Japanese and South Korean chemical suppliers. Single-source vulnerability in captive semiconductor production creates exposure for Western meter vendors lacking backward integration into chipset supply. Distribution runs through direct municipal tender participation and meter-as-a-service platform operators consolidating vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NB-IoT smart meter market sits in a replacement-cycle upswing driven by China's dual carbon tracking mandates and EU Green Deal metering directives, creating favorable conditions for equipment suppliers with certification-ready portfolios.
For Market Incumbents: Fortify integrated grid analytics capabilities against specialized ultrasonic platform vendors encroaching on district heating segments. Siemens AG and Huawei Technologies Co., Ltd. should deepen captive semiconductor production to defend margin position against module cost compression. Certification investment in ETSI M-Bus wireless interoperability and China's GB/T radio specifications preserves tender eligibility as procurement windows tighten. For New Entrants and Emerging Players: Lead with hybrid connectivity architectures targeting mid-market water utilities in India's smart city missions, where CEA technical standards alignment opens procurement access. Municipal operators in Bangalore and Hyderabad represent the most penetrable geography given budget constraints favoring meter-as-a-service arrangements over capital expenditure models. Outcome-based contracting linking vendor payments to leak reduction metrics offers differentiated go-to-market positioning against hardware-centric incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized measurement platforms with district heating expertise over diversified industrial conglomerates. Acquisition targets should display ultrasonic metering IP, multi-protocol firmware capabilities, or established municipal utility relationships. Long-term viability across the next decade hinges on ESG documentation compliance for EU CSRD disclosure requirements. The signal to monitor is spectrum reallocation proceedings in major economies, which would trigger replacement demand inflections.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Firmware Development | Simultaneous DLMS/COSEM and M-Bus support accelerates certification timelines for cross-border tenders. |
| System-in-Package Integration | Single-die RF solutions from East Asian fabs compress cost structures for compact ultrasonic form factors. |
| Outcome-Based Procurement Contracts | Dutch and Spanish water operators now link vendor payments to verified leak reduction metrics. |
| ESG Supply Chain Documentation | EU CSRD disclosure requirements mandate conflict mineral traceability for electric meter procurement. |
| Hybrid Connectivity Architecture | NB-IoT fallback with mesh protocol blending captures mid-market segments between premium cellular and economy radio. |
Research Methodology
The analysis maps electric, water, gas, and multi-utility meter segments, each validated through utility planning officers, RF engineering specialists, municipal procurement managers, and cellular module suppliers. Primary interviews with State Grid tender participants in Shenzhen and ETSI certification consultants in Copenhagen combined with secondary validation from MIIT spectrum filings, EU Green Deal directive texts, and FCC Part 22 authorization databases. Bottom-up deployment volume estimates and top-down infrastructure spending analysis triangulate market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs, with segmentation modeling across utility type, connectivity architecture, installation environment, and regional regulatory cluster. CAGRs derive from infrastructure replacement cycle analysis and mandate enforcement timelines. Forecast inputs include semiconductor supply allocation patterns, lithium thionyl chloride cell capacity constraints, and municipal budget authorization trajectories.
Underlying assumptions cover regulatory mandate enforcement continuity, spectrum allocation stability, and chipset supply normalization, with deviation risk concentrated in semiconductor fabrication allocation disruptions and battery chemistry performance thresholds. Revision becomes warranted when spectrum reallocation proceedings or cybersecurity certification timeline shifts cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
Absolute Pressure Sensor Market