
 Bionic Glove's Market | 2026-2036
Bionic Glove's Market Size, Share, and Industry Trends Forecast 2026-2036
Bionic Glove's Market Outlook
Direct-to-clinic distribution is narrowing as hospital procurement consortia consolidate purchasing power across European rehabilitation networks. Touch Bionics leverages its myoelectric specialization to sustain premium positioning in NHS supply frameworks. Ossur anchors Nordic market access through established orthotic channels, while Open Bionics competes on cost-engineered designs for pediatric prosthetic programs.
A bionic glove integrates actuators, sensors, and control systems to restore or augment hand function through myoelectric signal interpretation or soft robotic actuation. Manufacturing centers on silicone casting for soft robotic digits and precision machining for motorized joint assemblies, with gesture recognition algorithms enabling real-time grip pattern adaptation. Myoelectric product types dominate value pools due to component complexity and clinical reimbursement rates, while soft robotics represents the fastest-expanding category as elastomer actuator costs decline. Rehabilitation applications lead volume through institutional procurement cycles, though sports and assistive technology segments attract direct-consumer interest via subscription-based fitting services.
The FDA classifies powered bionic gloves as Class II medical devices requiring 510(k) clearance, while the EU MDR mandates notified body involvement for myoelectric prosthetics with higher clinical evidence thresholds. Japan's PMDA operates accelerated review pathways for METI-designated assistive robotics, shortening time-to-market for sensor-integrated designs. Stakeholders must monitor evolving reimbursement codes for gesture-controlled devices across Medicare, NHS England, and Japan's long-term care insurance system.
Market Dynamics
The EU Medical Device Regulation's tightened conformity requirements for myoelectric devices are compressing vendor margins while accelerating consolidation among European rehabilitation procurement networks.
Growth Catalysts
- Assistive Robotics Funding:METI's designated funding pathways in Japan accelerate hospital adoption of sensor-integrated gloves through shortened PMDA review timelines.
- Elastomer Cost Curves:Declining silicone actuator manufacturing costs expand addressable volume for soft robotic rehabilitation programs.
- Gesture Recognition Maturation:Real-time grip pattern adaptation algorithms improve functional outcomes in stroke rehabilitation protocols.
Market Restraints
- Premium Component Concentration:Precision machined motorized joint assemblies depend on German and Swiss machining clusters, creating single-source vulnerability.
- Reimbursement Code Gaps:Medicare and NHS England maintain inconsistent coverage for gesture-controlled devices versus traditional myoelectric prosthetics.
- Clinical Validation Burden:EU MDR's higher clinical evidence thresholds extend notified body review cycles for novel actuation mechanisms.
Strategic Opportunities
- Pediatric Direct-to-Consumer:Subscription-based fitting services bypass institutional procurement cycles for congenital limb difference cases.
- Sports Performance Adjacencies:Grip augmentation applications for climbing and adaptive athletics open non-reimbursed payment channels.
- Rehabilitation Robotics Integration:Convergence with exoskeleton therapy protocols creates bundled device procurement in German neurorehabilitation centers.
Industry Challenges
- Myoelectric Signal Calibration:Patient-specific electrode placement requires specialized occupational therapist training that outpaces workforce pipeline expansion.
- Legacy Silicone Casting Retooling:Soft robotic digit manufacturers face capital-intensive mold redesign for multi-material actuator integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bionic Glove's Market |
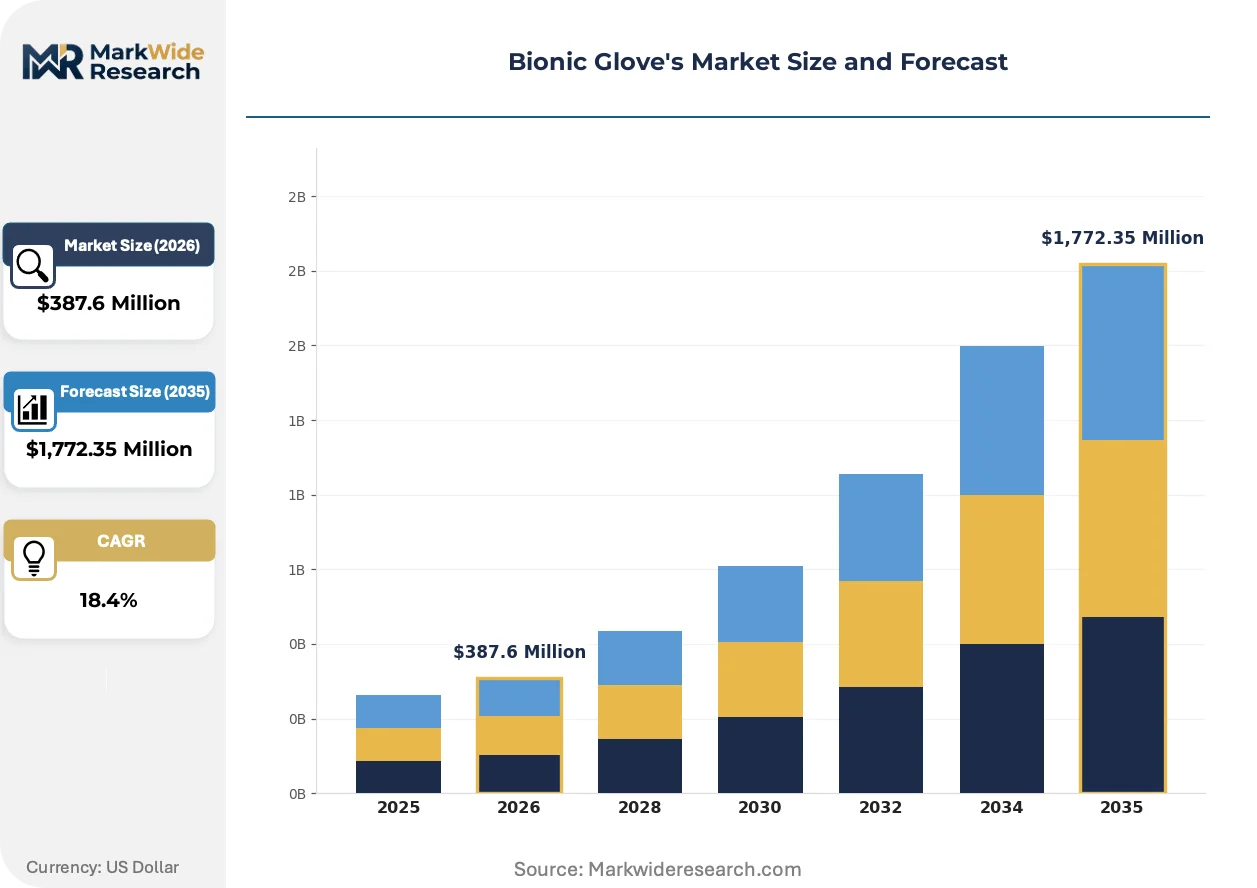
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized, Non-Motorized, Soft Robotics, Myoelectric Application: Rehabilitation, Prosthetics, Assistive Technology, Sports End User: Individuals, Clinics, Hospitals, Rehabilitation Centers Technology: Gesture Recognition, Sensors, Actuators, Control Systems |
| Companies Covered | Touch Bionics, Ossur, Bionic Gloves, Dexterous, BionX Medical Technologies, Open Bionics, SenseGlove, HaptX, Neofect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bionic Glove's Market Strategic Shifts
Soft robotic actuation architectures are compressing the cost-performance frontier for grip restoration devices, while regulatory convergence across major markets rewrites competitive entry requirements.
Dielectric elastomer actuators replace pneumatic bladders in soft robotic digits, delivering proportional force control without compressed air infrastructure. German rehabilitation centers pilot these systems for outpatient stroke therapy. Pneumatic soft robotics is rendering obsolete the tethered compressor designs that limited home deployment.
The EU MDR's post-market surveillance requirements now mandate systematic clinical follow-up for myoelectric prosthetics, not just pre-market validation. Manufacturers must establish notified body-approved quality management systems for adverse event reporting. Class II device reclassification in Germany and France is compressing time-to-revenue for novel sensor configurations.
Hospital procurement consortia across NHS England and German state rehabilitation networks now mandate outcome metrics for assistive device contracts. Traditional distributor relationships fragment as integrated delivery networks negotiate direct manufacturer agreements. This concentration is most visible in Bavaria and North Rhine-Westphalia, where university hospital alliances standardize on interoperable sensor platforms.
Bionic Glove's Market Segmentation
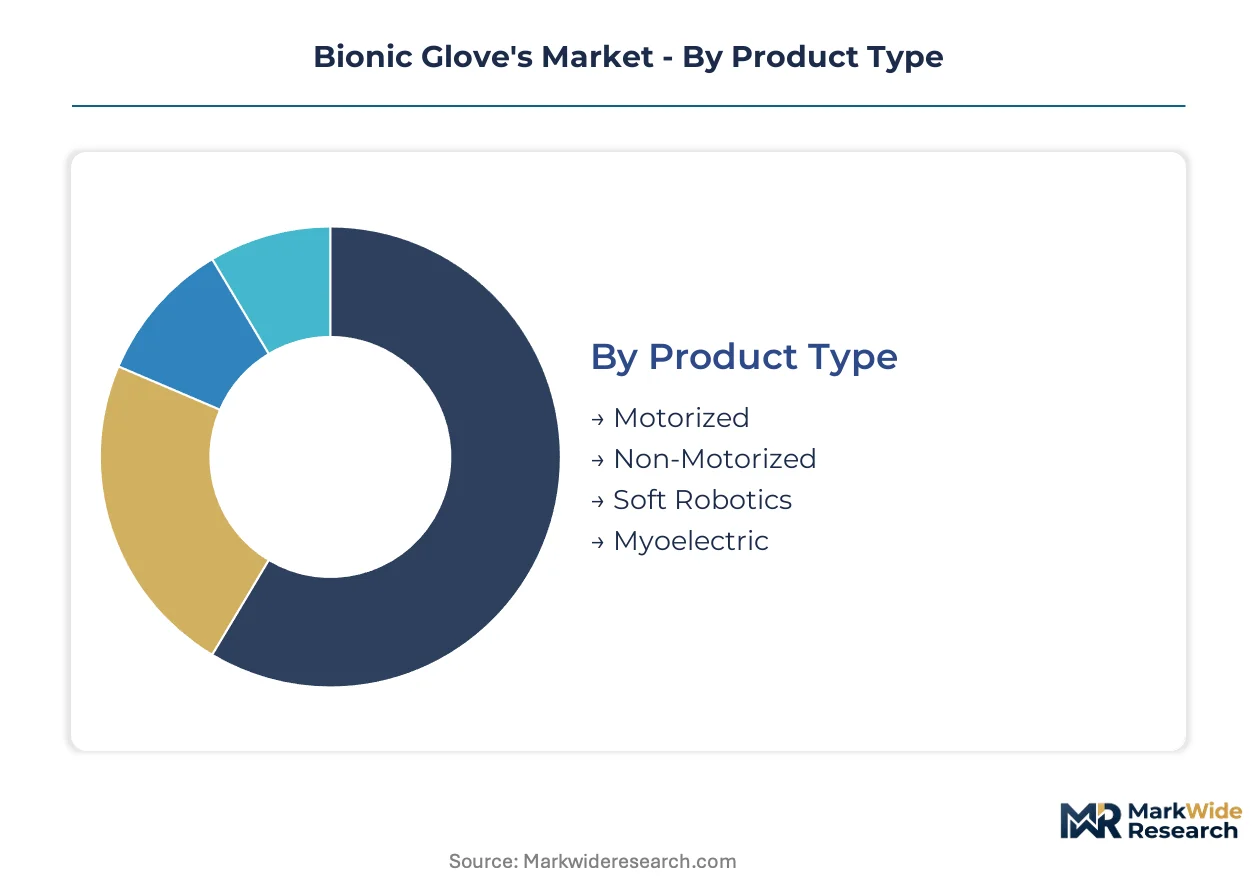
Segmentation in bionic gloves separates procurement velocity from reimbursement complexity. Cycle times vary dramatically across myoelectric versus soft robotic architectures, while institutional buyers impose distinct technical specifications that reshape manufacturing priorities.
Product Type:
Myoelectric and soft robotic systems turn inventory fastest through hospital procurement channels, while motorized joint assemblies face extended validation timelines in European rehabilitation networks.
- Myoelectric:Electrode arrays interpret muscle potentials to drive motorized digit articulation with proportional force control. German rehabilitation centers now mandate these systems for post-stroke hand therapy under consolidated NHS England procurement frameworks, though component complexity stretches reimbursement negotiation cycles.
- Soft Robotics:Elastomer actuators deliver compliant grip restoration without rigid skeletal structures, enabling lighter devices with reduced power consumption. METI-designated funding pathways in Japan accelerate hospital adoption of these sensor-integrated designs through shortened PMDA review timelines.
- Motorized:Precision-machined joint assemblies provide high-force grip patterns for industrial and heavy-duty rehabilitation applications. Swiss machining clusters supply critical geartrain components.
- Non-Motorized:Passive mechanical assistance through spring-loaded or elastic tension systems supports early-stage therapy where powered actuation remains contraindicated. Pediatric programs in Bavaria standardize on these for congenital limb difference cases.
Myoelectric systems dominate installed base through established reimbursement codes. Soft robotics is where expansion concentrates as silicone actuator costs decline and outpatient deployment models mature.
Application:
Cost tiers separate institutional procurement from direct-to-consumer channels, with rehabilitation commanding premium pricing through bundled therapy protocols while sports applications operate entirely outside reimbursement systems.
- Rehabilitation:Stroke and traumatic injury protocols in German neurorehabilitation centers integrate bionic gloves with exoskeleton therapy systems, creating bundled device procurement cycles. Outcome metrics now govern contract renewals across Bavaria and North Rhine-Westphalia university hospital alliances.
- Prosthetics:Congenital and acquired limb difference cases drive pediatric-focused engineering with modular growth accommodation. Open-source hardware initiatives compete with established manufacturers on cost-engineered designs for NHS supply frameworks.
- Assistive Technology:Daily living augmentation for degenerative conditions operates through Japan's long-term care insurance system with standardized functional assessment requirements.
- Sports:Grip augmentation for adaptive climbing and athletics bypasses institutional procurement entirely through subscription-based direct sales. No reimbursement coverage exists in any major market.
Rehabilitation applications anchor revenue concentration through recurring institutional orders. Sports represents the steepest expansion trajectory as non-medical payment channels proliferate.
End User:
Customer type determines specification intensity, with hospitals demanding interoperable sensor platforms while individual purchasers prioritize fitting convenience over clinical validation depth.
- Hospitals:Integrated delivery networks in NHS England and German state rehabilitation systems negotiate direct manufacturer agreements, bypassing traditional distributor relationships. Interoperability mandates with existing electronic health records constrain vendor selection.
- Rehabilitation Centers:Outpatient therapy facilities in Japan leverage METI funding accelerators to deploy sensor-integrated gloves at scale, with procurement consortia consolidating purchasing power across metropolitan Tokyo and Osaka networks.
- Clinics:Private occupational therapy practices face capital constraints that favor leased or subscription-based device models over outright purchase.
- Individuals:Direct-to-consumer sales for congenital limb difference cases bypass institutional procurement cycles through remote fitting services and modular component shipments.
Hospitals dominate installed base through multi-year framework agreements. Individual purchasers represent where expansion concentrates as remote fitting technologies reduce clinical dependency.
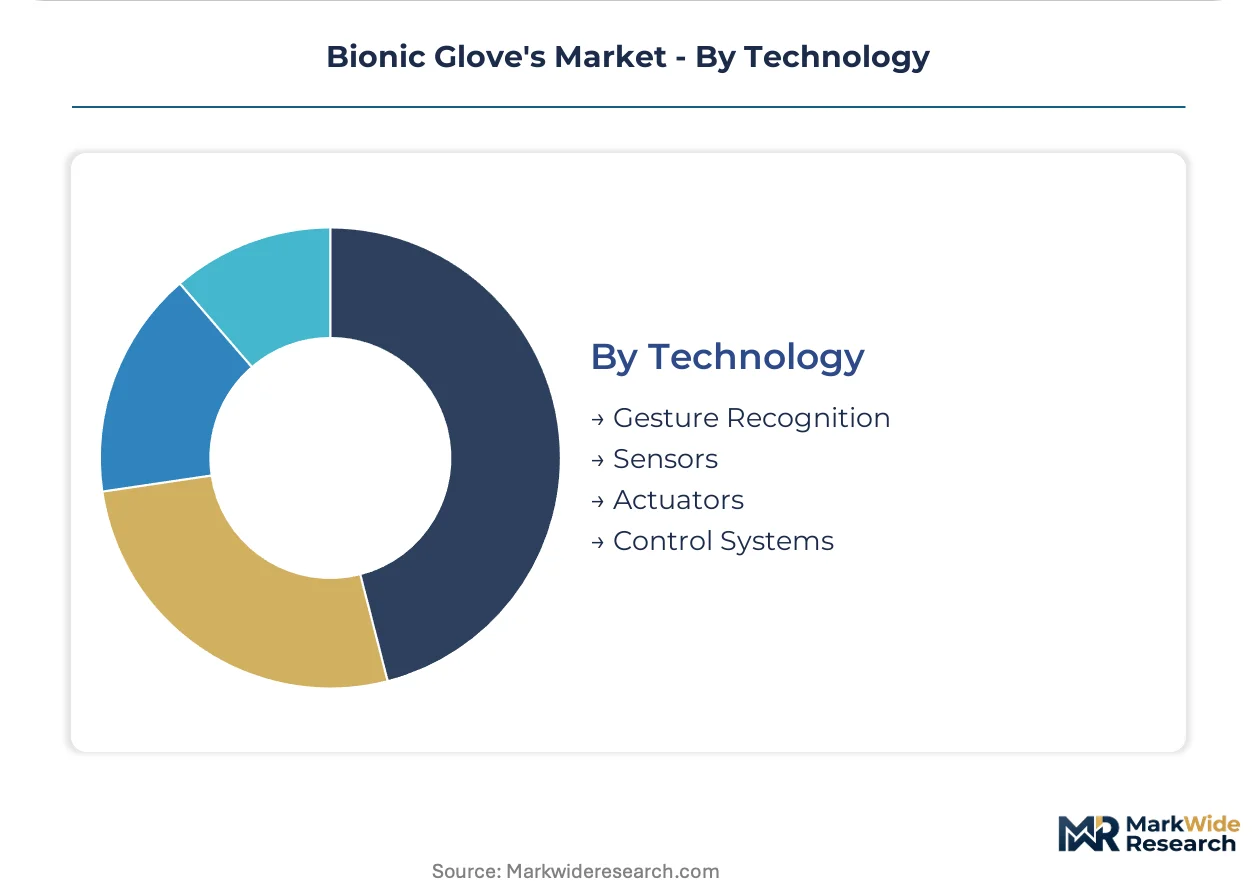
Technology:
Supply concentration in gesture recognition algorithms and precision actuators creates vendor lock-in risks, while sensor commoditization opens second-source pathways for cost-sensitive procurement.
- Gesture Recognition:Real-time grip pattern adaptation algorithms process electromyographic and inertial sensor inputs to predict intended hand postures. German rehabilitation pilots demonstrate measurable functional outcome improvements in stroke protocols.
- Actuators:Dielectric elastomer and pneumatic soft robotic architectures displace tethered compressor designs, enabling home deployment without compressed air infrastructure. Manufacturing concentrates in silicone casting facilities with multi-material mold capabilities.
- Sensors:Force, position, and myoelectric sensing arrays provide closed-loop control feedback. Component standardization accelerates across Japanese hospital procurement specifications.
- Control Systems:Embedded firmware manages power distribution, safety interlocks, and wireless connectivity to therapy monitoring platforms. FDA 510(k) clearance requirements extend development timelines for novel architectures.
Gesture recognition dominates installed base through clinical outcome differentiation. Control systems represent where expansion concentrates as EU MDR post-market surveillance mandates drive software update revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's distribution dominance for precision-machined actuator components, while Tokyo's Haneda logistics corridor accelerates METI-funded assistive robotics deployment across Japanese hospital networks.
Germany
Bavarian rehabilitation centers drive procurement volume for myoelectric stroke therapy systems. The EU MDR's notified body requirements compress vendor margins while consolidating purchasing power across university hospital alliances. Stuttgart's precision machining cluster supplies critical geartrain components for motorized joint assemblies.
Japan
Metropolitan Tokyo and Osaka rehabilitation networks deploy sensor-integrated gloves at scale through METI-designated funding pathways. PMDA accelerated review pathways shorten time-to-market for novel actuation designs. Nagoya's automotive component suppliers are retooling for soft robotic actuator casting.
United States
Stroke rehabilitation protocols in major academic medical centers anchor institutional demand for gesture-recognition systems. FDA 510(k) clearance requirements extend development timelines for embedded control architectures. The Boston-Worcester corridor concentrates myoelectric signal processing algorithm development.
Switzerland
Zurich and Basel rehabilitation networks import German-manufactured devices while maintaining independent procurement specifications. Swissmedic operates mutual recognition agreements with EU notified bodies for myoelectric prosthetics. The Jura Arc machining cluster produces high-torque joint components for heavy-duty applications.
South Korea
Seoul Capital Area hospitals pilot soft robotic digits for outpatient hand therapy programs. MFDS regulatory convergence with FDA 510(k) pathways accelerates parallel submission strategies. Busan-Ulsan's polymer processing infrastructure supports silicone elastomer actuator manufacturing.
Bionic Glove's Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision-machined actuators and sensor arrays. The vendor structure fragments across myoelectric incumbents, soft robotic entrants, and pediatric-focused cost engineers. Three archetypes dominate: established orthotic channel players, venture-backed gesture-recognition developers, and open-source hardware collectives. Competitive moves concentrate on strategic partnerships with rehabilitation procurement consortia and backward integration into silicone casting capabilities.
Within the established orthotic tier, Ossur and Touch Bionics occupy positions anchored through NHS and European rehabilitation network frameworks. Open Bionics exemplifies the cost-engineering archetype targeting pediatric congenital limb difference cases outside institutional procurement cycles. SenseGlove represents the venture-backed gesture-recognition vector penetrating industrial training and rehabilitation adjacencies.
| Leading Market Players |
|---|
| Touch Bionics |
| Ossur |
| Bionic Gloves |
| Dexterous |
| BionX Medical Technologies |
| Open Bionics |
| SenseGlove |
| HaptX |
| Neofect |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in German precision machining clusters is compressing component pricing for motorized joint assemblies while simultaneously pressuring suppliers toward volume-commitment contracts with rehabilitation procurement consortia. This utilization dynamic creates asymmetric pricing power favoring hospital buyers in Bavaria and North Rhine-Westphalia, where consolidated purchasing frameworks extract preferential terms from actuator manufacturers facing fixed-cost absorption pressures.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with NHS England and German state rehabilitation networks extracting 15-25% price concessions on myoelectric systems above 50-unit annual commitments. Pricing stratifies across premium myoelectric configurations, standard soft robotic platforms, and economy passive-assistance tiers, with differentiation driven by FDA 510(k) certification status and embedded gesture-recognition capability. Cost compression in soft robotic segments is intensifying as silicone casting capacity expands in South Korea and Japan, though myoelectric systems retain pricing resilience due to electrode array complexity. Pediatric direct-to-consumer channels exhibit highest price sensitivity, while German neurorehabilitation centers prioritize outcome-guaranteed contracts over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for sensor array manufacturers, with force-feedback components subject to dual-use export classification reviews. Precision-machined geartrains draw from German and Swiss machining clusters, while dielectric elastomer actuators source from Nagoya's automotive-component retooling facilities and Busan-Ulsan's polymer processing infrastructure. Single-source vulnerability concentrates in high-torque joint assemblies where Jura Arc suppliers maintain proprietary tooth-profile geometries. Distribution runs through hospital procurement consortia and direct-manufacturer agreements, bypassing traditional orthotic distributor networks in consolidated European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability mandates across German university hospital alliances signal a platform-economics inflection, with sensor-integrated gloves converging on standardized data exchange protocols that favor ecosystem orchestrators over standalone device vendors.
For Market Incumbents: Entrench position through backward integration into silicone casting capabilities and exclusive partnerships with NHS procurement frameworks, defending against open-source hardware collectives targeting pediatric cost-engineering segments. Prioritize EU MDR notified body relationship depth as a certification moat for novel actuation mechanisms. For New Entrants and Emerging Players: Pursue sports performance adjacencies in adaptive athletics and climbing grip augmentation, where non-reimbursed direct-to-consumer channels bypass institutional procurement barriers. Target subscription-based remote fitting services for congenital limb difference cases outside metropolitan hospital networks, leveraging modular component shipments to minimize clinical dependency. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among gesture-recognition platform developers with software-update revenue models driven by EU MDR post-market surveillance mandates. Long-term viability hinges on acquisition targets possessing captive silicone actuator manufacturing and established rehabilitation procurement consortia relationships. Watch for PMDA accelerated review pathway designations as inflection indicators for Japanese market penetration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Casting Backward Integration | Captive elastomer actuator production insulates margins from South Korean polymer price volatility. |
| Hospital Procurement Consortium Partnership | Direct agreements with Bavarian university hospital alliances lock out distributor-dependent competitors. |
| Gesture Recognition Platform Integration | Interoperability with German electronic health record systems creates switching costs for rehabilitation centers. |
| PMDA Accelerated Review Pathway Submission | METI-designated assistive robotics status compresses time-to-market for sensor-integrated glove launches. |
| Pediatric Direct-to-Consumer Subscription Launch | Remote fitting services bypass NHS procurement cycles for congenital limb difference cases. |
Study Parameters
Cross-validation between primary interviews with rehabilitation center procurement directors, biomedical engineers, and occupational therapists and secondary sources including FDA 510(k) clearance databases, NHS supply framework contracts, and METI assistive robotics funding disclosures anchors the qualitative findings. Bottom-up triangulation of hospital procurement volumes across German state rehabilitation networks and top-down calibration against EU medical device trade statistics ensures dimensional consistency. Primary fieldwork concentrated on stroke therapy protocol integration and myoelectric signal calibration training requirements.
Calibration against historical reimbursement code adoption curves and regulatory review timeline databases shapes the projection framework. Segmentation dimensions span product architecture, application setting, end-user type, and technology layer, with additional modeling of procurement channel evolution across institutional and direct-to-consumer pathways. CAGRs derive from elasticity-adjusted volume projections and pricing trajectory assumptions tied to silicone actuator cost curves and EU MDR compliance cost absorption rates.
Sensitivities concentrate around reimbursement code expansions for gesture-controlled devices, EU MDR notified body capacity constraints, and METI funding pathway renewal decisions. Forecasts embed assumptions on elastomer manufacturing scale economies and clinical validation burden trajectories. Material shifts in FDA Class II reclassification precedents or Japan's long-term care insurance functional assessment criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Assistive Robotics Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
North America Cloud Robotics Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Europe Logistics Robotics Market