
 Cyber-Physical System Market | 2026-2036
Cyber-Physical System Market Size, Share, and Industry Trends Forecast 2026-2036
Cyber-Physical System Market Analysis
Market Context with Strategic Players
Modular system bundling is broadening buyer choice across the Cyber-Physical System landscape. Siemens leverages its digital twin portfolio to anchor large-scale smart factory deployments in Europe. General Electric Company sustains competitive positioning through deep vertical integration into industrial control software and edge analytics. ABB differentiates via robotics-centric cyber-physical architectures that dominate automotive assembly lines.
Technical Definition and Structural Segments
A cyber-physical system integrates computational algorithms with physical processes through networked sensors, actuators, and real-time feedback loops operating at sub-millisecond latency thresholds, primarily enabling autonomous monitoring and control across manufacturing, energy, and transportation infrastructure. Embedded Systems and Control Systems occupy the mature core of the product mix, generating stable margin pools from process-heavy industries. Edge Computing and AI within the technology dimension represent the fastest-expanding capability layer, as latency-sensitive applications displace cloud-dependent architectures in autonomous vehicles and healthcare automation.
Regulatory Frame and Forward-Looking Close
The EU AI Act, NIS2 Directive, and IEC 62443 cybersecurity standards collectively shape product certification requirements and market access conditions for cyber-physical deployments across European industrial corridors. FDA guidance on software as a medical device and NHTSA autonomous vehicle safety mandates in the United States impose parallel compliance burdens on healthcare and transportation applications. Stakeholders must monitor divergence between European risk-classification frameworks and American performance-based standards when architecting cross-border system portfolios.
Market Dynamics
Latency requirements below one millisecond are forcing architectural decisions across automotive, healthcare, and energy infrastructure, compressing cloud-dependent designs in favor of localized compute nodes.
Growth Catalysts
- EU AI Act risk-classification mandates:High-risk system designations are accelerating certified component procurement across German and French industrial corridors.
- Smart manufacturing:Automotive and aerospace producers in Japan and the United States are deploying sensor-actuator networks for real-time quality control.
- Edge Computing:Sub-millisecond feedback loops are overtaking cloud architectures in autonomous vehicle testing and surgical robotics validation.
Market Restraints
- Semiconductor supply concentration:Advanced sensor and processor fabrication concentrates in Taiwan and South Korea, exposing lead time volatility.
- IEC 62443 certification costs:Multi-stage security assessments for industrial control systems extend product launch timelines by eight to fourteen months.
- Legacy integration complexity:Brownfield manufacturing sites in the United States and Germany face protocol translation costs when retrofitting analog equipment.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics and automotive components are attracting CPS module assembly investments.
- Digital twin convergence:Physics-based simulation fused with live operational data is opening predictive maintenance contracts in energy infrastructure.
- NIS2 Directive compliance services:Managed security offerings for OT-IT convergence represent recurring revenue streams across European industrial buyers.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineering for real-time operating systems faces recruitment gaps in Germany and the United States.
- Cross-border certification divergence:FDA software-as-medical-device pathways and EU MDR conformity routes impose dual-track documentation burdens on healthcare CPS vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyber-Physical System Market |
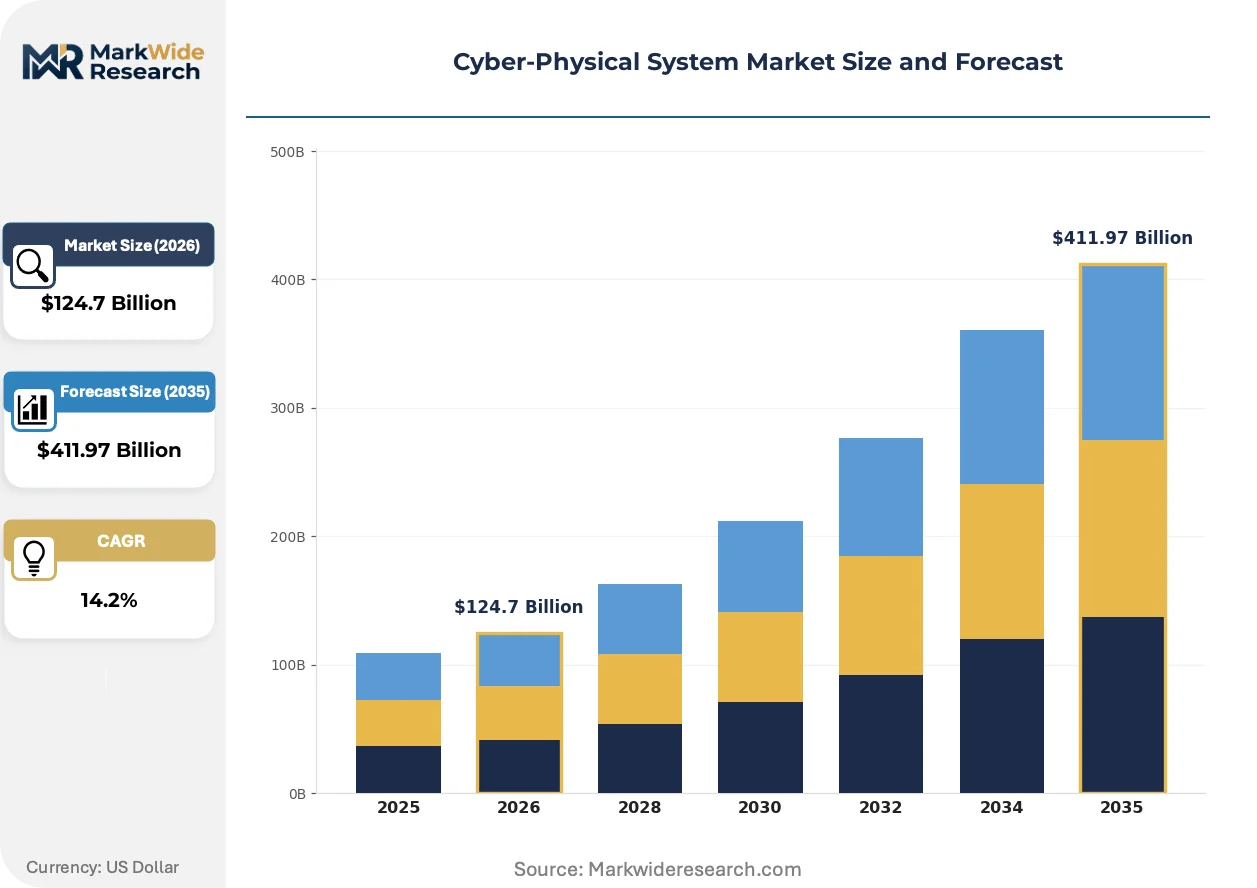
| Market Size in 2026 | $124.7 Billion |
| Market Size in 2035 | $411.97 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Control Systems, Robotics, Sensor Networks Application: Smart Manufacturing, Healthcare Automation, Autonomous Vehicles, Environmental Monitoring Technology: IoT, Edge Computing, AI, Machine Learning End User: Manufacturers, Healthcare Providers, Transportation Companies, Research Institutions |
| Companies Covered | Schneider Electric, General Electric Company, ABB, Robert Bosch GmbH, Hitachi, Ltd., Honeywell International Inc., Siemens, Continental AG, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyber-Physical System Market Emerging Trajectories
Architectural choices in compute placement and security certification are fragmenting vendor strategies, with latency-sensitive applications driving hardware localization while regulatory complexity favors modular compliance frameworks.
Time-sensitive networking (TSN) standards are overtaking proprietary industrial Ethernet protocols in automotive assembly and power grid automation. German and Japanese automotive suppliers are adopting IEEE 802.1AS time synchronization for robotic cell coordination. This convergence is compressing vendor lock-in durations and enabling multi-brand actuator interoperability.
The EU AI Act's high-risk system obligations took effect in August 2024, mandating conformity assessments for autonomous decision-making in manufacturing and transport. European industrial software vendors are restructuring product lines around risk-classification tiers. Healthcare and mobility segments face the steepest compliance cost escalation, with some vendors withdrawing lower-margin SKUs from EU markets.
Buyers in automotive and aerospace are unbundling hardware procurement from lifecycle service agreements, compressing initial contract values while extending vendor accountability periods. German OEMs now separate sensor-actuator purchases from predictive analytics subscriptions. This shift is most pronounced in battery manufacturing and airframe assembly, where capex scrutiny has intensified since 2023.
Cyber-Physical System Market Segmentation
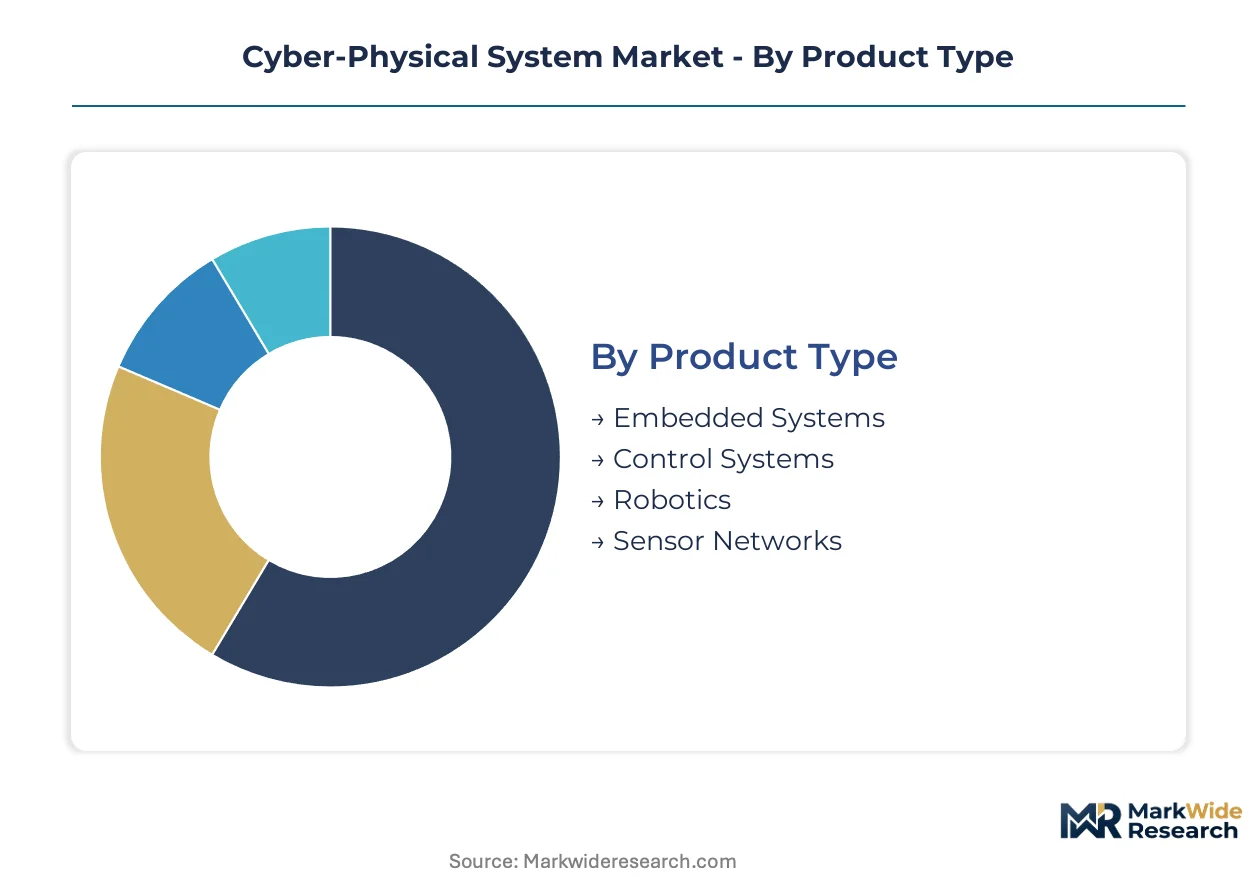
Cyber-physical systems fragment across four intersecting dimensions that determine architectural requirements, certification pathways, and vendor selection criteria. Product type and application layers define hardware specifications, while technology and end-user categories shape deployment complexity and service attach rates.
Product Type:
Embedded Systems and Control Systems anchor revenue volume through brownfield retrofit demand, while Robotics and Sensor Networks command premium pricing in greenfield deployments.
- Embedded Systems:Microcontroller-based architectures with real-time operating systems execute deterministic control loops in manufacturing equipment. German automotive suppliers and Japanese machine tool builders specify these for legacy protocol translation in brownfield sites.
- Control Systems:Programmable logic controllers and distributed control systems orchestrate multi-axis motion and process automation. Demand concentrates in US petrochemical facilities and German chemical corridors where IEC 62443 certification is mandatory.
- Robotics:Articulated and collaborative robot platforms with integrated force-torque sensing enable adaptive assembly operations.
- Sensor Networks:Wireless and wired sensor arrays with mesh topology support condition monitoring across distributed infrastructure.
Today's leader: Embedded Systems. Tomorrow's challenger: Robotics.
Application:
Smart Manufacturing absorbs the highest absolute volume, though Healthcare Automation and Autonomous Vehicles generate superior margins through regulatory complexity and safety-critical design requirements.
- Smart Manufacturing:Sensor-actuator networks with digital twin integration enable real-time quality control and predictive maintenance. Japanese automotive OEMs and US aerospace primes deploy these for zero-defect production targets.
- Autonomous Vehicles:Multi-sensor fusion platforms with sub-millisecond latency requirements process lidar, radar, and camera inputs for path planning. Testing validation in California, Arizona, and Germany drives component procurement.
- Healthcare Automation:Surgical robotics and patient monitoring systems with FDA and EU MDR compliance requirements.
- Environmental Monitoring:Distributed sensing infrastructure for air quality, water management, and emissions tracking.
Smart Manufacturing dominates current procurement volumes; Autonomous Vehicles show the steepest expansion trajectory as NHTSA and KBA testing protocols mature.
Technology:
IoT protocols deliver volume through connectivity standardization, while Edge Computing and AI layers capture margin through localized intelligence and autonomous decision-making capabilities.
- Edge Computing:Containerized compute nodes deployed at network periphery reduce cloud dependency for latency-sensitive workloads. German automotive test beds and US surgical robotics validation centers require sub-millisecond feedback loops.
- AI:Neural network inference engines for pattern recognition and predictive analytics operate on embedded hardware. EU AI Act high-risk system designations are accelerating certified component procurement across French and German industrial corridors.
- IoT:Connectivity protocols including MQTT, OPC-UA, and Time-Sensitive Networking for device interoperability.
- Machine Learning:Supervised and unsupervised learning models for anomaly detection and process optimization.
Edge Computing claims current deployment momentum; AI faces the steepest compliance cost escalation under EU risk-classification frameworks.
End User:
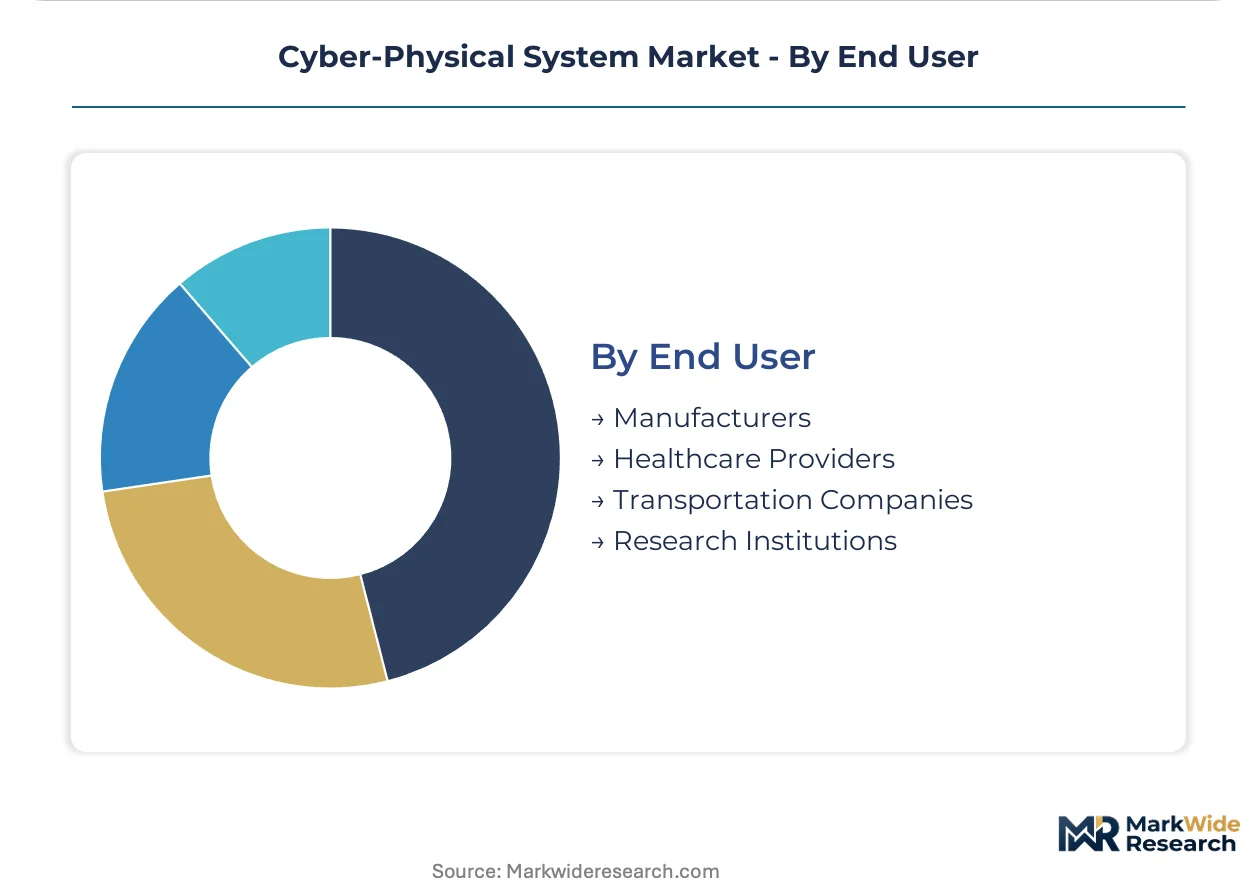
Manufacturers drive procurement scale through fleet standardization, while Healthcare Providers and Transportation Companies impose the most stringent certification and liability requirements.
- Manufacturers:Discrete and process industry operators deploy CPS across production lines, supply chains, and quality systems. German automotive OEMs unbundle hardware procurement from lifecycle service agreements, compressing initial contract values.
- Healthcare Providers:Hospital systems and surgical centers require FDA software-as-medical-device pathways and EU MDR conformity routes. Dual-track documentation burdens favor vendors with established regulatory affairs capabilities.
- Transportation Companies:Fleet operators and logistics providers integrate autonomous and semi-autonomous systems.
- Research Institutions:National laboratories and university consortia prototype next-generation architectures.
Manufacturers anchor current revenue concentration; Healthcare Providers represent the most demanding certification pathway expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial automation architectures during the 1980s, establishing the foundational protocols that now underpin cyber-physical integration across manufacturing corridors worldwide.
United States
Automotive OEMs in Michigan and California are deploying sensor-actuator networks for battery manufacturing quality control. NHTSA autonomous vehicle testing mandates in Arizona and California drive component procurement for multi-sensor fusion platforms. Detroit-Warren-Dearborn and San Jose-Sunnyvale-Santa Clara clusters concentrate validation centers for sub-millisecond feedback systems.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg specify embedded systems for legacy protocol translation in brownfield retrofits. EU AI Act high-risk system designations and IEC 62443 certification requirements shape procurement decisions across industrial corridors. Stuttgart and Munich anchor robotics-centric deployments for adaptive assembly operations.
Japan
Machine tool builders and automotive OEMs in Aichi and Kanagawa prefectures deploy zero-defect production targets through digital twin integration. METI smart manufacturing incentives accelerate sensor network adoption across Tier-1 supplier bases. Nagoya and Yokohama clusters concentrate edge computing validation for surgical robotics and autonomous systems.
India
Electronics and automotive component manufacturers in Maharashtra and Tamil Nadu are attracting CPS module assembly investments through PLI scheme incentives. Central Electricity Authority grid modernization directives drive demand for distributed control systems in power infrastructure. Pune and Chennai industrial corridors concentrate brownfield retrofit demand from process industries.
South Korea
Semiconductor and display panel manufacturers in Gyeonggi-do deploy real-time quality control systems for yield optimization. MFDS medical device software guidance and KBA autonomous vehicle protocols impose dual-track certification requirements. Suwon and Seoul Capital Area clusters concentrate embedded systems engineering for robotics and healthcare automation.
Cyber-Physical System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity and vertical integration depth. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive software portfolios, robotics specialists with force-torque sensing integration, and automation pure-plays with deep PLC installed bases. Dominant competitive moves include M&A targeting edge analytics capabilities and strategic partnerships for TSN protocol standardization.
Among diversified industrial conglomerates, Siemens and General Electric Company exemplify the premium-tier archetype through digital twin and industrial control software integration. ABB occupies a position within robotics-centric cyber-physical architectures, anchoring adaptive assembly solutions for automotive corridors. Schneider Electric and Rockwell Automation represent the automation pure-play segment, with deep installed bases in process industries and brownfield retrofit demand.
| Leading Market Players |
|---|
| Schneider Electric |
| General Electric Company |
| ABB |
| Robert Bosch GmbH |
| Hitachi, Ltd. |
| Honeywell International Inc. |
| Siemens |
| Continental AG |
| Rockwell Automation |
| Others |
Supply Flow & Price Mechanics
German automotive OEMs and Japanese machine tool builders command substantial pricing leverage through unbundled procurement models that separate hardware acquisition from lifecycle service subscriptions. This buyer concentration forces vendors to absorb upfront margin compression while extending accountability periods across predictive maintenance contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the CPS landscape, with premium tiers capturing certified IEC 62443 and EU AI Act-compliant architectures while economy tiers serve non-critical monitoring applications. Price differentiation hinges on certification grade and after-sales service bundling, with FDA and EU MDR pathways adding substantial documentation costs to healthcare tiers. Cost compression in standard-tier embedded systems is intensifying because Taiwanese semiconductor foundries face allocation volatility. Tier-1 automotive suppliers exhibit the highest price sensitivity due to capex scrutiny, whereas healthcare providers accept premium pricing for liability mitigation.
Supply Chain Analysis
Qualification gating through IEC 62443 and EU AI Act conformity assessments restricts supplier pools to certified fabricators, compressing vendor options for safety-critical components. Advanced sensor and processor fabrication concentrates in Taiwan and South Korea, with control system assembly anchored in Germany and the United States. Raw material dependencies span silicon wafers, rare earth magnets for robotics actuators, and specialized industrial Ethernet chipsets. Single-source vulnerability in Taiwanese foundry capacity exposes lead time volatility for automotive and aerospace programs. Distribution runs through authorized system integrators with certified installation capabilities, particularly in European industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cyber-Physical System Market functions as a geographic-arbitrage play where EU AI Act compliance costs in Stuttgart and Munich run substantially higher than equivalent certification burdens in Indian manufacturing corridors under PLI scheme incentives.
For Market Incumbents: Anticipate margin erosion from modular system bundling by diversifying into NIS2 Directive compliance services that generate recurring revenue across European industrial buyers. Deepen backward integration into edge analytics software to defend against automation pure-plays with deep PLC installed bases. Siemens and ABB exemplify this defensive posture through captive digital twin portfolios and robotics-centric architectures. For New Entrants and Emerging Players: Brownfield manufacturing sites in the United States and Germany represent an underserved buyer archetype with acute protocol translation needs and limited incumbent attention. Target mid-tier automotive suppliers in India's Maharashtra and Tamil Nadu corridors where PLI scheme incentives reduce initial procurement friction. A sensor-network-as-a-service model bypasses capital expenditure barriers while embedding predictive maintenance capabilities. For Investors and Strategic Acquirers: Diversified industrial conglomerates with captive software portfolios are the most active acquirer in this space, seeking edge analytics capabilities to complement hardware foundations. The acquisition target archetype comprises robotics specialists with force-torque sensing integration and established IEC 62443 certification pathways. Monitor FDA software-as-medical-device submission volumes as an inflection indicator for healthcare CPS segment maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Siemens anchors large-scale smart factory deployments through physics-based simulation fused with live operational data. |
| IEC 62443 Certification Investment | Multi-stage security assessments extend product launch timelines but unlock access to German chemical corridors and US petrochemical facilities. |
| Edge Computing Node Localization | Sub-millisecond feedback requirements in California and Arizona autonomous vehicle test beds displace cloud-dependent architectures. |
| NIS2 Compliance Service Launch | Managed security offerings for OT-IT convergence capture recurring revenue from European industrial buyers facing tightened cybersecurity mandates. |
| Robotics-Centric Architecture Development | ABB dominates automotive assembly lines through adaptive operations with integrated force-torque sensing and collaborative robot platforms. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory affairs specialists grounded the qualitative assessment, supplemented by SEC filings, customs and trade data, IEC certification registries, and hospital procurement databases. Bottom-up and top-down triangulation validated volume estimates across embedded systems, control systems, robotics, and sensor network segments.
Bottom-up modeling of component-level demand and top-down macroeconomic calibration shaped the analytical framework across the projection horizon. Segmentation dimensions included product type, application, technology layer, and end-user category, with regional regulatory clusters and certification intensity serving as cross-cutting variables. CAGRs were derived from installed base growth rates, replacement cycles, and greenfield deployment pipelines in automotive, aerospace, and healthcare verticals.
Underlying measurement precision varies by segment; embedded systems and control systems carry tighter precision due to established brownfield retrofit demand patterns, whereas AI-enabled edge computing faces wider uncertainty from evolving EU AI Act enforcement. Forecasts reflect assumptions about semiconductor supply normalization, regulatory implementation timelines, and industrial capital expenditure cycles. A model refresh is warranted upon material change in IEC 62443 certification processing times or NHTSA autonomous vehicle testing protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Robotic Process Automation in BFSI Market