
 Global Robotic Grippers Market | 2026-2036
Global Robotic Grippers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotic Grippers Market Intelligence
The shift towards robotics-as-a-service (RaaS) and equipment leasing models is rewriting the competitive landscape for robotic grippers. This asset-light approach allows smaller enterprises to deploy advanced automation without significant upfront capital expenditure. In this environment, OnRobot A/S competes on ease of integration and modularity for collaborative robots. Meanwhile, established industrial automation firms like SCHUNK GmbH And Co KG sustain their market position through extensive R&D in specialized, high-performance gripping solutions for demanding applications.
Robotic grippers are electromechanical or pneumatic devices that function as end-of-arm tooling (EOAT) on industrial robots. These components are designed to interact with objects, defined by parameters such as payload capacity, gripping force, and actuation speed. Their primary purpose is to pick, place, hold, and manipulate items in automated manufacturing and logistics environments. Electric grippers are gaining share over traditional pneumatic types due to their superior precision and energy efficiency, especially in cleanroom settings.
Product design and market access are shaped by machinery safety regulations, including OSHA standards in the United States and the mandatory CE marking for equipment sold in the European Union. These frameworks mandate risk assessments and integrated safety features, particularly for human-robot collaboration. The key decision for vendors revolves around balancing investments in universal, plug-and-play grippers versus highly specialized, application-specific solutions to capture diverse end-user requirements.
Market Dynamics
The central dynamic shaping the robotic gripper market is the strategic divergence between vendors pursuing universal, plug-and-play solutions for collaborative robots and those focusing on high-performance, specialized grippers for niche, demanding industrial applications.
Growth Catalysts
- Food Processing Adoption:Demand from the food and beverage industry for hygienic, soft grippers capable of handling delicate and irregularly shaped items like produce and baked goods is a primary catalyst.
- Collaborative Robot Safety Standards:The maturation of safety frameworks, such as ISO/TS 15066, enables wider deployment of grippers in fenceless environments, allowing for direct human-robot collaboration on assembly lines.
- Advanced Manufacturing in Germany:Germany’s automotive and electronics industries require high-precision grippers for automated assembly and packaging, concentrating demand for sophisticated electric and adaptive gripping technologies.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for advanced electric and adaptive grippers, compared to simpler pneumatic alternatives, remains a barrier for small and medium-sized enterprises.
- Payload and Force Limitations:Many grippers designed for collaborative robots have inherent payload and gripping force limitations, making them unsuitable for heavy-duty applications found in foundries or primary metal processing.
- System Integration Complexity:Integrating grippers with existing robotic arms and controllers from different manufacturers often requires custom development work due to a lack of universal communication protocols and mechanical interfaces.
Strategic Opportunities
- Pharmaceutical and Lab Automation:The use of precise, sterile grippers for automated sample handling, vial filling, and kit assembly represents a significant growth area within the life sciences sector.
- AI-Integrated Vision Systems:Incorporating artificial intelligence and machine learning algorithms directly into gripper control systems enables adaptive picking of unsorted objects in complex environments like e-commerce fulfillment.
- Expansion in Southeast Asian Electronics:Manufacturing hubs in countries like Vietnam and Malaysia present an opportunity for gripper deployment in high-volume electronics assembly and testing applications.
Industry Challenges
- Robotics Technician Skill Gap:A persistent shortage of technicians and engineers with the skills to program, integrate, and maintain robotic systems featuring advanced end-of-arm tooling hinders deployment.
- Interoperability Standardization:The absence of a universally accepted standard for gripper-to-robot electrical and mechanical connections creates friction for end-users and system integrators, increasing implementation costs and time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotic Grippers Market |
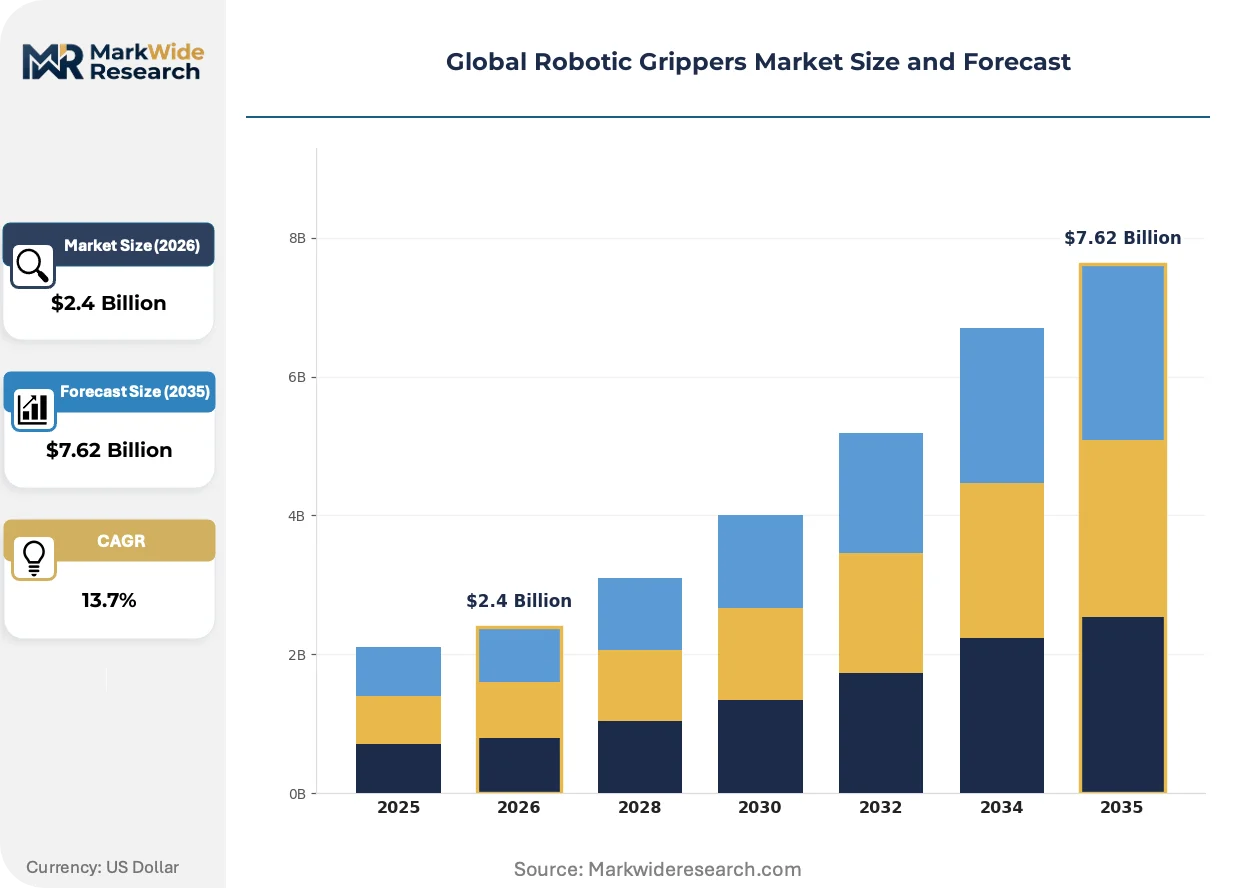
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Grippers, Vacuum Grippers, Magnetic Grippers, Adhesive Grippers Technology: Pneumatic, Hydraulic, Electric, Electrostatic, Piezoelectric Application: Material Handling, Packaging Solutions, Assembly Processes, Quality Inspection End User: Electronics Manufacturers, Consumer Goods Producers, Aerospace Manufacturers, Food Processing Units |
| Companies Covered | SCHUNK GmbH And Co KG, Festo SE And Co KG, Zimmer Group, SMC Corporation, ATI Industrial Automation, Schmalz GmbH, OnRobot A/S, Robotiq Inc, Destaco LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotic Grippers Market Strategic Shifts & Innovations
Sensory feedback and inherent adaptability are becoming defining features in gripper design. The market is moving beyond simple open-close actuation toward intelligent end-effectors that can perceive, adapt, and interact with their environment in a more nuanced way.
Soft robotics, utilizing compliant materials like silicone, enables grippers to conform to and gently handle a wide variety of object shapes and sizes. The food handling, agriculture, and medical device assembly sectors are adopting these systems for tasks involving delicate or easily damaged products. This technology is collapsing the divide between the high force of traditional industrial grippers and the dexterity required for complex manipulation tasks.
Harmonization of safety standards, particularly through ISO/TS 15066 for collaborative robots, is fundamentally altering product development. This regulatory guidance necessitates the integration of safety features directly into the gripper, such as force and torque limiting. Gripper manufacturers are most affected, now engineering products with inherent safety to permit fenceless operation alongside human workers in production environments across Europe and North America.
Asset-light consumption models, notably Robotics-as-a-Service (RaaS), are gaining favor over outright capital equipment purchases. This model disrupts the classic sales channel by allowing end-users to pay a subscription fee for a fully serviced automation solution, including the robot, gripper, and maintenance. This trend is most prominent in the logistics and e-commerce fulfillment sectors, where fluctuating demand makes scalable, opex-based automation highly attractive.
Global Robotic Grippers Market Segmentation
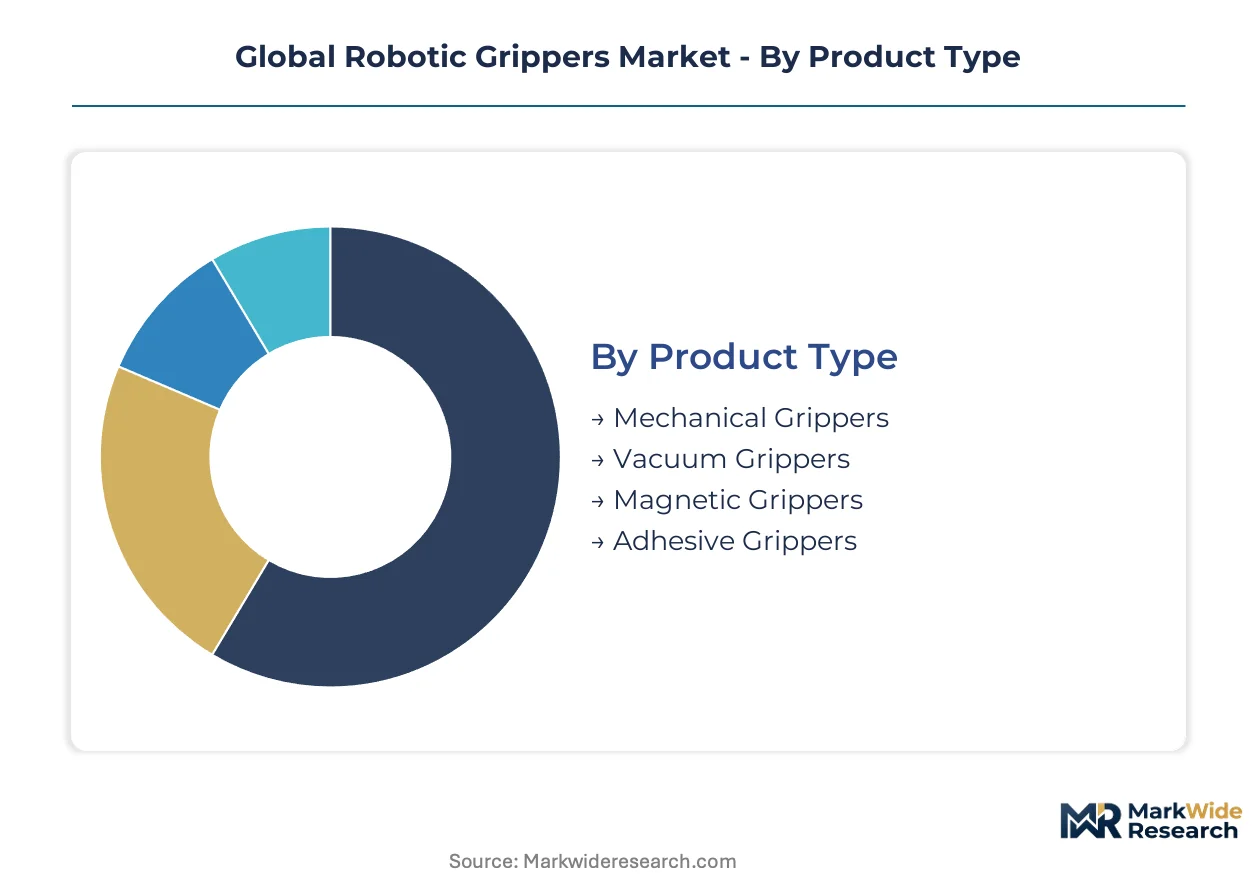
Understanding the varied requirements of industrial automation is critical for robotic gripper manufacturers. This market segmentation illuminates the diverse product configurations, underlying technologies, application areas, and end-user industries that define demand for these essential robotic components.
Product Type:
The functional design of robotic grippers varies significantly, impacting their suitability for different tasks and materials.
- Mechanical Grippers:These utilize jaws or fingers to grasp objects, powered by various actuation methods. Mechanical grippers are widely deployed in heavy manufacturing for robust material handling tasks in sectors like automotive assembly.
- Vacuum Grippers:Employing suction cups to lift and manipulate items, these grippers are ideal for handling flat, non-porous surfaces. Demand concentrates in packaging and logistics for picking and placing cartons or electronic components.
- Magnetic Grippers:Using electromagnetic forces, these devices secure ferromagnetic materials. Their primary use is in metal fabrication and automotive stamping plants for efficient part transfer.
- Adhesive Grippers:These grippers rely on sticky surfaces or gecko-inspired adhesion to handle delicate or irregularly shaped items without damage. They find application in food processing for soft produce and in electronics for fragile components.
Mechanical grippers command the established base. The steepest expansion runs through adhesive grippers.
Technology:
The underlying actuation mechanism dictates a gripper's performance characteristics, including speed, precision, and force control.
- Electric:These grippers use electric motors for precise control over gripping force and position, offering high repeatability and energy efficiency. Electric grippers are gaining share in cleanroom environments and collaborative robot applications across Germany.
- Pneumatic:Operating with compressed air, pneumatic grippers are known for their simplicity, speed, and high gripping force. These remain prevalent in high-speed pick-and-place operations within packaging and assembly lines.
- Hydraulic:Utilizing incompressible fluid pressure, hydraulic grippers deliver very high gripping forces for heavy-duty applications. Foundries and primary metal processing industries employ these for robust material manipulation.
- Electrostatic:These grippers use electrostatic forces to handle thin, lightweight, and fragile materials, such as semiconductor wafers or textile sheets. Precision electronics manufacturing benefits from their non-contact handling capabilities.
- Piezoelectric:Employing piezoelectric materials that change shape when an electric current is applied, these grippers offer ultra-high precision and rapid actuation for micro-manipulation tasks. Medical device assembly and laboratory automation increasingly use these systems.
Electric solutions are rapidly gaining share, while pneumatic systems retain a substantial installed base.
Application:
Robotic grippers are integral to automating a wide array of industrial processes, each demanding specific gripper capabilities.
- Material Handling:This broad category includes tasks like picking raw materials, moving work-in-progress, and palletizing finished goods. Heavy industries and logistics operations rely on grippers for efficient movement of diverse items.
- Packaging Solutions:Grippers in packaging handle items for bagging, boxing, and tray loading, often requiring gentle handling and high speed. The food and beverage industry demands specialized grippers for delicate product packaging.
- Assembly Processes:Grippers precisely place and join components in manufacturing lines, from small electronics to large automotive parts. High-precision electric grippers are crucial for complex assembly in Germany's automotive sector.
- Quality Inspection:Grippers present parts to vision systems or sensors for automated inspection, ensuring product consistency. They are used in electronics and medical device manufacturing to accurately position items for defect detection.
Material handling tasks represent the foundational demand, while specialized packaging applications show strong expansion.
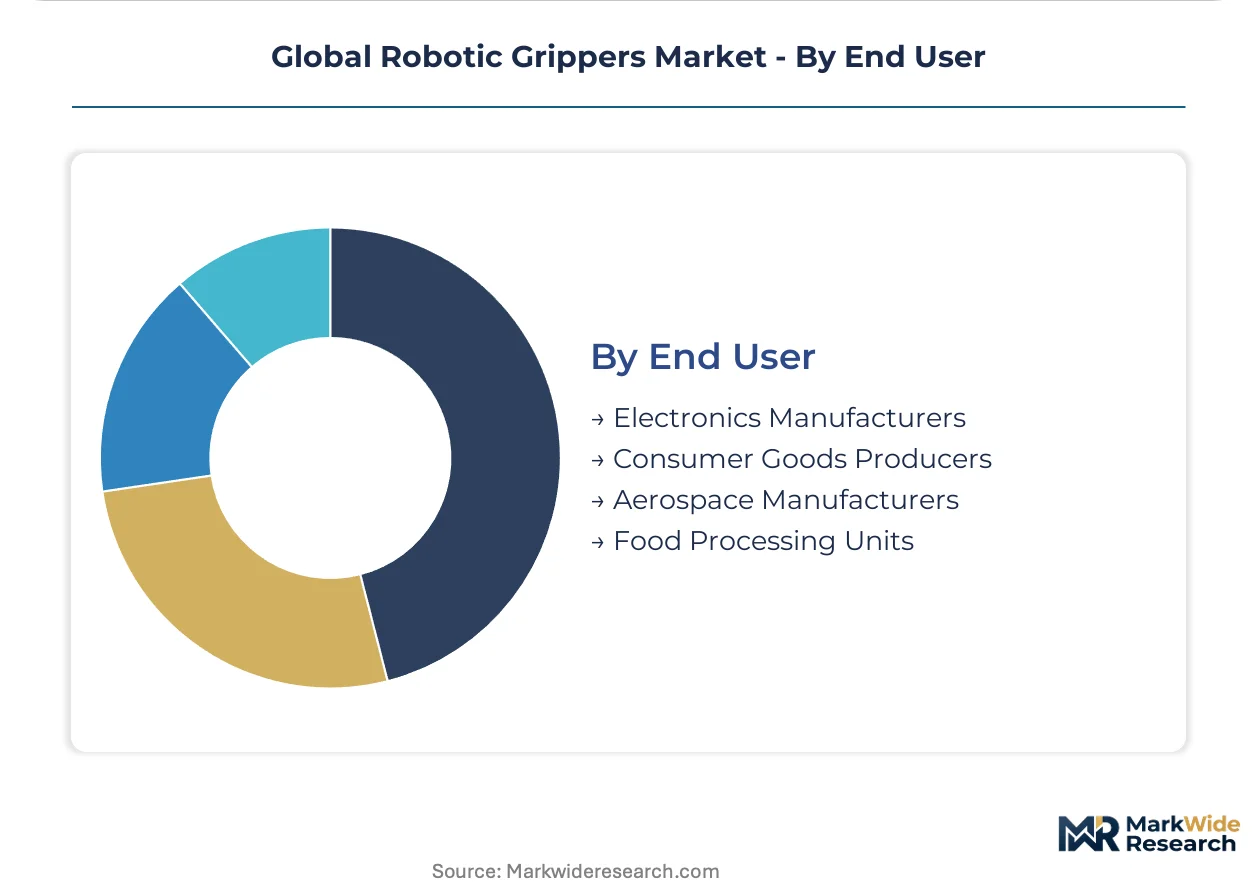
End User:
Different industry verticals have distinct requirements for robotic grippers, influencing design and market adoption.
- Food Processing Units:These require hygienic, washdown-capable grippers, often soft or vacuum-based, to handle delicate and irregularly shaped food items. Demand for these grippers is a primary growth catalyst.
- Electronics Manufacturers:Precision, anti-static, and small-footprint grippers are essential for assembling micro-components and handling sensitive circuit boards. Southeast Asian manufacturing hubs utilize these for high-volume production.
- Consumer Goods Producers:Grippers in this sector manage a wide variety of product sizes and packaging types, from personal care items to household goods. Flexible and adaptive grippers support diverse product lines.
- Aerospace Manufacturers:Large, robust grippers capable of handling heavy and often uniquely shaped components are critical for aircraft assembly. Specialized solutions address the demanding material properties and scale of aerospace parts.
Food processing units are driving new gripper designs, and electronics manufacturing continues as a core end-use segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global robotic grippers market exhibits a dynamic trade balance, where advanced manufacturing nations often lead in technology exports while emerging economies represent significant import opportunities for automation solutions. This interplay shapes regional demand patterns and supply chain configurations for end-of-arm tooling.
Germany
Germany’s advanced manufacturing sector drives demand for high-precision electric grippers in automotive and electronics assembly. The mandatory CE marking ensures integrated safety features for human-robot collaboration in production environments. Munich and Stuttgart, with their strong automotive clusters, concentrate demand for sophisticated gripping technologies.
United States
Logistics and e-commerce fulfillment operations in the United States fuel demand for adaptive and AI-integrated grippers for handling varied package sizes. OSHA standards guide the deployment of collaborative robotic systems, emphasizing worker safety in shared workspaces. The Midwest manufacturing belt and tech hubs like Silicon Valley require advanced automation solutions.
Japan
Japan's industrial automation sector requires ultra-high precision grippers for micro-manipulation in electronics and medical device manufacturing. The Ministry of Economy, Trade and Industry (METI) promotes robotics innovation, encouraging advanced end-effector development. Tokyo and Osaka's industrial zones are central to the adoption of piezoelectric and electrostatic gripping technologies.
China
China's vast electronics manufacturing and logistics sectors drive substantial demand for high-volume, cost-effective robotic grippers. The MIIT (Ministry of Industry and Information Technology) supports the development of domestic robotics capabilities through various industrial policies. Shenzhen and the Yangtze River Delta are major centers for gripper deployment in factory automation.
India
India's expanding automotive and consumer goods industries generate demand for robust material handling and packaging grippers. The Production Linked Incentive (PLI) scheme encourages domestic manufacturing, fostering automation adoption across various sectors. Bangalore and Pune, as emerging manufacturing and tech hubs, show increasing integration of robotic grippers.
Global Robotic Grippers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on niche end-of-arm tooling innovations. The market structure is bifurcated between established industrial automation giants and agile, specialized gripper manufacturers. Strategic archetypes include diversified automation providers, collaborative robotics specialists, and application-specific solution developers. Dominant competitive moves involve extensive R&D investments in new gripping technologies and strategic partnerships to expand integration capabilities.
Established industrial automation firms, such as SCHUNK GmbH And Co KG, exemplify the archetype of providers offering specialized, high-performance gripping solutions for demanding industrial applications. These companies often leverage deep engineering expertise to sustain their market position in traditional manufacturing sectors. OnRobot A/S represents the collaborative robotics specialist, focusing on ease of integration and modularity specifically designed for fenceless environments and human-robot interaction. Festo SE And Co KG sits within the diversified automation provider segment, known for its extensive range of pneumatic and electric grippers that cater to broad industry needs, from high-speed pick-and-place to precision assembly tasks.
| Leading Market Players |
|---|
| SCHUNK GmbH And Co KG |
| Festo SE And Co KG |
| Zimmer Group |
| SMC Corporation |
| ATI Industrial Automation |
| Schmalz GmbH |
| OnRobot A/S |
| Robotiq Inc |
| Destaco LLC |
Cost & Logistics Intelligence
High utilization rates in specialized gripper manufacturing facilities influence both supplier behavior and pricing strategies for advanced robotic grippers. This dynamic shapes the availability and cost of high-precision end-of-arm tooling across diverse industrial applications.
Pricing Analysis
Industrial OEM buyers anchor the pricing structure for robotic grippers, often securing long-term contracts for high-volume purchases. Price differentiation stems from the precision required for tasks like micro-manipulation and the level of customization for application-specific solutions. Pricing softness in the entry-level segment reflects competition from simpler alternatives and the emergence of Robotics-as-a-Service models. Small and medium-sized enterprises exhibit greater price sensitivity compared to large industrial automation firms investing in specialized, high-performance gripping technologies.
Supply Chain Analysis
Single-source vulnerability for specialized components, such as piezoelectric materials and advanced micro-actuators, presents a structural risk in the gripper supply chain. Geographic supply concentration includes Germany for high-precision manufacturing, China for cost-effective volume production, and Japan for ultra-high precision components. Raw material dependencies involve specialized polymers for soft grippers and sensor components for intelligent systems. Distribution runs through direct sales channels to large industrial clients and extensive integrator networks for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic grippers market is an early-cycle expansion story, buoyed by the maturation of collaborative robot safety standards enabling wider deployment.
For Market Incumbents: Pre-empt agile specialists by accelerating R&D in next-generation sensory and adaptive gripping technologies. Invest in advanced materials for soft robotics to address delicate handling tasks and acquire niche software integration firms. Leverage existing customer relationships and global distribution networks to counter disruption from new RaaS models. Focus R&D on solutions for demanding applications where high-performance gripping remains critical.
For New Entrants and Emerging Players: Pursue underpenetrated segments like pharmaceutical and lab automation with precise, sterile gripping solutions. Target e-commerce fulfillment with AI-integrated vision systems for adaptive picking of unsorted objects. Small and medium-sized enterprises (SMEs) represent a penetrable segment, particularly those seeking asset-light automation. Offer subscription-based Robotics-as-a-Service (RaaS) models with simplified integration to gain market share.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators offering comprehensive Robotics-as-a-Service solutions. The long-term viability stems from increasing automation demand across diverse industries and the ongoing need for specialized end-of-arm tooling. Companies specializing in AI-integrated vision systems or advanced soft robotics represent attractive acquisition targets. Watch for widespread adoption of universal communication protocols as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (AI-Integrated Grippers) | Enhances adaptive picking capabilities for unsorted objects in logistics. |
| Strategic Partnership (with RaaS providers) | Expands market access for gripper solutions without significant capital expenditure. |
| Capacity Expansion (in specialized materials) | Addresses growing demand for soft grippers in delicate food handling. |
| Acquisition of Specialist Firm (in piezoelectric tech) | Strengthens ultra-high precision offerings for micro-manipulation in electronics. |
| Certification Investment (ISO/TS 15066 compliance) | Enables fenceless operation and direct human-robot collaboration on production lines. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews, complemented by robust secondary validation. Stakeholders included plant engineers, automation integrators, R&D directors, and procurement managers across Germany and Southeast Asia. Secondary sources comprised industry association reports, company financial filings, machinery safety standards like ISO/TS 15066, and trade publications. A bottom-up data aggregation and top-down market sizing approach ensured comprehensive market coverage.
The analytical framework calibration involved cross-referencing historical market data with current industry trends over the projection horizon. Segmentation dimensions included product type, technology, application, end-user industry, and regional manufacturing output. Compound annual growth rates were derived from a blend of historical performance and projected adoption rates. Key inputs included robot installation rates and industrial production indices across major manufacturing hubs.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or labor costs would shift the trajectory of gripper deployment. Forecasts reflect documented assumptions regarding technological advancements and regulatory stability. Geopolitical shifts and rapid technological obsolescence represent specific risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Dispensing Robots Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Germany Cloud Robotics Market
Robotics and Automation
Metal Fabrication Robots Market