
 Wearable Physiotherapy Market | 2026-2036
Wearable Physiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Physiotherapy Market Insights
Subscription-based remote monitoring and software-defined exercise prescription is hardening into the core revenue architecture for wearable physiotherapy vendors. Medtronic plc leverages its cardiac rehabilitation telemetry infrastructure to anchor remote musculoskeletal programs. Stryker Corporation sustains institutional sales through its surgical-to-rehabilitation continuum in hospital systems. Hinge Health Inc. specializes in employer-direct digital physical therapy, competing on outcomes-based contracts rather than device margins.
Wearable physiotherapy devices integrate motion sensors, surface electromyography, and haptic feedback mechanisms to deliver quantified rehabilitation protocols outside clinical settings. These systems typically operate at sampling frequencies of 100-1000 Hz for kinematic data, with Bluetooth Low Energy transmission to cloud-based clinician dashboards for asynchronous oversight. Exoskeletons occupy the highest capital tier within product type segmentation, while smartbands capture volume through direct-to-consumer and insurer-subsidized channels. Neuromuscular therapy applications lead clinical adoption, though pain management represents the fastest-expanding reimbursement category as payers seek alternatives to opioid prescribing.
The FDA software-as-a-medical-device framework and HIPAA interoperability standards jointly determine which connected physiotherapy platforms gain market access in the United States. ISO 13485 quality management and IEC 60601 electrical safety certifications serve as baseline thresholds for CE-marked entry into European rehabilitation markets. Stakeholders must monitor whether emerging FDA guidance on artificial-intelligence-enabled therapeutic algorithms will require additional clinical validation layers for adaptive exercise prescription systems.
Market Dynamics
Subscription revenue architecture is compressing hardware margins while elevating software-defined exercise prescription as the dominant value capture mechanism in wearable physiotherapy. This structural shift forces vendors to reorient from device sales toward longitudinal patient engagement models.
Growth Catalysts
- Medicare reimbursement expansion:CMS pathways for digital therapeutics now cover remote musculoskeletal monitoring, accelerating provider adoption of connected rehabilitation platforms in the United States.
- Employer-sponsored musculoskeletal programs:Self-insured employers in the United States are consolidating vendor relationships around outcomes-based contracts that bundle wearable hardware with virtual physical therapy delivery.
- Surface electromyography miniaturization:Advances in sEMG sensor fabrication are enabling real-time neuromuscular feedback in consumer-accessible form factors, expanding clinical-grade monitoring beyond institutional settings.
Market Restraints
- FDA software-as-a-medical-device validation costs:Pre-market submission requirements for adaptive exercise algorithms impose six-figure compliance burdens that disadvantage early-stage hardware vendors.
- Bluetooth Low Energy transmission latency:Kinematic data sampling at 100-1000 Hz creates bandwidth constraints for real-time haptic feedback in high-motion rehabilitation protocols.
- Lithium-polymer battery supply concentration:Cell manufacturing for wearable exoskeletons concentrates in East Asian suppliers, exposing procurement to geopolitical friction and input cost volatility.
Strategic Opportunities
- Pain management reimbursement category:Payer alternatives to opioid prescribing are opening dedicated billing codes for wearable-delivered therapeutic interventions in the United States.
- Haptic feedback convergence with augmented reality:Spatial computing platforms are creating immersive rehabilitation environments that integrate force-feedback wearables with visual motor guidance.
- Sports medicine clinic channel expansion:Remote patient monitoring protocols are penetrating athletic training facilities that previously relied on in-person physical therapy staffing.
Industry Challenges
- ISO 13485 quality management certification timelines:European market entry requires 12-18 month implementation cycles for connected therapeutic hardware, compressing competitive response windows.
- HIPAA interoperability standard fragmentation:Cloud-based clinician dashboards face integration complexity with legacy electronic health record systems that lack standardized application programming interfaces.
- Clinical validation talent scarcity:Biomechanics engineers with regulatory submission experience command premium compensation, constraining vendor scaling velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Physiotherapy Market |
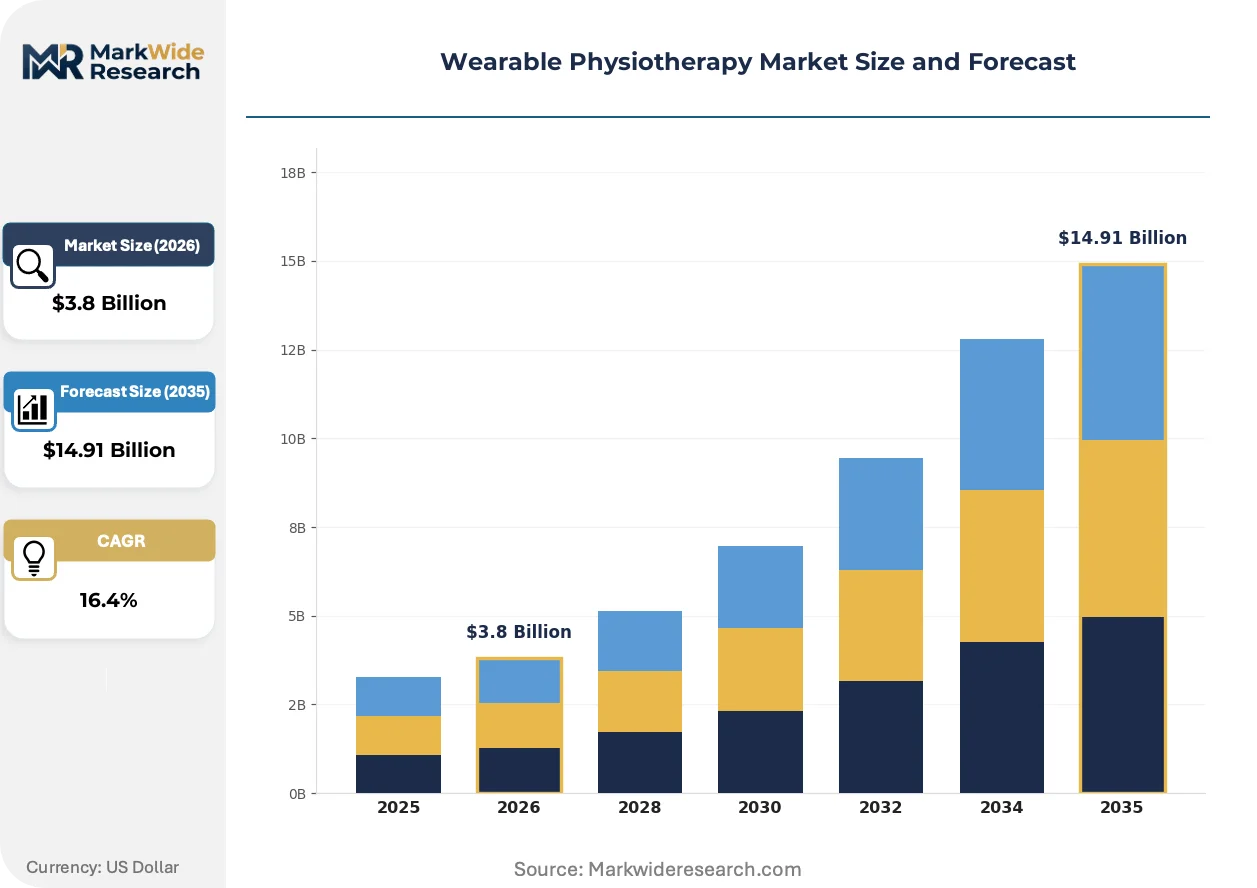
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartbands, Smartwatches, Sensors, Exoskeletons Technology: Bluetooth, Wi-Fi, RFID, NFC End User: Patients, Physiotherapists, Hospitals, Rehabilitation Centers Application: Neuromuscular Therapy, Pain Management, Mobility Improvement, Posture Correction |
| Companies Covered | Medtronic plc, Stryker Corporation, Zimmer Biomet Holdings Inc., Omron Healthcare Co. Ltd., Garmin Ltd., Hinge Health Inc., Sword Health Inc., Bioness, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Physiotherapy Market Trends and Innovations
Adaptive exercise prescription algorithms are displacing static rehabilitation protocols, creating feedback loops between patient movement data and real-time therapeutic adjustment. This convergence of artificial intelligence with biomechanical sensing is redefining clinical oversight models.
Machine learning inference at the edge is integrating motion pattern recognition directly into wearable processors, reducing cloud dependency for latency-sensitive haptic guidance. Sports medicine clinics are piloting these systems for asynchronous athlete monitoring between in-person consultations. The structural consequence is compressing the traditional physical therapy visit cadence while extending revenue capture across longer patient relationships.
The FDA's evolving guidance on artificial-intelligence-enabled therapeutic algorithms is tightening clinical validation requirements for adaptive exercise prescription systems. Hardware vendors must now submit prospective trial data demonstrating non-inferiority to supervised rehabilitation protocols. Exoskeleton manufacturers face the most acute compliance burden, as their higher-risk classification triggers pre-market approval pathways rather than 510(k) clearance.
Self-insured employers are consolidating vendor relationships around outcomes-based contracts that tie reimbursement to functional improvement metrics rather than device deployment. This procurement compression favors platforms with longitudinal data infrastructure over point-solution hardware vendors. The United States exhibits the most pronounced shift, where employer-sponsored musculoskeletal programs now represent the fastest-growing reimbursement channel for digital physical therapy.
Wearable Physiotherapy Market Segmentation
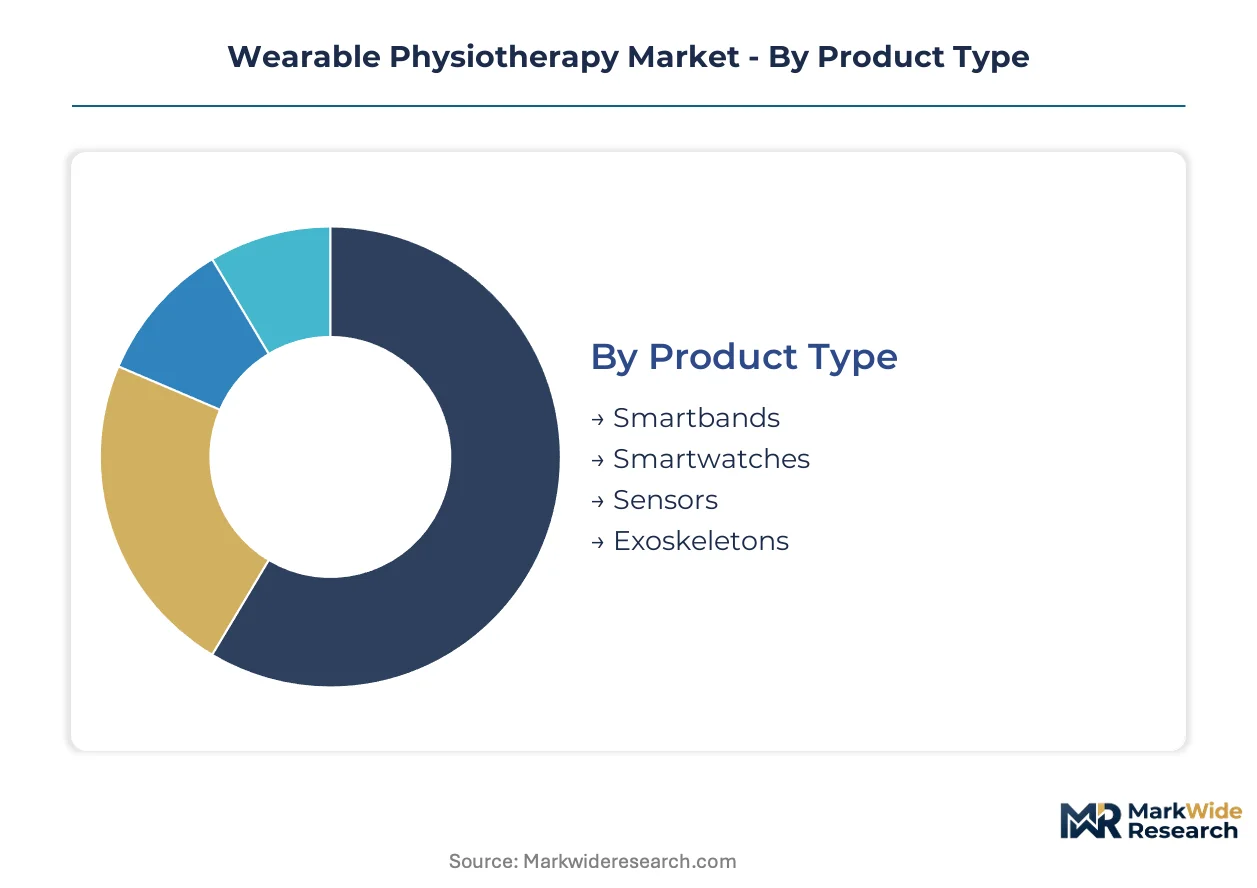
Segmentation in wearable physiotherapy reveals how capital requirements, reimbursement pathways, and clinical validation burdens concentrate differently across hardware tiers and connectivity architectures. Vendors must align product portfolios with the specific procurement channels and regulatory thresholds governing each segment.
Product Type:
Capital intensity stratifies sharply across this category, with powered exoskeletons demanding multimillion-dollar R&D cycles while disposable sensor patches require minimal fixed asset deployment.
- Smartbands:Fabric-based or silicone-encased wrist/ankle units integrating accelerometers and gyroscopes for kinematic tracking. Employer-sponsored musculoskeletal programs in the United States are consolidating procurement around these devices for remote workforce monitoring, driven by outcomes-based contract structures that penalize clinical inertia.
- Exoskeletons:Motorized orthotic frames with torque-actuated joints that provide active assistance during gait rehabilitation. FDA pre-market approval pathways impose the steepest compliance costs here, limiting viable competitors to capitalized medical device conglomerates with existing orthopedic portfolios.
- Smartwatches:Consumer electronics form factors with FDA-cleared rehabilitation software overlays. Apple and Samsung device ecosystems are absorbing clinical-grade functionality through third-party app validation.
- Sensors:Disposable or reusable surface electromyography and inertial measurement units for temporary deployment. Sports medicine clinics favor these for asynchronous athlete monitoring between competition seasons.
Exoskeletons absorb the bulk of installed capacity in institutional rehabilitation settings; smartbands are expanding most quickly through employer-direct and insurer-subsidized channels.
Technology:
Connectivity architecture determines latency tolerance for real-time haptic feedback and the regulatory surface area for data transmission security.
- Bluetooth:Low Energy protocols dominate consumer-accessible devices with 100-1000 Hz kinematic sampling. Bandwidth constraints at high motion velocities limit real-time therapeutic adjustment in exoskeleton applications.
- Wi-Fi:Higher throughput enables cloud-dependent machine learning inference for adaptive exercise prescription. Hospital systems mandate enterprise-grade encryption that consumer Wi-Fi chipsets often fail to satisfy.
- RFID:Passive tracking for inventory management and patient identification in high-throughput rehabilitation centers. No real-time biomechanical data transmission capability restricts clinical utility.
- NFC:Proximity-based pairing and authentication for multi-patient device sanitization protocols. European rehabilitation networks are piloting NFC for GDPR-compliant patient consent workflows.
Bluetooth carries the highest shipment volumes; Wi-Fi is climbing the fastest as cloud-based clinician dashboards displace local processing.
End User:
Procurement authority and reimbursement access fragment across clinical versus non-clinical settings, reshaping sales motion requirements.
- Patients:Direct-to-consumer purchasers paying out-of-pocket or through health savings accounts. Amazon and specialty medical device retailers are consolidating this channel around sub-$500 price points.
- Physiotherapists:Independent practitioners prescribing remote monitoring as billable service extensions. United States Medicare reimbursement for digital therapeutics is accelerating platform adoption in this segment.
- Hospitals:Integrated delivery networks with capital equipment committees and value-analysis teams. Stryker and Medtronic leverage existing vendor credentialing to bypass lengthy procurement cycles.
- Rehabilitation Centers:Dedicated post-acute facilities with higher patient throughput and standardized protocols. Hinge Health and competing platforms are displacing in-person staffing ratios through asynchronous oversight tools.
Hospitals command the largest average contract values; physiotherapists are gaining share fastest as solo practitioners consolidate around virtual care platforms.
Application:
Reimbursement category maturity determines addressable market expansion, with emerging billing codes outpacing established clinical workflows.
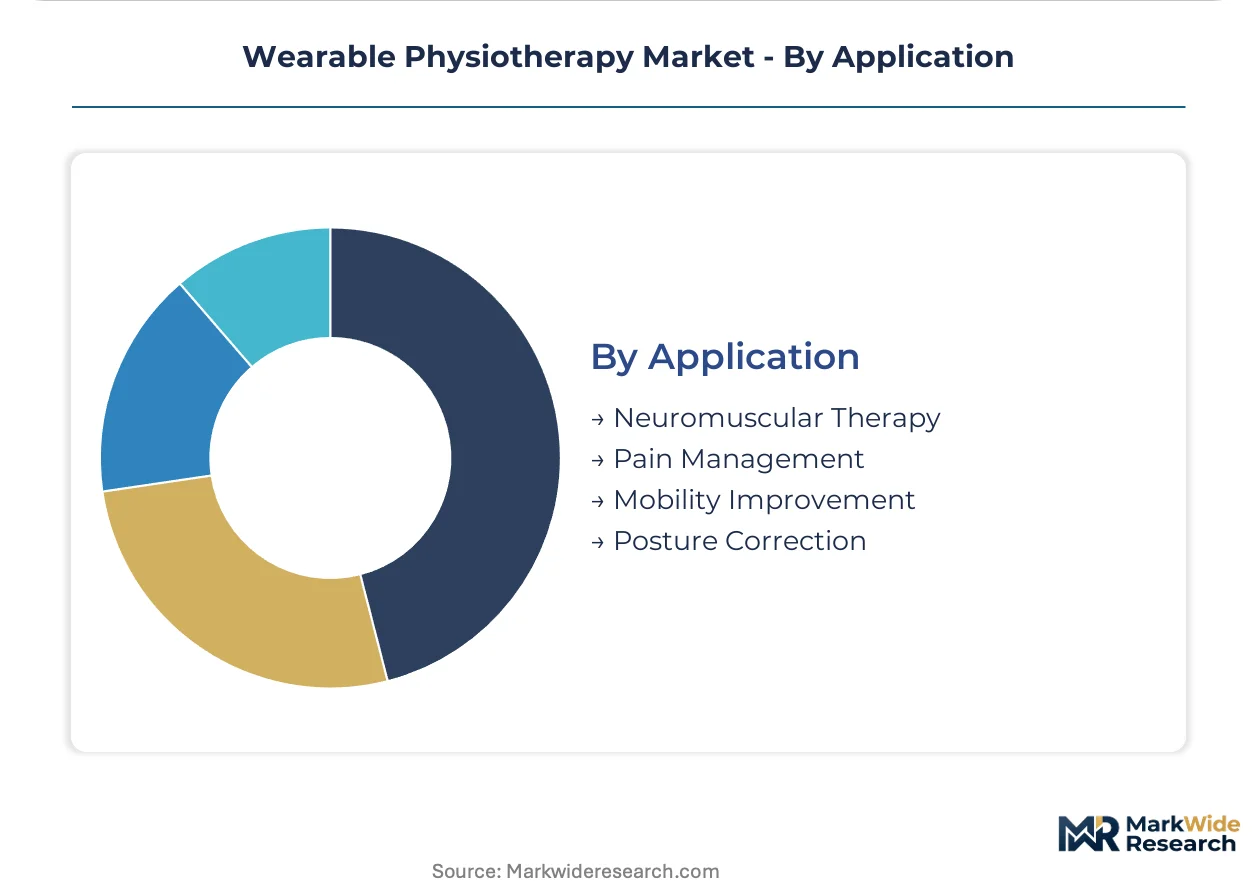
- Neuromuscular Therapy:Surface electromyography-guided motor relearning for stroke and spinal cord injury recovery. CMS coverage determinations in the United States have stabilized reimbursement for remote neurorehabilitation monitoring.
- Pain Management:Wearable-delivered transcutaneous electrical nerve stimulation and movement-based desensitization protocols. Payer alternatives to opioid prescribing are opening dedicated billing codes fastest in this category.
- Mobility Improvement:Gait training and fall risk reduction for geriatric populations. Japan's aging demographic is concentrating demand here through Ministry of Health, Labour and Welfare subsidized device procurement.
- Posture Correction:Haptic feedback for occupational musculoskeletal injury prevention. Employer wellness programs are absorbing these devices as loss-control investments rather than clinical interventions.
Neuromuscular therapy retains the deepest reimbursement infrastructure; pain management is expanding most quickly as regulatory pressure on opioid prescribing intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production concentrates in East Asian manufacturing clusters while consumption tilts toward Western reimbursement markets. The United States absorbs the largest share of subscription revenue for remote physiotherapy platforms. Germany and Japan anchor institutional procurement of capital-intensive exoskeleton systems.
United States
Employer-sponsored musculoskeletal programs and Medicare reimbursement for digital therapeutics drive procurement volume. FDA software-as-a-medical-device validation requirements shape which connected platforms gain market access. The Boston-Cambridge corridor hosts multiple venture-backed digital physical therapy ventures developing adaptive exercise algorithms.
Germany
Statutory health insurance digitization initiatives accelerate remote rehabilitation monitoring adoption in post-acute care. CE marking under EU MDR and ISO 13485 quality management certifications govern hardware market entry. The Baden-Württemberg medical technology cluster around Tübingen and Freiburg concentrates exoskeleton development and sEMG sensor fabrication.
Japan
Ministry of Health, Labour and Welfare subsidized device procurement addresses mobility improvement demand from an aging demographic. PMDA regulatory pathways for therapeutic software overlays on consumer wearables are tightening clinical evidence requirements. The Kansai region around Osaka anchors rehabilitation robotics manufacturing partnerships between medical device conglomerates and precision motor suppliers.
China
NMPA approval timelines for Class II therapeutic wearables are compressing as domestic manufacturers scale production. National reimbursement catalog expansion for digital health services is piloting in Shanghai and Beijing. The Yangtze River Delta manufacturing belt around Suzhou and Hangzhou dominates lithium-polymer cell supply and Bluetooth module assembly for export markets.
United Kingdom
NHS Long Term Plan targets for musculoskeletal pathway redesign are embedding remote monitoring into community rehabilitation services. MHRA convergence with EU MDR post-Brexit creates dual certification burdens for hardware vendors. London-based health technology assessment bodies are developing outcomes frameworks for employer-subsidized digital physical therapy procurement.
Wearable Physiotherapy Market Competitive Landscape
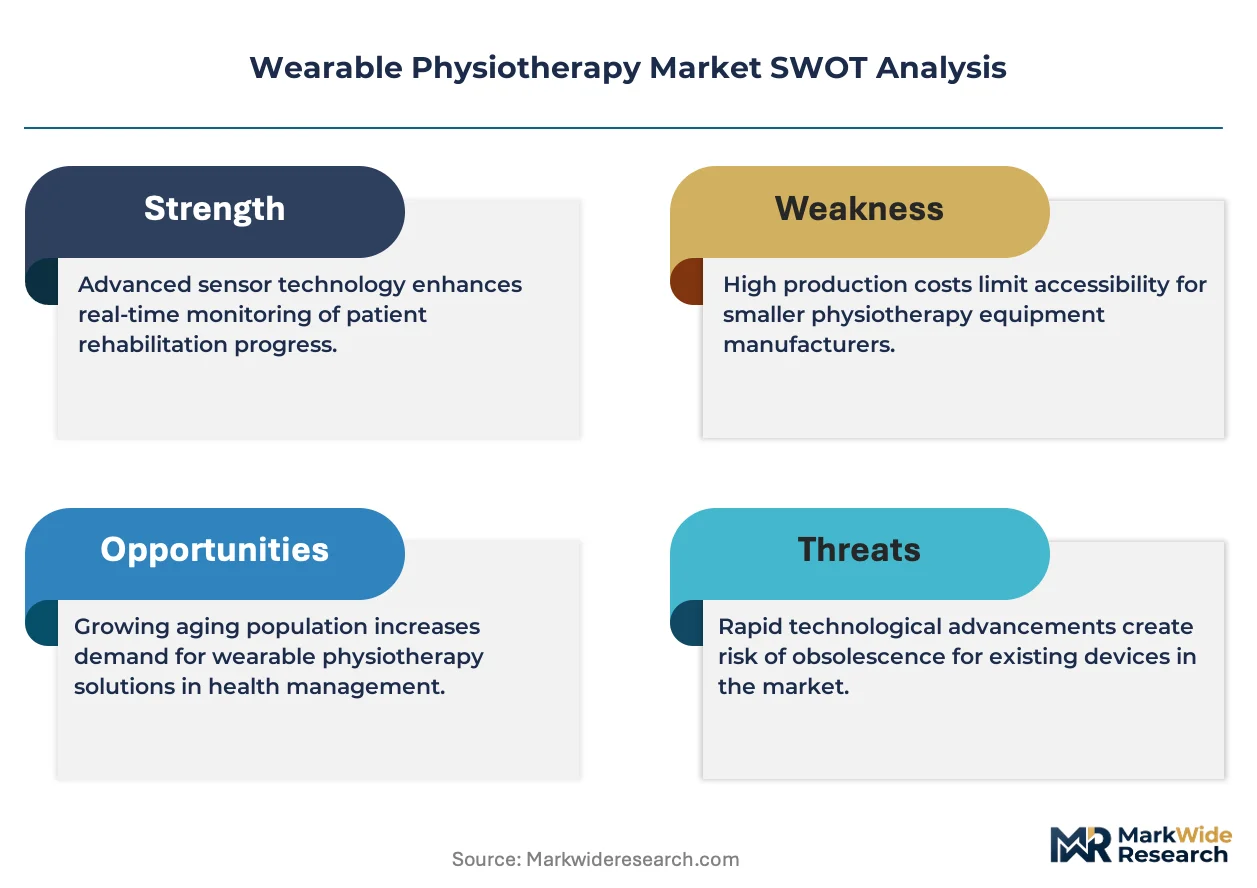
Capital-heavy medical device conglomerates compete with asset-light digital health platforms for patient relationship ownership. The market exhibits tiered consolidation: orthopedic hardware majors leverage institutional vendor credentialing, while virtual care specialists capture employer-direct contracts through outcomes-based pricing. Three archetypes dominate—surgical-to-rehabilitation continuum integrators, employer-focused digital physical therapy platforms, and consumer electronics ecosystems absorbing clinical functionality. Dominant competitive moves include strategic partnerships with self-insured employers and portfolio diversification into remote monitoring software.
Within the surgical-to-rehabilitation tier, Medtronic plc and Stryker Corporation exemplify capitalized conglomerates extending orthopedic footprints into longitudinal patient management. Hinge Health Inc. occupies a distinct position among asset-light platforms competing on functional outcome guarantees rather than device margins. Zimmer Biomet Holdings Inc. represents mid-scale specialists navigating between hardware manufacturing heritage and software-defined service expansion.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Zimmer Biomet Holdings Inc. |
| Omron Healthcare Co. Ltd. |
| Garmin Ltd. |
| Hinge Health Inc. |
| Sword Health Inc. |
| Bioness |
| Getinge |
| Others |
Pricing and Supply Chain Analysis
Surface electromyography miniaturization and edge computing integration are compressing component costs while concentrating procurement leverage among East Asian sensor foundries, simultaneously reshaping cost economics and supply concentration. This dual transformation forces vendors to navigate pricing power erosion in hardware tiers against software-defined margin expansion.
Pricing Analysis
Margin tightening in exoskeleton tiers reflects FDA pre-market approval validation burdens that capitalized conglomerates absorb more readily than emerging hardware vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and after-sales service bundling. Cost-down pressure on smartband tiers accelerates because employer-sponsored programs consolidate procurement around outcomes-based contracts. Physiotherapist-directed channels exhibit highest price sensitivity; hospital capital equipment committees demonstrate lowest sensitivity due to vendor credentialing lock-in.
Supply Chain Analysis
Domestic-content mandates in China's NMPA procurement guidelines are reshaping sourcing patterns for lithium-polymer cells and Bluetooth module assembly. Supply concentrates in China, South Korea, and Japan for motion sensors, surface electromyography electrodes, and torque-actuated joint motors. Raw material dependencies center on rare-earth magnets, medical-grade silicone substrates, and high-density energy storage cells. Single-source vulnerability in East Asian cell manufacturing exposes procurement to geopolitical friction. Distribution runs through hospital system value-analysis committees, employer benefits platforms, and direct-to-consumer medical device retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into longitudinal patient data infrastructure is becoming the decisive competitive lever as subscription revenue architectures displace transactional hardware margins.
For Market Incumbents: Deploy adaptive exercise algorithm development to defend against asset-light digital platforms encroaching on employer-direct contracts. Deepen ISO 13485 certification investment to accelerate European market entry ahead of EU MDR enforcement timelines. Consolidate channel control through exclusive hospital system partnerships that lock out emerging competitors from vendor credentialing databases.
For New Entrants and Emerging Players: Launch via sports medicine clinic remote monitoring protocols, the most penetrable channel as athletic training facilities displace in-person physical therapy staffing. Target pain management reimbursement categories where payer alternatives to opioid prescribing are opening dedicated billing codes fastest. Pursue surface electromyography miniaturization partnerships with East Asian sensor foundries to bypass capital-intensive R&D cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by surgical-to-rehabilitation continuum integrators seeking longitudinal patient relationship ownership. Long-term viability hinges on platforms demonstrating functional outcome guarantees rather than device shipment volumes. Watch FDA guidance on artificial-intelligence-enabled therapeutic algorithms as the critical inflection indicator for adaptive exercise prescription system valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Pre-market validation unlocks Medicare reimbursement pathways for remote musculoskeletal monitoring platforms. |
| CE Marking Pathway under EU MDR | ISO 13485 certification enables statutory health insurance digitization initiatives in German post-acute care markets. |
| Hospital System Partnership | Vendor credentialing bypass accelerates procurement cycles for capital-intensive exoskeleton deployments. |
| Software Companion Development | Adaptive exercise algorithms differentiate subscription pricing against static rehabilitation protocol competitors. |
| Reimbursement Strategy | Employer-sponsored musculoskeletal program consolidation favors outcomes-based contract structures. |
Research Methodology
Document review covered FDA 510(k) and pre-market approval filings, CMS national coverage determinations, and EU MDR technical documentation, complemented by interviews with biomedical engineers, hospital GPO contracts managers, digital health platform executives, and rehabilitation center clinical directors. Secondary validation drew from SEC 10-K disclosures, hospital procurement databases, and employer benefits platform vendor rosters. Bottom-up shipment modeling and top-down reimbursement expenditure analysis were triangulated to cross-validate market sizing.
Segmented outputs across the projection horizon reflect product type stratification, connectivity architecture differentiation, end-user procurement authority fragmentation, and application-specific reimbursement maturity. CAGRs were derived from time-series analysis of digital therapeutic adoption curves and Medicare billing code expansion trajectories. Forecast inputs incorporated surface electromyography sensor cost curves and employer-sponsored program penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for edge-based machine learning inference would alter the outlook for cloud-dependent platform economics. Forecasts reflect assumptions regarding FDA software-as-a-medical-device guidance evolution and employer benefits consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Pedometer Market