
 Hip Kits Market | 2026-2036
Hip Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Hip Kits Market Foresight
Multi-source procurement for implant components is consolidating among tier-one orthopedic suppliers as hospitals seek supply security. Stryker Corporation leverages integrated manufacturing networks across North America and Europe to sustain kit availability. Smith & Nephew anchors its position through specialized hip resurfacing portfolios that compete on bone-preserving outcomes. Zimmer Biomet Holdings dominates robotic-assisted procedure kits, extending its technology leadership into ambulatory settings.
Hip kits are sterile, procedure-specific assemblies containing femoral stems, acetabular cups, impactors, reamers, and trial implants engineered from cobalt-chrome alloys or titanium with polyethylene liners, designed to enable total or partial hip arthroplasty in operating theaters. The hip replacement kit segment leads volume due to established clinical pathways and broad surgeon familiarity, while robotic-assisted surgery technology commands premium positioning as hospitals amortize capital equipment through higher kit attach rates. Minimally invasive surgery approaches are gaining fastest in ambulatory surgical centers where reduced tissue disruption supports same-day discharge protocols.
The FDA's 510(k) clearance framework and EU MDR conformity requirements shape product development timelines and commercial access for hip kit manufacturers across their primary markets. ISO 13485 quality management standards and ASTM F138 material specifications further constrain supplier qualification, favoring incumbents with established regulatory infrastructure. Stakeholders must monitor reimbursement shifts toward outpatient hip replacement and the pace of ASC credentialing expansion as signals of where kit demand will migrate next.
Market Dynamics
The migration of hip arthroplasty into ambulatory surgical centers is compressing procedure timelines and forcing kit manufacturers to redesign packaging, sterilization protocols, and inventory models for decentralized settings.
Growth Catalysts
- EU MDR conformity pathways:Streamlined device certification for hip implant kits is accelerating market access for qualified suppliers across European orthopedic networks.
- Robotic-assisted surgical platforms:Capital equipment investments by United States hospital systems are creating attach-rate pull for compatible instrument kits.
- Titanium alloy supply networks:North American raw material sourcing concentration is stabilizing femoral stem production costs for tier-one manufacturers.
Market Restraints
- Cobalt-chrome price volatility:Mining concentration in Central Africa creates input cost instability for bearing surface components.
- FDA 510(k) notification backlog:Premarket review timelines for modified acetabular cup designs extend commercialization cycles by 8-14 months.
- Polyethylene liner substitution:Ceramic-on-ceramic bearing systems are displacing traditional metal-polyethylene constructs in premium joint reconstruction segments.
Strategic Opportunities
- Outpatient procedure migration:United States ASC credentialing expansion creates white-space demand for compact, same-day-discharge kit configurations.
- ISO 13485 certification acceleration:Quality management infrastructure investments unlock contract manufacturing partnerships with established orthopedic OEMs.
- Digital surgical planning convergence:Preoperative templating software integration with implant sizing databases is enabling patient-specific kit preconfiguration.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization study bottlenecks delay new material introductions.
- Legacy ERP integration:ASC inventory management systems require custom API development for real-time kit consumption tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hip Kits Market |
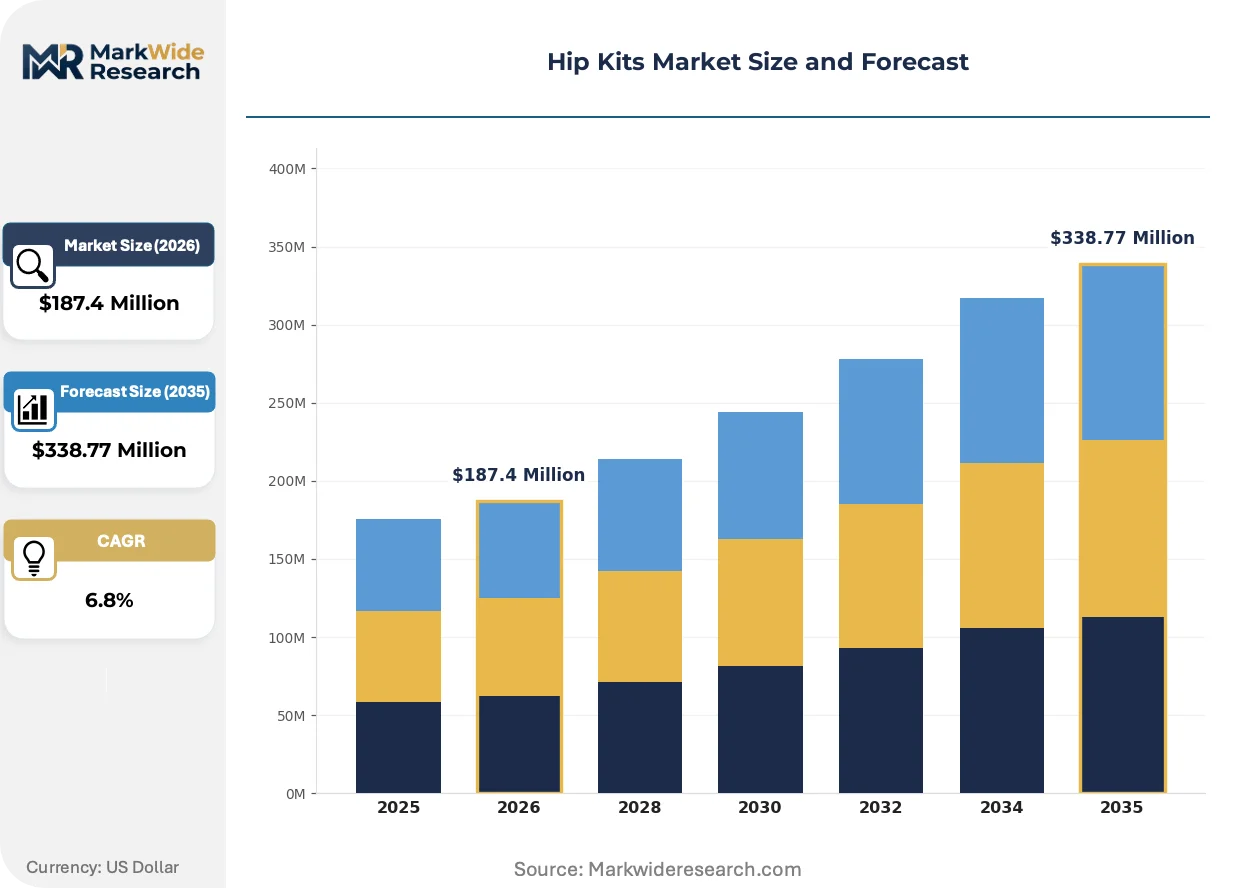
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hip Replacement Kit, Hip Resurfacing Kit, Orthopedic Instruments, Surgical Approaches End User: Hospitals, Clinics, Rehabilitation Centers, Ambulatory Surgical Centers Technology: Minimally Invasive Surgery, Robotic-assisted Surgery, Conventional Surgery, Navigation Systems Application: Trauma Management, Joint Reconstruction, Pain Management, Rehabilitation |
| Companies Covered | Stryker Corporation, Smith & Nephew, BodyHealt, Medi Touch Limited, Surgitech, Orthomax India, Zimmer Biomet Holdings, DJO Global, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hip Kits Market Shifts & Advancements
Orthopedic kit engineering is pivoting toward modularity and digital traceability as procedural settings fragment across hospital campuses and standalone surgical facilities.
Robotic navigation systems for hip arthroplasty are automating femoral stem positioning and acetabular cup alignment through intraoperative 3D mapping and haptic feedback controls. United States academic medical centers are deploying these platforms at scale, with community hospitals following at 18-24 month lag intervals. This automation is compressing operative time variability and reducing revision surgery rates, which in turn locks in kit standardization around manufacturer-specific instrument trays.
EU MDR Article 10 technical documentation requirements are mandating expanded clinical evidence and post-market surveillance for hip implant kits marketed in European Economic Area jurisdictions. Manufacturers must maintain systematic literature review protocols and periodic safety update reports across their entire implant portfolio. Small-to-mid tier suppliers without established regulatory affairs infrastructure are exiting the European market, consolidating commercial access among incumbents with dedicated MDR compliance teams.
Hospital supply chain directors are consolidating orthopedic kit procurement through single-source agreements that bundle implants, instruments, and disposable drapes under fixed per-procedure pricing. This model displaces traditional component-level purchasing through distributor networks. The shift is most visible in United States integrated delivery networks, where centralized value analysis committees now mandate standardization across 15-30 facility systems.
Hip Kits Market Segmentation
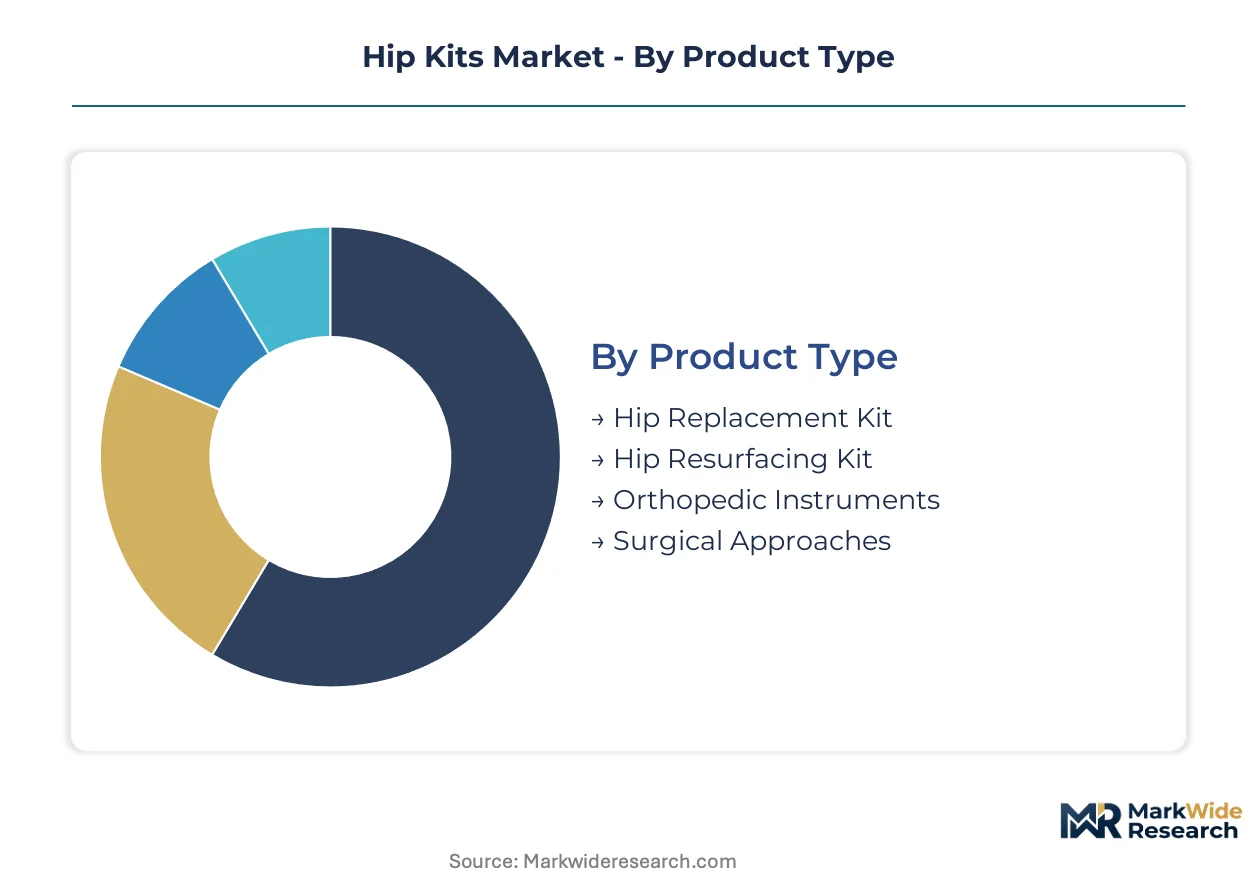
Segmentation in hip kits reflects divergent supply chain requirements across procedural settings. Manufacturers must configure kit contents, sterilization protocols, and instrument density differently for high-volume hospital systems versus dispersed ambulatory networks.
Product Type:
Standalone implant kits dominate procurement budgets, while embedded instrument systems lock in recurring revenue through proprietary compatibility requirements.
- Hip Replacement Kit:Complete sterile assemblies containing femoral stems, acetabular cups, polyethylene liners, and impactors engineered from cobalt-chrome or titanium alloys. United States integrated delivery networks concentrate procurement through single-source agreements that bundle implants with disposable drapes under fixed per-procedure pricing.
- Hip Resurfacing Kit:Bone-preserving constructs featuring metal-on-metal bearing surfaces and conservative femoral head preparation instruments. Demand clusters in European orthopedic networks where younger patient demographics and EU MDR conformity pathways favor revision-avoidance strategies.
- Orthopedic Instruments:Reusable reamers, broaches, and trial implants requiring sterilization validation cycles.
- Surgical Approaches:Procedure-specific instrument configurations for anterior, posterior, or lateral access techniques.
Volume placements concentrate in hip replacement configurations; the faster expansion belongs to resurfacing portfolios as bone-conserving techniques gain surgical acceptance.
End User:
Customer type determines kit complexity, with capital-rich institutions absorbing technology premiums and cost-constrained settings demanding stripped-down configurations.
- Hospitals:High-throughput orthopedic departments requiring comprehensive instrument trays with robotic navigation compatibility and dedicated sterilization infrastructure. United States academic medical centers deploy these platforms at scale, with community hospitals following at 18-24 month adoption intervals.
- Ambulatory Surgical Centers:Compact, same-day-discharge configurations with reduced instrument counts and disposable-heavy designs. United States ASC credentialing expansion is compressing procedure timelines and forcing manufacturers to redesign packaging and inventory models for decentralized settings.
- Clinics:Limited-procedure settings with outsourced sterilization and consignment inventory arrangements.
- Rehabilitation Centers:Post-acute facilities requiring pain management and mobility assessment tools rather than operative kits.
Procurement authority sits with hospital value analysis committees; the steepest expansion trajectory belongs to ambulatory surgical centers as outpatient hip migration accelerates.
Technology:
Technology tiering separates capital equipment-dependent platforms from manual techniques, creating divergent margin structures and replacement cycle dynamics.
- Robotic-assisted Surgery:Capital equipment investments by United States hospital systems create attach-rate pull for compatible instrument kits. Intraoperative 3D mapping and haptic feedback controls automate femoral stem positioning, compressing operative time variability and locking in kit standardization around manufacturer-specific trays.
- Minimally Invasive Surgery:Reduced tissue disruption approaches gaining fastest in ambulatory surgical centers where smaller incisions support same-day discharge protocols and lower postoperative complication rates.
- Conventional Surgery:Established manual techniques with broad surgeon familiarity and lower capital barriers.
- Navigation Systems:Computer-assisted alignment tools without robotic actuation, occupying a mid-tier price position.
Installed base concentrates in conventional techniques; premium positioning belongs to robotic platforms as hospitals amortize capital equipment through higher kit attach rates.
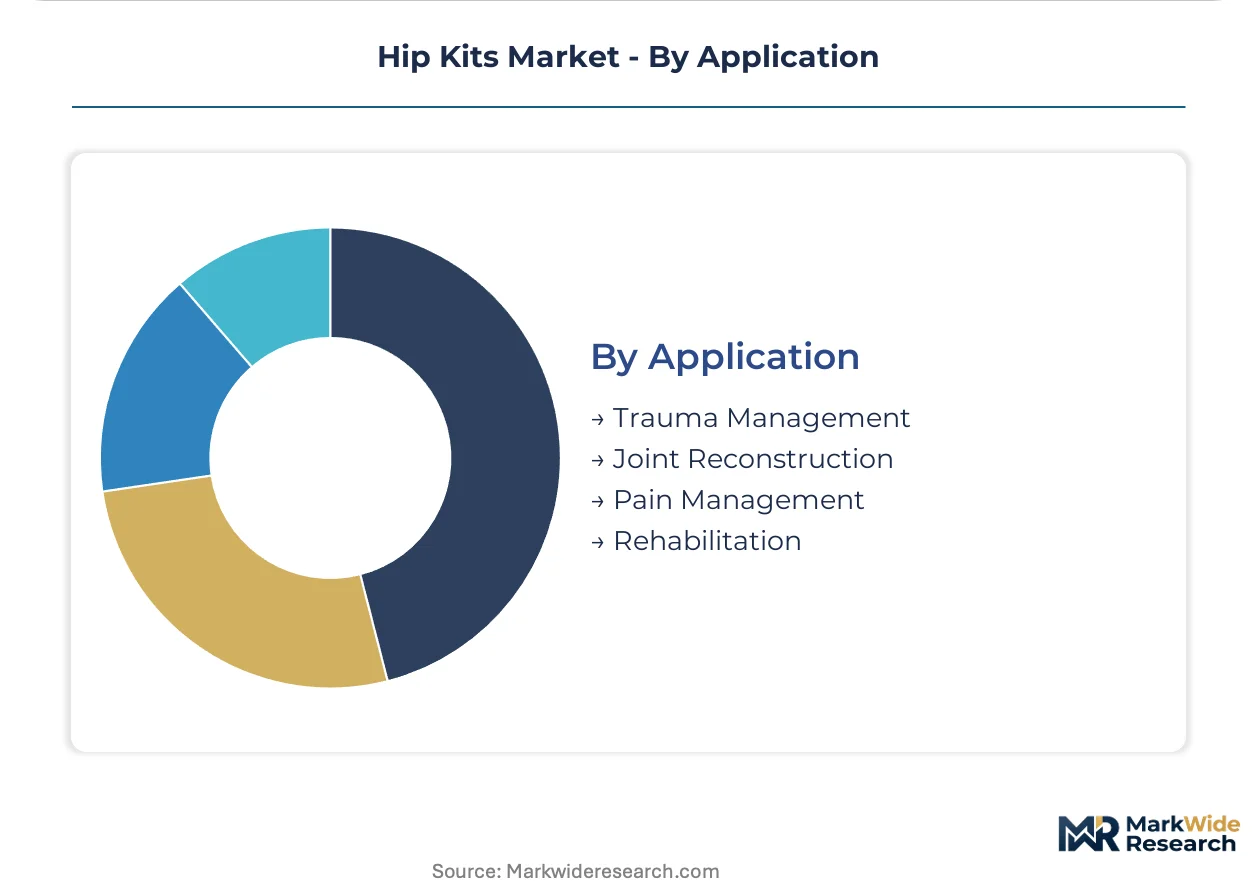
Application:
Application focus determines regulatory pathway complexity, with reconstructive indications demanding extensive clinical evidence and trauma applications requiring rapid deployment capabilities.
- Joint Reconstruction:Elective arthroplasty procedures with preoperative templating and patient-specific implant sizing. Digital surgical planning convergence with implant databases is enabling customized kit preconfiguration for complex deformity cases.
- Trauma Management:Acute fracture fixation requiring expedited kit availability and modular stem options for compromised bone quality.
- Pain Management:Diagnostic and therapeutic interventions preceding surgical candidacy determination.
- Rehabilitation:Postoperative mobility restoration protocols with limited kit content requirements.
Procedure volume clusters in joint reconstruction; regulatory investment intensity concentrates in trauma applications where FDA 510(k) notification backlogs extend commercialization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloy supply networks concentrate in North American and European metallurgical corridors, anchoring femoral stem production for hip kit manufacturers serving hospital systems and ambulatory surgical centers.
United States
Ambulatory surgical centers in Florida, Texas, and Arizona are driving outpatient hip arthroplasty migration with same-day discharge protocols. FDA 510(k) premarket notification requirements elevate qualification barriers for modified acetabular cup designs. The Southeast ASC cluster around Atlanta and Nashville is compressing procedure timelines and forcing kit redesigns for decentralized inventory models.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia deploy robotic navigation platforms for femoral stem positioning with 18-24 month adoption intervals reaching community hospitals. EU MDR Article 10 technical documentation mandates expanded clinical evidence for implant kits marketed across European Economic Area jurisdictions. The Stuttgart-Tübingen orthopedic corridor anchors precision instrument manufacturing for hip resurfacing portfolios.
Japan
Aging demographics in Kanto and Kansai regions sustain elective joint reconstruction volumes with preoperative templating integration. PMDA pharmaceutical and medical device regulations govern biocompatibility testing protocols under ISO 10993 standards. The Osaka-Kobe medical device cluster specializes in ceramic-on-ceramic bearing systems displacing traditional metal-polyethylene constructs.
United Kingdom
Integrated care systems in London and the Midlands consolidate orthopedic kit procurement through single-source agreements bundling implants and instruments. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR conformity requirements for market access. The Cambridge-Oxford medical technology corridor advances digital surgical planning convergence with implant sizing databases.
Australia
Private hospital networks in New South Wales and Victoria expand robotic-assisted surgery capabilities with capital equipment investments creating attach-rate pull for compatible instrument kits. TGA therapeutic goods administration oversees device certification under harmonized standards with European regulators. The Sydney- Melbourne orthopedic corridor concentrates demand for minimally invasive surgery approaches in day-surgery facilities.
Hip Kits Market Competitive Landscape
Global majors compete with regional champions across regulatory infrastructure and supply chain integration, producing a tiered structure where incumbents with dedicated MDR compliance teams consolidate European access while mid-tier suppliers exit. Three archetypes dominate: integrated manufacturing networks spanning multiple continents, specialized hip resurfacing portfolios competing on bone-preserving outcomes, and robotic-assisted procedure kit developers extending technology leadership into ambulatory settings. M&A activity targets ISO 13485-certified contract manufacturers, while strategic partnerships lock in titanium alloy supply security.
Within the integrated manufacturing tier, Stryker Corporation and Zimmer Biomet Holdings exemplify scale-driven positioning with North American and European production footprints. Smith & Nephew occupies a specialist position exemplifying bone-preserving technology development. These three entities anchor the competitive structure, with Stryker representing supply security consolidation, Zimmer Biomet sitting within robotic-assisted platform integration, and Smith & Nephew exemplifying differentiated clinical outcome positioning.
| Leading Market Players |
|---|
| Stryker Corporation |
| Smith & Nephew |
| BodyHealt |
| Medi Touch Limited |
| Surgitech |
| Orthomax India |
| Zimmer Biomet Holdings |
| DJO Global |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Orthopedic instrument engineers in Stuttgart-Tübingen and Warsaw anchor kit manufacturing, with labor-cost differentials between German precision-machining clusters and Eastern European contract manufacturers driving pricing-tier spreads across European markets.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from stripped-down economy offerings, with extended instrument validation cycles and field-replacement guarantees included in comprehensive contracts. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and robotic-platform compatibility. Cost compression in economy tiers intensifies because ASC procurement committees demand per-procedure caps. Hospital value analysis committees exhibit lowest price sensitivity; standalone ambulatory surgical centers demonstrate highest.
Supply Chain Analysis
Reverse-logistics networks for reusable reamers and trial implants concentrate refurbishment capacity in Germany and Switzerland, with validated sterilization cycles feeding back into kit redeployment. Raw material sourcing draws from North American titanium alloy corridors and Central African cobalt-chrome mining regions. Single-source vulnerability in bearing-surface metallurgy creates supply continuity exposure. Distribution runs through integrated delivery network central warehouses with consignment inventory at point-of-use.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance costs and FDA 510(k) notification backlogs are forcing mid-tier suppliers without dedicated regulatory infrastructure to exit, consolidating commercial access among incumbents with established quality management systems.
For Market Incumbents: Lock in ASC channel control through compact kit configurations with disposable-heavy designs that compress sterilization logistics. Secure titanium alloy supply through backward integration into North American metallurgical networks to defend against raw material price volatility from Central African mining concentration. For New Entrants and Emerging Players: EU MDR Article 10 streamlined certification pathways in Germany and the Netherlands open a window for ISO 13485-accredited contract manufacturers to enter European orthopedic networks. Target ambulatory surgical center credentialing expansion in Florida and Texas with same-day-discharge kit formats. Pursue white-label manufacturing partnerships with tier-one OEMs lacking European production footprints. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 13485-certified mid-tier manufacturers given EU MDR compliance team scarcity and incumbent acquisition appetite for regulatory infrastructure. Long-term viability centers on suppliers with robotic-platform instrument compatibility and ASC-dedicated product lines. Monitor FDA 510(k) notification backlog resolution timelines as inflection indicator for new entrant commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Article 10 technical documentation unlocks European Economic Area market access for qualified suppliers. |
| Robotic Platform Partnership | Intraoperative 3D mapping compatibility locks in kit standardization around manufacturer-specific instrument trays. |
| ASC Credentialing Expansion | Same-day-discharge protocol adoption in Florida and Texas compresses procedure timelines for compact kit formats. |
| Titanium Supply Security | North American metallurgical corridor sourcing stabilizes femoral stem production costs against cobalt-chrome volatility. |
| Digital Surgical Planning Integration | Preoperative templating software convergence enables patient-specific kit preconfiguration for complex deformity cases. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR Article 10 technical documentation filings, and hospital GPO contract records, complemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and ASC operations directors. Secondary validation drew from ISO 13485 certification registries, ASTM F138 material specification databases, and orthopedic implant procurement platforms. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Segment-level projections across product type, end user, technology tier, and application dimensions were generated through the modeling period. CAGRs were derived from weighted-average procedure growth assumptions and kit attach-rate trajectories. Forecast inputs incorporated ASC credentialing expansion timelines, robotic platform installation forecasts, and EU MDR transition completion rates.
The model assumes a particular technology adoption path; alternative pathways for ceramic-on-ceramic bearing systems displacing metal-polyethylene constructs would alter the outlook for traditional hip kit configurations. Forecasts reflect assumptions regarding FDA review timeline normalization and EU MDR notified body capacity expansion. Practitioners should monitor outpatient hip replacement reimbursement shifts and ASC same-day-discharge protocol adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ventilator Accessories Market
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Baby Thermometer Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Europe Ventilator Market
Medical Devices
Global Angiography Catheters Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market