
 Asia-Pacific Coated Paper Market | 2026-2036
Asia-Pacific Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Coated Paper Market Outlook
The gap between premium coated paper and commodity grades is expanding in concrete terms. Nine Dragons Paper Holdings Limited leverages its captive pulp supply to control cost volatility at the commodity end. Nippon Paper Industries Co Ltd differentiates through precision-calendered gloss stocks for commercial publishing. Oji Holdings Corporation anchors premium positioning with forest-certified lightweight grades targeting Japanese export packaging.
Coated paper consists of a base paper substrate layered with mineral pigments such as kaolin and calcium carbonate bound in latex, then calendered to a specified smoothness typically below two microns roughness for high-resolution halftone reproduction. Its primary commercial purpose is to deliver controlled ink holdout and visual uniformity for quality printing and protective packaging applications. Gloss coated and matte coated categories dominate volume, while silk coated commands margin pools in luxury packaging. The packaging end user segment leads growth trajectory, with direct sales channels capturing the largest share of mill-to-converter relationships.
China's MEE enforces wastewater discharge limits that compel mills to upgrade coating wastewater recovery systems. Japan's METI and India's CEA both impose energy efficiency benchmarks on paper manufacturing, shaping capital allocation toward coated lines with lower thermal intensity. Stakeholders must monitor how evolving ESG disclosure rules across the region reshape procurement criteria for coated paper buyers.
Market Dynamics
China's dual carbon goals are forcing pulp and paper mills across Asia-Pacific to retool coating lines for lower thermal intensity, while Japan's METI mandates and India's CEA benchmarks accelerate capital rotation toward barrier-grade coated stocks.
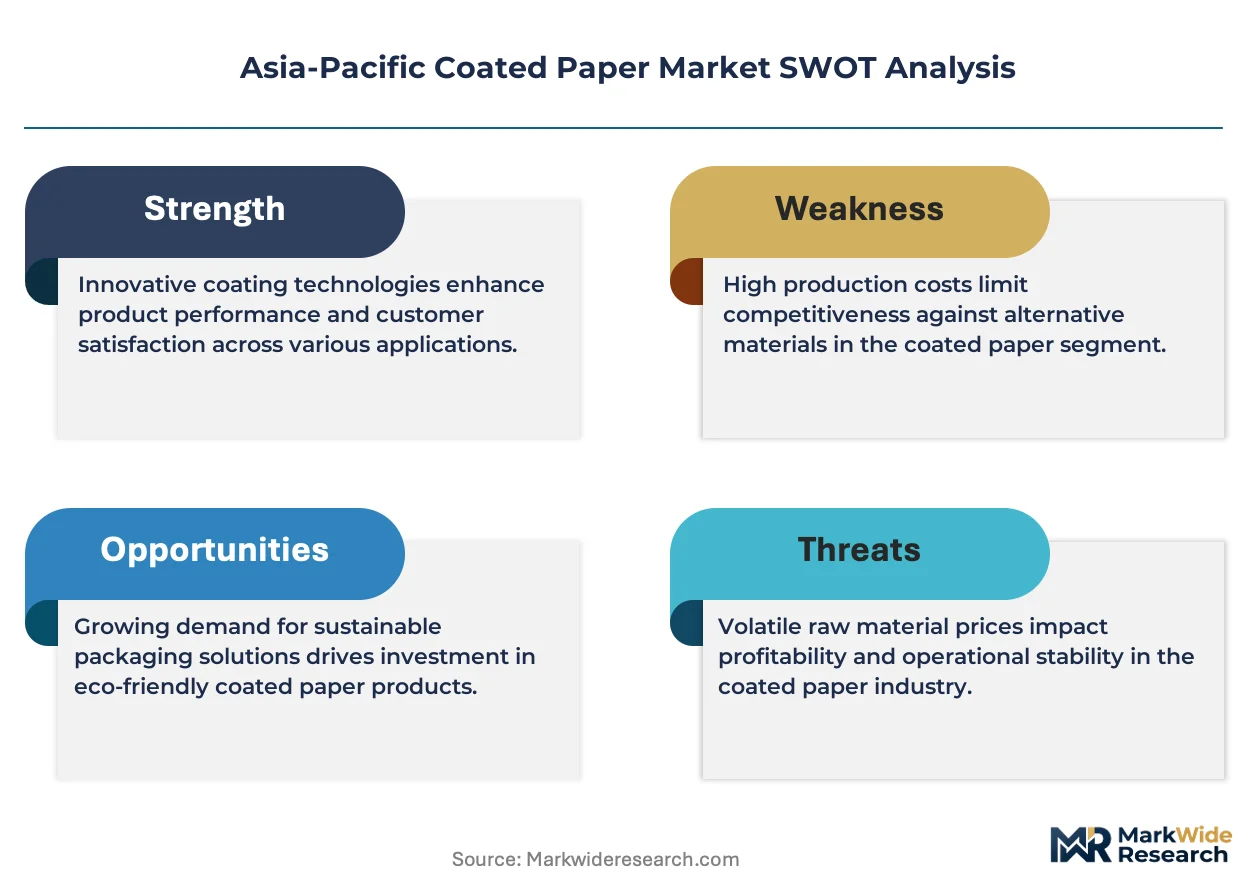
Growth Catalysts
- High-barrier coated grades:Packaging converters across Southeast Asia are lifting orders for moisture-resistant and oxygen-barrier coatings that extend shelf life for food and pharmaceutical exports.
- India's western industrial corridor:Demand concentrates from Gujarat through Maharashtra as domestic brands expand premium packaging capacity for consumer goods.
- Japan's METI efficiency mandates:Energy benchmarking rules are pushing mills to invest in precision-calendered lines that reduce steam consumption per tonne.
Market Restraints
- Kaolin and calcium carbonate volatility:Coating mineral pigment prices fluctuate with mining output constraints in China and Vietnam, compressing margin predictability for commodity-grade producers.
- MEE wastewater discharge limits:China's Ministry of Ecology and Environment enforces strict effluent standards that require costly recovery system upgrades at legacy mills.
- Plastic film substitution:Flexible polymer barriers continue displacing coated paper in moisture-critical applications where recyclability trade-offs are acceptable.
Strategic Opportunities
- Forest-certified lightweight grades:Japanese export packaging buyers are specifying FSC and PEFC chain-of-custody certification, creating premium positioning for compliant mills.
- Direct mill-to-converter channels:Digital platform integration is enabling spot purchasing and specification matching that bypasses traditional distributor markups.
- Silk coated luxury packaging:Cosmetic and spirits brands in South Korea and Australia are adopting low-sheen coated stocks for tactile differentiation at retail.
Industry Challenges
- Coating wastewater recovery capex:MEE compliance requires membrane filtration and closed-loop chemical recovery systems that strain mid-cap mill balance sheets.
- Calendering precision talent:Operating high-speed supercalenders to sub-two-micron roughness specifications demands specialized technicians in short supply across Vietnam and Indonesia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Coated Paper Market |
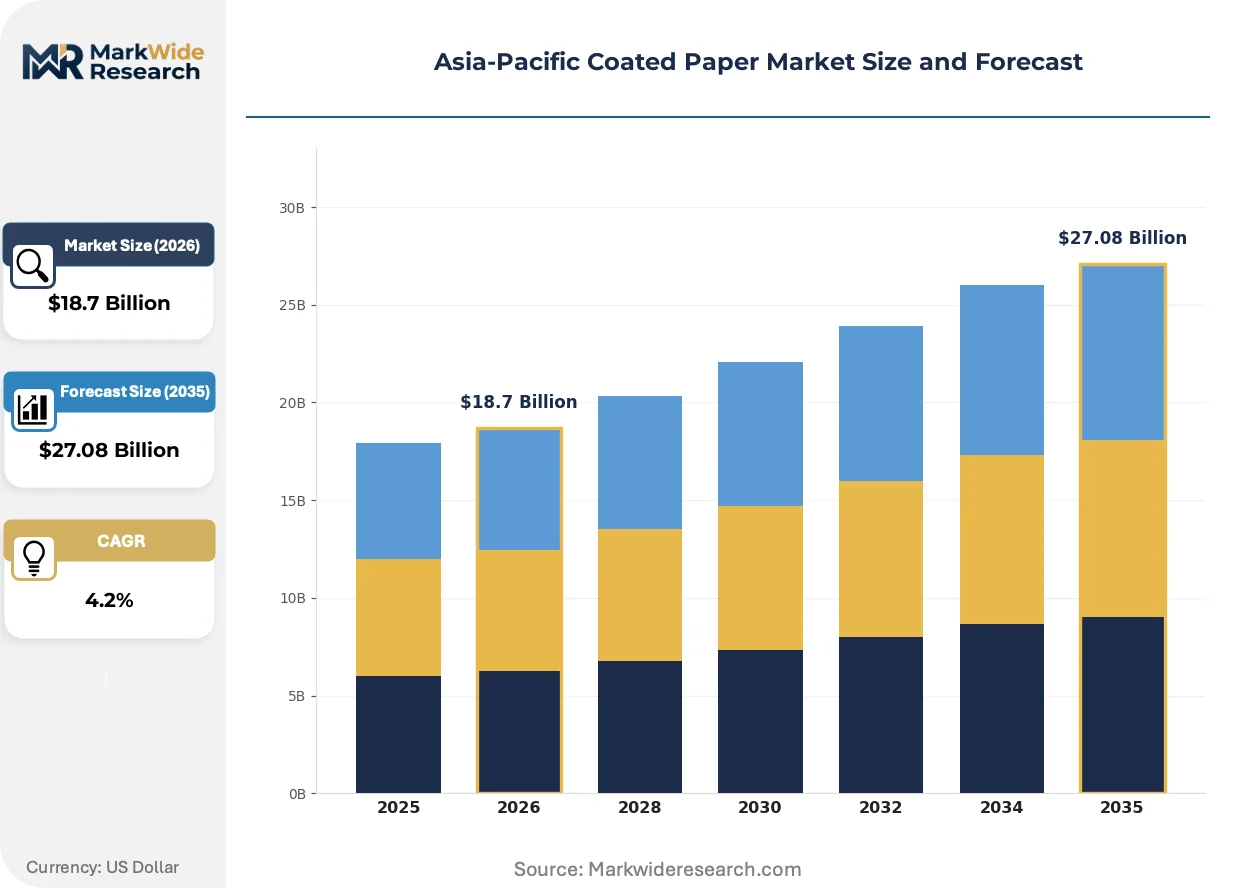
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloss Coated, Matte Coated, Silk Coated, Semi-Gloss Coated End User: Publishing, Packaging, Printing, Stationery Distribution Channel: Direct Sales, Distributors, Online Retail, Retail Stores Thickness: Lightweight, Standard, Heavyweight, Ultra Heavyweight |
| Companies Covered | Nine Dragons Paper Holdings Limited, Chenming Group, Nippon Paper Industries Co Ltd, JK Paper Limited, Shandong Sun Paper Industry Joint Stock Co Ltd, Oji Holdings Corporation, Lee and Man Paper Manufacturing Limited, Emami Paper Mills Limited, Asia Pulp and Paper Sinar Mas, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Coated Paper Market Strategic Shifts
Digital inkjet compatibility is reshaping coated paper formulation priorities across Asia-Pacific, as commercial print shops demand faster drying and sharper dot gain control without sacrificing offset runnability.
Barrier coating chemistry is converging with bio-based polymer binders to replace petroleum-derived latex in food-contact applications. Japanese pharmaceutical blister pack manufacturers are piloting these formulations for moisture protection. This convergence is compressing the performance gap between conventional and sustainable coated stocks.
China's MEE is tightening volatile organic compound emission limits for coating operations, compelling mills to install thermal oxidizers or switch to waterborne formulations. The policy most affects gloss-coated magazine paper production in Shandong and Jiangsu provinces, where mills are consolidating lines to amortize abatement costs.
Brand procurement teams are consolidating supplier panels and demanding lifecycle carbon disclosure from coated paper vendors. Direct sourcing agreements now specify scope three emissions thresholds that exclude uncertified mills, with this pattern most visible among Australian consumer goods exporters and Japanese electronics packaging buyers.
Asia-Pacific Coated Paper Market Segmentation
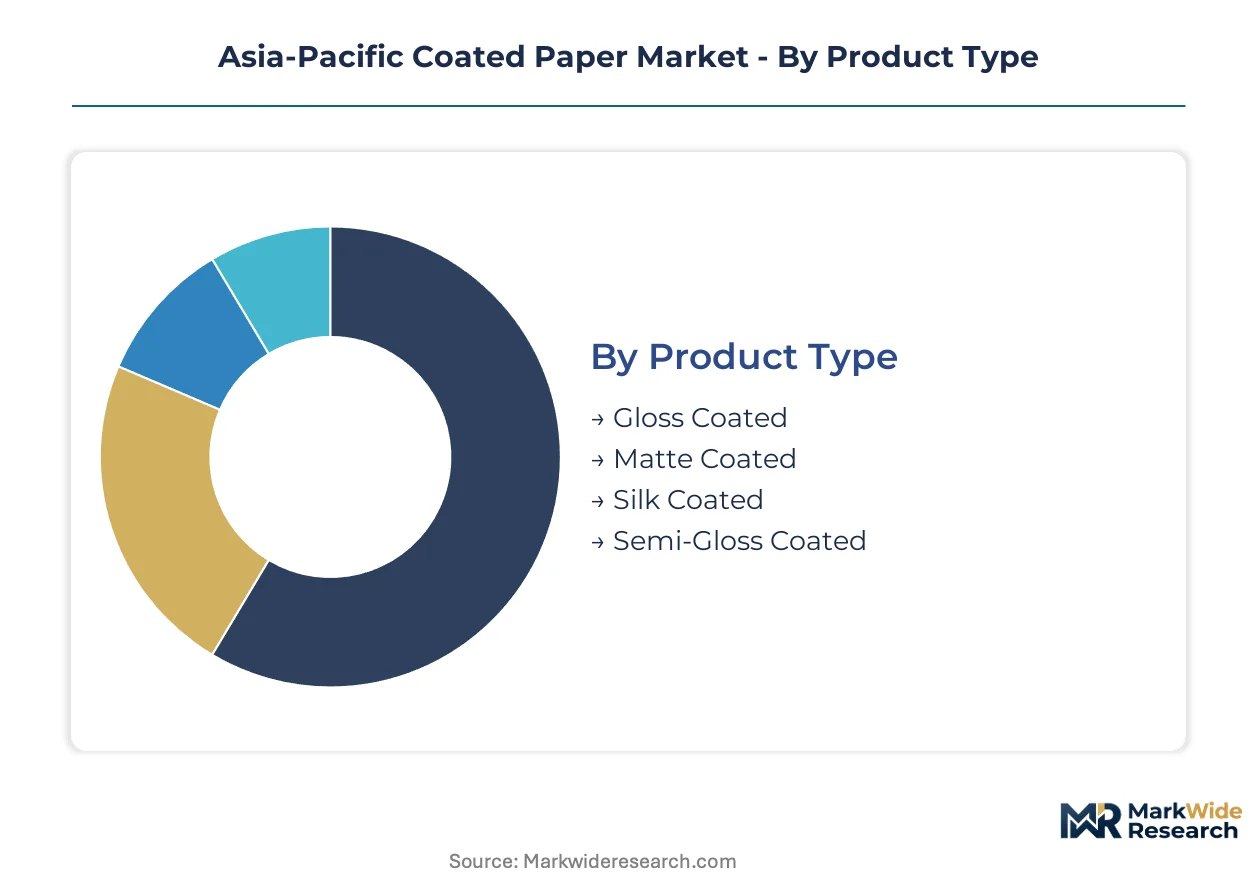
Coated paper segmentation in Asia-Pacific reflects divergent technical requirements across publishing, packaging, and commercial printing end uses. Specification differences in calendering precision, barrier chemistry, and substrate weight determine mill capital allocation and customer procurement criteria.
Product Type:
Certification burden varies sharply across finish grades, with food-contact silk coated stocks requiring Japan's FSSC 22000 and China's GB 4806 compliance while commodity gloss grades face lighter regulatory scrutiny.
- Gloss Coated:High-sheen mineral pigment layering with latex binder delivers sub-two-micron roughness for halftone reproduction. Magazine publishers in Japan and South Korea specify these grades for retail display impact, though China's MEE volatile organic compound limits are forcing thermal oxidizer investments at Shandong mills.
- Matte Coated:Reduced calendering pressure preserves diffuse surface reflectance for text-heavy applications. Textbook printers across India's western industrial corridor from Gujarat through Maharashtra are consolidating procurement around matte stocks as state education boards refresh curriculum materials.
- Silk Coated:Intermediate sheen profile targets luxury packaging with tactile differentiation requirements. Cosmetic brands in South Korea specify FSC-certified silk grades for shelf presence.
- Semi-Gloss Coated:Balanced optical properties serve general commercial printing where offset and digital hybrid workflows converge. Australian direct mail specialists favor semi-gloss for variable-data campaigns.
Gloss coated sits at the top of the volume ranking, with silk coated climbing the fastest on premium packaging demand.
End User:
Customer scale and specification complexity separate these segments, with multinational packaging converters demanding mill-level carbon disclosure that book publishers rarely enforce.
- Packaging:High-barrier coated grades with moisture and oxygen resistance dominate export food and pharmaceutical applications. Southeast Asian converters are lifting orders for extended-shelf-life specifications as regional processed food exports expand.
- Publishing:Commercial catalog and magazine production drives volume, though digital substitution compresses run lengths. Japanese periodical publishers are consolidating supplier panels to three mills maximum.
- Printing:Commercial print shops require inkjet-compatible formulations with faster drying profiles. Digital platform integration is enabling spot purchasing that bypasses traditional distributor markups.
- Stationery:Premium notebook and greeting card applications specify tactile surface characteristics. Domestic brands in Maharashtra are expanding premium stationery capacity.
Packaging commands the largest revenue pool, with printing expanding most quickly on digital workflow adoption.
Distribution Channel:
Channel selection determines margin capture and specification control, with direct relationships enabling custom calendering adjustments that distributor stocks cannot match.
- Direct Sales:Mill-to-converter relationships dominate high-volume packaging procurement with long-term offtake agreements. Japanese electronics packaging buyers now specify scope three emissions thresholds in direct contracts.
- Distributors:Inventory pooling serves small-lot commercial printers with standard specifications. Regional distributors in Vietnam and Indonesia maintain safety stock for quick-turn jobs.
- Online Retail:Digital platforms aggregate spot demand from independent designers and small publishers. Specification matching algorithms are compressing search costs for specialty grades.
- Retail Stores:Limited presence for consumer-facing stationery and craft applications. Urban centers in Australia stock premium coated sheets for hobbyist segments.
Direct sales anchors volume leadership, with online retail gaining share fastest among digitally native procurement teams.
Thickness:
Weight specification correlates with end-use durability requirements and freight economics, with lightweight grades offering logistics savings that heavyweight stocks sacrifice for rigidity.
- Lightweight:Sub-100 gsm construction reduces shipping costs for export-bound packaging. Japanese export packaging buyers specify forest-certified lightweight grades for air freight applications.
- Standard:100-150 gsm range balances printability with handling durability for general commercial use. Indian consumer goods brands in Gujarat are expanding standard-weight premium packaging capacity.
- Heavyweight:150-250 gsm construction serves rigid box and display applications. Cosmetic blister packs in South Korea require heavyweight substrate stability.
- Ultra Heavyweight:Above-250 gsm grades target luxury rigid packaging and archival portfolios. Limited production concentrates at Japanese and Australian specialty mills.
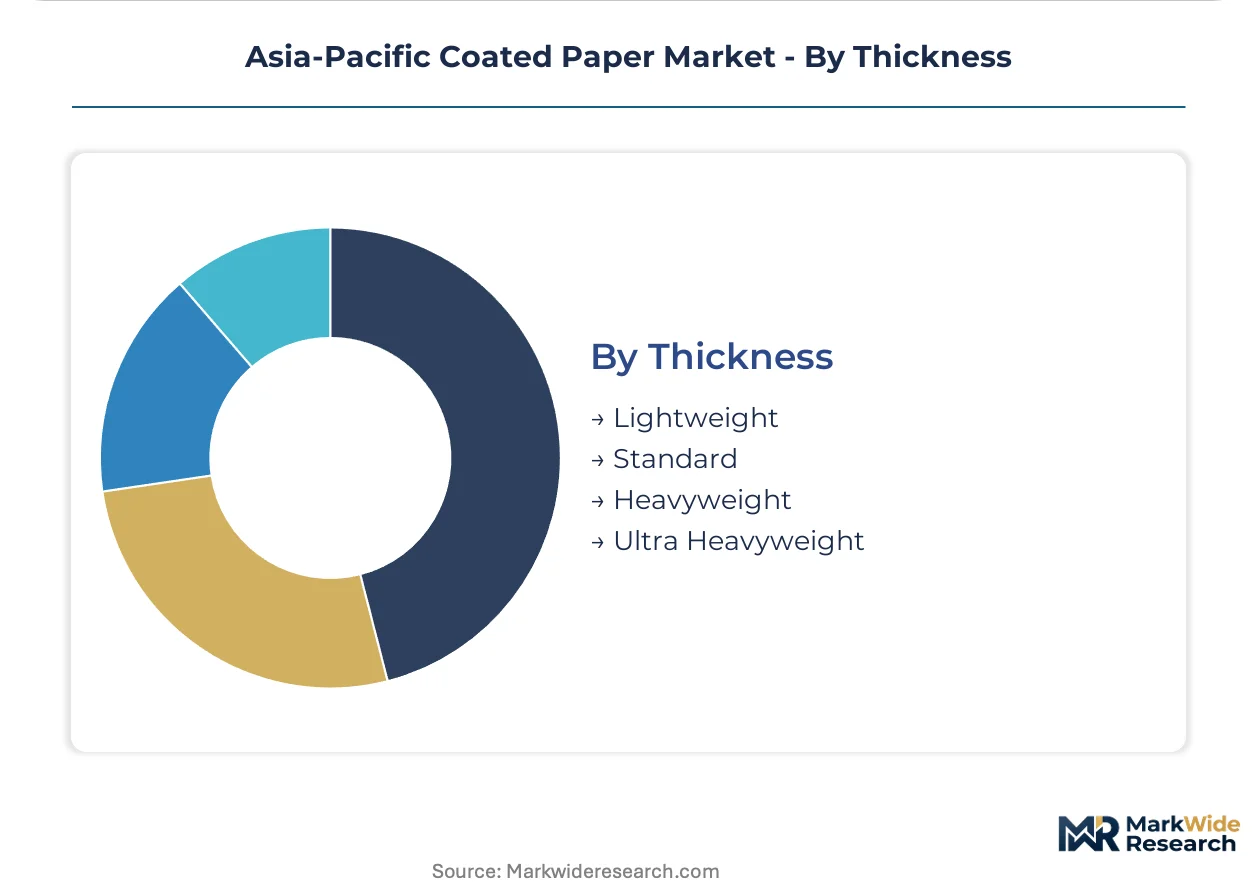
Standard thickness leads volume, with lightweight showing steepest expansion trajectory on logistics cost pressure and sustainability scoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp mill technicians and coating line specialists concentrate in China's Shandong-Jiangsu corridor and Japan's Kanto industrial belt, anchoring the region's technical workforce base.
China
Packaging converters in Guangdong and Jiangsu provinces are scaling high-barrier coated grades for processed food exports. The MEE enforces volatile organic compound emission limits that compel mills in Shandong to install thermal oxidizers or switch to waterborne formulations. Production gravity centers on the Yangtze River Delta where coating line consolidation is amortizing abatement costs across fewer, larger assets.
Japan
Commercial publishers in Tokyo and Osaka specify precision-calendered gloss stocks for retail display impact. METI energy efficiency benchmarks push mills to invest in supercalendered lines that reduce steam consumption per tonne. The Kanto region hosts specialized lightweight grade production targeting export packaging buyers demanding FSC chain-of-custody certification.
India
Domestic consumer goods brands from Gujarat through Maharashtra are expanding premium packaging capacity for cosmetics and pharmaceuticals. The CEA imposes energy efficiency benchmarks on paper manufacturing that shape capital allocation toward lower thermal intensity coating lines. The western industrial corridor concentrates new coated paper demand as state education boards refresh textbook procurement with matte grade specifications.
South Korea
Cosmetic and spirits brands in Seoul are adopting silk coated stocks for tactile differentiation at retail. The MFDS regulates food-contact coating formulations, creating compliance hurdles for imported barrier grades. Gyeonggi-do province hosts digital print shops demanding inkjet-compatible coated papers with faster drying profiles.
Vietnam
Southeast Asian packaging converters are lifting orders for moisture-resistant coated grades serving regional processed food exports. The country's national environmental regulator is tightening effluent standards for pulp and paper mills along the Red River Delta. Ho Chi Minh City anchors converter demand while Hai Phong concentrates port-facing mill capacity for export-bound production.
Asia-Pacific Coated Paper Market Competitive Environment
Top-tier vendors anchor premium positioning through forest-certified lightweight grades and precision-calendered gloss stocks, while mid-cap commodity producers compete on captive pulp supply and coating wastewater recovery efficiency. The vendor base stratifies across integrated pulp-to-paper conglomerates, specialty calendering houses, and regional packaging-grade suppliers. Three archetypes dominate: backward-integrated giants controlling fiber supply, precision-calendering specialists serving commercial publishing, and barrier-coating innovators targeting pharmaceutical and food-contact applications. Competitive moves center on coating line consolidation to amortize environmental compliance costs and direct mill-to-converter platform integration bypassing distributor markups.
Within the integrated conglomerate tier, Nine Dragons Paper Holdings Limited and Chenming Group represent scale-driven positioning anchored to captive pulp supply chains. Nippon Paper Industries Co Ltd exemplifies the precision-calendering specialist archetype serving quality-sensitive commercial publishing segments. Oji Holdings Corporation occupies a position within the forest-certified premium tier targeting Japanese export packaging buyers with lightweight grade specifications. These three company types collectively illustrate how coating capability, fiber control, and certification access define competitive positioning across the Asia-Pacific landscape.
| Leading Market Players |
|---|
| Nine Dragons Paper Holdings Limited |
| Chenming Group |
| Nippon Paper Industries Co Ltd |
| JK Paper Limited |
| Shandong Sun Paper Industry Joint Stock Co Ltd |
| Oji Holdings Corporation |
| Lee and Man Paper Manufacturing Limited |
| Emami Paper Mills Limited |
| Asia Pulp and Paper Sinar Mas |
| Others |
Value Chain & Pricing Dynamics
Kaolin and calcium carbonate coating pigments flow from Chinese and Vietnamese mining clusters through three pricing tiers downstream. MEE wastewater compliance costs and freight differentials separate premium FSC-certified lightweight grades from commodity gloss stocks.
Pricing Analysis
Unbundled pigment and latex pricing dominates spot transactions, while bundled long-term offtake agreements lock in volume for packaging converters. Certification grade and calendering precision drive price differentiation, with FSC chain-of-custody commanding substantial premiums over uncertified commodity stocks. Cost compression in gloss magazine grades is intensifying because MEE thermal oxidizer investments concentrate at Shandong mills. Small-lot commercial printers show highest price sensitivity, while Japanese electronics packaging buyers prioritize carbon disclosure over unit cost.
Supply Chain Analysis
Freight economics from Yangtze River Delta ports to Southeast Asian converters compress margins on lightweight grades. Supply concentrates in China, Japan, and India, with coating formulation chemistry drawing from petroleum-derived latex and emerging bio-based polymer alternatives. Single-source vulnerability sits with Chinese kaolin deposits facing mining output constraints. Distribution runs through direct mill-to-converter channels for high-volume packaging, while regional distributors in Vietnam and Indonesia pool inventory for quick-turn commercial print jobs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through coating line consolidation that amortizes MEE compliance costs across fewer assets, and through silk coated luxury packaging where tactile differentiation commands premium positioning.
For Market Incumbents: Hedge against plastic film substitution by deepening captive pulp supply integration and accelerating barrier-coating R&D for pharmaceutical blister applications. Consolidate gloss-coated magazine capacity in Shandong to spread thermal oxidizer capex across higher throughput. Forest-certified lightweight grades for Japanese export packaging anchor defensible premium positioning.
For New Entrants and Emerging Players: Begin with India's western industrial corridor where domestic consumer goods brands expand premium packaging capacity and coating wastewater recovery talent remains scarce. Target silk coated cosmetic applications in South Korea and Australia where MFDS compliance hurdles disadvantage imported barrier grades. Digital platform spot purchasing offers low-friction customer acquisition.
For Investors and Strategic Acquirers: Consolidation pressure builds where MEE compliance capex strains mid-cap mill balance sheets and calendering precision technicians remain in short supply across Vietnam and Indonesia. Five-to-ten-year viability favors backward-integrated assets with captive fiber supply and coating wastewater recovery systems already installed. Watch for scope three emissions disclosure mandates spreading from Japanese electronics packaging buyers to Australian consumer goods exporters as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Consolidation | Amortizes MEE thermal oxidizer investments across fewer, larger Shandong assets. |
| Backward Integration into Pulp Supply | Nine Dragons and Chenming anchor cost control through captive fiber sourcing. |
| Forest Certification Investment | FSC and PEFC chain-of-custody unlocks Japanese export packaging premium tiers. |
| Digital Platform Integration | Direct mill-to-converter spot purchasing bypasses distributor markups for converters. |
| Bio-Based Barrier Coating Development | Japanese pharmaceutical blister manufacturers pilot polymer binders replacing petroleum latex. |
Study Parameters
Bottom-up packaging converter demand modeling reconciled against top-down pulp mill capacity tracking forms the analytical core of this study. Primary interviews with coating line operators, procurement managers at Southeast Asian converters, MEE compliance officers, and METI energy benchmarking specialists combined with secondary validation from customs trade data, China Paper Association output statistics, and FSC chain-of-custody certification databases. This dual approach enables triangulation between order flow signals and installed production capacity.
Input-output matrix framing connects kaolin and calcium carbonate pigment supply through coating formulation chemistry to finished grade specifications across the projection horizon. Segmentation dimensions include finish grade tier, end-use industry, distribution channel structure, and substrate weight classification. CAGRs derive from slope-intercept modeling of historical capacity additions against forward order book visibility, with MEE regulatory phase-in schedules and METI efficiency mandate timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt shifts in China's dual carbon policy enforcement, unforeseen plastic film substitution acceleration, and geopolitical disruptions to Southeast Asian converter export markets. Forecasts reflect assumptions about coating wastewater recovery technology adoption curves and calendering precision labor availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Packaging Materials Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market