
 Die Cut Box Market | 2026-2036
Die Cut Box Market Size, Share, and Industry Trends Forecast 2026-2036
Die Cut Box Market Analytics
India's corrugated board capacity build-out is fragmenting die cut box supply chains across South Asia. WestRock leverages integrated pulp-to-box operations across multiple continents to sustain margin control. International Paper anchors North American linerboard supply for e-commerce die cut formats. Mondi Group differentiates through kraft paper specialization in Central European consumer goods packaging.
A die cut box is a paperboard or corrugated container engineered with pre-scored creases and cut lines that allow flat blanks to fold into precise three-dimensional shapes without additional tooling. These boxes typically employ E-flute or B-flute corrugated constructions between 1.5 mm and 4.0 mm thickness, with die-cut tolerances of ±0.5 mm ensuring automated assembly line compatibility. Corrugated material commands the largest volume share due to stacking strength requirements in palletized distribution, while kraft paper grades capture premium positioning in organic food and cosmetic applications where unbleached fiber aesthetics signal sustainability credentials. Custom size configurations are expanding fastest as direct-to-consumer brands demand dimensional optimization to minimize void fill and dimensional weight shipping penalties.
EPA guidelines on recycled content thresholds and FDA food-contact substance regulations shape substrate selection and adhesive chemistry for U.S. die cut box converters. The EU Green Deal's packaging waste reduction targets and REACH chemical compliance are forcing European manufacturers to eliminate certain petroleum-based coatings and accelerate water-based barrier formulations. Stakeholders must monitor how evolving extended producer responsibility schemes in multiple jurisdictions will redistribute cost structures between brand owners, converters, and waste management operators.
Market Dynamics
The EU Packaging and Packaging Waste Regulation's material recovery mandates are compressing substrate choice flexibility for die cut box converters, forcing capital reallocation toward certified recyclable supply chains and water-based barrier chemistry.
Growth Catalysts
- E-commerce fulfillment density:Automated pick-and-pack operations in Germany and the United States require die cut tolerances of ±0.5 mm for high-speed case erectors, pulling volume toward precision-engineered corrugated formats.
- REACH chemical compliance:The EU's elimination of certain petroleum-based coatings is accelerating water-based and bio-derived barrier adoption among Central European food-contact packaging producers.
- Dimensional optimization:Direct-to-consumer brands in cosmetics and organic food segments demand custom size configurations to minimize dimensional weight penalties and void fill material.
Market Restraints
- Old corrugated container price volatility:Recycled fiber input costs fluctuate with municipal collection system throughput, compressing converter margins during supply disruptions.
- Linerboard supply concentration:North American containerboard capacity is controlled by a handful of integrated producers, creating bottleneck risk for independent die cut box manufacturers.
- Fluting substitution ceiling:Solid fiberboard and molded pulp formats cannot replicate E-flute stacking strength above 15 kg load requirements, limiting displacement in palletized distribution.
Strategic Opportunities
- India industrial corridor build-out:Corrugated board capacity expansion across Maharashtra and Gujarat is creating supply chain reconfiguration opportunities for export-oriented die cut box sourcing.
- Extended producer responsibility schemes:France and Italy's advanced EPR frameworks reward certified recyclable packaging with fee reductions, incentivizing substrate innovation.
- Digital print convergence:Single-pass inkjet integration with die cutting lines enables lot-size-one production for personalized subscription box programs.
Industry Challenges
- Die-making artisan shortage:Skilled tool-and-die craftspersons with rotary and flatbed expertise are retiring faster than apprenticeship programs replace them.
- FDA food-contact certification timelines:New adhesive chemistries face 18-24 month migration testing protocols, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Cut Box Market |
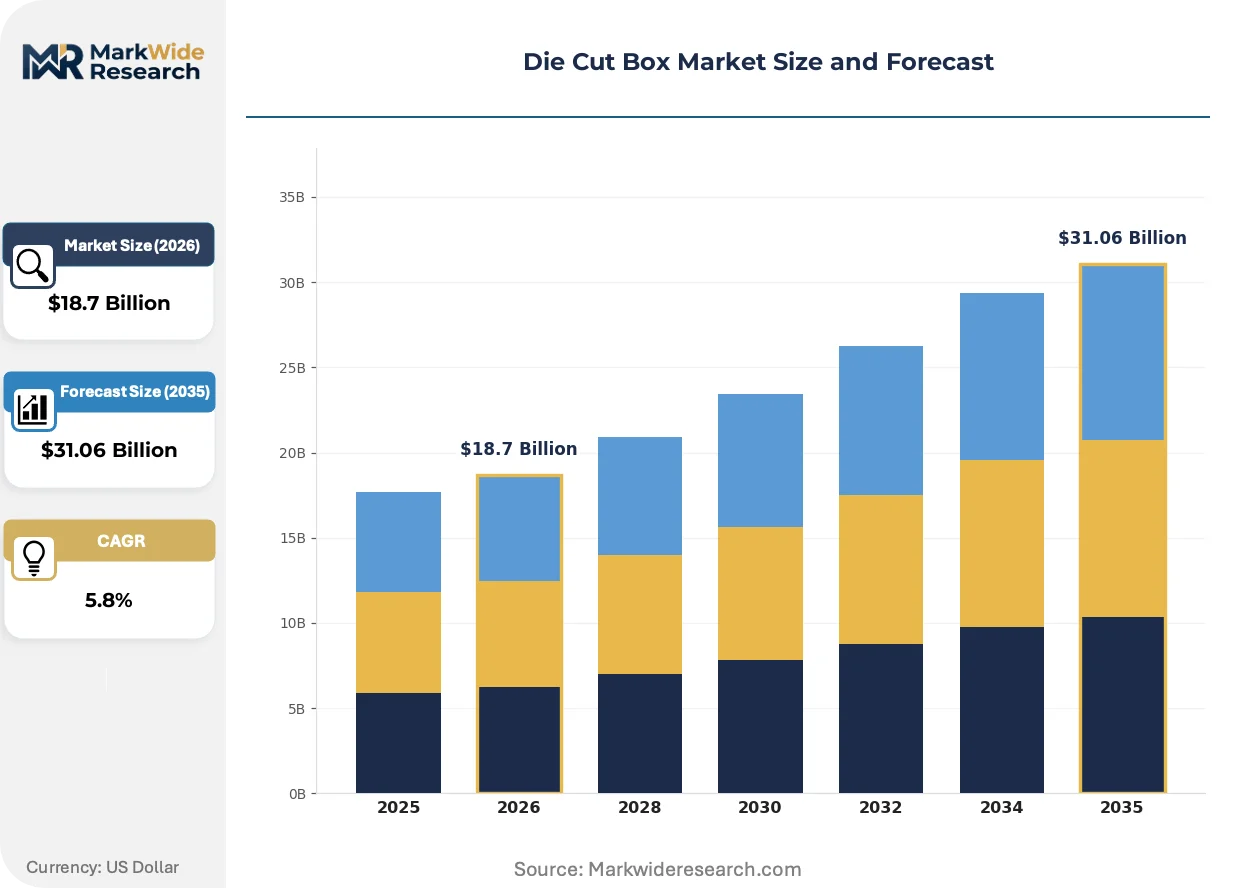
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Corrugated, Kraft Paper, Rigid Paper End User: Consumer Electronics, Food & Beverage, E-commerce, Healthcare Size: Small, Medium, Large, Custom Design Type: Plain, Printed, Laminated, Embossed |
| Companies Covered | WestRock, International Paper, Mondi Group, Smurfit Kappa Group, DS Smith, Pratt Industries, Georgia-Pacific, Packaging Corporation of America, Alpha Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Cut Box Market Evolving Landscape
Die cut box manufacturing is experiencing simultaneous pressure from automation imperatives, chemical formulation constraints, and dimensional precision requirements that are rewiring equipment investment priorities across converter facilities.
Barrier-coated kraft paper is hybridizing with conventional corrugated structures to create moisture-resistant formats that retain fiber-based recyclability credentials. Organic food and cosmetic brands in Germany and France are specifying these constructions for premium positioning. The technology is hybridizing substrate categories that previously occupied distinct specification tiers.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating oil-and-grease-resistant fluorochemical coatings from food-contact applications. European converters are reformulating with plant-derived waxes and chitosan barriers at commercial scale. Bakery and ready-meal segments in the EU are absorbing the 8-12% cost premium to maintain regulatory access.
Brand owners are consolidating vendor relationships around full-service packaging partners capable of design-to-delivery integration. Small and mid-sized e-commerce merchants are losing direct supplier access as converters prioritize volume commitments from multinational fulfillment operations. This concentration is most visible in the United States, where Amazon's Packaging Support and Supplier Network qualification requirements have become de facto industry standards for automated warehouse compatibility.
Die Cut Box Market Segmentation
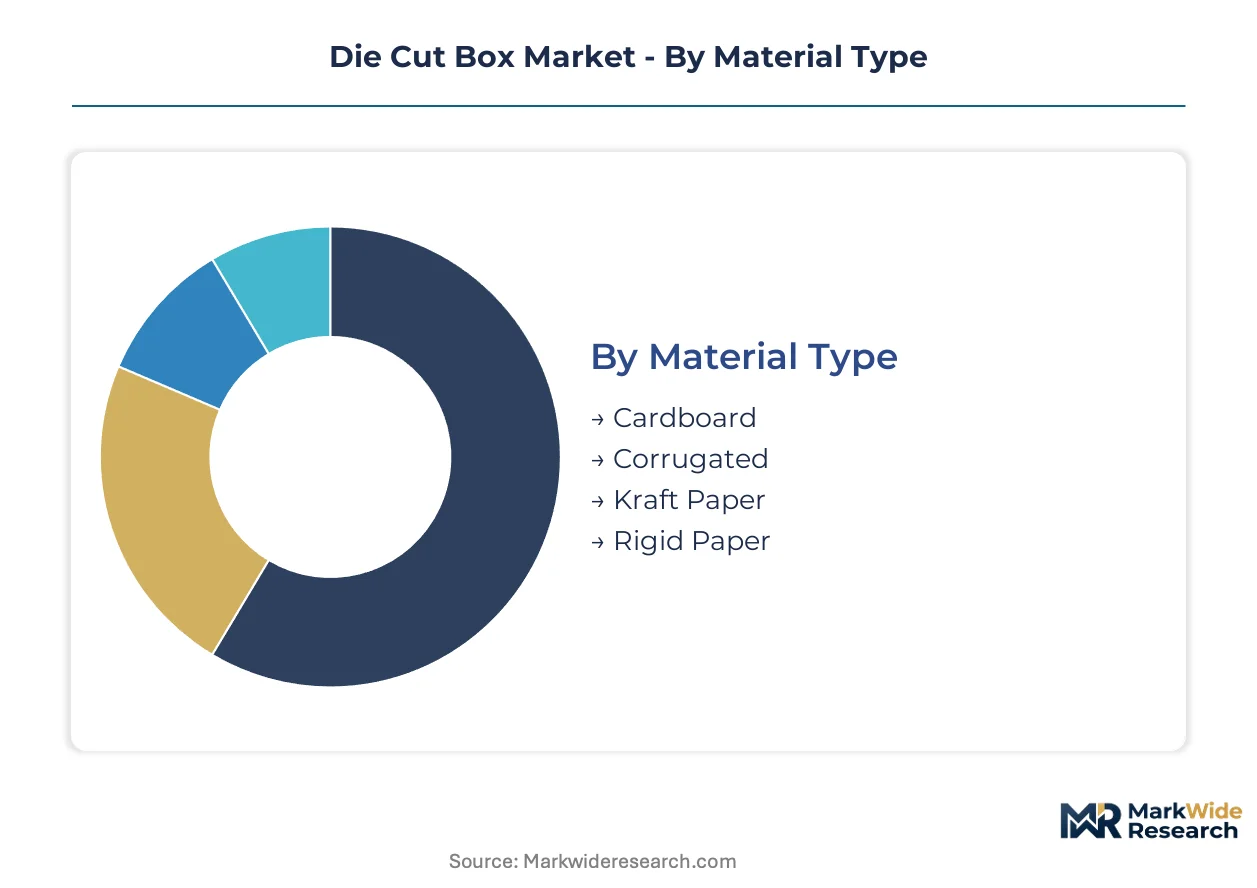
Die cut box procurement decisions cascade through material specifications, end-use performance requirements, and dimensional precision needs. Each segmentation axis carries distinct after-sales service implications, from FDA migration testing support to custom die maintenance programs.
Material Type:
After-sales service intensity varies sharply by substrate, with corrugated demanding fleet maintenance partnerships and kraft paper requiring barrier performance guarantees.
- Corrugated:E-flute and B-flute constructions between 1.5 mm and 4.0 mm thickness dominate palletized distribution networks. Automated case erectors in Germany and the United States require ±0.5 mm die-cut tolerances, pulling volume toward precision-engineered formats with integrated linerboard supply backing.
- Kraft Paper:Unbleached fiber constructions capture premium positioning in organic food and cosmetic segments where sustainability credentials drive specification. France and Germany absorb 8-12% cost premiums for plant-derived wax barriers replacing REACH-restricted fluorochemical coatings.
- Cardboard:Solid fiberboard serves lightweight consumer goods with moderate stacking requirements below 15 kg loads.
- Rigid Paper:High-density constructions target luxury packaging with structural integrity demands exceeding standard corrugated limits.
By volume, corrugated leads. By growth pace, kraft paper is ahead.
End User:
Cost tier stratification separates fulfillment-scale e-commerce from precision-tolerance healthcare applications.
- E-commerce:Direct-to-consumer brands demand dimensional optimization to minimize void fill and dimensional weight shipping penalties. Amazon's Packaging Support and Supplier Network qualification requirements have become de facto industry standards for automated warehouse compatibility in the United States.
- Food & Beverage:FDA food-contact substance regulations and EU REACH compliance shape adhesive chemistry and barrier formulation selection. Bakery and ready-meal segments drive water-based barrier adoption at commercial scale.
- Consumer Electronics:Anti-static and moisture-resistant specifications dominate, with barrier-coated hybrid structures gaining specification.
- Healthcare:Sterile barrier integrity and tamper-evidence requirements impose the tightest die-cut tolerances and longest certification timelines.
By revenue concentration, e-commerce leads. By margin structure, healthcare is ahead.
Size:
Volume economics favor standardized formats while customization commands premium positioning.
- Custom:Lot-size-one production enabled by single-pass inkjet integration with die cutting lines serves personalized subscription box programs. Dimensional optimization minimizes shipping penalties for cosmetics and organic food direct-to-consumer brands.
- Small:Standardized formats for individual unit protection in electronics and cosmetics distribution.
- Medium:Multi-unit consolidation formats for retail shelf-ready packaging.
- Large:Bulk shipment configurations with reinforced stacking strength for palletized distribution.
By unit volume, small and medium lead. By value expansion, custom is climbing fastest.
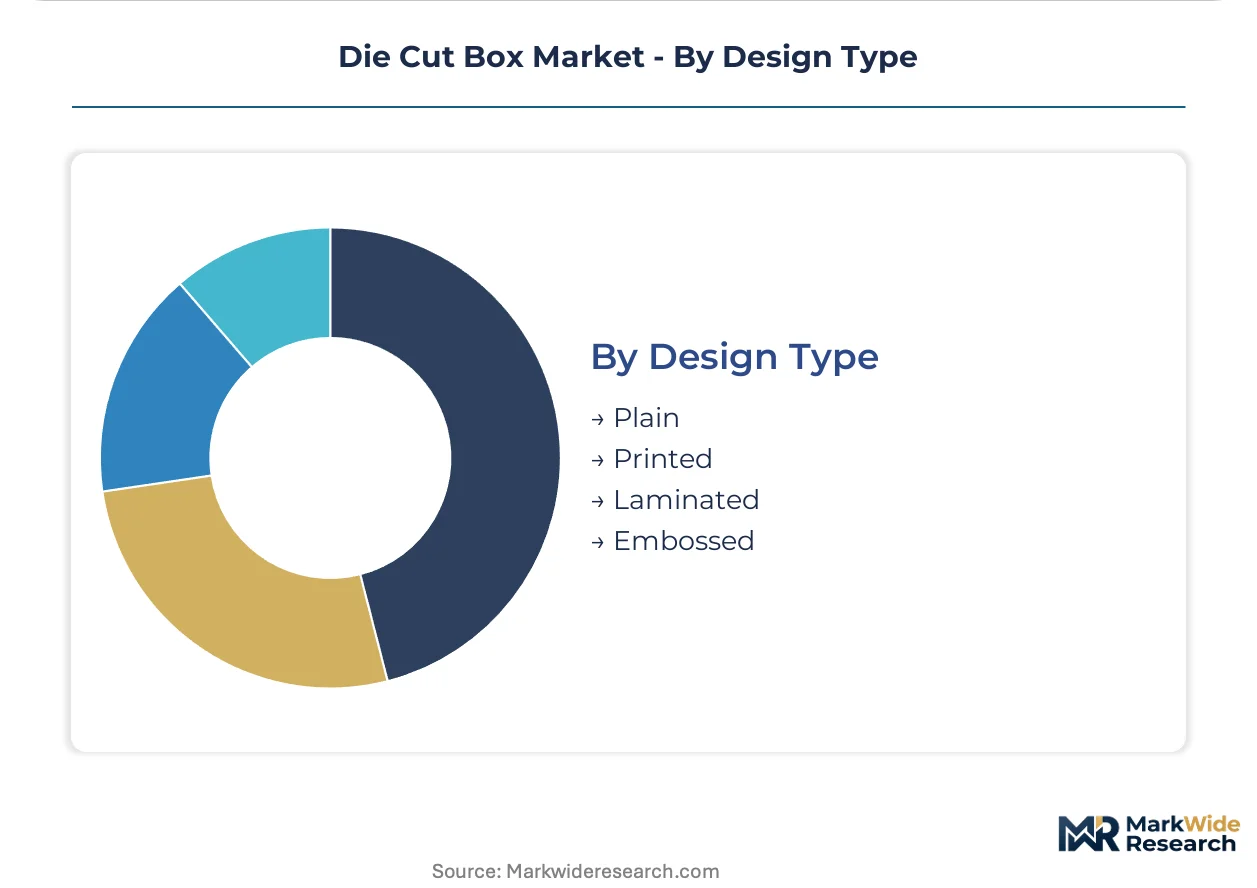
Design Type:
Supply concentration in digital print capabilities is restructuring competitive access for mid-sized merchants.
- Printed:Single-pass inkjet convergence with die cutting lines enables variable data and personalized graphics at production speeds. Brand owners consolidate vendor relationships around full-service partners capable of design-to-delivery integration.
- Laminated:Multi-substrate constructions combining moisture resistance with fiber-based recyclability credentials. Organic food brands in Germany and France specify these hybrid formats.
- Plain:Undecorated formats for cost-sensitive industrial and secondary packaging applications.
- Embossed:Tactile premium positioning for luxury cosmetics and gift packaging segments.
By adoption breadth, printed leads. By specification growth, laminated is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-box operations concentrate in Germany, the United States, and China, while India's capacity build-out fragments South Asian supply chains. Regulatory divergence between EPA guidelines, EU Green Deal packaging mandates, and China's dual carbon goals forces converters into jurisdiction-specific compliance architectures.
United States
E-commerce fulfillment density drives precision die cut tolerance demand for automated case erectors. EPA recycled content thresholds and FDA food-contact substance regulations shape substrate selection and adhesive chemistry. Georgia-Pacific and Packaging Corporation of America anchor linerboard supply for automated warehouse formats across the Southeast and Midwest industrial corridors.
Germany
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate fluorochemical coatings from food-contact applications. The EU Packaging and Packaging Waste Regulation tightens material recovery targets, pushing converters toward certified recyclable substrates. Mondi Group's kraft paper specialization serves organic food and cosmetic brands in Bavaria and Baden-Württemberg.
China
Export manufacturing zones in the Yangtze River Delta and Pearl River Delta absorb volume for cross-border e-commerce fulfillment. MIIT standards and dual carbon goals accelerate water-based barrier chemistry adoption. Corrugated board capacity concentrates in Zhejiang and Guangdong provinces for palletized distribution networks.
India
Corrugated board capacity expansion across Maharashtra and Gujarat creates supply chain reconfiguration opportunities for export-oriented sourcing. BIS certification requirements and FSSAI food-contact regulations shape converter qualification protocols. The Delhi-Mumbai Industrial Corridor attracts die cut box investment for domestic e-commerce and pharmaceutical packaging segments.
Die Cut Box Market Competitive Landscape
Integrated conglomerates and regional specialists split the market between margin-controlled pulp-to-box operations and agile custom-format converters. WestRock leverages captive fiber supply across multiple continents to sustain cost position. International Paper anchors North American linerboard availability for high-volume e-commerce accounts. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters secure substrate access and automated production technology.
Among North American integrated producers, WestRock and International Paper exemplify the pulp-to-box archetype that controls substrate cost volatility through backward integration into linerboard manufacturing. Mondi Group occupies a differentiated position within the European specialty tier, anchoring kraft paper and barrier-coated formats for premium organic food and cosmetic applications. These three entities represent the strategic poles—scale integration, regional specialization, and premium substrate innovation—that structure competitive access across major demand corridors.
| Leading Market Players |
|---|
| WestRock |
| International Paper |
| Mondi Group |
| Smurfit Kappa Group |
| DS Smith |
| Pratt Industries |
| Georgia-Pacific |
| Packaging Corporation of America |
| Alpha Packaging |
| Others |
Value Network & Pricing Analysis
The Hamburg-Rotterdam container corridor's freight cost volatility compresses converter margins while amplifying price differentiation between integrated producers and independent manufacturers. REACH compliance investments and recycled fiber input costs stratify pricing tiers, with brand owners absorbing premium differentials for certified sustainable formats.
Pricing Analysis
EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across the European die cut box market. Three-tier pricing separates premium kraft-barrier formats from standard corrugated grades and economy recycled-content constructions. Price differentiation rests on certification grade and volume scale, with organic food brands absorbing 8-12% premiums for plant-derived wax barriers. Cost compression in mid-tier corrugated segments intensifies because of old corrugated container price volatility. Small e-commerce merchants exhibit highest price sensitivity, while multinational fulfillment operations prioritize automated warehouse compatibility over unit cost.
Supply Chain Analysis
Integrated linerboard producers in the United States, Germany, and China hold concentrated contract-manufacturing capacity for precision die cut formats. Raw material supply draws from virgin pulp mills, recycled fiber collection systems, and kraft paper specialty producers. Single-source vulnerability concentrates in North American linerboard supply, where a handful of integrated producers control containerboard capacity. Distribution runs through direct fulfillment center contracts for e-commerce volumes and regional converter networks for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Die cut box manufacturing sits at a high-growth inflection as single-pass inkjet convergence with die cutting lines enables lot-size-one production. EU Green Deal packaging mandates and FDA food-contact certification timelines are compressing competitive windows for substrate innovation and barrier chemistry reformulation.
For Market Incumbents: Entrench automated production technology investments to defend against digital-native converters capturing personalized subscription box volumes. Prioritize captive fiber supply through backward integration into linerboard manufacturing, particularly across Southeast Asian capacity expansions. Secure Amazon Packaging Support and Supplier Network qualification to lock in multinational fulfillment commitments. Accelerate water-based barrier R&D ahead of REACH Annex XVII enforcement deadlines. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors offer underpenetrated white-space for export-oriented die cut box sourcing. Target custom-format segments serving cosmetics and organic food direct-to-consumer brands demanding dimensional optimization. Establish design-to-delivery integration capabilities to compete with full-service packaging partners consolidating vendor relationships. Leverage single-pass inkjet partnerships to bypass capital-intensive rotary die infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified paper conglomerates with non-core packaging divisions lacking barrier-coating expertise. Long-term viability favors specialists with certified recyclable supply chains and automated warehouse compatibility credentials. Watch for inflection signals in extended producer responsibility scheme adoption across France, Italy, and emerging Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Chemistry Scale-Up | REACH Annex XVII compliance secures EU food-contact market access for bakery and ready-meal segments. |
| Single-Pass Inkjet Integration | Digital print convergence enables lot-size-one production for personalized subscription box programs. |
| India Capacity Expansion | Maharashtra and Gujarat build-out captures export-oriented sourcing from fragmented South Asian supply chains. |
| Certified Recyclable Substrate Investment | EU Green Deal material recovery targets reward compliant packaging with EPR fee reductions. |
| Automated Case Erector Compatibility Program | ±0.5 mm die-cut tolerance qualification secures high-volume e-commerce fulfillment contracts. |
Research Methodology
Initial hypotheses were tested against primary input from corrugated plant managers, e-commerce fulfillment procurement leads, food-contact packaging R&D directors, and barrier chemistry suppliers and refined through secondary validation. Primary fieldwork combined structured interviews with converter operations executives and brand owner packaging specification teams. Secondary sources encompassed EPA recycled content guidelines, EU ECHA substance restriction databases, FSSAI food-contact regulations, and customs trade data for linerboard and kraft paper flows. Bottom-up volume triangulation across material type, end-use segment, and regional production clusters was cross-checked against top-down macroeconomic drivers.
Demand-supply balance modeling anchored value projections across the analysis window, with segmentation dimensions spanning material construction, end-use performance requirements, dimensional precision tiers, and geographic regulatory clusters. CAGRs were derived from regression analysis of historical capacity utilization, e-commerce fulfillment density indices, and substrate substitution elasticity. Forecast inputs incorporated automated warehouse adoption curves, REACH chemical compliance implementation timelines, and extended producer responsibility scheme rollout patterns.
Practitioners should monitor old corrugated container price indices, FDA adhesive migration testing backlogs, and EU packaging waste reduction enforcement intensity for early signals of forecast revision. Quarterly review of linerboard capacity announcements, digital print equipment installation rates, and EPR fee schedule adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Europe Paper Packaging Market