
 Watt Meter Market | 2026-2036
Watt Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Watt Meter Market Analytics
A capital-intensity divergence between integrated semiconductor fabricators and assembly-focused instrument makers is bifurcating competitive dynamics in the watt meter landscape. Siemens AG leverages captive silicon sourcing and in-house ASIC design to sustain margin resilience across industrial-grade product lines. Keysight Technologies differentiates through precision calibration laboratories and aerospace-defense channel control, occupying premium segments where metrology traceability commands price authority.
A watt meter is an electromechanical or electronic instrument that quantifies real power consumption in watts by measuring instantaneous voltage and current with a defined phase-angle compensation, typically achieving accuracy classes of 0.1 to 2.5 under IEC 62053 standards. The device serves primary commercial purpose in revenue-grade energy settlement, load profiling, and power quality diagnostics across generation, transmission, and end-use nodes. Digital watt meters lead volume shipments due to declining ADC costs and mandatory smart metering rollouts, while IoT-enabled architectures represent the fastest-expanding technology tier as utilities demand remote disconnect and time-of-use telemetry. Analog watt meters retain residual demand in cost-sensitive residential retrofits and legacy industrial panels where electromagnetic robustness outweighs connectivity requirements.
The US Federal Energy Regulatory Commission mandates synchrophasor and AMI interoperability standards that shape procurement specifications for grid-connected watt meters, while the EU F-Gas Regulation and CE marking framework constrain refrigerant-cooled instrument designs and electromagnetic compatibility thresholds. India's Central Electricity Authority enforces metering codes under the Electricity Act that drive demand for networked meters with remote-reading capability. Stakeholders must monitor how cybersecurity certification requirements for critical infrastructure equipment reshape vendor qualification timelines and R&D allocation across hardware-software integrated platforms.
Market Dynamics
The watt meter market is bifurcating around silicon sourcing strategies, as integrated semiconductor fabricators capture margin from assembly-focused instrument makers through captive ASIC supply and in-house calibration IP.
Growth Catalysts
- India's PLI scheme:Domestic manufacturing incentives accelerate local production of networked watt meters for rural electrification programs, reducing import dependency for utilities.
- EU F-Gas Regulation:Tightened energy efficiency mandates for metering equipment force upgrades across European distribution networks, creating replacement demand for compliant instruments.
- AMI interoperability standards:FERC-mandated synchrophasor compatibility drives procurement of grid-connected meters with remote telemetry and time-of-use billing capabilities.
Market Restraints
- ADC cost volatility:Fluctuating prices for precision analog-to-digital converters squeeze margins on digital watt meter production lines.
- Semiconductor supply concentration:Dependence on concentrated East Asian foundry capacity creates vulnerability for meter manufacturers lacking captive silicon.
- Electromagnetic compatibility thresholds:CE marking constraints on refrigerant-cooled instrument designs limit product architecture flexibility for industrial-grade units.
Strategic Opportunities
- Rural India electrification:Underpenetrated distribution networks offer volume expansion for cost-optimized networked meters with remote-reading capability.
- IoT-enabled architectures:Convergence of wireless communication modules with power quality diagnostics opens premium segments for predictive maintenance services.
- EU Green Deal funding:Carbon neutrality incentives subsidize smart grid deployments, creating procurement tailwinds for revenue-grade settlement meters.
Industry Challenges
- Metrology calibration expertise:Scarcity of precision calibration technicians extends vendor qualification timelines for aerospace-defense channel entry.
- Cybersecurity certification complexity:Critical infrastructure equipment standards reshape R&D allocation across hardware-software integrated platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Watt Meter Market |
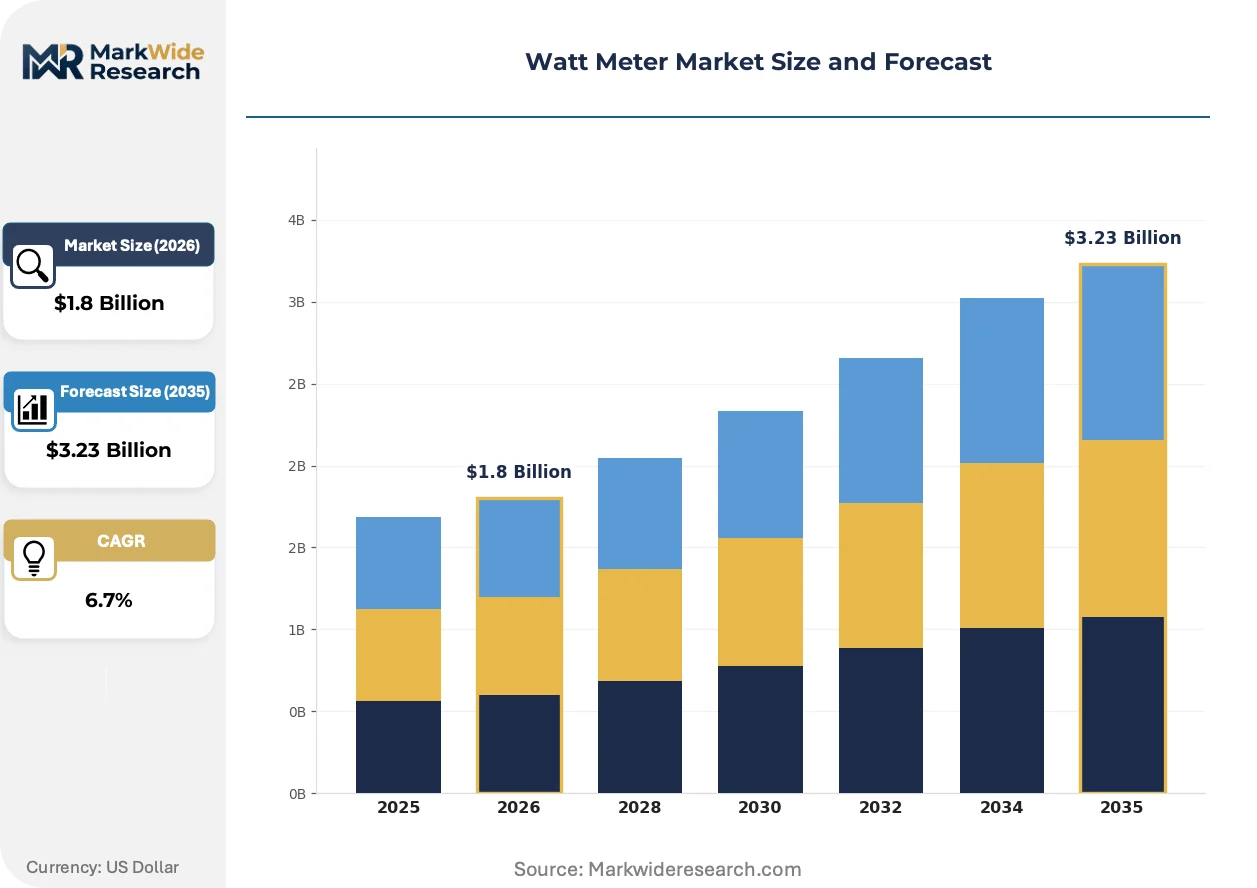
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Digital Watt Meter, Analog Watt Meter, Smart Meter, Clamp Meter Application: Residential, Commercial, Industrial, Renewable Energy Technology: IoT Enabled, Traditional, Networked, Wireless End User: Utilities, Energy Managers, Homeowners, Facility Operators |
| Companies Covered | Fluke Corporation, Keysight Technologies, Texas Instruments, Siemens AG, Schneider Electric, Honeywell International Inc., Yokogawa Electric Corporation, HIOKI E.E. Corporation, National Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Watt Meter Market Evolving Landscape
Digital measurement architectures are compressing the technology lifecycle, while regulatory interoperability mandates and utility procurement centralization reshape competitive positioning across the value chain.
Non-invasive current sensors with Rogowski coil designs are supplanting traditional current transformers in retrofit applications. Commercial building operators in Germany and Japan are adopting these clamp-on architectures for sub-metering deployments where panel shutdown is economically prohibitive. The shift is compressing installation labor costs and enabling faster deployment cycles for energy management system integrators.
The EU F-Gas Regulation is tightening refrigerant-cooled instrument specifications across industrial meter categories. Manufacturers must redesign thermal management systems to comply with phasedown schedules for hydrofluorocarbons, adding engineering validation cycles to product roadmaps. Meter suppliers serving process industries are responding by accelerating solid-state cooling alternatives and revising CE conformity assessment protocols.
Centralized procurement by national utilities is consolidating vendor relationships and compressing switching cycles for meter suppliers. India's state electricity boards are bundling multi-year AMI rollout contracts, displacing fragmented municipal purchasing and favoring scale-capable manufacturers with integrated software platforms. This concentration is most visible in Maharashtra and Gujarat, where tender sizes now exceed single-source capacity thresholds.
Watt Meter Market Segmentation
Watt meter procurement specifications diver sharply across regulatory jurisdictions, with FERC-mandated AMI interoperability in the United States, CE marking thresholds under the EU F-Gas Regulation, and CEA metering codes in India each dictating distinct hardware-software configurations. Vendors must architect product portfolios around these compliance boundaries rather than treating geography as a secondary sales channel.
Type:
FERC synchrophasor standards and IEC 62053 accuracy classes create divergent certification burdens across meter architectures, privileging vendors with captive metrology laboratories.
- Digital Watt Meter:Solid-state architectures employing precision ADCs achieve 0.1 to 2.5 accuracy classes under IEC 62053. Demand concentrates in European distribution networks where the EU F-Gas Regulation mandates energy efficiency upgrades and CE marking compliance forces thermal management redesigns.
- Smart Meter:Networked devices with remote disconnect and time-of-use telemetry capabilities dominate utility procurement in India, where Maharashtra and Gujarat state electricity boards bundle multi-year AMI contracts exceeding single-source capacity thresholds.
- Analog Watt Meter:Electromechanical designs retain residual demand in cost-sensitive residential retrofits across rural India and legacy industrial panels where electromagnetic robustness outweighs connectivity requirements.
- Clamp Meter:Rogowski coil non-invasive sensors enable sub-metering in German and Japanese commercial buildings where panel shutdown is economically prohibitive.
Established volume favors Digital Watt Meter; emerging adoption favors Smart Meter.
Application:
Cost tier differentiation separates premium revenue-grade settlement meters from economy-grade monitoring devices across building automation and grid infrastructure deployments.
- Industrial:Process industries require refrigerant-cooled instrument designs with solid-state thermal management alternatives to comply with EU F-Gas phasedown schedules, extending engineering validation cycles.
- Renewable Energy:Solar and wind integration demands power quality diagnostics with predictive maintenance telemetry, expanding fastest in EU Green Deal subsidized smart grid deployments.
- Residential:Rural electrification programs in India drive demand for cost-optimized networked meters with remote-reading capability under CEA metering codes.
- Commercial:Building operators in Germany and Japan adopt clamp-on architectures for energy management system integration where installation labor costs determine project viability.
Margin concentration sits with Industrial; volume expansion centers on Residential.
Technology:
Supply concentration in East Asian foundry capacity shapes which communication architectures achieve cost-competitive scale.
- IoT Enabled:Wireless modules converged with power quality diagnostics open premium service revenue streams through predictive maintenance platforms for facility operators.
- Networked:AMI interoperability standards mandate these architectures for grid-connected deployment, with India's PLI scheme accelerating domestic manufacturing to reduce import dependency.
- Wireless:Communication modules face ADC cost volatility pressures that squeeze margins on integrated meter production lines.
- Traditional:Hardwired designs persist in aerospace-defense channels where metrology traceability commands price authority and calibration expertise scarcity extends vendor qualification timelines.
Technology maturity favors Traditional; capability investment flows to IoT Enabled.
End User:
Customer procurement centralization is consolidating vendor relationships and compressing switching cycles across the value chain.
- Utilities:National electricity boards in India and grid operators in Germany centralize multi-year contract awards, displacing fragmented municipal purchasing and favoring scale-capable manufacturers with integrated software platforms.
- Facility Operators:Commercial building portfolios in Japan demand sub-metering solutions with minimal installation disruption, driving Rogowski coil adoption.
- Energy Managers:Industrial process operators require cybersecurity-certified hardware-software platforms for critical infrastructure equipment, reshaping R&D allocation timelines.
- Homeowners:Cost-sensitive residential retrofits in underpenetrated rural Indian distribution networks favor economy-grade analog or basic digital meters.
Contract scale favors Utilities; solution complexity favors Facility Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across watt meter procurement channels. Rural electrification programs in India prioritize cost-optimized units, while German industrial operators absorb premiums for metrology-traceable instruments.
United States
Grid modernization investments drive demand for AMI-interoperable meters with synchrophasor capabilities. FERC mandates shape procurement specifications for investor-owned utilities. Texas and California utilities consolidate multi-year smart meter contracts, favoring vendors with integrated software platforms.
Germany
Industrial process operators require power quality diagnostics with predictive maintenance telemetry. The EU F-Gas Regulation forces thermal management redesigns for refrigerant-cooled instruments. Manufacturing clusters in Bavaria and Baden-Württemberg anchor precision instrument production for export markets.
India
Rural electrification programs accelerate deployment of networked meters with remote-reading capability. The PLI scheme and CEA metering codes under the Electricity Act drive domestic manufacturing scale. Maharashtra and Gujarat state electricity boards bundle AMI contracts exceeding single-source capacity thresholds.
Japan
Commercial building operators adopt Rogowski coil sub-metering where panel shutdown is economically prohibitive. METI efficiency standards shape procurement for facility management integrators. The Kanto and Kansai regions concentrate demand for clamp-on energy management solutions.
China
Smart grid deployments at provincial grid operators create volume demand for digital watt meters. GB standards and dual carbon goals tighten energy efficiency mandates for metering equipment. Manufacturing capacity in the Yangtze River Delta supplies cost-competitive ADC-integrated architectures.
Watt Meter Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the watt meter landscape. The market structure consolidates around integrated semiconductor fabricators with captive silicon supply and assembly-focused instrument makers dependent on external foundry capacity. Three archetypes dominate: precision metrology specialists, industrial automation conglomerates, and semiconductor-integrated platform vendors. Competitive moves center on backward integration into ASIC design and strategic partnerships for calibration IP licensing.
Among precision instrumentation specialists, Keysight Technologies and Fluke Corporation exemplify metrology-traceable positioning where calibration expertise commands price authority. Siemens AG anchors the industrial automation tier with captive silicon sourcing and in-house ASIC design capabilities. Yokogawa Electric Corporation occupies a position bridging precision measurement and process industry applications. These three represent distinct competitive vectors rather than overlapping market contests.
| Leading Market Players |
|---|
| Fluke Corporation |
| Keysight Technologies |
| Texas Instruments |
| Siemens AG |
| Schneider Electric |
| Honeywell International Inc. |
| Yokogawa Electric Corporation |
| HIOKI E.E. Corporation |
| National Instruments Corporation |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for precision ADCs concentrate pricing power with integrated semiconductor fabricators while squeezing margin for assembly-dependent instrument makers across the watt meter value chain.
Pricing Analysis
After-sales calibration contracts and extended warranty tiers drive lifetime value differentiation across industrial-grade meter portfolios. Three-tier pricing structure across premium metrology-traceable, standard networked, and economy analog units reflects IEC 62053 accuracy certification levels and volume procurement scale. Pricing pressure stems from ADC cost volatility in digital architectures, compressing margins on high-volume production lines. Utilities in India exhibit highest price sensitivity due to rural electrification budget constraints, while German process operators absorb premiums for F-Gas compliant refrigerant-cooled instruments.
Supply Chain Analysis
Inventory buffers for precision analog-to-digital converters rarely exceed thirty days, exposing meter manufacturers to foundry allocation disruptions. Taiwan, South Korea, and China anchor semiconductor wafer supply for watt meter ASICs, while Germany and Japan concentrate precision calibration equipment production. Raw material dependencies span silicon substrates, rare-earth magnetic components for current sensors, and refrigerant gases for industrial thermal management. Single-source vulnerability in East Asian foundry capacity creates procurement risk for vendors lacking captive silicon. Distribution runs through direct utility procurement contracts and industrial automation channel partners serving facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from regulatory divergence across FERC, EU F-Gas, and CEA compliance boundaries, creating specialized niches for certification-capable vendors.
For Market Incumbents: Consolidate backward integration into ASIC design to defend margin against semiconductor supply concentration. Siemens AG's captive silicon sourcing exemplifies this defensive posture. Capture calibration IP through strategic laboratory acquisitions to extend qualification timelines for aerospace-defense channels. Threat substitution from IoT-enabled architectures demands software platform investments to retain utility contract scale. For New Entrants and Emerging Players: Lead with non-invasive Rogowski coil sub-metering solutions for German and Japanese commercial building retrofits where panel shutdown costs block incumbent penetration. Target rural Indian distribution networks under CEA metering codes for cost-optimized networked meters with remote-reading capability. Pursue white-label manufacturing partnerships with state electricity boards bundling multi-year AMI contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates divesting non-core instrument divisions lacking semiconductor integration. Long-term viability centers on vendors with captive metrology laboratories and software platform capabilities. Watch F-Gas Regulation phasedown schedules as inflection indicator for solid-state cooling technology adoption and thermal management redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into ASIC Design | Captive silicon sourcing insulates margin from East Asian foundry allocation volatility. |
| Calibration Laboratory Acquisition | Metrology traceability credentials unlock aerospace-defense premium pricing tiers. |
| IoT Platform Development | Wireless telemetry convergence opens predictive maintenance service revenue streams. |
| Rogowski Coil Product Line Expansion | Non-invasive architecture captures German and Japanese commercial retrofit demand. |
| PLI Scheme Manufacturing Localization | Domestic India production reduces import dependency for state electricity board contracts. |
Research Methodology
A standing panel of utility procurement officers, precision instrument calibration technicians, semiconductor supply chain managers, and industrial facility energy managers provided ongoing calibration against secondary data validation. Primary fieldwork combined structured interviews with meter manufacturer product strategists and distribution channel partners. Secondary sources encompassed FERC regulatory filings, EU F-Gas Regulation implementation guidance, CEA metering code amendments, and customs trade data for ADC and current sensor imports. Bottom-up shipment estimates triangulated against top-down utility capital expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated meter type, application, communication technology, and end-user procurement channel dimensions. CAGRs derived from regression analysis of historical deployment trajectories and policy-mandated rollout schedules. Forecast inputs included India's PLI scheme capacity buildout timelines and EU Green Deal smart grid subsidy allocation patterns.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply normalization or accelerated F-Gas phasedown schedules would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and utility procurement centralization trends. Cybersecurity certification complexity for critical infrastructure equipment represents a specific risk factor that could reshape vendor qualification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Digital Water Meters Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Power Quality Meter Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
North America Gas Meter Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
Smart Meters Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
AMI Smart Water Meter Market