
 Waterproof Boots Market | 2026-2036
Waterproof Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Boots Market Analytics
Recycled thermoplastic polyurethane is broadening waterproof boot economics by cutting virgin petroleum dependence while preserving seam-sealed performance. Columbia Sportswear Company leverages vertically integrated sourcing across Asian manufacturing hubs to control cost volatility. Wolverine World Wide anchors its position through captive tannery operations that stabilize leather input quality. Salomon Group differentiates via bonded construction techniques originally developed for alpine ski boots.
Waterproof boots are footwear engineered with hydrophobic membranes, sealed seams, and water-repellent treatments to block liquid ingress while permitting vapor escape, typically rated to withstand submersion depths from 4 to 8 inches for extended periods. Their primary purpose spans occupational safety compliance, outdoor recreation endurance, and urban weather protection across variable climates. Hiking boots lead material innovation as Gore-Tex liners penetrate premium price tiers while synthetic uppers capture mid-market volume from leather alternatives. Work boots concentrate margin pools where ANSI-certified safety toes and electrical hazard ratings command institutional procurement premiums.
EU PPE Regulation 2016/425 mandates CE marking for occupational waterproof boots sold across member states, forcing design standardization for toe protection and slip resistance. EPA per- and polyfluoroalkyl substances scrutiny in the United States is pressuring manufacturers to reformulate durable water repellent chemistries ahead of anticipated restrictions. Stakeholders must monitor membrane chemistry transitions and regional chemical phase-out timelines to preserve product claims and market access.
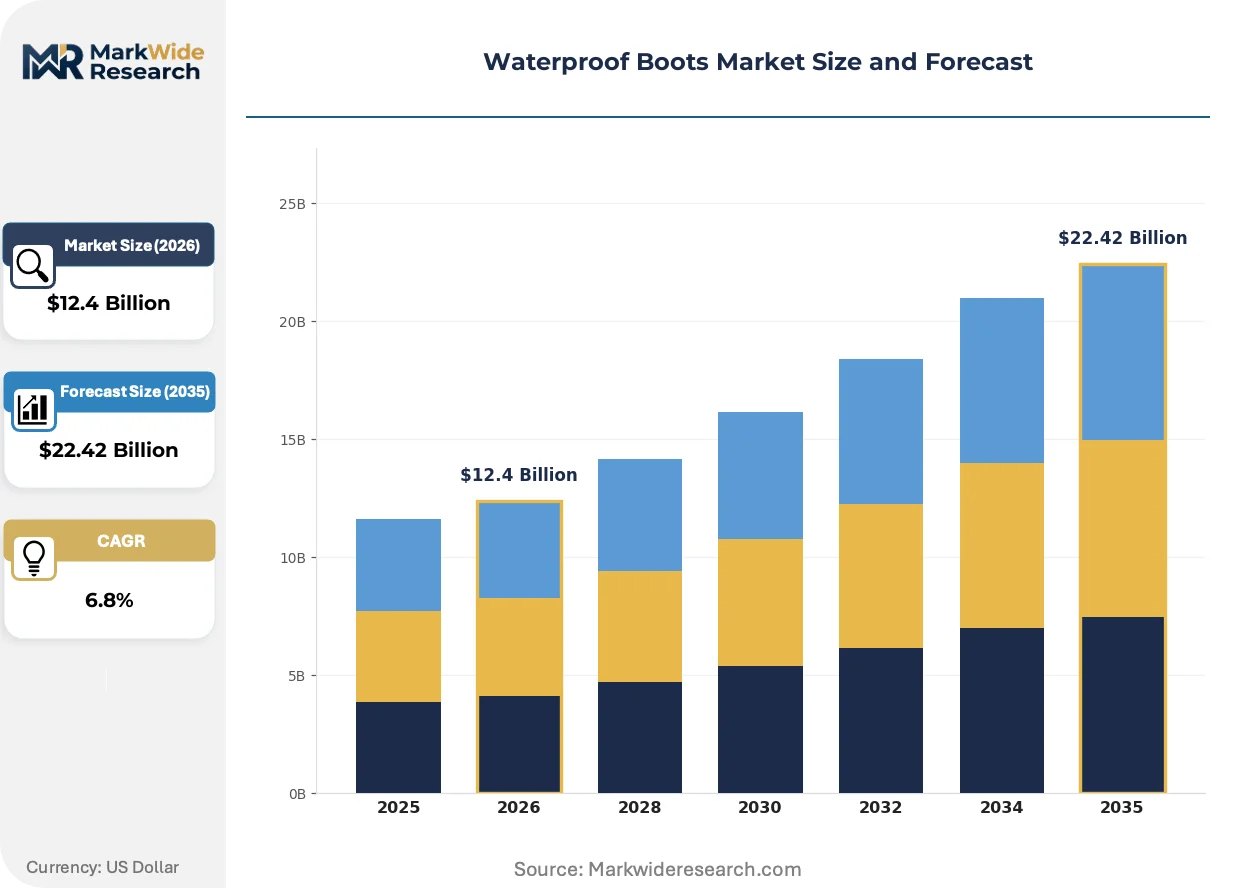
Market Dynamics
Membrane chemistry transitions are forcing manufacturers to rebuild supply chains around PFAS-free alternatives while preserving hydrostatic head ratings that institutional buyers demand.
Growth Catalysts
- EU PPE Regulation 2016/425:Mandatory CE marking for occupational footwear is standardizing procurement specifications across German industrial sites and accelerating replacement cycles for non-compliant inventory.
- Recycled thermoplastic polyurethane:Virgin petroleum displacement through closed-loop material recovery is lowering input cost volatility for mid-market hiking boot production without sacrificing seam-sealed performance.
- United States outdoor recreation participation:Trail maintenance volunteer programs and backcountry permit expansion in national parks are compressing boot replacement intervals among dedicated users.
Market Restraints
- Petrochemical input volatility:Synthetic upper resins and TPU membranes face price instability tied to naphtha cracking margins, squeezing mid-tier manufacturer gross margins.
- Asian membrane supplier concentration:Gore-Tex and eVent manufacturing nodes cluster in China and Taiwan, creating single-source vulnerability for brands lacking alternative hydrophobic liner qualifications.
- REACH chemical registration timelines:Novel PFAS-free DWR chemistries face 18-24 month ECHA approval windows, delaying product reformulation and market entry.
Strategic Opportunities
- Indian industrial safety expansion:BIS certification mandates for construction and mining footwear are opening procurement channels for CE-certified exporters with localized testing partnerships.
- Direct-to-consumer refurbishment services:Membrane re-treatment and sole replacement programs bypass retail margin extraction while capturing lifetime value from premium hiking boot owners.
- Biodegradable midsole foams:Algae-based EVA alternatives combined with bio-based waterproofing treatments align with EU Green Deal circular economy procurement preferences.
Industry Challenges
- Membrane bonding technician scarcity:Hot-melt seam-sealing expertise concentrates in legacy Portuguese and Italian footwear manufacturing clusters, constraining new facility ramp rates.
- Multi-certification testing backlog:Simultaneous ANSI, CE, and CSA safety toe validation creates 6-9 month product launch delays for work boot lines targeting cross-border institutional contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Boots Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Athletic, Hiking, Casual, Work Material: Leather, Synthetic, Rubber, Gore-Tex End User: Men, Women, Kids, Professionals Usage: Outdoor Activities, Industrial Work, Fashion, Sports |
| Companies Covered | Columbia Sportswear Company, VF Corporation, Wolverine World Wide, Deckers Outdoor Corporation, KEEN Footwear, Salomon Group, Hunter Boot Ltd., Bogs Footwear, Muck Boot Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Boots Market Evolving Landscape
Laser-guided cutting systems are reshaping upper panel production by eliminating die-cutting setup waste while enabling small-batch customization that mass manufacturers previously rejected.
Automated membrane bonding workstations are automating the seam-sealing process that previously required skilled manual alignment. Industrial work boot producers in Germany and the United States are adopting these systems to reduce defect rates below 2 percent. This compression of labor-dependent quality variation is enabling consistent CE certification pass rates across high-volume production runs.
EPA scrutiny of per- and polyfluoroalkyl substances is forcing DWR chemistry reformulation ahead of anticipated federal restrictions. Manufacturers are pivoting toward silicone-based and hydrocarbon alternatives that sacrifice some oil repellency for regulatory compliance. Hiking boot brands with premium positioning face the steepest reformulation timeline pressure as their customers associate fluorinated treatments with performance durability.
Specialty outdoor retailers are unbundling boot fitting from transaction fulfillment by charging for custom insole molding and gait analysis separately from product markup. This service revenue model spreads across independent shops in Colorado, Oregon, and British Columbia. The shift protects brick-and-mortar margins against direct-to-consumer pricing while creating switching costs through personalized fit databases.
Waterproof Boots Market Segmentation
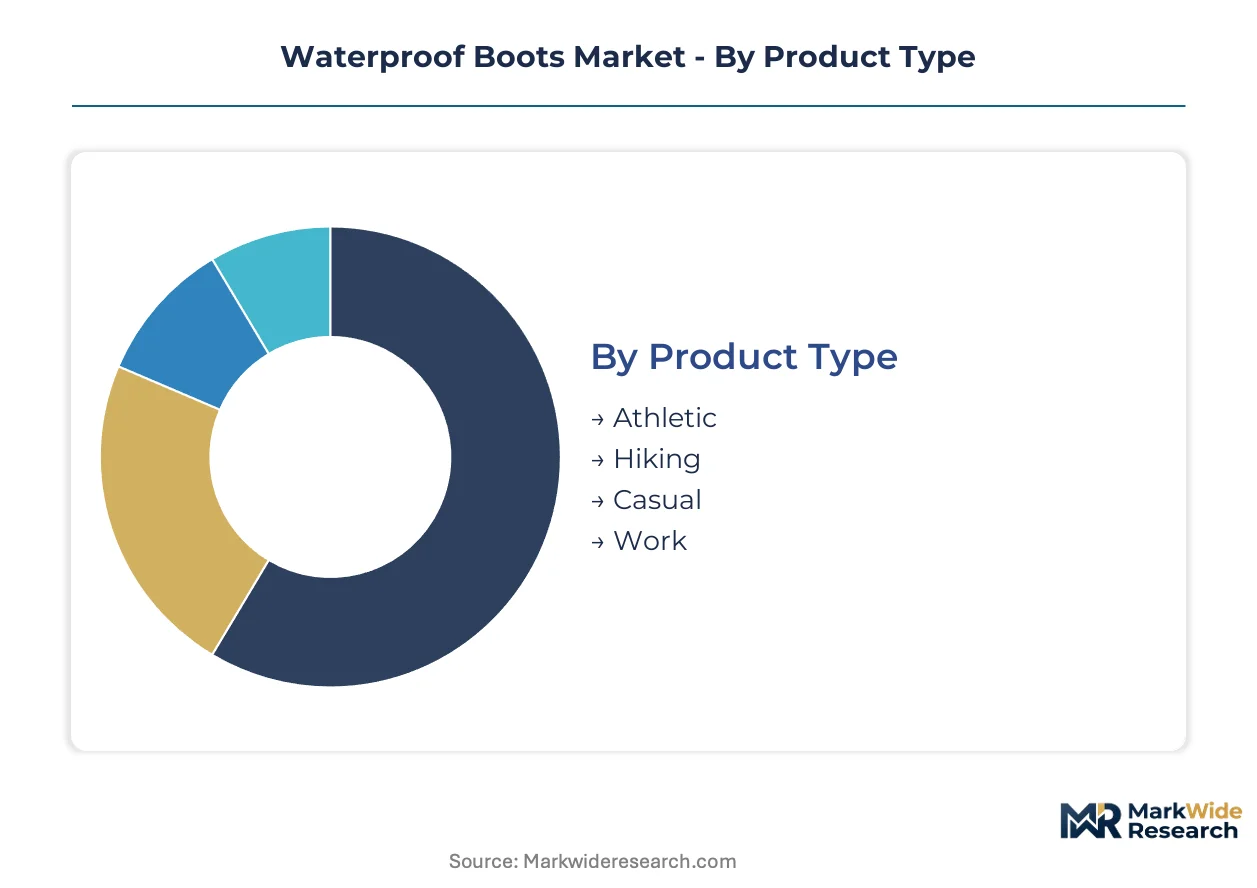
Waterproof boots fragment across four distinct category axes, each reflecting divergent buyer priorities from ANSI safety compliance to trail performance aesthetics. Procurement managers, outdoor enthusiasts, and fashion retailers evaluate entirely different specification sets when sourcing from overlapping manufacturer portfolios.
Product Type:
End-use application dictates membrane thickness, sole lug geometry, and safety certification requirements across institutional and consumer channels.
- Hiking:Mid-cut designs with bonded synthetic uppers and seam-sealed Gore-Tex liners dominate backcountry replacement cycles. United States national park permit expansion compresses replacement intervals among dedicated trail users.
- Work:ANSI-certified safety toes and electrical hazard ratings command procurement premiums from German industrial sites under EU PPE Regulation 2016/425. CE marking mandates accelerate inventory turnover for non-compliant legacy stock.
- Athletic:Lightweight TPU membranes with running-shoe last geometries target urban commuters in wet climates. Breathability metrics outweigh hydrostatic head ratings for this segment's performance claims.
- Casual:Waxed leather uppers with minimal membrane integration serve weatherproof fashion positioning. Style cycles drive purchase frequency rather than functional degradation.
Volume sits with Work; growth tilts toward Hiking.
Material:
Input cost volatility and regulatory chemistry transitions are reshaping supplier relationships across petroleum-derived and bio-based alternatives.
- Synthetic:Recycled thermoplastic polyurethane uppers displace virgin petroleum dependence while preserving seam-sealed performance. Mid-market hiking boot producers leverage closed-loop recovery to stabilize gross margins against naphtha cracking volatility.
- Gore-Tex:Expanded polytetrafluoroethylene membranes set hydrostatic head benchmarks that institutional buyers specify in procurement tenders. Manufacturing concentration in China and Taiwan creates single-source vulnerability for brands lacking alternative liner qualifications.
- Leather:Captive tannery operations at major vertically integrated manufacturers stabilize input quality for premium work boot lines. REACH chemical registration timelines constrain novel tanning agent adoption.
- Rubber:Natural latex and synthetic nitrile blends dominate injection-molded rain boot construction for agricultural and sanitation end-uses. Plantation supply disruptions in Southeast Asia periodically constrain compound availability.
Margin concentrates in Gore-Tex; expansion is steepest in Synthetic.
End User:
Fit geometry, aesthetic preference, and purchase authority distribute unevenly across demographic cohorts with divergent channel behaviors.
- Men:Technical specification focus dominates work and hiking segments with above-average price tolerance for safety certification. Size run standardization simplifies inventory planning for retailers.
- Women:Narrower heel last requirements and colorway diversity drive SKU proliferation that challenges forecast accuracy. Specialty outdoor retailers capture margin through custom insole molding services.
- Professionals:Institutional procurement channels aggregate demand from construction, mining, and utility operators with mandated PPE budgets. BIS certification requirements in India are opening channels for CE-certified exporters.
- Kids:Outgrowth-driven replacement cycles compress useful life to 8-14 months regardless of wear intensity. Parents prioritize price positioning over membrane durability for this segment.
Revenue pools deepest with Professionals; demographic expansion favors Women.
Usage:
Environmental exposure severity and regulatory oversight intensity create tiered performance requirements that manufacturers address through platform engineering.
- Industrial Work:Submersion depth ratings, slip resistance coefficients, and electrical hazard protection face third-party validation for site access eligibility. EPA per- and polyfluoroalkyl substances scrutiny is pressuring DWR chemistry reformulation ahead of anticipated restrictions.
- Outdoor Activities:Vapor transmission rates and ankle support geometry dominate product reviews and retailer assortment decisions. Laser-guided cutting systems now enable small-batch customization previously rejected by mass manufacturers.
- Sports:Alpine ski boot heritage construction techniques transfer to winter hiking variants with rigid sole platforms and insulated liners. Bonded assembly methods developed by Salomon Group differentiate technical positioning.
- Fashion:Weatherproof styling without functional membrane investment captures seasonal trend cycles. Direct-to-consumer refurbishment services bypass retail margin extraction for premium positioning.
Certification burden is heaviest in Industrial Work; brand heat concentrates in Outdoor Activities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Dongguan and Quanzhou concentrate membrane lamination capacity for footwear exporters serving North American and European retail channels.
United States
National park permit expansion and trail maintenance volunteer programs compress replacement cycles for backcountry hiking boots. EPA scrutiny of per- and polyfluoroalkyl substances pressures manufacturers to reformulate durable water repellent chemistries ahead of anticipated federal restrictions. Portland, Oregon and Denver, Colorado anchor specialty outdoor retail clusters where independent shops capture margin through custom insole molding services.
Germany
Industrial work sites expand protective footwear procurement under EU PPE Regulation 2016/425 mandates for CE marking. ECHA registration timelines for novel PFAS-free DWR chemistries create 18-24 month approval windows that delay product reformulation. Bavaria and North Rhine-Westphalia concentrate automated membrane bonding workstation adoption among work boot producers seeking sub-2 percent defect rates.
China
Vertically integrated manufacturers leverage Dongguan and Quanzhou special economic zones to control cost volatility across synthetic upper and TPU membrane production. NMPA-equivalent standards for occupational footwear align with export certification requirements for European and North American markets. Yangtze River Delta clusters host Gore-Tex and eVent manufacturing nodes that create single-source vulnerability for brands lacking alternative hydrophobic liner qualifications.
India
BIS certification mandates for construction and mining footwear open procurement channels for CE-certified exporters with localized testing partnerships. Central Electricity Authority regulations for utility worker protective equipment accelerate institutional procurement cycles. Maharashtra and Gujarat industrial corridors concentrate safety boot manufacturing for domestic infrastructure expansion and export qualification.
Japan
METI industrial standards for occupational footwear align with ISO benchmarks that facilitate export qualification for premium work boot lines. Aging workforce demographics in construction and utilities drive replacement demand for lightweight synthetic alternatives. Kansai region manufacturing clusters preserve hot-melt seam-sealing expertise that constrains new facility ramp rates elsewhere.
Waterproof Boots Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium hiking and work boot categories consolidating around vertically integrated players while mid-market volume fragments across OEM suppliers. Three archetypes dominate: membrane technology licensors controlling hydrostatic head benchmarks, captive tannery operators stabilizing leather input quality, and synthetic material specialists leveraging recycled thermoplastic polyurethane closed-loop recovery. Competitive moves concentrate on backward integration into membrane manufacturing and geographic expansion through localized testing partnerships for BIS and CE certification.
Among North American branded specialists, Columbia Sportswear Company and Wolverine World Wide exemplify divergent sourcing strategies—one leveraging vertically integrated Asian manufacturing hubs, the other anchoring position through captive tannery operations. VF Corporation sits within the portfolio-holding archetype, aggregating multiple footwear brands under shared distribution infrastructure. Salomon Group represents the alpine-heritage technical specialist, transferring bonded construction techniques from ski boot platforms to winter hiking variants.
| Leading Market Players |
|---|
| Columbia Sportswear Company |
| VF Corporation |
| Wolverine World Wide |
| Deckers Outdoor Corporation |
| KEEN Footwear |
| Salomon Group |
| Hunter Boot Ltd. |
| Bogs Footwear |
| Muck Boot Company |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Portugal and Italy preserve hot-melt seam-sealing expertise that commands pricing premiums from brands seeking CE certification compliance without automated workstation capital expenditure. This ownership pattern concentrates supply-side pricing power while forcing multinational competitors into equipment-heavy automation investments to bypass labor scarcity.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to CE-certified work boot orders from German industrial sites facing EU PPE Regulation 2016/425 replacement deadlines, while spot inventory of non-compliant legacy stock trades at distressed levels. Pricing stratifies across premium Gore-Tex-lined hiking variants, standard synthetic-upper mid-market offerings, and economy rain boots with minimal membrane investment. Cost compression in the mid-tier is intensifying because naphtha-derived TPU membrane inputs face cracking margin volatility. Institutional procurement managers demonstrate lowest price sensitivity due to mandated PPE budgets, whereas parents purchasing kids' outgrowth-driven replacements prioritize unit economics over durability claims.
Supply Chain Analysis
Indian domestic-content mandates under BIS certification requirements are reshaping sourcing patterns for construction and mining footwear, forcing CE-certified exporters to establish localized testing partnerships rather than pure export models. Manufacturing gravity centers on China for Gore-Tex and eVent membrane lamination, Taiwan for ePTFE substrate production, and Vietnam for synthetic upper assembly. Raw material flows draw from petroleum-derived TPU resins, natural rubber plantations in Southeast Asia, and chrome-tanned leather from captive tannery operations in the United States. Single-source vulnerability concentrates in Yangtze River Delta membrane nodes. Distribution runs through specialty outdoor retailers in Colorado and Oregon, institutional procurement channels for industrial safety, and direct-to-consumer refurbishment services capturing lifetime value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where membrane chemistry control and captive tannery operations determine margin capture against input volatility. Players are pursuing backward integration into PFAS-free DWR formulation to preempt EPA restrictions and preserve product claims.
For Market Incumbents: Anchor position through automated membrane bonding workstation deployment in Bavaria and North Rhine-Westphalia to achieve sub-2 percent defect rates and consistent CE certification pass rates. Invest in Portuguese and Italian hot-melt seam-sealing technician apprenticeships to constrain competitor facility ramp rates. Defend against synthetic-upstart displacement by emphasizing captive leather quality stability and heritage construction credibility. For New Entrants and Emerging Players: Enter via Indian BIS certification partnerships targeting Maharashtra and Gujarat industrial corridor safety boot procurement under Central Electricity Authority utility regulations. Exploit white-space in direct-to-consumer refurbishment services for premium hiking boot membrane re-treatment and sole replacement, bypassing retail margin extraction. Capture urban commuter athletic segment through lightweight TPU membrane positioning with breathability metrics exceeding hydrostatic head focus. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated membrane bonding equipment owners in Germany and the United States over labor-dependent Portuguese and Italian specialists facing technician scarcity. Long-term viability over the next decade hinges on PFAS-free chemistry transition completion and regional certification localization. Watch EPA final rulemaking on per- and polyfluoroalkyl substances as the inflection indicator for DWR reformulation capex cycles and stranded inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free DWR Reformulation | EPA scrutiny forces silicone-based chemistry pivots ahead of anticipated federal restrictions. |
| Automated Membrane Bonding Deployment | German producers adopt workstations to compress defect rates below CE certification thresholds. |
| Indian BIS Localization Partnership | CE-certified exporters establish testing relationships to access Maharashtra construction procurement. |
| Direct-to-Consumer Refurbishment Launch | Membrane re-treatment programs capture lifetime value from Colorado and Oregon specialty retail customers. |
| Recycled TPU Closed-Loop Integration | Mid-market hiking boot producers stabilize gross margins against naphtha cracking volatility. |
Research Methodology
Independent corroboration across membrane supplier technical documentation, EU PPE Regulation 2016/425 compliance filings, and EPA chemical substance databases underwrites the qualitative findings. Primary interviews with footwear brand sourcing directors, Portuguese and Italian hot-melt seam-sealing technicians, German industrial safety procurement managers, and specialty outdoor retail buyers in Colorado and Oregon combined with secondary validation. Secondary sources include customs and trade data for synthetic upper and TPU membrane flows, SEC 10-K filings from vertically integrated manufacturers, and ECHA REACH registration timelines for novel DWR chemistries. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Rate-of-change decomposition across the analysis window isolates replacement cycle compression from permit expansion, regulatory-driven inventory turnover, and material substitution effects. Segmentation dimensions modeled include product type, material chemistry, end-user demographic, and usage environment severity. CAGRs derive from installed base erosion rates, certification mandate phase-in schedules, and regional outdoor participation trend extrapolation. Forecast inputs incorporate naphtha cracking margin volatility projections and ECHA approval window duration assumptions for PFAS-free alternatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA restriction timelines or Southeast Asian natural rubber supply disruptions. Assumptions reflect current regulatory trajectories and membrane supplier concentration patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Work Boots Market
Protective Gear
Heated Goggles Market
Protective Gear
Tactical Boots Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Military Boots Market
Protective Gear
Hand Gloves Market
Protective Gear
Helmet Lining Market
Protective Gear
Helmets Market
Protective Gear
Pet Control Devices Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Combat Boots Market
Protective Gear
Diving Suits Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Personal Flotation Devices Market