
 Helmets Market | 2026-2036
Helmets Market Size, Share, and Industry Trends Forecast 2026-2036
Helmets Market Intelligence
The gap between premium and commodity helmet tiers is expanding. Arai Helmet Limited and Shoei Co., Ltd. dominate the high-end segment through handcrafted shell construction and proprietary composite blends, while Bell Helmets and LS2 Helmets compete aggressively on price in volume-driven markets. HJC Helmets occupies the middle ground with modular designs that balance certification grades against accessible price points.
A helmet is a protective headgear device engineered with an outer shell of polycarbonate, fiberglass, or carbon fiber bonded to an inner liner of expanded polystyrene (EPS) foam, designed to absorb and dissipate impact energy across motorcycling, cycling, industrial, and sports applications. Full-face configurations command the largest revenue share due to superior chin-bar protection and aerodynamic stability at highway speeds, while carbon fiber materials represent the fastest-growing material segment as manufacturers reduce weight without sacrificing ECE 22.06 or Snell certification thresholds. Modular helmets are gaining share among urban motorcyclists who demand versatility across commuting and touring use cases.
Regulatory frameworks from the U.S. Department of Transportation (DOT), the United Nations Economic Commission for Europe (ECE), and India's Bureau of Indian Standards (BIS) mandate minimum impact-absorption thresholds, rotational-force testing, and labeling protocols that dictate product development timelines and market access eligibility. Compliance costs are rising as ECE 22.06 introduces oblique-impact testing and stricter visor optical standards, forcing smaller manufacturers to outsource certification or exit European distribution channels. Stakeholders must monitor regulatory divergence between DOT's self-certification model and ECE's third-party homologation system, as this friction determines which production lines can serve multiple jurisdictions without redundant tooling investments.
Market Dynamics
ECE 22.06's oblique-impact testing mandates are compressing product development cycles and forcing shell material transitions across European distribution channels, while Indian BIS enforcement accelerates replacement demand in two-wheeler dense urban corridors.
Growth Catalysts
- Regulatory Mandate Intensification:India's BIS helmet certification enforcement in tier-2 and tier-3 cities is accelerating replacement cycles among commuter motorcyclists who previously operated with non-certified headgear.
- Material Science Advancement:Multi-density EPS liner configurations are enabling manufacturers to meet ECE 22.06's rotational-force thresholds without adding shell weight or compromising ventilation channels.
- Two-Wheeler Ownership Expansion:Emerging economy urbanization in Vietnam, Indonesia, and Nigeria is creating first-time helmet demand among delivery fleet operators and informal transport workers.
Market Restraints
- Certification Cost Burden:ECE 22.06 third-party homologation expenses are excluding smaller manufacturers from European distribution, concentrating supply among firms with captive testing laboratories.
- Raw Material Concentration:Carbon fiber prepreg supply is concentrated among Japanese and South Korean suppliers, exposing helmet manufacturers to aerospace sector demand spikes and allocation rationing.
- Substitution Pressure:Shared mobility adoption in Chinese and Indian megacities is reducing personal two-wheeler ownership rates among younger urban demographics who prefer electric scooter rentals with provided helmets.
Strategic Opportunities
- Smart Helmet Integration:Heads-up display and Bluetooth communication modules are creating premium price tiers among touring motorcyclists in Germany and the United States who demand navigation and intercom functionality.
- Industrial Safety Expansion:Construction and mining sectors in Brazil and South Africa are adopting full-brim safety helmets with integrated cooling systems as occupational safety enforcement tightens.
- Direct-to-Consumer Channels:Modular helmet configurations with customizable fit systems are bypassing traditional powersports retailers through manufacturer-owned digital platforms in Australia and Canada.
Industry Challenges
- Homologation Timeline Compression:ECE 22.06's expanded test matrix is extending certification cycles from 8 months to 14 months, delaying product launches and inventory positioning for seasonal buying windows.
- Skilled Pattern-Making Scarcity:Handcrafted fiberglass shell production requires specialized technicians whose training pipelines have contracted in Japan and Italy, constraining premium segment volume scaling.
- Cross-Border Testing Recognition:DOT self-certification and ECE third-party homologation remain non-harmonized, forcing redundant tooling investments for manufacturers serving both North American and European distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helmets Market |
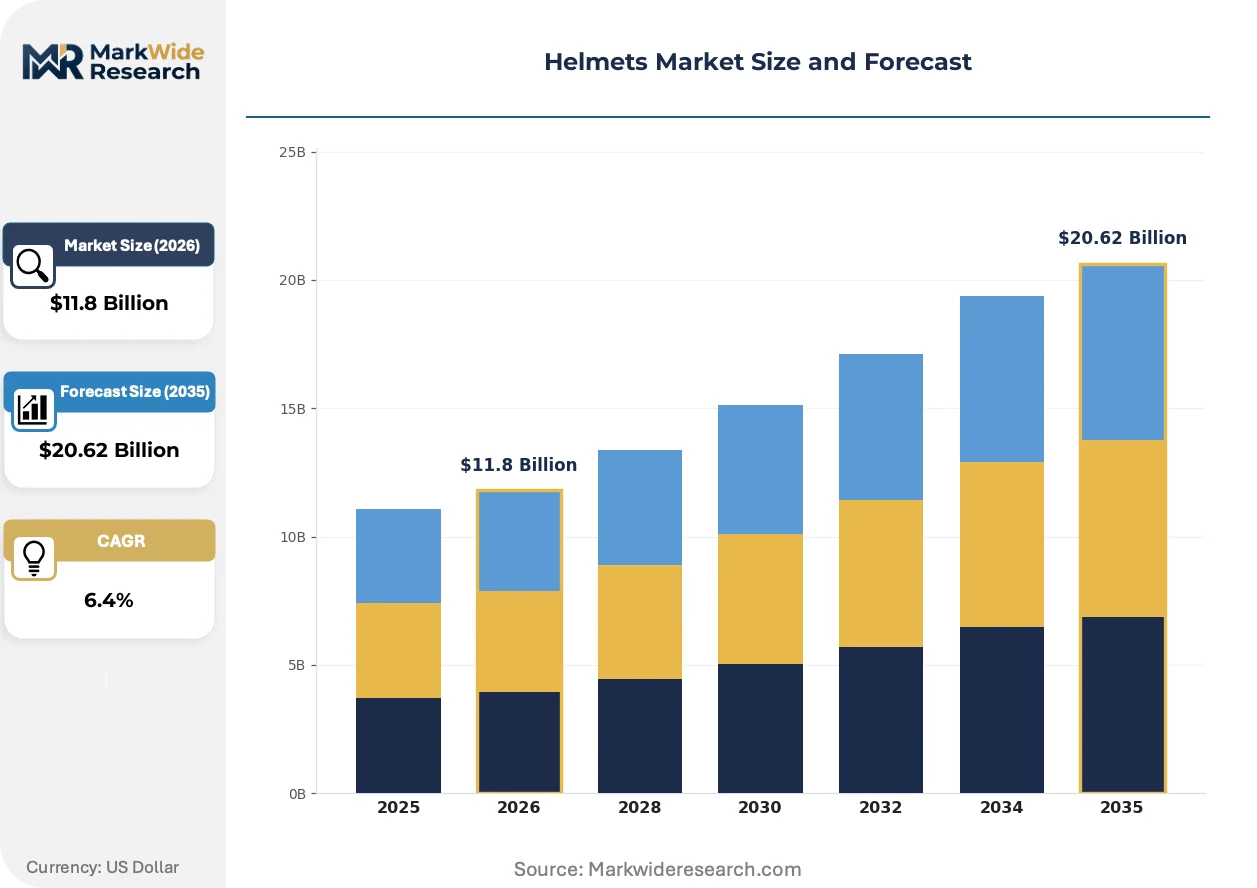
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Face, Open Face, Modular, Half Helmet End User: Motorcyclists, Cyclists, Construction Workers, Sports Enthusiasts Material: Polycarbonate, Fiberglass, Carbon Fiber, EPS Foam Application: Motorcycling, Biking, Industrial Safety, Sports |
| Companies Covered | Shoei Co., Ltd., Arai Helmet Limited, Bell Helmets, AGV (Dainese), Schuberth GmbH, HJC Helmets, Shark Helmets, Nolan Helmets, LS2 Helmets, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helmets Market Strategic Shifts & Innovations
Active safety integration and biomaterial substitution are redefining helmet architecture, while regulatory fragmentation forces parallel certification investments that reshape competitive positioning across price tiers.
Multi-density expanded polystyrene liners with tuned compression zones are absorbing oblique-impact energy in ways that satisfy ECE 22.06's rotational-force criteria. Premium manufacturers in Japan and Germany are adopting these configurations fastest, compressing the performance gap between mid-tier and high-end shell constructions. The technology is absorbing market share from traditional single-density liners in touring and racing segments where certification grades determine retail placement.
REACH chemical restrictions on certain flame retardants and plasticizers are forcing EPS foam reformulation across European supply chains. Manufacturers must requalify liner materials with notified bodies, extending development timelines and raising raw material substitution costs. Modular helmet categories face disproportionate impact because their hinge mechanisms and dual-shell configurations multiply component compliance touchpoints.
Urban commuters in Indian and Vietnamese cities are compressing replacement cycles from 4-5 years to 2-3 years as BIS enforcement and aesthetic preference shifts accelerate turnover. Digital-native buyers are bypassing traditional brick-and-mortar channels for manufacturer-direct platforms that offer fit-scanning applications and customization interfaces. This behavioral shift is most visible in Bengaluru and Ho Chi Minh City, where two-wheeler density and smartphone penetration intersect to enable virtual try-on adoption.
Helmets Market Segmentation
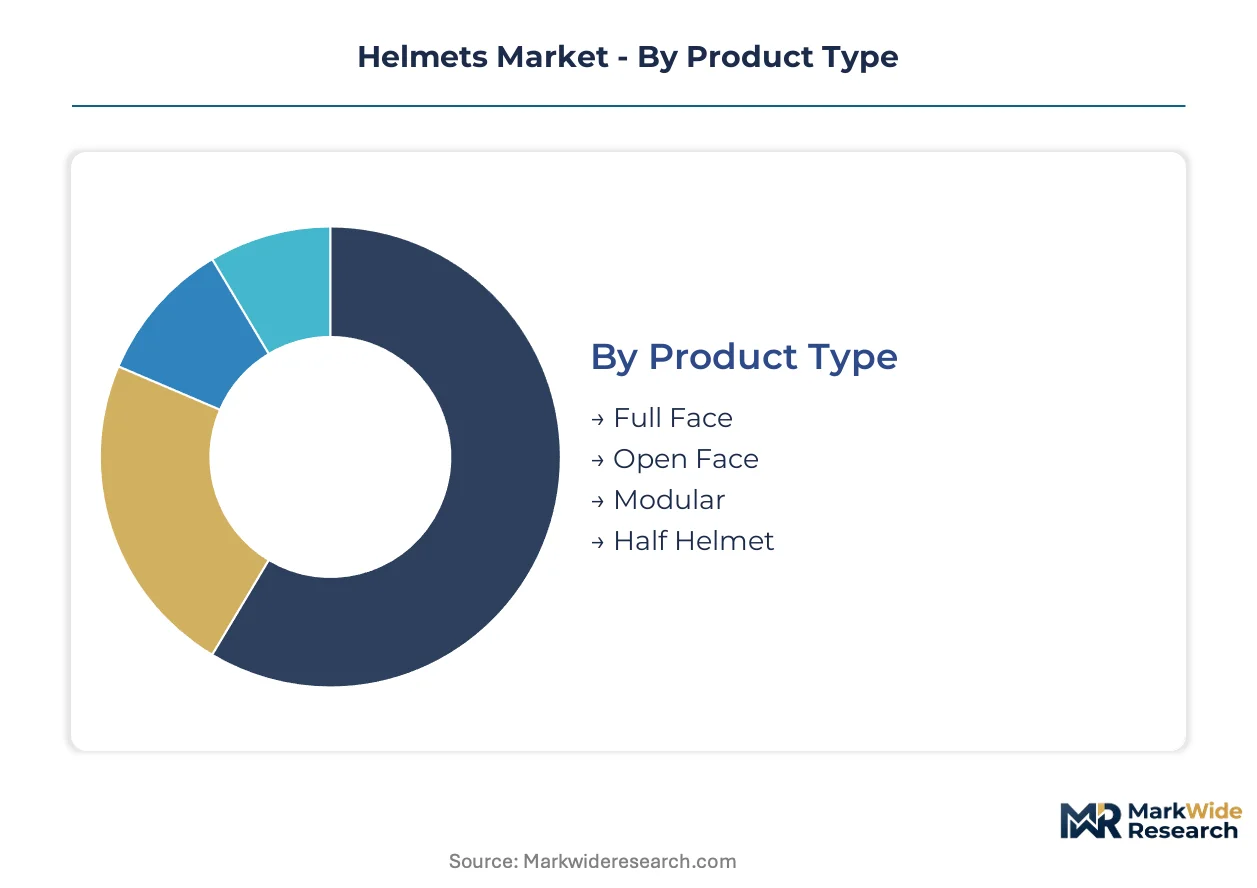
Helmet purchasing decisions diverge sharply across use cases, with motorcyclists prioritizing aerodynamic stability and certification grades while industrial buyers emphasize ventilation systems and regulatory compliance. Material selection and product architecture determine which distribution channels manufacturers can access and which price tiers they can command.
Product Type:
Buyer risk tolerance and speed exposure dictate shell configuration preferences across commuting, touring, and racing applications.
- Full Face:Enclosed shell design with integrated chin bar and visor mechanism provides maximum facial protection and highway-speed aerodynamics. Demand concentrates among German and Japanese touring motorcyclists who prioritize ECE 22.06 certification grades for autobahn and expressway riding.
- Modular:Hinge-enabled chin bar pivots upward to convert between full-face and open configurations without helmet removal. Urban commuters in Bengaluru and Ho Chi Minh City are adopting these for versatility across stop-and-go traffic and highway segments.
- Open Face:Three-quarter coverage shell exposes the chin and jawline for improved ventilation and peripheral vision. Classic motorcycle enthusiasts and scooter operators in Mediterranean European cities favor these for low-speed urban maneuverability.
- Half Helmet:Minimalist skull cap design meets only basic DOT certification with no facial or ear protection. Price-sensitive delivery fleet operators in Nigerian and Indonesian markets use these where enforcement of comprehensive standards remains inconsistent.
Volume sits with Full Face configurations; growth tilts toward Modular designs.
End User:
Professional obligation versus recreational choice separates institutional procurement from individual purchase behavior.
- Motorcyclists:Encompasses private owners, commercial delivery operators, and touring enthusiasts who self-select protection levels based on speed exposure and regulatory environment. Replacement cycles compress from wear damage, impact incidents, or certification updates rather than calendar aging alone.
- Cyclists:Road racers, mountain bikers, and urban commuters demand ultralight shells with extensive ventilation ports. European markets lead specification intensity as competitive cycling culture drives MIPS rotational-impact adoption and aesthetic customization.
- Construction Workers:Site safety mandates in Brazil and South Africa are accelerating full-brim hard hat replacement with integrated cooling and communication systems. Procurement runs through employer programs rather than individual purchase.
- Sports Enthusiasts:Skiing, American football, hockey, and climbing participants require sport-specific impact geometries and retention systems. Seasonal demand patterns and team bulk orders distinguish this segment from year-round individual replacement.
Construction Workers drive institutional volume; Motorcyclists deliver the steepest expansion trajectory.
Material:
Shell composition determines weight-performance tradeoffs and which certification thresholds manufacturers can achieve.
- Carbon Fiber:Woven composite layup delivers highest strength-to-weight ratio for racing and premium touring applications. Japanese and South Korean prepreg supply concentration creates allocation vulnerability when aerospace demand spikes.
- Fiberglass:Hand-laminated or chopped-strand construction balances impact absorption with moderate weight for mid-premium positioning. Italian and Japanese production of these shells faces skilled technician scarcity that constrains volume scaling.
- Polycarbonate:Injection-molded thermoplastic enables high-volume, low-cost production for entry-level and developing market distribution. Mass-market manufacturers in China and India dominate this tier through automated shell forming.
- EPS Foam:Expanded polystyrene liner material bonds to shell interiors for impact energy dissipation; multi-density configurations now satisfy ECE 22.06 rotational-force criteria without weight penalties. REACH chemical restrictions are forcing reformulation across European supply chains.
Polycarbonate commands production volume; Carbon Fiber climbs the fastest on weight-reduction priorities.
Application:
Activity-specific hazard profiles determine whether buyers prioritize penetration resistance, rotational-force management, or environmental sealing.
- Motorcycling:Highway-speed impact protection and aerodynamic stability requirements drive full-face and modular adoption. Regulatory divergence between DOT self-certification and ECE third-party homologation forces parallel product lines for North American versus European distribution.
- Biking:Low-speed rotational impacts and ventilation priority distinguish cycling helmet architecture from motorcycling designs. MIPS and similar slip-plane technologies are penetrating this segment faster than motorcycling due to lower certification barriers.
- Industrial Safety:Falling object protection and electrical insulation standards govern hard hat specifications. Brazilian and South African mining and construction enforcement tightening is accelerating replacement of legacy suspension systems.
- Sports:Activity-specific standards from football to hockey to climbing create fragmented certification landscapes. Team and league procurement contracts concentrate volume with manufacturers holding multi-sport certification capabilities.
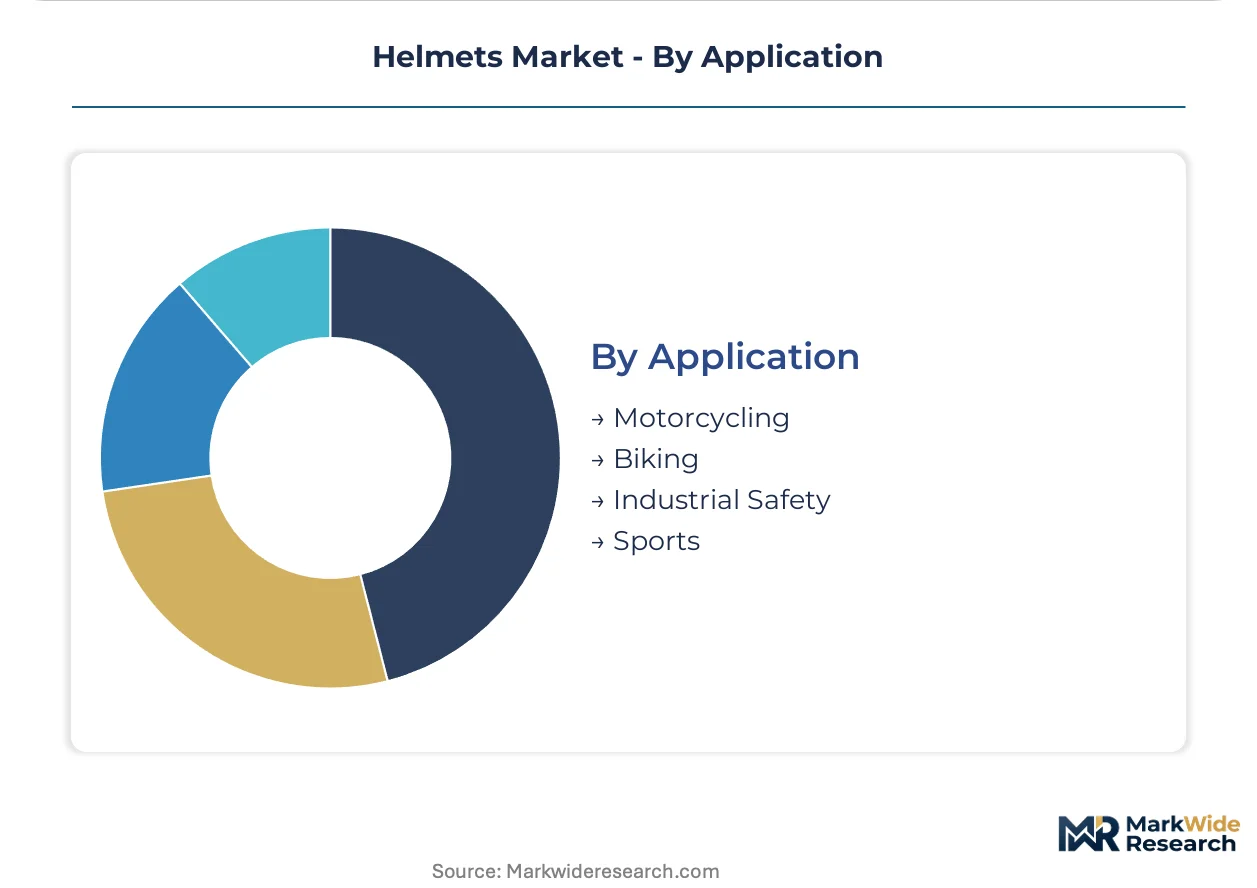
Motorcycling anchors revenue concentration; Industrial Safety gains share fastest on regulatory enforcement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's two-wheeler density and smartphone penetration intersect to create India's most dynamic helmet replacement corridor, while Ho Chi Minh City anchors Southeast Asian demand for modular configurations suited to stop-and-go traffic.
United States
Highway touring culture and touring motorcyclist demographics sustain premium full-face demand across the Interstate corridor. NHTSA maintains DOT self-certification standards that diverge from European homologation protocols. Southern California's powersports retail clusters concentrate inventory positioning for seasonal buying windows.
Germany
Autobahn speed exposure drives ECE 22.06 certification intensity among touring enthusiasts. KBA enforcement of third-party homologation excludes non-compliant imports from distribution channels. Bavaria's manufacturing belt hosts captive testing laboratories serving premium European brands.
India
BIS enforcement in tier-2 and tier-3 cities accelerates replacement cycles among commuter motorcyclists. The Bureau of Indian Standards mandates IS 4151 certification for all two-wheeler helmets sold domestically. Maharashtra's Pune-Nashik industrial corridor concentrates polycarbonate shell injection molding capacity.
Vietnam
Delivery fleet expansion and informal transport worker growth generate first-time helmet demand in urban corridors. The country's national standards body enforces QCVN helmet specifications with increasing rigor in Hanoi and Ho Chi Minh City. The Mekong Delta's assembly operations supply price-sensitive ASEAN distribution.
Brazil
Construction and mining sector expansion drives institutional procurement of full-brim safety helmets. ANVISA-aligned occupational safety enforcement tightens suspension system replacement protocols. São Paulo state's industrial safety equipment distributors aggregate volume for Latin American re-export.
Helmets Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification grade and shell material sophistication. The vendor base stratifies into three tiers: handcrafted composite specialists, automated polycarbonate volume producers, and modular design generalists. Consolidation pressure concentrates among mid-tier firms facing ECE 22.06 homologation cost barriers. Dominant competitive moves include geographic licensing partnerships and captive testing laboratory acquisition.
Within the handcrafted composite tier, Shoei Co., Ltd. and Arai Helmet Limited represent Japanese specialists whose proprietary shell construction occupies premium positioning. Bell Helmets exemplifies the volume-accessible archetype through its North American manufacturing heritage and broad distribution footprint. These three anchors illustrate how certification grade and production method determine margin capture across the price spectrum.
| Leading Market Players |
|---|
| Shoei Co., Ltd. |
| Arai Helmet Limited |
| Bell Helmets |
| AGV (Dainese) |
| Schuberth GmbH |
| HJC Helmets |
| Shark Helmets |
| Nolan Helmets |
| LS2 Helmets |
| Others |
Cost & Logistics Intelligence
Carbon fiber prepreg pricing volatility cascades through helmet manufacturing tiers, compressing margins at premium composite specialists while polycarbonate injection molders absorb cost fluctuations through volume scale. ECE 22.06 compliance investments and Japanese supplier allocation rationing are widening the cost gap between handcrafted shell producers and automated thermoplastic operations.
Pricing Analysis
Certification-grade anchoring determines price positioning across the helmet market, with ECE 22.06 homologation separating premium handcrafted composite tiers from DOT self-certified polycarbonate volumes. Price differentiation stems from shell material sophistication and third-party testing burden, with carbon fiber configurations commanding substantial premiums over injection-molded alternatives. Pricing pressure intensifies among mid-tier modular manufacturers facing compressed development timelines and extended certification cycles. Fleet procurement managers in emerging economies exhibit highest price sensitivity, while German autobahn touring enthusiasts demonstrate lowest elasticity for certified premium protection.
Supply Chain Analysis
Direct-to-retail and manufacturer-owned digital platforms are displacing traditional powersports distributor networks in Australia and Canada. Raw material sourcing concentrates in Japan and South Korea for carbon fiber prepreg, China and India for polycarbonate resin, and Italy and Japan for handcrafted fiberglass shell production. The supply chain rests on aerospace sector demand spikes that trigger carbon fiber allocation rationing, exposing helmet manufacturers to input scarcity. Distribution runs through OEM accessory channels, independent powersports retailers, and emerging direct-to-consumer platforms with fit-scanning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helmet supply constraints are tightening around skilled pattern-making technician scarcity and ECE 22.06 homologation bottlenecks, propping pricing power among captive laboratory operators while excluding smaller competitors from European distribution.
For Market Incumbents: Deepen captive testing laboratory investments to compress certification timelines and defend European market access against homologation-excluded rivals. Acquire distressed mid-tier modular specialists facing ECE 22.06 cost barriers, consolidating volume positions while integrating their distribution footprints. Prioritize backward integration into carbon fiber prepreg sourcing to mitigate aerospace sector demand spike exposure.
For New Entrants and Emerging Players: Smart helmet communication modules offer entry pathways into premium touring segments where German and United States buyers prioritize navigation and intercom functionality over commodity protection. Target industrial safety expansion in Brazilian and South African construction sectors, where employer-mandated procurement programs bypass consumer price sensitivity. Pursue direct-to-consumer digital platforms with fit-scanning applications to circumvent established powersports retail gatekeepers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier modular manufacturers with existing BIS or DOT certification but insufficient capital for ECE 22.06 homologation investment, particularly in Indian and Vietnamese urban corridors. Long-term viability hinges on regulatory compliance scalability across multiple jurisdiction frameworks. Monitor carbon fiber prepreg allocation announcements from Japanese suppliers as inflection indicators for premium segment margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Laboratory Acquisition | ECE 22.06 homologation bottlenecks compress timelines for firms with in-house certification capabilities. |
| Smart Helmet Module Integration | Bluetooth communication and heads-up displays create premium price tiers among German touring motorcyclists. |
| Direct-to-Consumer Platform Launch | Manufacturer-owned digital channels with fit-scanning bypass traditional powersports retailer margins in Australia. |
| Industrial Safety Certification Expansion | ANVISA-aligned enforcement in Brazilian mining drives institutional procurement of full-brim cooling helmets. |
| Carbon Fiber Supply Agreement | Long-term prepreg contracts with Japanese suppliers hedge against aerospace sector demand spike rationing. |
Research Approach
Multi-period observation of BIS enforcement intensity, ECE 22.06 adoption timelines, and carbon fiber prepreg allocation patterns anchored the trend analysis, supplemented by interviews with helmet manufacturing executives, regulatory affairs specialists at notified bodies, powersports retail buyers, and industrial safety procurement managers. Secondary validation drew from KBA homologation databases, BIS certification registries, customs trade records, and SEC filings of publicly traded component suppliers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-weighting across product type, material composition, end-user archetype, and geographic regulatory cluster determined volume and value distributions throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycle compression, two-wheeler ownership trajectories, and certification mandate adoption curves. Industry-specific inputs included ECE 22.06 test matrix expansion impacts on development timelines and REACH chemical restriction effects on EPS foam reformulation costs.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions, abrupt carbon fiber supply disruptions from geopolitical events, and technological substitution from shared mobility platform expansion. Forecasts reflect assumptions about enforcement continuity and material science advancement rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Work Boots Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Hand Gloves Market
Protective Gear
Earplug Distributor Market
Protective Gear
Insect Repellent Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Combat Boots Market
Protective Gear
Waterproof Cases Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Flavored Condoms Market
Protective Gear
Fluorescent Reflective Vest Market