
 Antistatic Protection Shoes Market | 2026-2036
Antistatic Protection Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Antistatic Protection Shoes Market Insights
Asset-light leasing models for industrial safety footwear is reconfiguring competitive dynamics by lowering capital barriers for mid-sized distributors. Honeywell leverages its captive supply chain to control raw material costs across leather and synthetic grades. ELTEN GmbH anchors its position through specialized German engineering in composite toe-cap integration. MengKe Safety Co.,Ltd competes on manufacturing scale from its Dongguan production base.
Antistatic protection shoes incorporate conductive or static-dissipative elements typically measured at 10^5 to 10^8 ohms resistance, engineered to prevent electrostatic discharge damage in sensitive production environments. Leather material segments sustain premium pricing through durability advantages in chemical-exposure settings, while synthetic variants lead volume growth in electronics cleanroom applications. Manufacturing end-use dominates current procurement, though pharmaceutical demand accelerates fastest as aseptic processing expands.
OSHA workplace safety mandates and IEC 61340 electrostatic standards shape North American product compliance requirements, while China's GB standards and EU CE marking govern access to their respective markets. Stakeholders must monitor how evolving semiconductor fabrication protocols in East Asia redefine static-control thresholds for footwear certification.
Market Dynamics
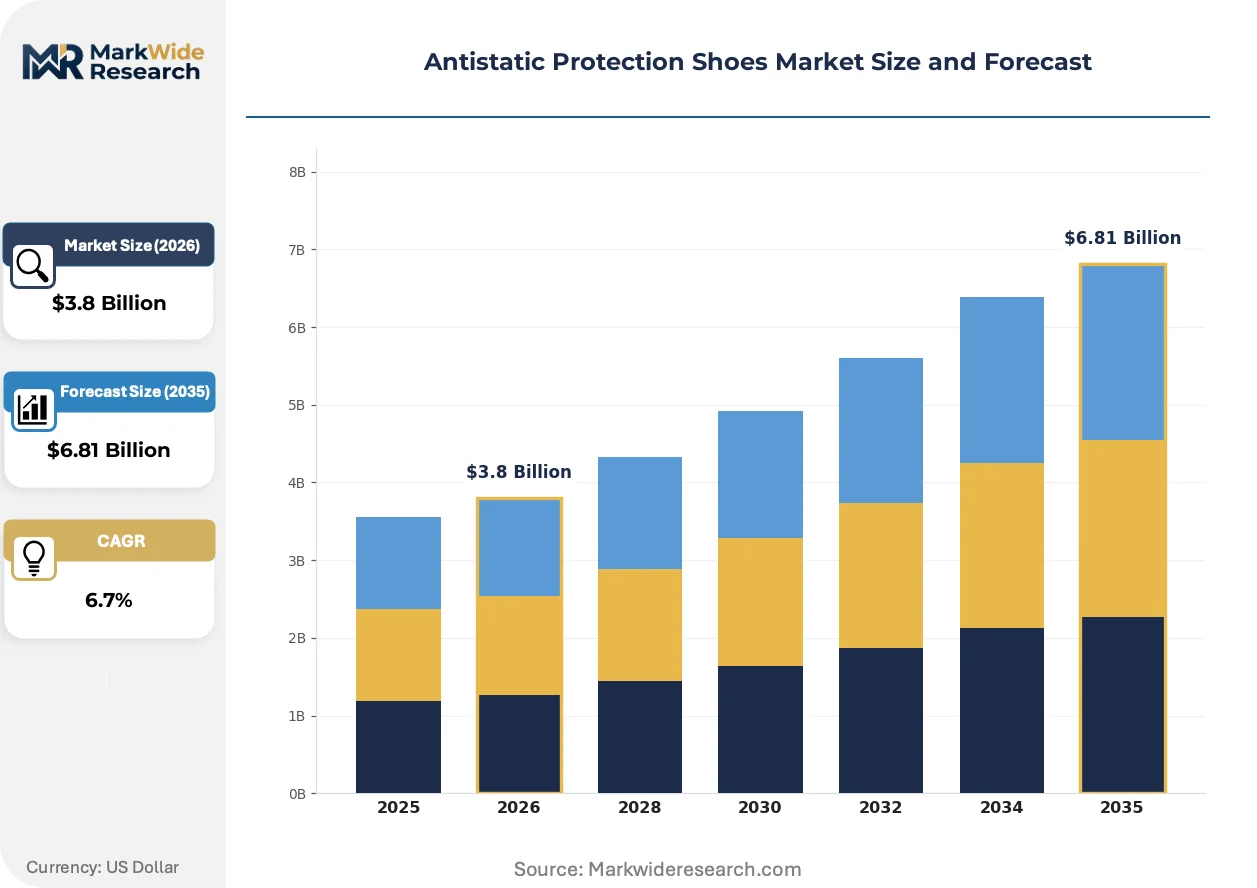
Semiconductor fabrication expansion across East Asia is compressing procurement cycles for static-control footwear as fabs demand faster certification turnaround and localized supply.
Growth Catalysts
- IEC 61340-5-1 standardization:Harmonized ESD protection protocols across electronics manufacturing are mandating conductive footwear deployment in cleanroom environments.
- China's domestic chipmaking surge:Government-backed semiconductor self-sufficiency programs are accelerating facility construction and attendant safety equipment procurement.
- Pharmaceutical aseptic processing:Sterile manufacturing protocols requiring particulate and electrostatic control are expanding footwear specifications beyond traditional electronics end-uses.
Market Restraints
- Synthetic polymer feedstock volatility:Polyurethane and carbon-black composite prices fluctuate with petrochemical indices, squeezing margin on volume-grade antistatic soles.
- China-centric manufacturing concentration:Over 70 percent of mid-tier production clusters in Guangdong and Zhejiang provinces creates geopolitical and logistics vulnerability.
- Leather tanning environmental compliance:REACH restrictions on chromium VI and wastewater discharge are eliminating smaller European tanneries from premium-grade supply chains.
Strategic Opportunities
- India's electronics manufacturing corridor:PLI scheme subsidies for semiconductor and mobile device assembly are creating greenfield demand in Karnataka and Tamil Nadu.
- Rental and managed service models:Industrial laundries and safety equipment lessors are capturing mid-sized electronics contractors previously priced out of capital purchase.
- Biodegradable static-dissipative compounds:Convergence of bio-based polymers and conductive fillers addresses EU Green Deal circular economy mandates for disposable PPE reduction.
Industry Challenges
- ESD certification testing backlog:IEC-accredited laboratories face 12-16 week queues for resistance-range validation, delaying product launches.
- Composite toe-cap integration complexity:Merging non-metallic impact protection with conductive pathways requires specialized molding expertise scarce outside German and Japanese engineering centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antistatic Protection Shoes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boots, Sneakers, Loafers, Sandals Material: Leather, Synthetic, Rubber, Textile Application: Manufacturing, Electronics, Pharmaceuticals, Construction End User: Industrial Workers, Laboratory Staff, Engineers, Technicians |
| Companies Covered | Honeywell, Aimboo, ATLAS, ELTEN GmbH, Giasco, U-Power, MengKe Safety Co.,Ltd, Anbusafety, Deltaplus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antistatic Protection Shoes Market Trends and Innovations
Material science breakthroughs and regulatory tightening are converging to redefine product specifications and procurement relationships across the antistatic footwear value chain.
Graphene-infused rubber compounds are rendering obsolete traditional carbon-black loading methods for achieving 10^5 to 10^8 ohm resistance targets. Samsung and TSMC supplier facilities in South Korea and Taiwan are specifying graphene-enhanced soles for their next-generation fab expansions. This shift is compressing formulation know-how into a handful of polymer specialists capable of uniform dispersion at industrial scale.
EU F-Gas Regulation phase-down schedules are indirectly pressuring footwear manufacturers through fluorinated polymer restrictions in breathable membrane laminates. The industrial consequence is accelerated migration to non-fluorinated moisture-wicking textiles for cleanroom-compatible uppers. German automotive electronics suppliers are most affected, driving dual-sourcing requirements that lengthen qualification timelines.
Consolidated procurement through industrial safety distributors is displacing direct manufacturer relationships for mid-volume electronics contract manufacturers. Arrow Safety and similar channel intermediaries are bundling antistatic footwear with garment and glove programs, capturing purchasing decisions previously held by plant-level ESD coordinators. This concentration is most visible in Malaysia's Penang electronics cluster and Mexico's Guadalajara high-tech corridor.
Antistatic Protection Shoes Market Segmentation
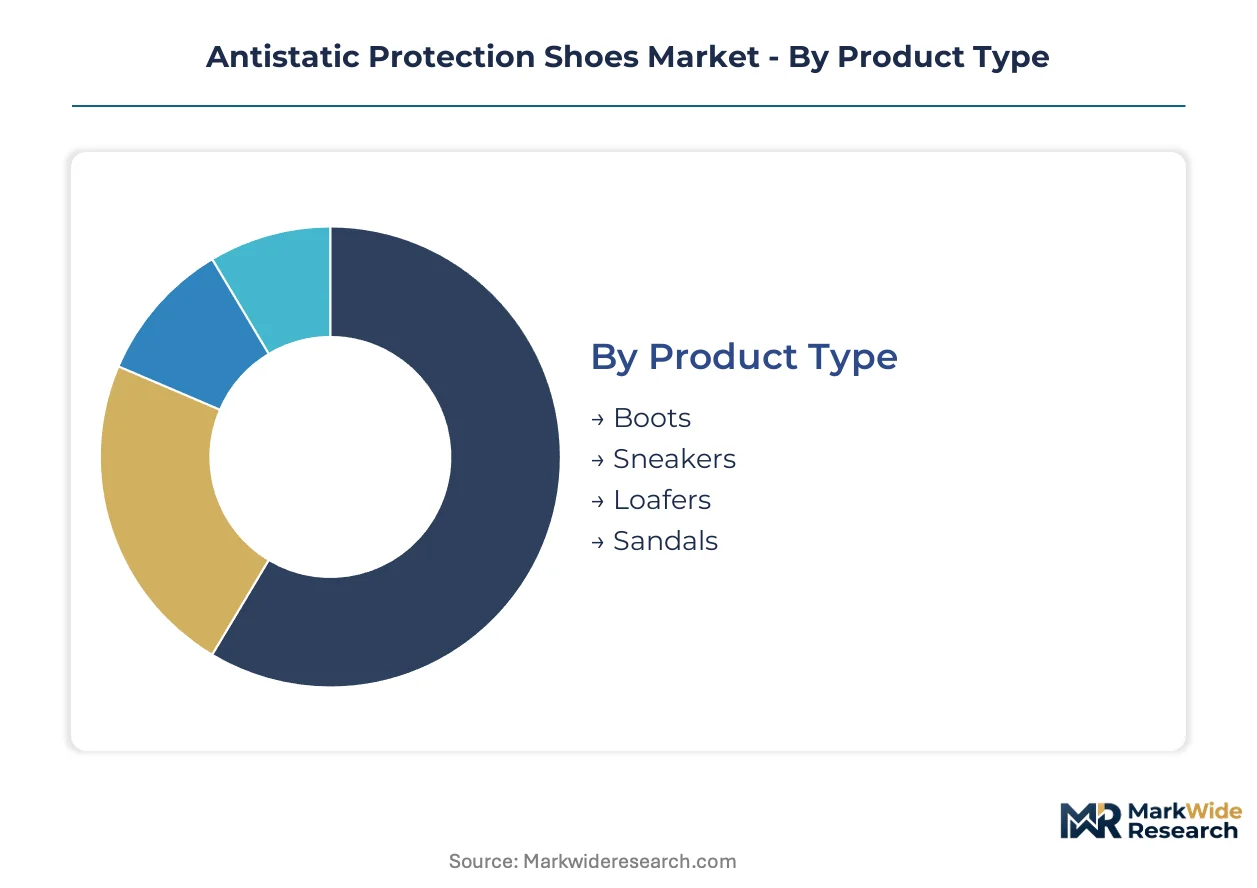
Antistatic footwear segmentation reflects divergent technical requirements across cleanroom protocols, chemical exposure levels, and worker mobility demands. Procurement patterns vary sharply between semiconductor fabs requiring conductive sole certification and pharmaceutical suites prioritizing particulate control alongside static dissipation.
Product Type:
Mature industrial boot formats coexist with emerging sneaker derivatives engineered for extended cleanroom standing shifts.
- Boots:Ankle-height and mid-calf configurations integrate conductive rubber outsoles with chemical-resistant leather or synthetic uppers. Semiconductor fabrication facilities in South Korea and Taiwan specify certified boot formats for chemical handling zones, though procurement cycles lengthen due to IEC 61340-5-1 resistance validation queues.
- Sneakers:Low-profile athletic designs with static-dissipative midsoles address electronics assembly lines requiring worker mobility across extended shifts. Malaysia's Penang electronics cluster and Mexico's Guadalajara corridor are driving sneaker-format procurement as contract manufacturers prioritize comfort metrics alongside ESD compliance.
- Loafers:Slip-on configurations serve laboratory environments with minimal contamination risk and no chemical splash exposure.
- Sandals:Open designs see restricted deployment in controlled electronics zones with toe protection waivers.
Boots retain volume leadership; sneakers hold the steepest expansion curve.
Material:
Cost tier stratification separates premium-grade leather from volume-positioned synthetics and commodity rubber compounds.
- Leather:Full-grain and split-hide constructions deliver chemical resistance and abrasion durability for heavy manufacturing. REACH chromium VI restrictions are eliminating smaller European tanneries, compressing premium supply into Italian and Spanish processing clusters.
- Synthetic:Polyurethane and microfiber uppers dominate electronics cleanroom procurement through particulate control and moisture-wicking properties. China's Dongguan manufacturing base supplies volume synthetic output for Asia-Pacific fab construction.
- Rubber:Nitrile and conductive rubber compounds form the essential static-dissipative sole layer across all product formats.
- Textile:Engineered mesh and non-woven uppers address breathable requirements in climate-controlled pharmaceutical suites.
Synthetics command the largest procurement volumes; leather maintains premium pricing power.
Application:
Volume concentration in manufacturing contrasts with margin-rich pharmaceutical specifications requiring dual certification.
- Manufacturing:Broad industrial deployment spans automotive electronics, appliance assembly, and general ESD-sensitive production. China's domestic semiconductor self-sufficiency programs are accelerating manufacturing-sector procurement as new fabs in Shanghai and Beijing reach operational status.
- Electronics:Cleanroom-specific designs with particulate-controlled uppers serve wafer processing and chip packaging operations. Samsung and TSMC supplier facilities specify graphene-enhanced sole compounds for next-generation fab expansions in South Korea and Taiwan.
- Pharmaceuticals:Aseptic processing protocols demand sterile-compatible materials with concurrent static control. India's PLI scheme subsidies for pharmaceutical manufacturing are creating greenfield demand in Karnataka and Tamil Nadu.
- Construction:Composite toe-cap integration with conductive pathways addresses specialized electrical installation and explosive atmosphere work.
Manufacturing absorbs the highest unit volumes; pharmaceuticals are climbing the fastest.
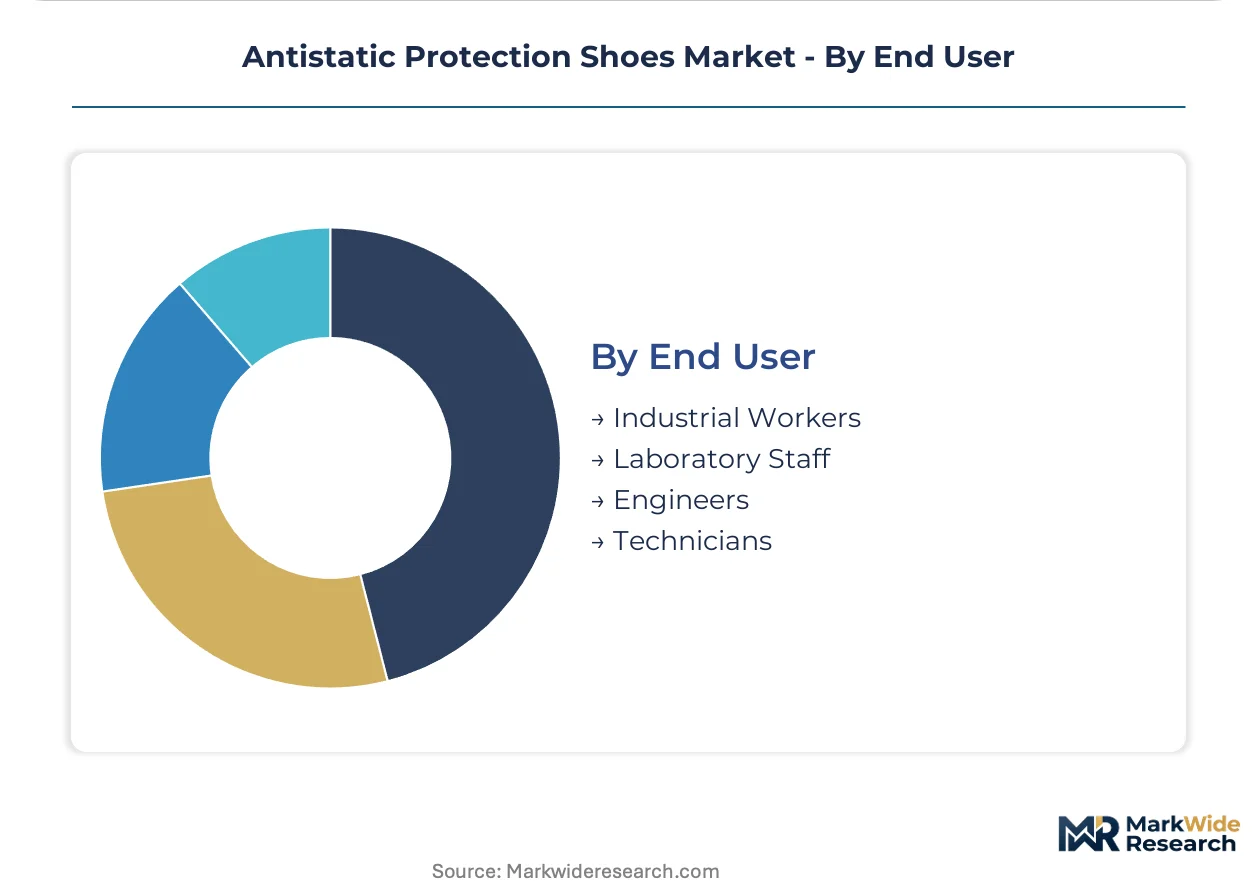
End User:
Customer type differentiation separates capital-equipped industrial employers from research-scale laboratory operators.
- Industrial Workers:Production floor personnel in electronics and automotive sectors drive recurring replacement demand through wear-cycle protocols. Asset-light leasing models are lowering capital barriers for mid-sized electronics contractors previously priced out of direct purchase programs.
- Laboratory Staff:Research and quality control personnel require low-particulate designs with static dissipation for analytical instrument protection. EU F-Gas Regulation phase-down schedules are accelerating migration to non-fluorinated moisture-wicking textiles for cleanroom-compatible uppers.
- Engineers:Technical staff with mixed cleanroom and office duties favor sneaker-format crossover products.
- Technicians:Maintenance and calibration personnel need durable boot configurations with chemical resistance.
Industrial workers represent the core installed base; laboratory staff are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering commands premium pricing for composite safety components, while Chinese manufacturing scales deliver volume-grade antistatic footwear at substantially lower unit economics. This asymmetry shapes procurement patterns across semiconductor fabrication corridors worldwide.
China
Domestic chipmaking self-sufficiency programs are accelerating fab construction in Shanghai and Beijing, driving attendant safety equipment procurement at unprecedented scale. GB standards govern product certification alongside IEC harmonization efforts. Dongguan's manufacturing base supplies volume synthetic output for Asia-Pacific fab construction, with Guangdong and Zhejiang provinces concentrating over 70 percent of mid-tier production.
Germany
Automotive electronics suppliers and precision engineering firms sustain demand for premium-grade leather configurations with chemical resistance. REACH chromium VI restrictions are eliminating smaller European tanneries, compressing premium supply into Italian and Spanish processing clusters. Bavaria and Baden-Württemberg host specialized engineering centers for composite toe-cap integration with conductive pathways.
United States
OSHA workplace safety mandates and IEC 61340 electrostatic standards shape North American product compliance requirements for electronics manufacturing. Semiconductor fabrication expansion in Arizona and Texas is compressing procurement cycles for static-control footwear. Austin and Phoenix metro areas are driving localized supply chain development as new fabs demand faster certification turnaround.
South Korea
Samsung supplier facilities are specifying graphene-enhanced sole compounds for next-generation fab expansions, rendering traditional carbon-black loading methods obsolete. METI-aligned standards and IEC harmonization govern technical specifications. Pyeongtaek and Hwaseong industrial corridors are driving specification upgrades for conductive footwear deployment in cleanroom environments.
India
PLI scheme subsidies for semiconductor and mobile device assembly are creating greenfield demand in Karnataka and Tamil Nadu. BIS standards and DGFT import regulations shape market access requirements for foreign suppliers. Bengaluru and Chennai electronics corridors are emerging as procurement centers as contract manufacturers prioritize comfort metrics alongside ESD compliance.
Antistatic Protection Shoes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and materials expertise. The vendor base organizes across three tiers: multinational safety conglomerates with captive supply chains, regional engineering specialists with composite integration capabilities, and scale-driven Asian manufacturers serving volume procurement. Two dominant competitive moves are reshaping positioning: asset-light leasing models lowering capital barriers for mid-sized distributors, and graphene compound specialization compressing formulation know-how into polymer specialists capable of uniform dispersion at industrial scale.
Among German engineering specialists, ELTEN GmbH exemplifies the composite toe-cap integration tier, while Honeywell represents multinational platform integration with captive raw material control. At the scale-driven end, MengKe Safety Co.,Ltd anchors volume manufacturing from its Dongguan production base. These three archetypes capture the essential competitive structure without exhausting the participant set.
| Leading Market Players |
|---|
| Honeywell |
| Aimboo |
| ATLAS |
| ELTEN GmbH |
| Giasco |
| U-Power |
| MengKe Safety Co.,Ltd |
| Anbusafety |
| Deltaplus |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Guangdong synthetic footwear manufacturing is compressing margins on volume-grade antistatic soles while concentrating pricing power with German engineering specialists holding scarce composite toe-cap integration expertise. This utilization divergence shapes procurement negotiations across semiconductor fabrication corridors, where fabs accept premium configured pricing for IEC 61340-5-1 certified formats while electronics contract manufacturers drive standard-grade tenders to commodity levels.
Pricing Analysis
The customization-premium spread separates configured-to-order graphene-enhanced soles for Samsung and TSMC supplier facilities from standard carbon-black loaded formats serving mid-tier electronics assembly. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade stratification, with IEC-accredited resistance validation adding substantial configured premiums. Cost compression in synthetic polymer feedstocks is intensifying because polyurethane and carbon-black composite prices fluctuate with petrochemical indices. Mid-sized electronics contractors exhibit highest price sensitivity, while semiconductor fabs demonstrate lowest sensitivity due to fab-down-time costs from ESD failures.
Supply Chain Analysis
Contract manufacturing concentration rests with Dongguan-based synthetic specialists and Bavarian composite integration engineering centers holding scarce molding expertise for non-metallic impact protection. Raw material dependencies draw from Italian and Spanish tanning clusters for premium leather, Chinese petrochemical complexes for polyurethane compounds, and specialized German polymer laboratories for graphene dispersion. Single-source vulnerability concentrates in IEC-accredited certification laboratories facing validation backlogs. Distribution runs through industrial safety distributors bundling footwear with garment and glove programs, displacing direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed service and leasing models for industrial safety footwear are expanding faster than hardware procurement as asset-light operators capture mid-sized electronics contractors. This service-attach dynamic reorients value capture toward recurring-revenue layers including certification management, replacement logistics, and compliance auditing.
For Market Incumbents: Entrench market position through captive supply chain control over graphene compound formulation and backward integration into conductive polymer production. Prioritize certification investment in IEC 61340-5-1 resistance validation capacity to reduce 12-16 week laboratory queues threatening customer retention. Channel control through industrial safety distributor exclusivity agreements defends against emerging Asian scale manufacturers. For New Entrants and Emerging Players: Pursue India's PLI scheme electronics manufacturing corridors in Karnataka and Tamil Nadu as greenfield demand surfaces with limited incumbent presence. Target biodegradable static-dissipative compound development addressing EU Green Deal circular economy mandates as the most penetrable specification tier. Go-to-market angle through industrial laundry and safety equipment lessor partnerships bypasses capital-purchase barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among industrial safety distributors with managed service contracts and certification-compliance bundling, positioning this archetype for premium valuation multiples. Long-term viability across the analysis window favors polymer specialists with graphene dispersion capabilities and IEC-accredited testing infrastructure. Monitor semiconductor fabrication buildout announcements in East Asia as the signal indicating demand inflection for next-generation ESD footwear specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Polymers | Captive graphene compound supply secures margin control against petrochemical volatility. |
| IEC Certification Laboratory Capacity Expansion | Reduced validation queues capture fab procurement cycles compressed by facility construction timelines. |
| Biodegradable Compound Development | EU Green Deal compliance positioning addresses disposable PPE reduction mandates. |
| Managed Service Model Launch | Asset-light leasing captures mid-sized contractors priced out of capital purchase programs. |
| India Electronics Corridor Geographic Expansion | PLI scheme subsidies in Karnataka and Tamil Nadu create greenfield procurement relationships. |
Research Methodology
Cross-validation between primary fieldwork with ESD coordinators, plant safety managers, and industrial safety distributors and secondary validation through IEC standard documentation, customs trade data, and SEC filings anchors the qualitative findings. ESD coordinators at Samsung and TSMC supplier facilities, procurement leads at pharmaceutical aseptic processing operations, and channel managers at Arrow Safety and similar distributors provided operational demand signals. Secondary sources include IEC 61340 technical committee publications, REACH restriction updates from ECHA, and import-export statistics from China's General Administration of Customs. Bottom-up procurement volume estimates triangulate against top-down market sizing from safety equipment distributor revenue disclosures.
Calibration against historical procurement cycles in semiconductor fabrication construction and pharmaceutical facility commissioning informs the analytical framework across the projection horizon. Segmentation dimensions model product type, material grade, application sector, and end-user archetype alongside regional regulatory cluster differentiation. CAGRs derive from elasticity-adjusted demand curves incorporating fab construction pipelines, ESD standard adoption trajectories, and polymer feedstock price indices. Forecast inputs include graphene compound commercialization timelines and IEC laboratory capacity expansion schedules.
Sensitivities concentrate around semiconductor self-sufficiency program funding continuity in China and India, REACH restriction scope expansion affecting tanning operations, and petrochemical index volatility impacting synthetic sole margins. Forecasts reflect assumptions regarding ESD standard harmonization pace and cleanroom protocol convergence. Quarterly review of fab construction announcements, IEC accreditation queue lengths, and polymer feedstock futures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Dust Covers Market
Protective Gear
China Pollution Mask Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Earplug Distributor Market
Protective Gear
Helmets Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Safety Shoes Market
Protective Gear
Waterproof Cases Market
Protective Gear
Boxed Glove for Food Market
Protective Gear
Earplugs Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Flavored Condoms Market
Protective Gear
Tactical Boots Market