
 UK Mobility Devices Market | 2026-2036
UK Mobility Devices Market Size, Share, and Industry Trends Forecast 2026-2036
UK Mobility Devices Market Insights
The NHS Net Zero Supplier Roadmap is rebalancing procurement criteria toward carbon-accounted equipment across UK health trusts. Invacare Corporation leverages its established NHS supply agreements to sustain volume throughput in manual wheelchair categories. Sunrise Medical anchors its competitive stance through specialized seating configurations for complex rehabilitation cases. Ottobock dominates the high-assist powered segment with advanced actuator technology developed for neurological conditions.
Mobility devices encompass wheeled, powered, and ambulatory assistive products engineered to restore or augment locomotion for individuals with impaired gait, balance, or endurance. These products incorporate specified load ratings, seat depth dimensions, and battery capacity thresholds measured in ampere-hours to ensure safe daily operation across varied terrain and user weights. Powered scooters and mobility scooters lead volume contribution due to widespread community-dwelling senior use, while stair lifts command concentrated margin pools tied to home modification financing. Lightweight aluminum and lithium-ion batteries represent the fastest-expanding technology pairing as users prioritize portability and extended range between charges.
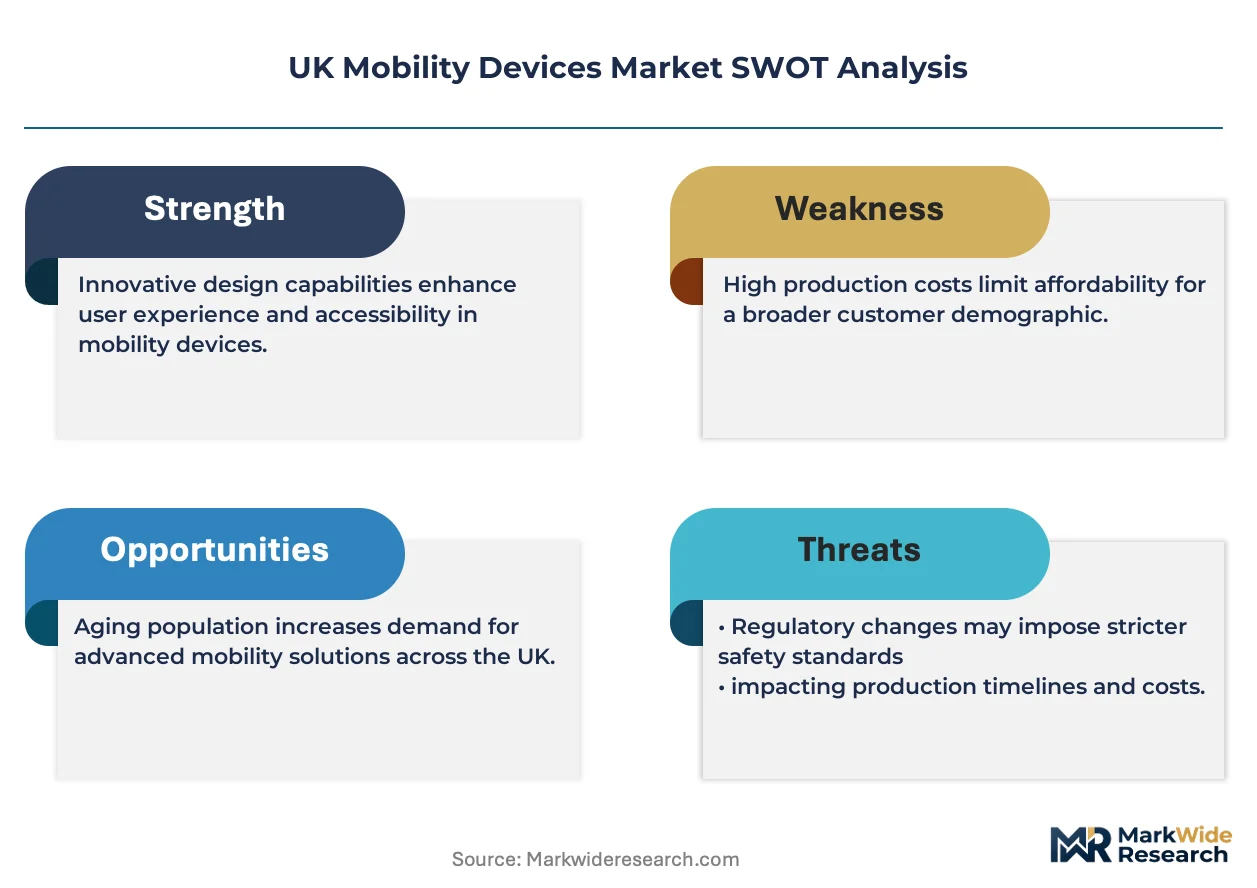
The Care Quality Commission enforces equipment safety standards alongside NHS England procurement frameworks that mandate supplier environmental disclosures. The Medicines and Healthcare products Regulatory Agency governs electrical medical device conformity, creating compliance cost barriers for non-UK manufacturers seeking market entry. MHRA post-market surveillance requirements and evolving NHS sustainability scoring will force stakeholders to recalibrate sourcing strategies and R&D allocation without delay.
Market Dynamics
The NHS Net Zero Supplier Roadmap is forcing carbon-accounted procurement across England's health trusts, rebalancing supplier selection toward lifecycle emissions disclosure and aluminum-intensive lightweight designs that reduce transport and operational energy burdens.
Growth Catalysts
- England's Care Quality Commission standards:Assisted living facilities are expanding equipment procurement to meet updated safety and accessibility mandates. Facility managers prioritize powered mobility with documented service histories.
- Lithium-ion battery chemistry:Extended range between charges and reduced weight are converting manual wheelchair users to powered alternatives. Community-dwelling seniors in suburban corridors drive replacement cycles.
- Southeast England demographic clustering:Aging populations in Kent, Surrey, and Sussex overlap with NHS procurement hubs. Regional concentration creates efficient distribution economies for suppliers.
Market Restraints
- Aluminum price volatility:Lightweight frame production faces input cost swings tied to energy-intensive smelting. Manufacturers absorb margin compression or pass through to constrained NHS budgets.
- East Asian battery cell concentration:Lithium-ion cell supply concentrates in South Korean and Chinese production zones. UK assemblers face extended lead times and currency exposure.
- MHRA electrical device conformity:Non-UK manufacturers face layered testing and documentation requirements. Compliance cost barriers limit entrant diversity in powered segments.
Strategic Opportunities
- Wales and Northern England underpenetration:Rural geographies outside the Southeast corridor show lower powered mobility adoption. NHS regional procurement offices are decentralizing sourcing authority.
- Home modification financing integration:Stair lift and platform lift sales link to housing adaptation grants. Partnerships with local authority occupational therapy teams unlock bundled project approvals.
- NHS sustainability scoring tailwind:Environmental disclosure mandates favor suppliers with verified carbon accounting. Early movers capture preferred supplier status in framework agreements.
Industry Challenges
- Rehabilitation engineering skill scarcity:Complex seating configuration requires specialized clinical assessment capacity. NHS therapy services face recruitment gaps in wheelchair posture specialists.
- MHRA post-market surveillance compliance:Powered device incidents require rapid reporting and corrective action documentation. Smaller suppliers lack regulatory affairs infrastructure to manage surveillance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Mobility Devices Market |
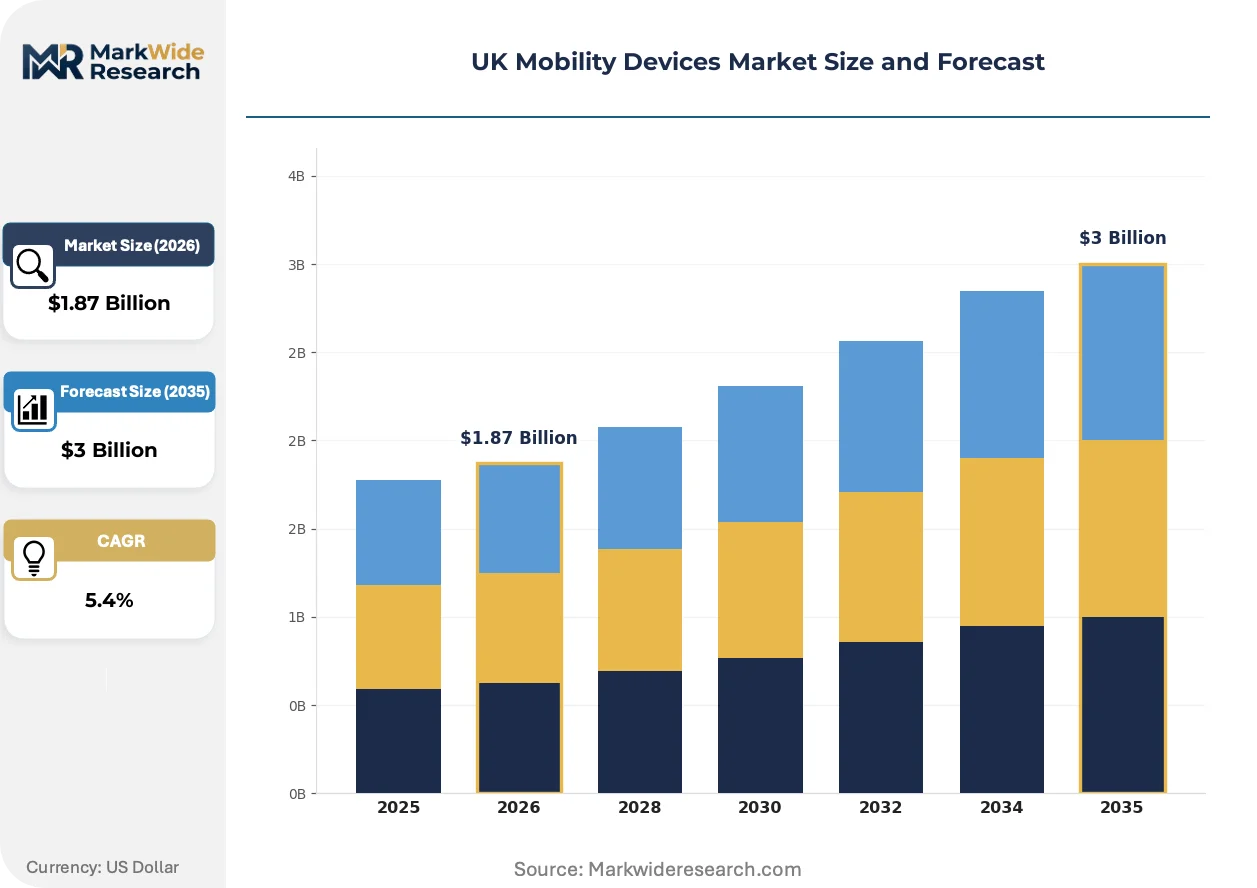
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wheelchairs, Powered Scooters, Walking Frames, Stair Lifts, Mobility Scooters Technology: Electric Drive, Hydraulic Systems, Lightweight Aluminum, Lithium-ion Batteries, Foldable Mechanisms End User: Senior Citizens, Rehabilitation Centers, Assisted Living Facilities, Disabled Individuals, Hospitals Distribution Channel: Specialty Stores, Online Retailers, Medical Supply Companies, Home Healthcare Providers, Pharmacies |
| Companies Covered | Invacare Corporation, Sunrise Medical, Permobil, Pride Mobility Products Corp., Ottobock, Drive DeVilbiss Healthcare, Etac AB, Roma Medical, NRS Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Mobility Devices Market Trends and Innovations
Lightweight materials and intelligent power management are compressing product lifecycles and redrawing competitive boundaries between manual and powered categories.
Modular lithium-ion battery systems with hot-swappable cells are decentralizing service models for powered wheelchairs. Community equipment services in England's metropolitan counties are adopting rapid battery exchange programs rather than depot-based repair. This architecture reduces vehicle fleet requirements and enables same-day mobility restoration.
The NHS Net Zero Supplier Roadmap is mandating embodied carbon disclosure for all framework-listed equipment. Suppliers must submit lifecycle assessments covering raw material extraction through end-of-life processing. Powered mobility categories face the steepest documentation requirements due to battery and electronics content.
Direct-to-user digital channels are fragmenting traditional community equipment service relationships. Consumers in England's affluent suburban belts research specifications online before contacting occupational therapists. This pattern compresses the traditional assessment-to-delivery interval and pressures local authority procurement to match retail responsiveness.
UK Mobility Devices Market Segmentation
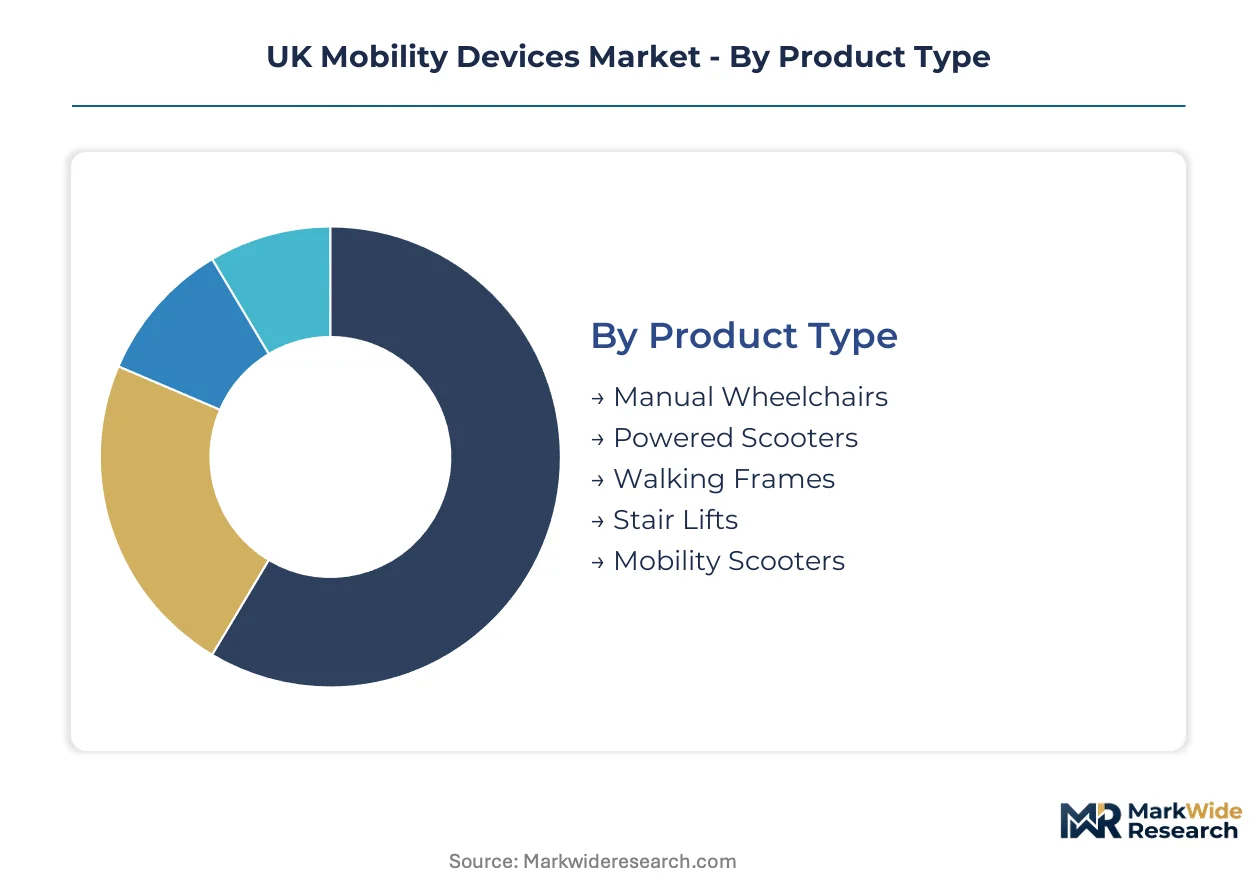
Mobility device procurement in the UK splits across clinical, retail, and institutional pathways with divergent specification requirements. NHS framework agreements favor standardized configurations with carbon disclosure, while direct-to-consumer channels reward portability and rapid delivery. Understanding these segment boundaries enables suppliers to align R&D and distribution investments with actual purchasing authority.
Product Type:
Customization intensity varies sharply across this category, from bespoke seating engineering to mass-produced walking aids.
- Powered Scooters:Electric motor systems with tiller steering and platform footrests, rated for pavement and limited road use. Demand clusters among community-dwelling seniors in Kent and Sussex suburbs, where housing stock lacks elevator access and NHS community equipment services face delivery backlogs.
- Manual Wheelchairs:Frame structures in steel, aluminum, or titanium with configurable seat widths, depths, and camber angles. Rehabilitation centers in England's Southeast corridor drive specification complexity, as NHS wheelchair services mandate postural assessment for complex cases.
- Mobility Scooters:Three-wheel and four-wheel variants with shopping basket attachments and lighting packages. Retail purchasers in coastal retirement towns prioritize road-crossing speed and boot-folding dimensions.
- Stair Lifts:Straight and curved rail systems with swivel seats and safety sensors. Local authority housing adaptation grants in Wales and Northern England fund installation where home modification financing integrates with occupational therapy assessment.
- Walking Frames:Wheeled and non-wheeled aluminum structures with height-adjustable handgrips. Hospital discharge protocols specify these for transitional mobility, creating volume through NHS procurement hubs.
Leading the category by volume: Powered Scooters. Expanding most quickly: Stair Lifts, tied to housing adaptation grant processing acceleration.
Technology:
Cost tier stratification separates premium electromechanical systems from commodity mechanical alternatives.
- Lithium-ion Batteries:Rechargeable cells with 10-25 mile range ratings and 300-500 cycle lifespans, integrated into powered wheelchair and scooter bases. England's Care Quality Commission standards for assisted living facilities now require documented battery service histories, accelerating replacement demand.
- Lightweight Aluminum:6061-T6 and 7005 alloy tubing with heat-treated joints, reducing frame weight by 30-40% versus steel equivalents. NHS Net Zero Supplier Roadmap procurement scoring favors aluminum-intensive designs for transport emission reductions.
- Electric Drive:Brushless DC motors with programmable speed controllers and electromagnetic brakes. Complex rehabilitation cases in specialist seating clinics require torque calibration for slope navigation.
- Hydraulic Systems:Cylinder-actuated lift mechanisms for stair lift and patient hoist applications. Home modification contractors specify these where electrical installation proves impractical in older housing stock.
- Foldable Mechanisms:Hinge and locking systems enabling collapsed transport dimensions. Community equipment services in metropolitan counties prioritize these for vehicle fleet efficiency.
Dominating by procurement value: Lithium-ion Batteries. Steepest expansion trajectory: Lightweight Aluminum, driven by carbon-accounted NHS sourcing.
End User:
Application context determines specification rigor, from clinical assessment protocols to self-directed retail selection.
- Assisted Living Facilities:CQC-regulated residential settings with communal dining and activity programming. Managers procure powered mobility with maintenance contracts to meet updated safety and accessibility mandates.
- Senior Citizens:Individuals aged 65+ with gait, balance, or endurance limitations. Suburban corridors in Surrey show concentrated scooter adoption where retail showrooms enable specification comparison.
- Disabled Individuals:Users with congenital or acquired impairments requiring postural support or environmental control interfaces. NHS wheelchair services provide assessment pathways distinct from retail channels.
- Rehabilitation Centers:Inpatient and outpatient facilities delivering neuro-rehabilitation and orthopedic recovery. Specialized seating configurations for complex cases demand clinical engineering capacity.
- Hospitals:Acute and community trusts managing discharge mobility. Ward-based walking frame provision transitions to community equipment service loans for longer-term needs.
Highest procurement authority by contract value: Assisted Living Facilities. Gaining share fastest: Senior Citizens through direct-to-user digital research patterns.
Distribution Channel:
Customer type concentration splits between institutional procurement offices and individual decision-makers.
- Medical Supply Companies:NHS framework-listed distributors with warehousing, fitting, and repair infrastructure. These intermediaries manage MHRA electrical device conformity documentation for powered segments.
- Home Healthcare Providers:Regional contractors delivering community equipment services under local authority commissioning. Rapid battery exchange programs in England's metropolitan counties reshape their service model economics.
- Specialty Stores:Showroom-based retailers with assessment rooms and demonstration stock. Coastal retirement towns sustain these through senior population density.
- Online Retailers:Direct-to-user platforms with specification comparison tools and financing options. Affluent suburban belts research online before occupational therapist contact, compressing assessment intervals.
- Pharmacies:High-street locations with limited mobility aid ranges for immediate-need walking frames. NHS minor ailment scheme integration drives foot traffic conversion.
Controlling largest procurement volume: Medical Supply Companies. Expanding most quickly: Online Retailers, fragmenting traditional community equipment service relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for mobility devices remains weighted toward continental European production zones, while consumption clusters in England's aging suburban corridors where NHS procurement authority and demographic density overlap.
England's Southeast Corridor
Kent, Surrey, and Sussex host the densest concentration of assisted living facilities and community-dwelling seniors requiring powered mobility solutions. NHS England procurement frameworks channel equipment funding through regional hubs in this zone, creating efficient distribution economies for suppliers. The Care Quality Commission enforces updated safety mandates that accelerate replacement cycles for facility managers in Brighton, Guildford, and Tunbridge Wells.
Midlands
Birmingham and Leicester anchor rehabilitation engineering capacity for complex seating configurations serving NHS wheelchair services. The region's manufacturing heritage supports aluminum frame fabrication and component assembly operations. Local authority occupational therapy teams in the West Midlands coordinate housing adaptation grant processing for stair lift installations in aging housing stock.
North England
Manchester and Leeds demonstrate underpenetration in powered mobility adoption relative to demographic need, presenting expansion opportunities for suppliers. NHS regional procurement offices are decentralizing sourcing authority to address geographic inequities. Community equipment services in South Yorkshire are piloting rapid battery exchange programs to reduce vehicle fleet requirements.
Scotland
Edinburgh and Glasgow concentrate demand for outdoor-capable mobility scooters suited to variable terrain and climate conditions. The Scottish Government's health and social care integration agenda reshapes equipment provision pathways. NHS Scotland procurement operates distinct frameworks from England, creating separate supplier registration requirements for access.
Wales
Rural geographies in North and West Wales show lower baseline adoption of powered mobility devices despite substantial aging populations. Local authority housing adaptation grant processing accelerates stair lift and platform lift installations. Cardiff-based distribution operations serve dispersed communities with extended service territories and higher per-delivery costs.
UK Mobility Devices Market Competitive Landscape
The competitive structure tilts toward established NHS framework incumbents with repair infrastructure and regulatory compliance capacity. Market concentration remains moderate, with tiered positioning separating premium rehabilitation specialists from volume-driven community equipment suppliers. Three archetypes dominate: multinational manufacturers with full-category portfolios, regional assemblers serving specific NHS trusts, and direct-to-consumer retailers capturing affluent suburban demand. Competitive moves center on sustainability certification alignment and service model restructuring toward rapid battery exchange networks.
Within the multinational tier, Invacare Corporation, Sunrise Medical, and Ottobock occupy positions shaped by their historical NHS supply relationships and specialized seating engineering reputations. These entities exemplify the compliance-heavy operational model required for powered device categories under MHRA surveillance requirements. Regional British fabricators and distributors compete on responsiveness to local authority commissioning patterns, while direct-to-consumer channels fragment traditional community equipment service relationships in England's affluent belts.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical |
| Permobil |
| Pride Mobility Products Corp. |
| Ottobock |
| Drive DeVilbiss Healthcare |
| Etac AB |
| Roma Medical |
| NRS Healthcare |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between MHRA-registered powered devices and unregistered manual alternatives splits procurement budgets and supplier investment patterns across the UK mobility devices sector. NHS framework compliance costs concentrate pricing power with established incumbents, while aluminum and lithium-ion import dependencies tether margin structures to East Asian commodity cycles and currency exposure.
Pricing Analysis
Cost-down pressure on powered wheelchair tiers accelerates because NHS sustainability scoring mandates carbon-accounted lifecycle assessments that smaller assemblers cannot document. Three-tier pricing structure across premium rehabilitation seating, standard community equipment, and economy walking aids reflects MHRA registration burden and aluminum content grade. Price differentiation hinges on battery service contract bundling versus transactional hardware-only supply. Assisted living facilities show lowest price sensitivity due to CQC-mandated replacement cycles, while individual retail purchasers in coastal retirement towns drive hard bargains on scooter road-crossing speed specifications.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean lithium-ion cell production zones that feed UK wheelchair and scooter assembly operations. Aluminum frame fabrication draws from German extrusion specialists and domestic Midlands fabricators with heat-treatment capacity. Supply chain risk centers on extended lead times from East Asian battery cell concentration, compounded by sterling-yuan volatility. Distribution runs through NHS framework-listed medical supply companies with MHRA electrical device conformity documentation infrastructure, bypassing direct manufacturer-to-user channels for powered segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum in the UK mobility devices market centers on captive battery assembly capacity and rapid-exchange service network ownership. Players are racing upstream into lithium-ion cell sourcing partnerships and downstream into metropolitan county equipment service contracts.
For Market Incumbents: Deploy rapid battery exchange program infrastructure to lock in community equipment service contracts across England's metropolitan counties. Consolidate aluminum frame fabrication through Midlands manufacturing partnerships to hedge against energy-intensive smelting cost volatility. The threat of direct-to-consumer digital channels fragmenting traditional occupational therapist relationships demands preemptive channel control investments in online specification tools. For New Entrants and Emerging Players: Direct-to-user digital platforms with financing integration offer the most penetrable route into Surrey and Kent suburban corridors where affluent seniors research specifications before clinical contact. Wales and Northern England rural geographies present white-space targets with decentralized NHS regional procurement authority. Partner with local authority occupational therapy teams for bundled housing adaptation grant processing to bypass incumbent medical supply company intermediation. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap regional assemblers with NHS framework listings and MHRA regulatory affairs infrastructure. Long-term viability in this sector rests on sustainability certification alignment and service model density rather than pure manufacturing scale. Watch for inflection in NHS Net Zero Supplier Roadmap enforcement intensity as the signal for preferred supplier status consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Rapid Battery Exchange Network Deployment | Reduces vehicle fleet requirements for community equipment services in metropolitan counties. |
| Carbon Accounting Certification Investment | Secures preferred supplier status under NHS Net Zero Supplier Roadmap procurement scoring. |
| Aluminum Frame Fabrication Backward Integration | Hedges margin compression from energy-intensive smelting input cost volatility. |
| Direct-to-Consumer Digital Platform Launch | Captures affluent suburban demand where online research precedes occupational therapist contact. |
| Local Authority Partnership Structuring | Unlocks bundled housing adaptation grant approvals for stair lift and platform lift installations. |
Research Methodology
Independent corroboration across NHS procurement database extracts, MHRA device registration filings, and Care Quality Commission inspection reports underwrites the qualitative findings in this study. Primary interviews with wheelchair service clinical engineers, assisted living facility procurement managers, and local authority occupational therapy leads combined with secondary validation from NHS England framework documentation and aluminum trade flow customs records. Bottom-up demand modeling across product type, technology, and end user segments triangulates against top-down health and social care expenditure allocations.
Rate-of-change decomposition across the projection horizon separates volume expansion from value migration effects. The analytical framework models product type, technology pairing, end user setting, and distribution channel dimensions alongside regional procurement authority decentralization patterns. CAGRs derive from fitted trend extrapolation adjusted for NHS Net Zero policy implementation pace and lithium-ion battery replacement cycle acceleration. Forecast inputs include CQC enforcement intensity indices and housing adaptation grant processing velocity by local authority.
The model holds under stable NHS commissioning structures and continued MHRA electrical device conformity requirements; deviation in regulatory enforcement intensity or aluminum price volatility would shift volume and value trajectories. Forecasts reflect documented assumptions about policy implementation timelines and commodity input stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Pet Control Devices Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Heated Goggles Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Work Shoes Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Cooking Gloves Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Earplugs Market
Protective Gear
Dust Covers Market
Protective Gear
Helmets Market
Protective Gear
Waterproof Cases Market
Protective Gear
Mobile Phone Protective Cover Market