
 Heated Goggles Market | 2026-2036
Heated Goggles Market Size, Share, and Industry Trends Forecast 2026-2036
Heated Goggles Market Insights
Subscription-based equipment leasing is reconfiguring competitive dynamics in the heated goggles space. OutdoorMaster leverages direct-to-consumer channel control to bypass traditional retail markups. Smith Optics sustains technology leadership through in-house production of thermal lens systems. POC Sports anchors premium positioning with medical-grade fit certification for cold-weather optical protection.
Heated goggles integrate conductive heating elements—typically carbon fiber filaments or infrared emitters—within dual-pane lens assemblies to prevent fogging and ice formation in sub-zero environments. These devices maintain optical clarity at temperatures below minus twenty degrees Celsius through active thermal management powered by rechargeable battery packs. Battery-operated electric variants dominate unit volume while hybrid systems command the strongest margin pools due to dual-power flexibility. Winter sports applications lead absolute demand, though medical use segments for patients with cold-induced vascular conditions represent the fastest-growing end-use category.
FDA oversight of heated eyewear with medical claims shapes product labeling and clinical validation requirements in the United States, while CE marking under the EU Medical Device Regulation governs market access across European Economic Area member states. Japan's Ministry of Economy, Trade and Industry (METI) enforces electrical safety standards for battery-powered personal equipment that directly influence heating element design specifications. Stakeholders must monitor evolving battery transportation regulations and thermal performance certification thresholds as these standards increasingly determine which product architectures qualify for commercial distribution.
Market Dynamics
Battery-powered thermal management systems are displacing passive anti-fog coatings across winter sports and medical applications, compressing replacement cycles while elevating performance expectations for optical clarity in extreme cold.
Growth Catalysts
- Lithium-polymer cell energy density improvements:Extended runtime per charge expands addressable use cases beyond resort skiing into backcountry and industrial cold-weather operations.
- FDA clearance pathway for vascular condition claims:Medical-grade heated eyewear for Raynaud's phenomenon patients opens reimbursement channels and clinical distribution networks.
- Japan's METI electrical safety standards harmonization:Unified testing protocols reduce certification costs for manufacturers targeting Asian markets, accelerating cross-border product launches.
Market Restraints
- Cobalt and lithium carbonate price volatility:Battery pack input costs fluctuate with raw material commodity cycles, compressing margins on mid-tier product lines.
- Single-source dependency for infrared emitter substrates:Germanium crystal suppliers concentrate in three facilities, creating geographic concentration risk for premium heating element production.
- CE marking timeline under EU MDR:Extended clinical documentation requirements for heated eyewear with therapeutic claims delay European market entry by 8-14 months versus legacy medical device directives.
Strategic Opportunities
- Underpenetrated Nordic backcountry segments:Norway, Sweden, and Finland show low heated goggle adoption despite extreme winter conditions and high disposable income levels.
- Integration with heads-up display systems:Convergence of thermal management and AR navigation overlays targets military and search-and-rescue procurement channels.
- India's PLI scheme for wearable electronics:Production-linked incentives for battery-powered personal equipment manufacturing attract contract assembly investment for export markets.
Industry Challenges
- Optical engineer talent scarcity:Dual expertise in thermal physics and lens design commands premium compensation, constraining R&D team scaling.
- IP fragmentation around conductive filament weaving patterns:Patent thickets covering carbon fiber heating element geometries complicate freedom-to-operate analysis for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heated Goggles Market |
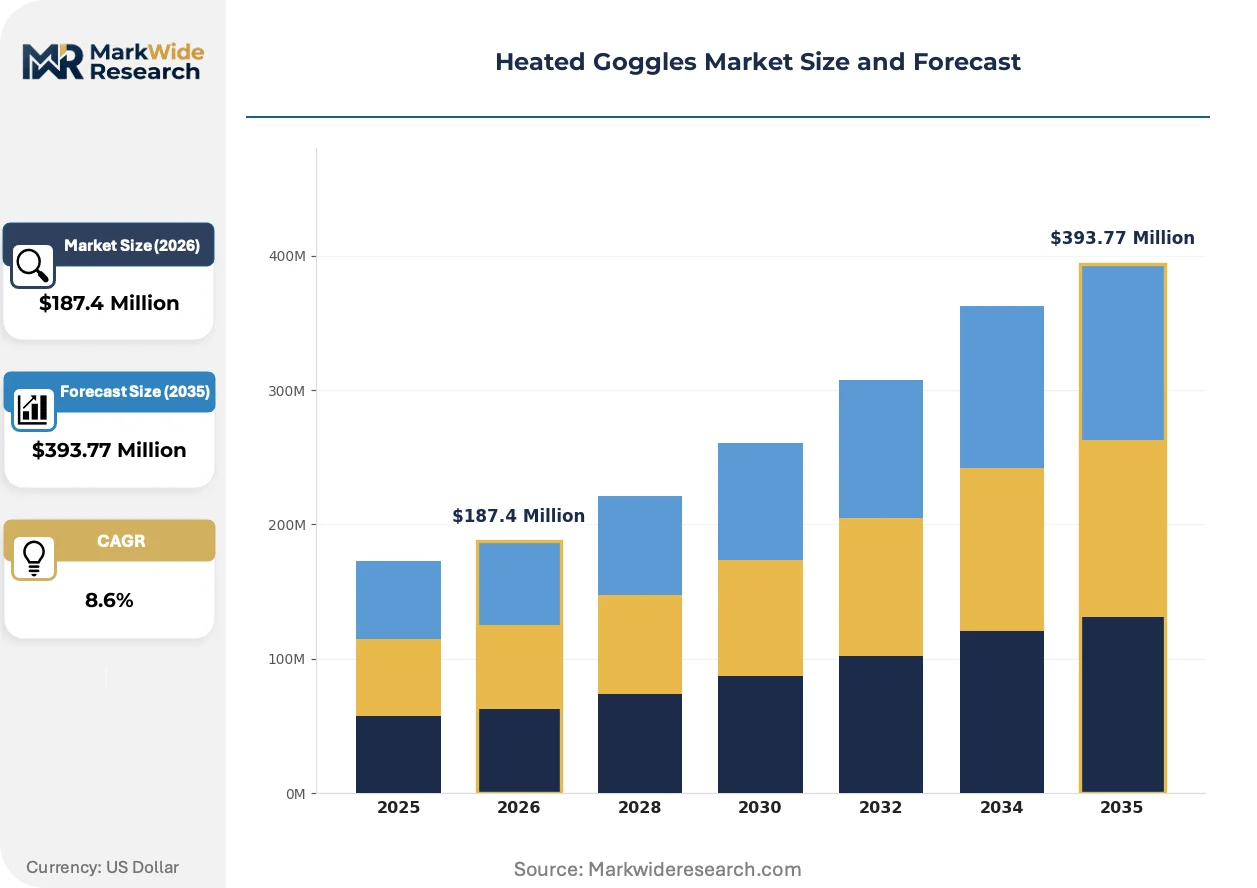
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heated, Battery Operated, Manual Heated, Hybrid End User: Athletes, Skiers, Snowboarders, Outdoor Enthusiasts Technology: Infrared Heating, Thermal Insulation, Smart Fabric, Carbon Fiber Application: Winter Sports, Medical Use, Outdoor Work, Recreational Activities |
| Companies Covered | Tempest Optics, Oakley, Inc., Smith Optics, Anon Optics, Spy Optic, Dragon Alliance, POC Sports, Giro Sport Design, OutdoorMaster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heated Goggles Market Trends and Innovations
Active thermal management is converging with smart connectivity and modular power architectures, shifting product roadmaps from standalone devices toward integrated cold-weather systems.
Carbon fiber heating element technology is hybridizing with thin-film infrared emitters to create dual-mode thermal systems that switch between conductive and radiant heating based on ambient temperature and power availability. Backcountry skiers and ice-climbing guides adopt these hybrid configurations fastest, prioritizing runtime flexibility over single-mode efficiency. The technology is hybridizing price-performance tiers, enabling premium thermal capabilities to cascade into mid-market product lines within two design cycles.
EU MDR Article 10 clinical evidence requirements for heated eyewear with therapeutic claims now mandate biocompatibility testing for all materials contacting periorbital skin. Manufacturers must submit technical documentation including thermal cycling validation and battery failure-mode analysis to notified bodies before CE marking. Alpine European markets show the steepest compliance cost increases, with smaller brands consolidating or exiting rather than absorbing expanded quality management system investments.
Subscription-based equipment leasing is displacing outright purchase in North American resort corridors, with seasonal access models capturing younger demographics and occasional users. Rental shop networks and direct-to-consumer platforms disintermediate traditional sporting goods retail, compressing distributor margins while expanding addressable reach. Colorado's Ikon Pass holder community exhibits the highest subscription conversion rates, treating heated goggles as consumable seasonal equipment rather than durable goods.
Heated Goggles Market Segmentation
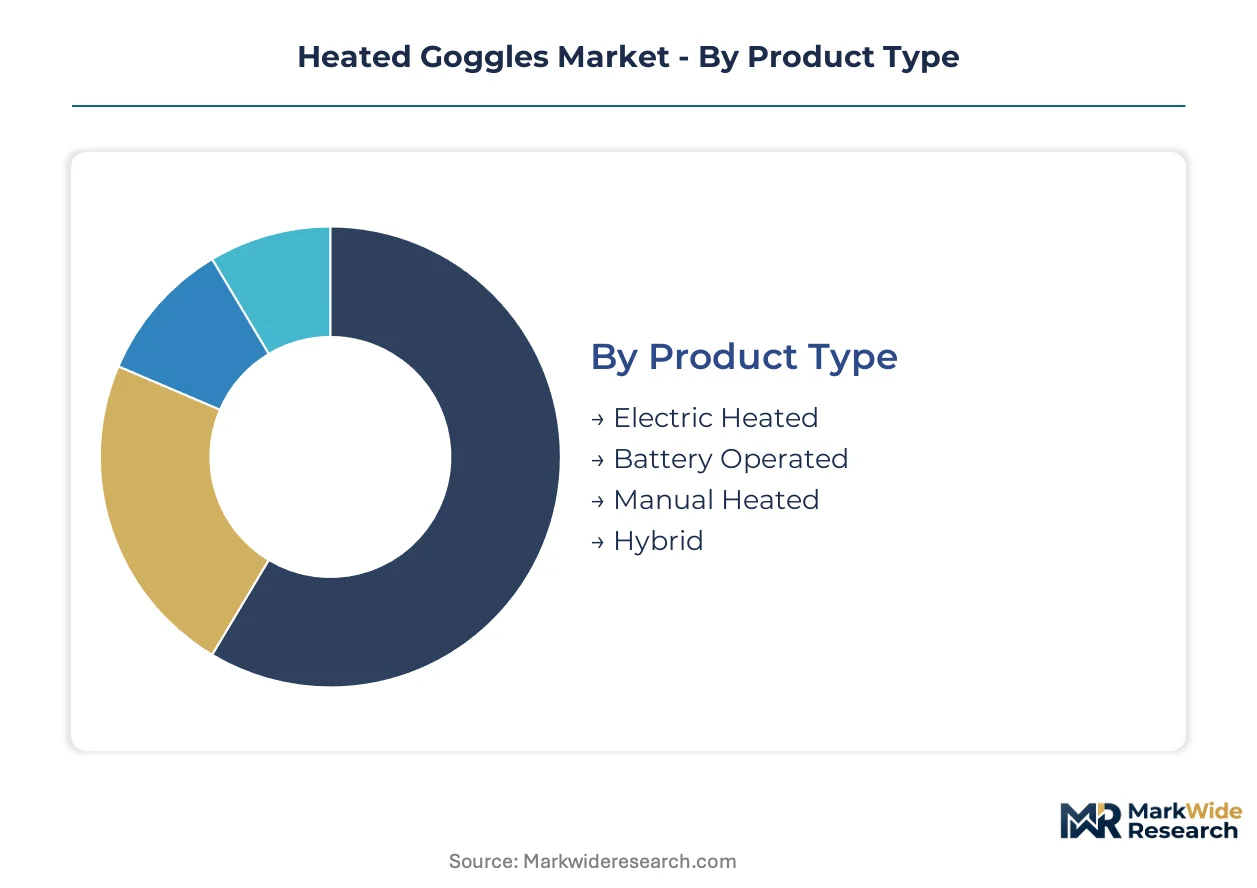
Heated goggles manufacturers must align R&D investment with distinct performance requirements across power architectures, user athletic intensity, and environmental exposure levels. Segment boundaries are blurring as hybrid systems and medical applications redraw traditional category lines.
Product Type:
Cost tier differentiation separates entry-level passive solutions from active thermal management systems with rechargeable power architectures.
- Battery Operated:Lithium-polymer cells embedded in frame temples deliver sustained heating through conductive elements. Demand concentrates in Colorado's resort corridor and Japan's Hokkaido prefecture where sub-zero optical clarity commands premium pricing.
- Hybrid:Dual-power flexibility allows switching between battery and manual thermal reservoirs. Backcountry skiers and ice-climbing guides adopt these configurations fastest, prioritizing runtime adaptability over single-mode efficiency.
- Electric Heated:Continuous power delivery through tethered connections suits industrial cold-weather operations with fixed power access.
- Manual Heated:Chemical or phase-change thermal packs occupy declining share as battery density improvements compress replacement cycles.
Battery Operated commands the established base. The steepest expansion runs through Hybrid configurations.
End User:
Application intensity dictates heating element durability requirements and frame fit certification standards.
- Snowboarders:Wide field-of-view lens geometries and impact-resistant frames accommodate aggressive riding styles and frequent tumbles. North American resort corridors drive volume as terrain park culture elevates equipment performance expectations.
- Athletes:Competitive racing specifications demand FIS-compliant optical clarity with active anti-fog under aerobic exertion. Alpine European markets concentrate procurement through team equipment contracts.
- Skiers:Recreational downhill and cross-country variants span price-performance tiers with modular power compatibility.
- Outdoor Enthusiasts:Multi-sport users prioritize interchangeability across snowshoeing, mountaineering, and motorized winter recreation.
Snowboarders anchor volume concentration. Athletes demonstrate the steepest technology premium tolerance.
Technology:
Material science advancement determines thermal efficiency ratios and manufacturing scalability.
- Carbon Fiber:Conductive filament weaving patterns distribute heat evenly across dual-pane lens assemblies. Patent thickets around geometric configurations constrain new entrant freedom-to-operate.
- Infrared Heating:Thin-film emitters enable zone-specific thermal targeting with lower power draw than conductive alternatives. Medical applications for Raynaud's phenomenon patients drive clinical validation investments.
- Thermal Insulation:Passive barrier layers complement active heating to reduce battery load in extreme ambient conditions.
- Smart Fabric:Responsive textile integration adjusts heating intensity based on facial temperature sensors and ambient moisture detection.
Carbon Fiber retains manufacturing maturity. Infrared Heating climbs fastest on medical reimbursement pathway expansion.
Application:
Environmental exposure severity and regulatory classification reshape distribution channel requirements.
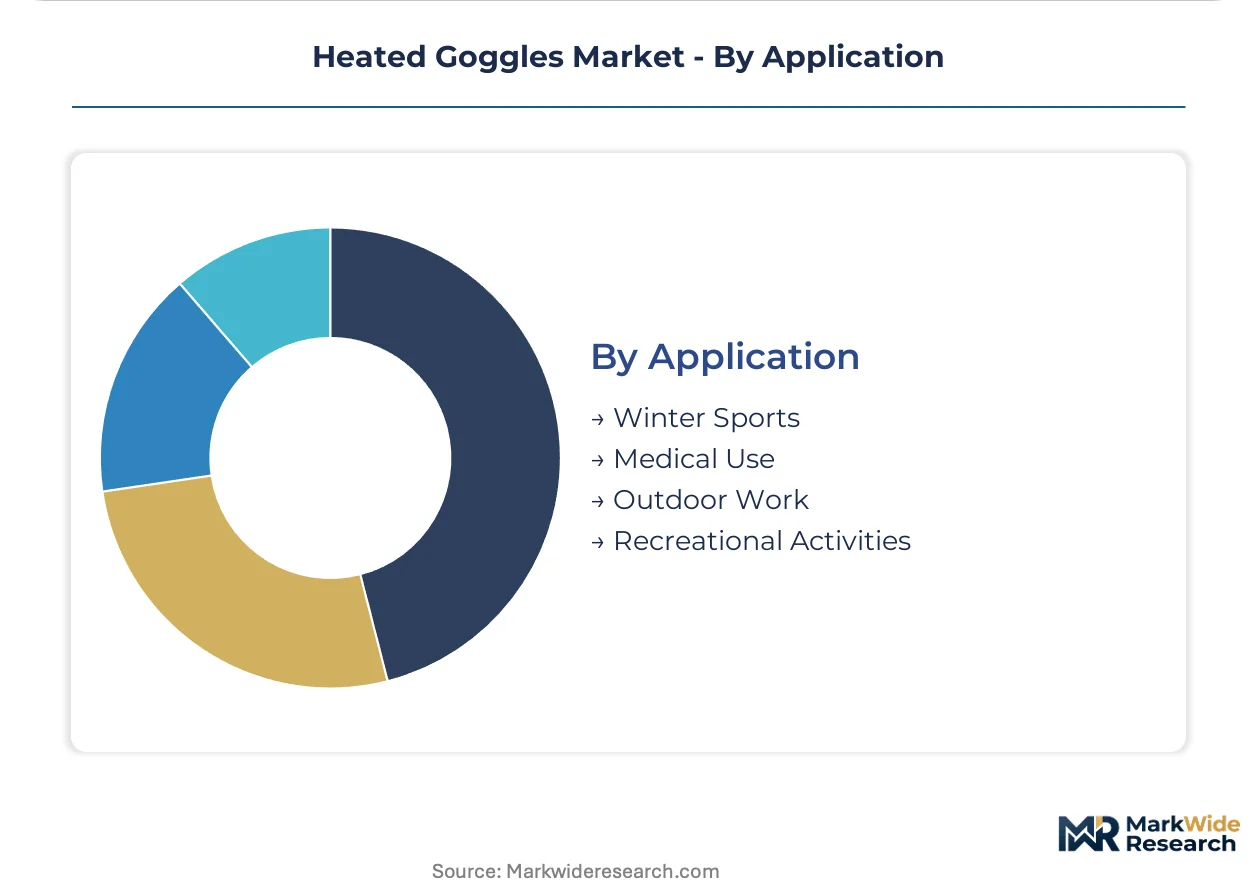
- Winter Sports:Resort skiing and competitive racing dominate absolute demand with established retail and rental shop networks. Colorado's Ikon Pass holder community exhibits highest subscription conversion rates for seasonal equipment access.
- Medical Use:Cold-induced vascular condition management represents the fastest-growing end-use category. FDA clearance for Raynaud's phenomenon claims opens reimbursement channels and clinical distribution networks.
- Outdoor Work:Utility, construction, and logistics operations in sub-zero climates require ANSI-rated impact protection combined with thermal management.
- Recreational Activities:Casual snowshoeing, sightseeing, and amateur photography prioritize comfort over performance certification.
Winter Sports commands the established base. Medical Use gains share fastest on regulatory clearance momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for wearable electronics is attracting contract assembly investment for export markets. Battery-powered thermal management systems find manufacturing scale in production-linked incentive zones. This policy driver reshapes regional competitive positioning across Asia-Pacific manufacturing corridors.
United States
FDA clearance pathways for vascular condition claims are opening reimbursement channels for medical-grade heated eyewear. Colorado's resort corridor concentrates absolute demand, with Ikon Pass holders driving subscription-based equipment leasing models. Denver-Boulder manufacturing clusters are scaling lithium-polymer assembly for domestic and export markets.
Japan
METI electrical safety standards harmonization is reducing certification costs for battery-powered personal equipment targeting Asian markets. Hokkaido prefecture anchors winter sports demand with sub-zero optical clarity commanding premium pricing. Nagoya industrial zones are producing carbon fiber heating element substrates for regional supply chains.
Germany
CE marking under EU MDR Article 10 is mandating biocompatibility testing for materials contacting periorbital skin. Alpine European markets show steepest compliance cost increases, with smaller brands consolidating. Bavarian precision optics clusters are adapting to extended clinical documentation timelines for therapeutic claims.
Sweden
Underpenetrated Nordic backcountry segments present expansion opportunities despite extreme winter conditions and high disposable income levels. EU Green Deal alignment pressures are shaping battery pack sustainability requirements for Scandinavian distribution. Stockholm-Uppsala technology corridors are developing smart fabric integration for responsive heating systems.
India
PLI scheme incentives for wearable electronics manufacturing are attracting contract assembly investment for export markets. BIS standards for electrical safety are converging with international protocols to streamline cross-border qualification. Tamil Nadu and Karnataka electronics manufacturing zones are scaling battery-powered personal equipment production for North American and European buyers.
Heated Goggles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Direct-to-consumer platforms and rental shop networks are disintermediating traditional sporting goods retail, compressing distributor margins while expanding addressable reach. Three archetypes dominate: vertically integrated optics manufacturers, direct-to-consumer equipment platforms, and medical-grade certification specialists. Strategic moves concentrate on backward integration into thermal lens production and technology licensing for hybrid power architectures.
Within the premium-tier vector, Oakley Inc. and Smith Optics exemplify vertically integrated manufacturing archetypes with in-house thermal system capabilities. POC Sports occupies a position within the medical-grade certification tier, leveraging European regulatory positioning for cold-weather optical protection claims. OutdoorMaster represents the direct-to-consumer channel control archetype, bypassing traditional retail markups through platform-based distribution. These three players anchor competitive positioning across distinct value capture mechanisms without overlapping strategic territory.
| Leading Market Players |
|---|
| Tempest Optics |
| Oakley, Inc. |
| Smith Optics |
| Anon Optics |
| Spy Optic |
| Dragon Alliance |
| POC Sports |
| Giro Sport Design |
| OutdoorMaster |
| Others |
Pricing and Supply Chain Analysis
Cobalt and lithium carbonate price volatility compresses margin pools across mid-tier product lines while simultaneously widening spreads between battery-operated and hybrid configurations. This commodity-driven cost pressure forces manufacturers to recalibrate tier positioning and sourcing geography, with certification-grade premiums becoming the primary buffer against input cost swings.
Pricing Analysis
Certification level creates the primary spread between economy and premium tiers, with FDA-cleared medical-grade variants commanding substantial premiums over recreational CE-marked alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differential thermal performance guarantees and battery runtime specifications. Pricing pressure stems from raw material commodity cycles, particularly lithium-polymer cell costs. Resort rental operators and subscription platforms exhibit highest price sensitivity, while backcountry specialists and medical users demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between China and North American markets dominates strategic sourcing decisions for battery pack assembly and carbon fiber heating element substrates. Manufacturing concentrates in China, Japan, and Germany, with Nagoya industrial zones producing conductive filament substrates and Bavarian clusters handling precision optics. Supply chains draw from germanium crystal suppliers concentrated in three facilities, creating single-source vulnerability for infrared emitter production. Distribution runs through direct-to-consumer platforms and resort rental networks, bypassing traditional sporting goods retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based equipment access is reconfiguring heated goggles from durable goods to consumable seasonal services, with platform economics favoring operators who control both thermal hardware and rental logistics infrastructure.
For Market Incumbents: Pre-empt platform commoditization by locking in exclusive resort corridor partnerships and securing captive supply of lithium-polymer cells through backward integration into battery assembly. Medical-grade certification investments create defensive moats against direct-to-consumer entrants lacking clinical validation capabilities. For New Entrants and Emerging Players: Establish a beachhead in underpenetrated Nordic backcountry segments where extreme winter conditions and high disposable income levels meet low competitive density. Hybrid power architectures offer the most penetrable technical wedge, with ice-climbing guides and backcountry skiers prioritizing runtime adaptability over brand heritage. For Investors and Strategic Acquirers: The market sits at a platform-economics inflection phase that favors vertically integrated rental operators over pure-product manufacturers. Long-term viability hinges on controlling seasonal inventory turns and subscription renewal rates rather than unit shipment volumes. Watch FDA clearance momentum for Raynaud's phenomenon claims as the signal indicating medical-channel scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Certification Investment | FDA clearance for vascular condition claims unlocks reimbursement channels and clinical distribution networks. |
| Hybrid Power Architecture Development | Dual-mode thermal systems capture backcountry skiers prioritizing runtime flexibility over single-mode efficiency. |
| Resort Corridor Partnership Lock-In | Exclusive rental shop agreements disintermediate traditional retail and compress competitor addressable reach. |
| Backward Integration into Battery Assembly | In-house lithium-polymer production buffers margin compression from cobalt and lithium carbonate price volatility. |
| Subscription Platform Launch | Seasonal access models convert Ikon Pass holders and younger demographics from purchase to recurring revenue. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with winter sports equipment buyers, resort rental operators, optical engineers, battery pack procurement managers, and regulatory affairs specialists at FDA and CE marking consultancies. Secondary validation drew from METI electrical safety filings, EU MDR technical documentation databases, customs trade records for lithium-polymer cells, and SEC filings from vertically integrated optics manufacturers. Bottom-up segment sizing triangulated against top-down market value estimates.
Calibration across the analysis window employed multi-dimensional segmentation modeling across power architecture, end-user athletic intensity, technology material, and application regulatory classification. CAGRs were derived from fitted growth curves applied to unit shipment and average selling price trajectories. Forecast inputs incorporated battery energy density improvement curves, regulatory clearance timeline assumptions, and subscription penetration rate scenarios.
Stress conditions across cobalt price bands, CE marking timeline delays, and Nordic adoption rate scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding lithium-polymer cost trajectories and hybrid system technical maturation. Material shifts in FDA reimbursement policy for heated eyewear would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Earplugs Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Cooking Gloves Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Hand Gloves Market
Protective Gear
Waterproof Cases Market
Protective Gear
China Pollution Mask Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Waterproof Boots Market
Protective Gear
Tactical Boots Market
Protective Gear
Dust Covers Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Bungee Cords and Accessories Market
Protective Gear
Pet Control Devices Market