
 Personal Flotation Devices Market | 2026-2036
Personal Flotation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Flotation Devices Market Intelligence
Market Context
A wide capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is reorganizing competitive tiers in personal flotation devices. Johnson Outdoors Inc. leverages captive manufacturing infrastructure across North American facilities to control cost curves. Mustang Survival Corp. anchors its position through military and first-responder contracts that demand sustained R&D investment. Survitec Group Limited competes via marine safety specialization and channel dominance in commercial shipping.
Technical Definition and Segment Structure
Personal flotation devices are wearable buoyancy apparatus engineered to keep wearers afloat in water, typically constructed with foam cores rated at 15.5 to 22 pounds minimum buoyancy or inflatable chambers activated by manual or automatic gas inflation mechanisms. Their primary purpose spans recreational water safety, commercial marine compliance, and emergency rescue operations where survival time directly correlates with flotation performance. Inflatable PFDs command expanding share among recreational boaters seeking low-profile comfort, while life jackets retain institutional dominance in regulated commercial fishing and marine rescue applications where foam reliability outweighs convenience premiums. Nylon and neoprene material segments split along performance-versus-price lines, with neoprene sustaining margin pools in water sports and cold-water rescue use cases.
Regulatory Frame and Outlook
The US Coast Guard enforces Type I through V classification standards that mandate minimum buoyancy, visibility, and performance testing for domestic waterways, while ISO 12402 governs international certification benchmarks for export-oriented manufacturers. The EU's PPE Regulation and CE marking requirements shape market access for products entering European recreational and commercial channels. Stakeholders must monitor evolving harmonization gaps between USCG and ISO testing protocols as divergence in inflation mechanism standards threatens to fragment product development roadmaps.
Market Dynamics
The US Coast Guard's Type I-V classification update is compressing certification timelines and forcing manufacturers to consolidate testing protocols across foam and inflatable architectures, reshaping competitive barriers around compliance infrastructure rather than scale alone.
Growth Catalysts
- Leisure marine participation:Recreational boaters in Florida, California, and Texas are replacing legacy foam vests with low-profile inflatable PFDs, driving unit velocity through marine retail channels.
- ISO 12402 harmonization pressure:Export-oriented manufacturers are consolidating product lines to serve both USCG and European markets simultaneously, reducing SKU complexity and accelerating inventory turns.
- Neoprene cold-water performance:Water sports operators and rescue services in the Pacific Northwest and Great Lakes states are specifying neoprene constructions for thermal protection, sustaining premium material demand.
Market Restraints
- CO2 cartridge supply concentration:Inflation mechanism production clusters in East Asian manufacturing zones, exposing inflatable PFD assemblers to shipping volatility and tariff exposure.
- Foam core petrochemical dependency:Closed-cell polyethylene and PVC foam inputs track crude oil indices, compressing margins for integrated manufacturers during feedstock price spikes.
- Manual inflation reliability thresholds:USCG Type V standards require 99.2% activation success rates in saltwater immersion testing, disqualifying marginal mechanism designs and elevating R&D burn rates.
Strategic Opportunities
- Smart PFD sensor integration:Automatic inflation systems incorporating GPS beacons and man-overboard alerts are converging with marine electronics ecosystems, opening adjacent revenue streams.
- Commercial fishing fleet modernization:Alaska and New England trawler operators face phased USCG compliance deadlines, creating concentrated replacement demand for hybrid foam-inflatable work vests.
- Direct-to-consumer channel expansion:Specialty water sports retailers and paddleboard outfitters are bypassing traditional marine distributors, capturing margin through subscription-based inspection and re-arming services.
Industry Challenges
- Flotation engineer talent scarcity:The intersection of marine safety engineering and textile manufacturing expertise concentrates in coastal Massachusetts and Seattle metro labor markets, constraining expansion timelines.
- Multi-jurisdiction certification lag:Simultaneous USCG, Transport Canada, and EU PPE approval processes extend product launch windows by 14-18 months for new inflatable architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Flotation Devices Market |
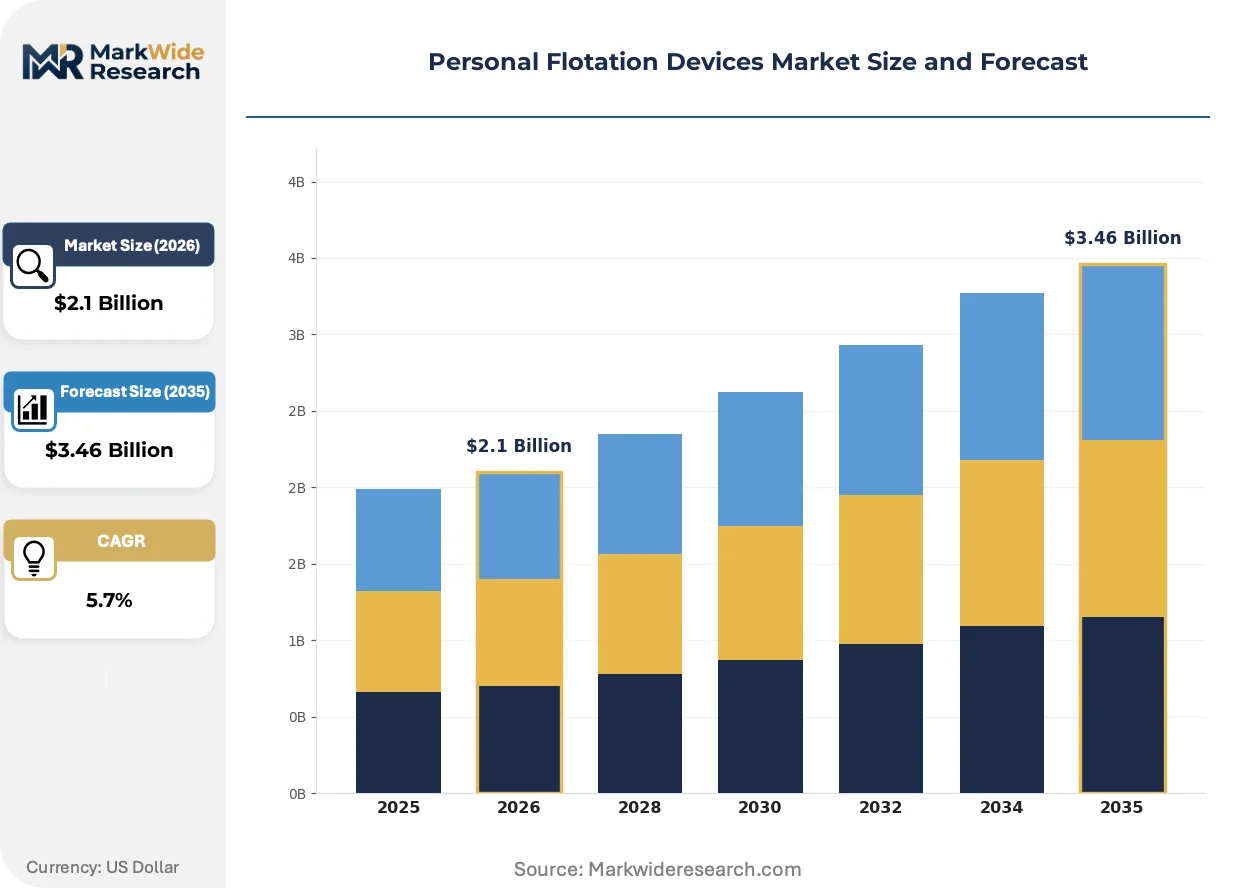
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.46 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Jackets, Life Vests, Buoyancy Aids, Inflatable PFDs End User: Recreational Boaters, Commercial Fishermen, Water Sports Enthusiasts, Emergency Services Material: Nylon, Neoprene, PVC, Polyester Application: Water Sports, Marine Rescue, Commercial Fishing, Leisure Activities |
| Companies Covered | Johnson Outdoors Inc., Aqua Lung International, Mustang Survival Corp., Survitec Group Limited, Kent Sporting Goods Co., Inc., The Coleman Company, Inc., LALIZAS, Hutchwilco Ltd., Kokatat, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Flotation Devices Market Strategic Shifts & Innovations
Personal flotation device architecture is bifurcating between minimalist inflatable platforms for recreational comfort and redundant foam systems for commercial reliability, with material science and embedded electronics driving divergence.
Inflatable bladder technology is miniaturizing. Hydrophobic fabric coatings and laser-welded seam construction enable 33% chamber volume reduction while maintaining 22-pound minimum buoyancy. Kayak anglers and stand-up paddleboard users in the Chesapeake Bay and Puget Sound corridors are adopting these slim-profile vests for unrestricted casting motion. The technology is compressing traditional foam life jacket shelf space in coastal marine retail.
REACH substance restrictions are tightening neoprene formulation standards. The European Chemicals Agency's candidate list expansion for short-chain chlorinated paraffins is forcing reformulation of cold-water rescue vests destined for EU commercial shipping channels. Manufacturers serving dual US-EU markets are migrating to limestone-based neoprene alternatives, elevating unit costs but preserving market access.
Marine safety procurement is consolidating around fleet-level compliance management. Charter operators and harbor master services in the Gulf Coast and Mid-Atlantic regions are shifting from transactional vest purchases to multi-year service contracts bundling equipment, inspection, and documentation. This unbundles traditional distributor relationships and favors vendors with captive service infrastructure.
Personal Flotation Devices Market Segmentation
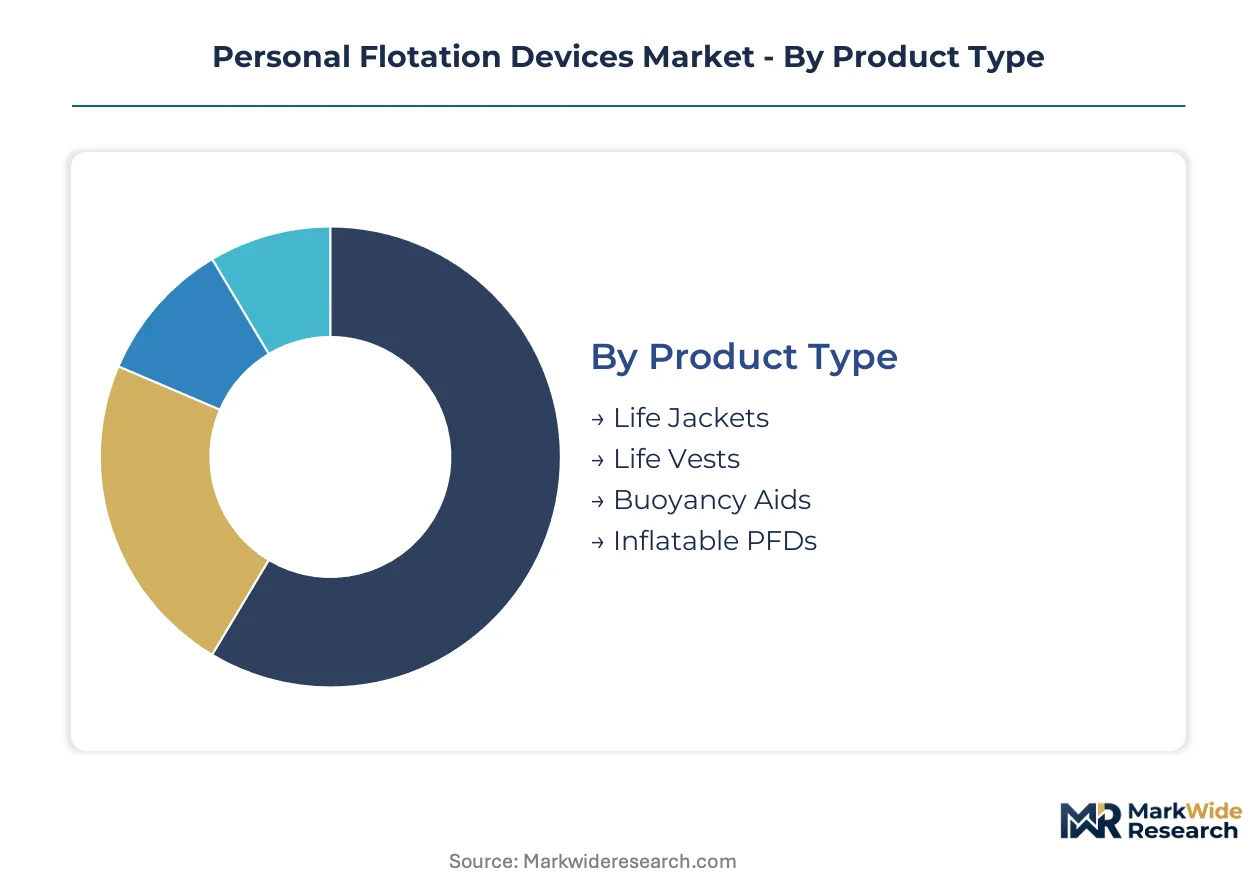
Product architecture in personal flotation devices diverges sharply between recreational comfort priorities and commercial compliance mandates. Segment boundaries shift as inflatable technology displaces foam in leisure channels while institutional procurement reinforces traditional construction for regulated marine work.
Product Type:
Substitution pressure runs strongest against legacy foam platforms as inflatable mechanisms achieve reliability parity at lower bulk and weight profiles.
- Life Jackets:Foam-core construction using closed-cell polyethylene or PVC achieves 15.5 to 22 pounds minimum buoyancy through inherently buoyant materials requiring no wearer action. Commercial fishing fleets in Alaska and New England face phased USCG compliance deadlines that sustain replacement demand despite inflatable encroachment in adjacent segments.
- Inflatable PFDs:Gas-inflation chambers activated manually or automatically via hydrostatic pressure sensors deliver equivalent buoyancy at roughly one-third the packed volume of foam equivalents. Recreational boaters in Florida, California, and Texas are replacing legacy vests through marine retail channels, compressing traditional foam shelf space in coastal stores.
- Life Vests:Terminology overlap with life jackets persists in consumer marketing, though technical specifications align with Type II USCG classifications for near-shore buoyancy. Kayak anglers and paddleboard users specify low-profile variants for unrestricted upper-body motion.
- Buoyancy Aids:Slimmer-profile foam constructions rated below full life jacket specifications serve water sports where mobility outweighs passive flotation requirements. Surf schools and wakeboard operators in coastal California and Australia specify these for supervised instruction environments.
Life Jackets retain volume leadership in regulated commercial channels; Inflatable PFDs hold the steepest expansion curve as recreational adoption accelerates.
End User:
Cost tier stratification separates institutional procurement with multi-year service contracts from transactional recreational purchases through specialty retail.
- Recreational Boaters:Leisure marine participation growth in coastal states drives replacement cycles, with inflatable PFDs capturing preference among cabin boat and sailboat operators seeking stowability. Channel expansion through paddleboard outfitters and direct-to-consumer platforms is capturing margin traditionally held by marine distributors.
- Commercial Fishermen:Alaska and New England trawler operators face USCG-mandated fleet modernization deadlines, creating concentrated demand for hybrid foam-inflatable work vests combining reliability with reduced bulk. Procurement is consolidating around multi-year service contracts bundling equipment, inspection, and documentation.
- Water Sports Enthusiasts:Wakeboard, waterski, and towed-sport participants prioritize neoprene constructions for thermal protection and impact cushioning. Operators in the Pacific Northwest and Great Lakes states specify cold-water performance grades.
- Emergency Services:First responder and search-and-rescue units demand ISO 12402-certified architectures with visible coloration and attachment points for tethered recovery. Military contracts through specialized suppliers sustain dedicated R&D investment.
Recreational Boaters dominate unit volume through retail velocity; Commercial Fishermen concentrate value through fleet-level contract structures.
Material:
Supply concentration in East Asian petrochemical processing shapes margin exposure across synthetic fabric categories.
- Neoprene:Synthetic rubber foam laminates provide thermal insulation and abrasion resistance for cold-water rescue and water sports applications. REACH substance restrictions on short-chain chlorinated paraffins are forcing reformulation toward limestone-based alternatives for EU market access, elevating unit costs.
- Nylon:Woven polyamide shells dominate inflatable PFD outer construction for tear resistance and UV stability at moderate cost. Marine retail channels in the United States specify nylon for recreational price-competitive tiers.
- PVC:Closed-cell foam cores and coated fabrics serve budget-conscious institutional procurement where chemical resistance outweighs weight penalties. Feedstock price volatility tracks crude oil indices directly.
- Polyester:Lower-cost woven alternatives to nylon sacrifice some abrasion resistance for price positioning in emerging market channels and disposable rescue applications.
Neoprene commands premium positioning in performance segments; Nylon sustains volume leadership through inflatable PFD expansion.
Application:
Customer type fragmentation separates leisure experience purchases from safety-critical procurement with liability exposure.
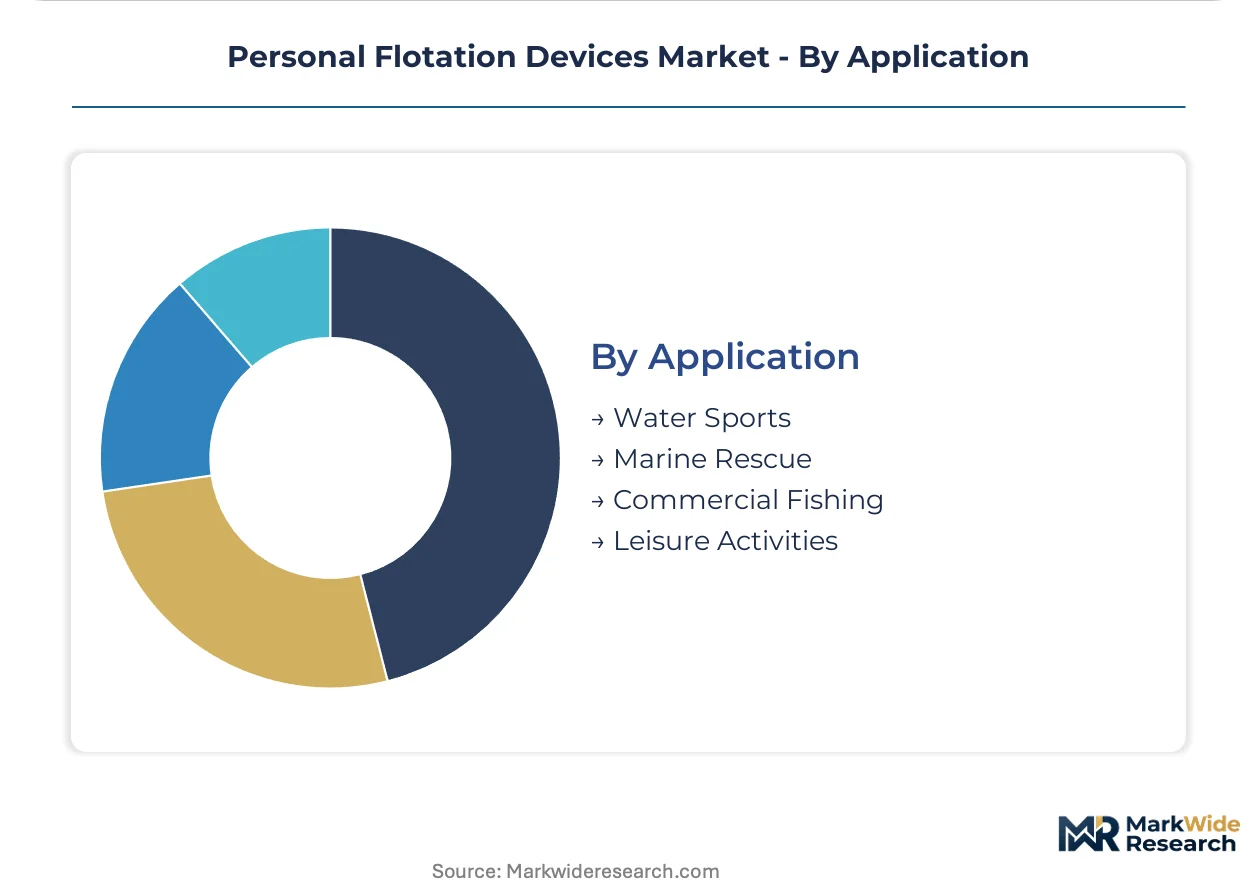
- Water Sports:Wakeboarding, waterskiing, and towed-sport applications specify impact-rated vest constructions with hinge panels for spinal flexibility. School and rental operators in Florida and California drive replacement velocity through high-wear utilization.
- Commercial Fishing:Work vest specifications mandate USCG Type I or hybrid Type V ratings with integrated harness points for man-overboard recovery. Fleet operators in Alaska face the most stringent enforcement timelines.
- Marine Rescue:Search-and-rescue and lifeguard services require high-visibility coloration, quick-don features, and compatibility with helicopter hoisting operations. Procurement concentrates through specialized safety distributors.
- Leisure Activities:Casual boating and shoreline recreation represent the largest addressable population but lowest per-unit specification, with inflatable PFDs displacing foam through comfort advantages.
Leisure Activities generate widest population reach; Commercial Fishing concentrates regulatory-driven replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between coastal states with strict USCG enforcement and inland regions where recreational adoption lags. Florida boaters replace inflatable PFDs every three to four seasons, while Great Lakes operators favor neoprene for thermal resilience. European demand concentrates in Mediterranean charter fleets facing REACH substance deadlines.
United States
Coastal states from Florida to Washington drive replacement velocity through USCG Type I-V compliance mandates. The Coast Guard's updated classification standards compress certification timelines for inflatable mechanisms. Marine retail clusters in Fort Lauderdale and Seattle concentrate inventory turns for low-profile recreational vests.
Canada
Transport Canada harmonization with USCG protocols enables cross-border product lines for Great Lakes and Pacific Coast operators. Cold-water rescue specifications in British Columbia and Nova Scotia sustain neoprene demand for thermal protection. Vancouver harbors specialized procurement for commercial fishing fleet modernization.
Germany
EU PPE Regulation and CE marking requirements shape access for inflatable architectures entering Baltic and North Sea channels. The country's national water safety regulator enforces ISO 12402 standards for commercial shipping and inland waterway operations. Hamburg anchors distribution for marine safety equipment serving Northern European charter fleets.
Australia
State-level maritime safety authorities in New South Wales and Queensland mandate wearable flotation for recreational vessel operators. Surf lifesaving clubs along the Gold Coast specify high-visibility buoyancy aids for patrol duties. Sydney clusters manufacturing for limestone-based neoprene alternatives responding to REACH restrictions.
Japan
METI standards and JIS certification requirements govern product entry for coastal fishing and recreational boating segments. Demographic shifts toward leisure marine participation in Kansai and Chubu regions drive inflatable PFD preference. Osaka manufacturers specialize in compact inflation mechanisms for regional export.
Personal Flotation Devices Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier competing on certification infrastructure and channel access. Three archetypes dominate: captive manufacturers controlling foam and textile inputs, military-first responders sustaining R&D investment through institutional contracts, and marine safety specialists leveraging fleet-level service bundling. Competitive moves concentrate on consolidation of testing protocols across jurisdictions and backward integration into inflation mechanism supply.
Among North American-integrated manufacturers, Johnson Outdoors Inc. exemplifies captive production infrastructure, while Mustang Survival Corp. anchors the military-contractor archetype with sustained technical investment. Survitec Group Limited occupies the marine specialization tier through channel dominance in commercial shipping procurement.
| Leading Market Players |
|---|
| Johnson Outdoors Inc. |
| Aqua Lung International |
| Mustang Survival Corp. |
| Survitec Group Limited |
| Kent Sporting Goods Co., Inc. |
| The Coleman Company, Inc. |
| LALIZAS |
| Hutchwilco Ltd. |
| Kokatat, Inc. |
| Others |
Cost & Logistics Intelligence
USCG Type I-V classification standards gate both supplier qualification and price differentiation simultaneously, compressing certification timelines for inflatable mechanisms while elevating compliance costs that stratify pricing tiers across recreational and commercial channels.
Pricing Analysis
Long-term service contracts bundling equipment, inspection, and re-arming dominate commercial fishing procurement, while transactional per-unit sales persist in recreational retail. Price differentiation separates USCG Type V certified hybrids from basic Type II foam vests, with neoprene cold-water grades commanding additional premiums. Cost compression in inflatable PFD tiers intensifies as East Asian CO2 cartridge supply volatility feeds through to assembler margins. Charter operators and fleet managers show lowest price sensitivity due to liability exposure, while casual recreational boaters gravitate toward economy nylon constructions.
Supply Chain Analysis
China and Taiwan anchor CO2 inflation mechanism production, while Vietnam and Bangladesh concentrate textile cutting and sewing operations for nylon shell assemblies. Closed-cell polyethylene foam cores and hydrophobic fabric coatings draw from South Korean and Japanese petrochemical processors. Single-source vulnerability runs through East Asian gas cartridge manufacturing clusters exposed to shipping disruption and tariff exposure. Distribution runs through marine retail chains in Fort Lauderdale and Seattle, with direct-to-consumer platforms capturing growing share from traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward fleet-level procurement consolidation in commercial fishing and charter operations, fragmenting transactional demand across recreational channels while concentrating contract value among multi-year service bundlers.
For Market Incumbents: Fortify certification infrastructure across USCG, Transport Canada, and EU PPE jurisdictions to extend product launch windows that marginal competitors cannot match. Deepen captive production of inflation mechanisms to offset East Asian supply volatility threatening margin stability in inflatable PFD tiers. For New Entrants and Emerging Players: Post-sale inspection and re-arming services represent underserved white space where incumbents rely on third-party distributors. Target paddleboard outfitters and kayak angler communities in the Chesapeake Bay and Puget Sound corridors through subscription-based maintenance programs bypassing traditional marine retail markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart PFD sensor integration as GPS beacon and man-overboard alert technologies converge with marine electronics ecosystems. Acquisition candidates with ISO 12402 testing infrastructure and established military-first responder contracts offer durable positioning. Watch for harmonization gaps between USCG and inflation mechanism standards as inflection signals for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inflation Mechanisms | Captive CO2 cartridge production insulates margins from East Asian supply volatility and tariff exposure. |
| Smart Sensor Platform Development | GPS beacon integration with marine electronics ecosystems opens adjacent revenue streams beyond hardware sales. |
| Fleet-Level Service Contract Expansion | Multi-year bundling of equipment, inspection, and documentation captures value from consolidating commercial procurement. |
| Limestone-Based Neoprene Reformulation | REACH-compliant alternatives preserve EU market access as chlorinated paraffin restrictions tighten. |
| Direct-to-Consumer Channel Buildout | Subscription-based re-arming services bypass traditional distributor relationships in recreational segments. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary research phases, incorporating marine safety engineers at Johnson Outdoors and Mustang Survival, procurement managers at Alaska trawler cooperatives, retail buyers at Fort Lauderdale marine distributors, and USCG certification officials. Secondary validation drew from USCG approval databases, ISO 12402 technical documentation, EU PPE Regulation filings, and customs trade records for neoprene and CO2 cartridge flows. Bottom-up unit economics triangulated against top-down market sizing across product architecture, end-user segment, material composition, and application type.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented demand curves for inflatable versus foam platforms, recreational versus commercial procurement patterns, and neoprene versus nylon material splits. CAGRs derived from replacement cycle analysis tied to USCG compliance deadlines, leisure marine participation indices, and fleet modernization schedules in Alaska and New England.
Forecasts assume regulatory continuity in USCG Type I-V standards, EU PPE Regulation, and Transport Canada harmonization protocols; material policy shifts in inflation mechanism certification or REACH substance restrictions would require re-modeling. Recalibration cycles align with material shifts in USCG classification updates, ISO 12402 revision schedules, and petrochemical feedstock volatility patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Waterproof Boots Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Combat Boots Market
Protective Gear
China Pollution Mask Market
Protective Gear
Helmets Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Insect Repellent Market
Protective Gear
Work Boots Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Disposable Hygiene Footwear Market