
 Pet Control Devices Market | 2026-2036
Pet Control Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Control Devices Market Analytics
Aftermarket service revenue from subscription-based location tracking and cloud-stored activity data is tilting margin pools away from one-time hardware sales toward recurring software income. Garmin Ltd. leverages its proprietary GPS chipset ecosystem to command premium positioning in outdoor training applications. Tractive GmbH anchors its European-installed base with tiered cellular data plans that reduce customer churn. PetSafe Brands competes through broad retail distribution and backward integration into collar manufacturing.
Pet control devices encompass electronic systems designed to manage, monitor, or modify animal behavior through radio-frequency, cellular, or satellite-linked hardware paired with receiver collars or wearable sensors, typically operating on frequencies between 400 MHz and 2.4 GHz with IP67-rated waterproofing for outdoor deployment. These systems serve commercial and consumer end users by enabling geofenced containment, remote command delivery, biometric monitoring, or real-time location transmission to mobile applications. Smart collars and GPS trackers capture the fastest-expanding margin pools as cellular module costs decline and pet owners prioritize safety monitoring over basic indoor control functions. Electric fences retain volume leadership in rural and semi-rural applications where physical fencing remains impractical, though this segment shows slower technology refresh cycles.
The U.S. Federal Communications Commission enforces Part 15 rules on unintentional radiators, which constrains transmitter power and frequency stability for all RF-based pet containment and training devices sold in the American market. The European Union's Radio Equipment Directive and REACH chemical restrictions on collar materials jointly shape product design cycles and market access timelines for manufacturers targeting EU distribution. Stakeholders must monitor evolving spectrum allocation decisions and emerging state-level animal welfare legislation that could mandate biometric reporting standards or restrict certain corrective stimulus thresholds.
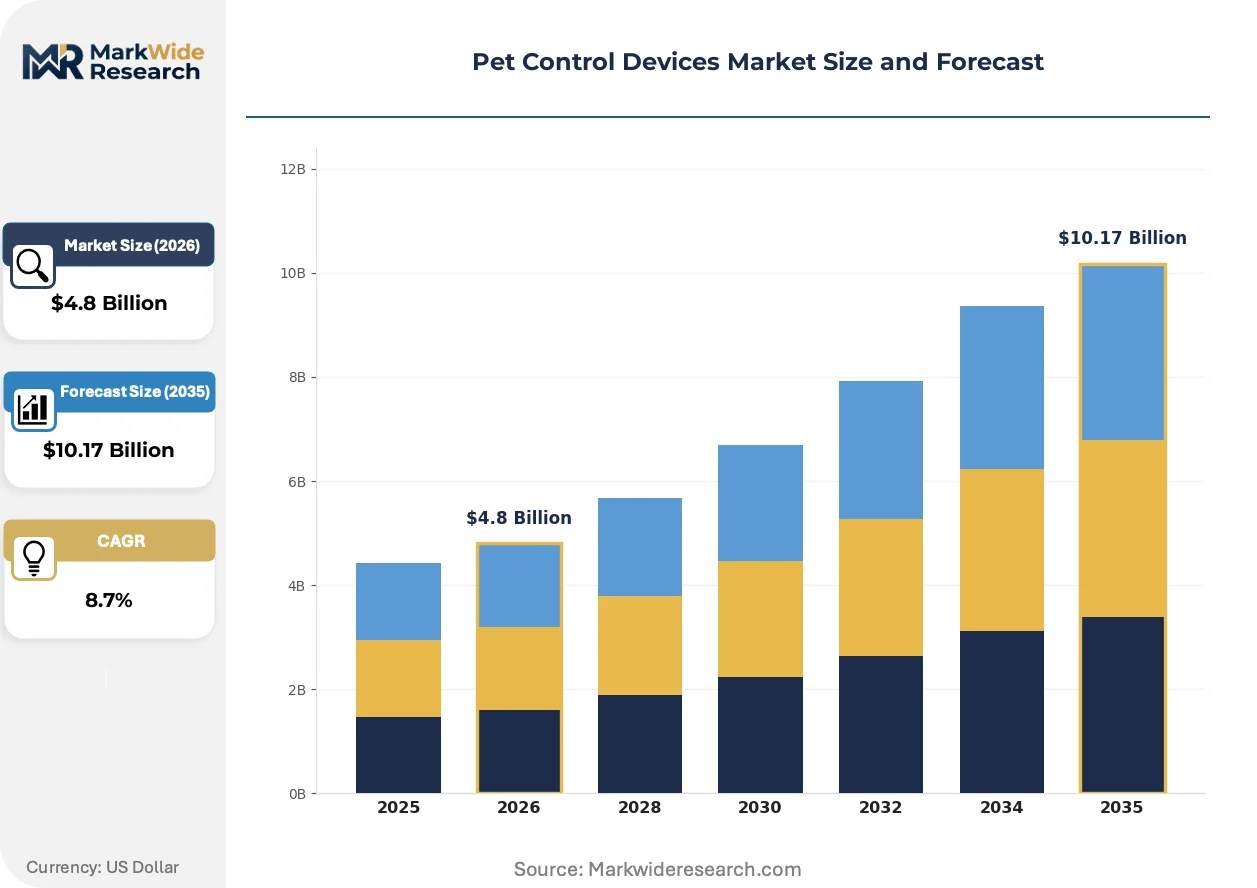
Market Dynamics
Cellular module cost deflation is compressing hardware margins while unlocking recurring software revenue streams across pet safety and training applications. This structural shift is tilting value capture toward subscription-based location services and cloud-stored biometric data, forcing manufacturers to reconfigure business models around lifetime customer value rather than one-time collar sales.
Growth Catalysts
- FCC Part 15 Equipment Authorization:Tightened transmitter power and frequency stability requirements are accelerating compliance investments by domestic manufacturers, filtering out marginal competitors and consolidating procurement relationships with certified suppliers.
- Veterinary Clinic Procurement:Professional training facilities are expanding GPS-enabled system deployments for behavioral monitoring, creating institutional demand channels with higher attach rates for cellular data plans.
- Suburban Household Concentration:Exurban markets with elevated pet ownership rates are driving replacement cycles for legacy radio-frequency containment systems with satellite-linked alternatives.
Market Restraints
- Cellular Module Supply Concentration:Dependence on Asian semiconductor foundries for LTE-M and NB-IoT chipsets exposes manufacturers to lead time volatility and tariff exposure.
- REACH Chemical Restrictions:ECHA-mandated limitations on collar material compositions extend EU product design cycles and delay market access timelines.
- Physical Fencing Substitution:Traditional perimeter solutions retain cost advantages in rural applications with ample property boundaries, constraining electric fence penetration.
Strategic Opportunities
- Biometric Reporting Mandates:Emerging state-level animal welfare legislation in the United States is creating compliance-driven demand for wearable health monitoring devices.
- AI-Enabled Behavioral Analytics:Convergence of edge computing and machine learning algorithms is enabling predictive stress detection and automated training intervention.
- Direct-to-Consumer Channels:Bypassing retail intermediaries through manufacturer-owned e-commerce platforms captures margin and enables tiered subscription packaging.
Industry Challenges
- RF Engineering Talent Scarcity:Shortage of designers experienced in 400 MHz to 2.4 GHz antenna optimization for IP67-rated wearables delays product development timelines.
- Multi-Regulatory Certification Burden:Simultaneous FCC, CE marking, and state-level animal welfare compliance creates documentation complexity and testing cost inflation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Control Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Fences, Remote Trainers, GPS Trackers, Smart Collars Application: Outdoor Training, Indoor Control, Safety Monitoring, Activity Tracking End User: Pet Owners, Professional Trainers, Veterinary Clinics, Animal Shelters Technology: Bluetooth, Wi-Fi, RFID, Cellular |
| Companies Covered | PetSafe Brands, Whistle Labs, Garmin Ltd., Tractive GmbH, FitBark Inc., Petcube Inc., Sure Petcare, PetPace LLC, Furbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Control Devices Market Evolving Landscape
Artificial intelligence integration is transforming passive tracking devices into predictive health and behavior management platforms. This evolution is compressing the boundary between consumer electronics and veterinary diagnostics.
Machine learning algorithms embedded in collar-mounted processors are digitizing raw accelerometer and GPS telemetry into actionable behavioral insights. Veterinary telemedicine providers are adopting these systems at accelerating pace for remote patient monitoring. The technology is digitizing traditional in-clinic observation into continuous ambient data collection, expanding addressable market scope beyond containment into preventive care.
The FCC's equipment authorization rules are tightening electromagnetic emission standards for unintentional radiators. Manufacturers face expanded testing protocols and documentation requirements before commercial release. Radio-frequency pet containment products bear the heaviest compliance burden, with design cycles extending to accommodate regulatory review timelines.
Pet owner purchasing behavior is fragmenting across channel types, with subscription bundling displacing standalone hardware transactions. Direct manufacturer relationships are capturing share from retail intermediaries through cellular plan packaging. This shift concentrates most visibly in suburban United States markets where smartphone app integration drives brand loyalty and reduces price sensitivity.
Pet Control Devices Market Segmentation
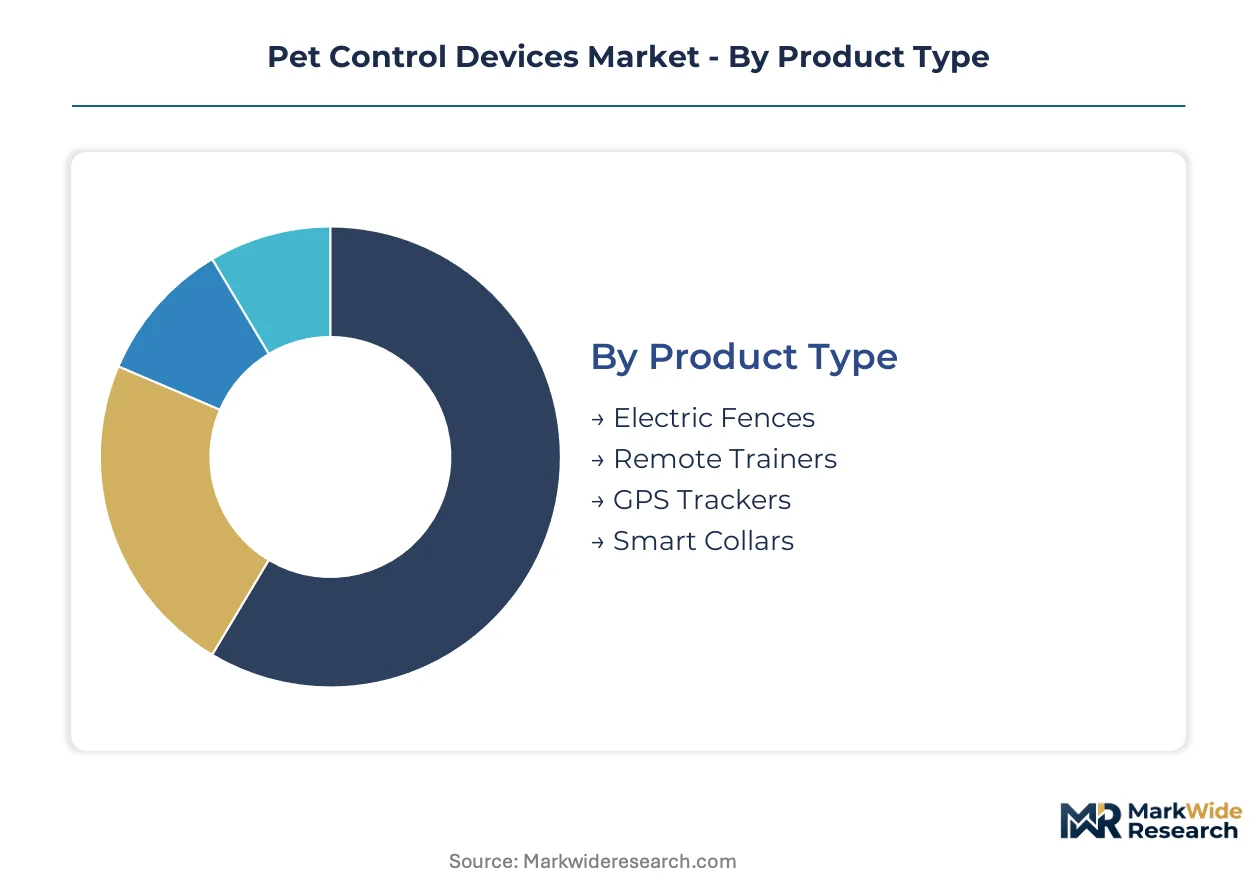
Segmentation in pet control devices reveals divergent margin architectures across hardware categories and diverging procurement patterns between consumer and institutional channels. Understanding these splits enables manufacturers to align R&D investment with the highest-value use cases and compliance requirements.
Product Type:
Use-case spectrum spans passive containment through active behavioral intervention to predictive health management, with technology intensity and recurring revenue potential escalating across that progression.
- GPS Trackers:Satellite-linked modules transmit real-time location data to mobile applications, typically incorporating LTE-M or NB-IoT chipsets with IP67-rated housings. Demand concentrates in suburban United States households where off-leash recreation and theft recovery concerns drive cellular subscription attach rates above other product categories.
- Smart Collars:Integrated sensor arrays capture accelerometer, temperature, and biometric signals processed through edge computing for predictive health alerts. Veterinary clinics in exurban markets are expanding procurement for remote patient monitoring, converting episodic clinic visits into continuous data relationships.
- Electric Fences:Radio-frequency boundary systems with buried wire or wireless transmitter configurations.
- Remote Trainers:Handheld transmitter and receiver collar pairings delivering tone, vibration, or static stimulus.
Established volume favors electric fences; emerging adoption favors smart collars.
Application:
Cost tier stratification separates basic containment functions from premium predictive services, with subscription bundling concentrated in higher-value application layers.
- Safety Monitoring:Geofenced alerts, escape notifications, and real-time location recovery services delivered through cellular-connected hardware. Professional trainers in the United States are deploying these systems for client dogs in board-and-train programs, creating institutional demand with enterprise-grade data management requirements.
- Activity Tracking:Continuous accelerometer and GPS telemetry converted into exercise metrics, sleep quality scores, and behavioral pattern recognition through cloud-based analytics. Pet owners in smartphone-integrated households show highest willingness-to-pay for tiered subscription plans with veterinary data sharing.
- Outdoor Training:Command delivery and behavioral conditioning in field environments.
- Indoor Control:Boundary enforcement and behavior modification within residential structures.
Margin pools concentrate in safety monitoring; volume throughput remains strongest in outdoor training.
End User:
Customer type determines procurement channel, with institutional buyers demanding certification documentation and API integration that consumer channels rarely require.
- Veterinary Clinics:Licensed practices purchasing biometric monitoring systems for remote patient management and preventive care program expansion. FCC Part 15 equipment authorization and state veterinary board compliance documentation are mandatory procurement filters.
- Professional Trainers:Certified behaviorists and training facilities deploying GPS-enabled systems for client program transparency and liability reduction.
- Pet Owners:Individual household purchasers through retail or direct-to-consumer channels.
- Animal Shelters:Municipal and nonprofit facilities managing intake populations with basic identification and containment needs.
Procurement sophistication peaks with veterinary clinics; price sensitivity concentrates in animal shelters.
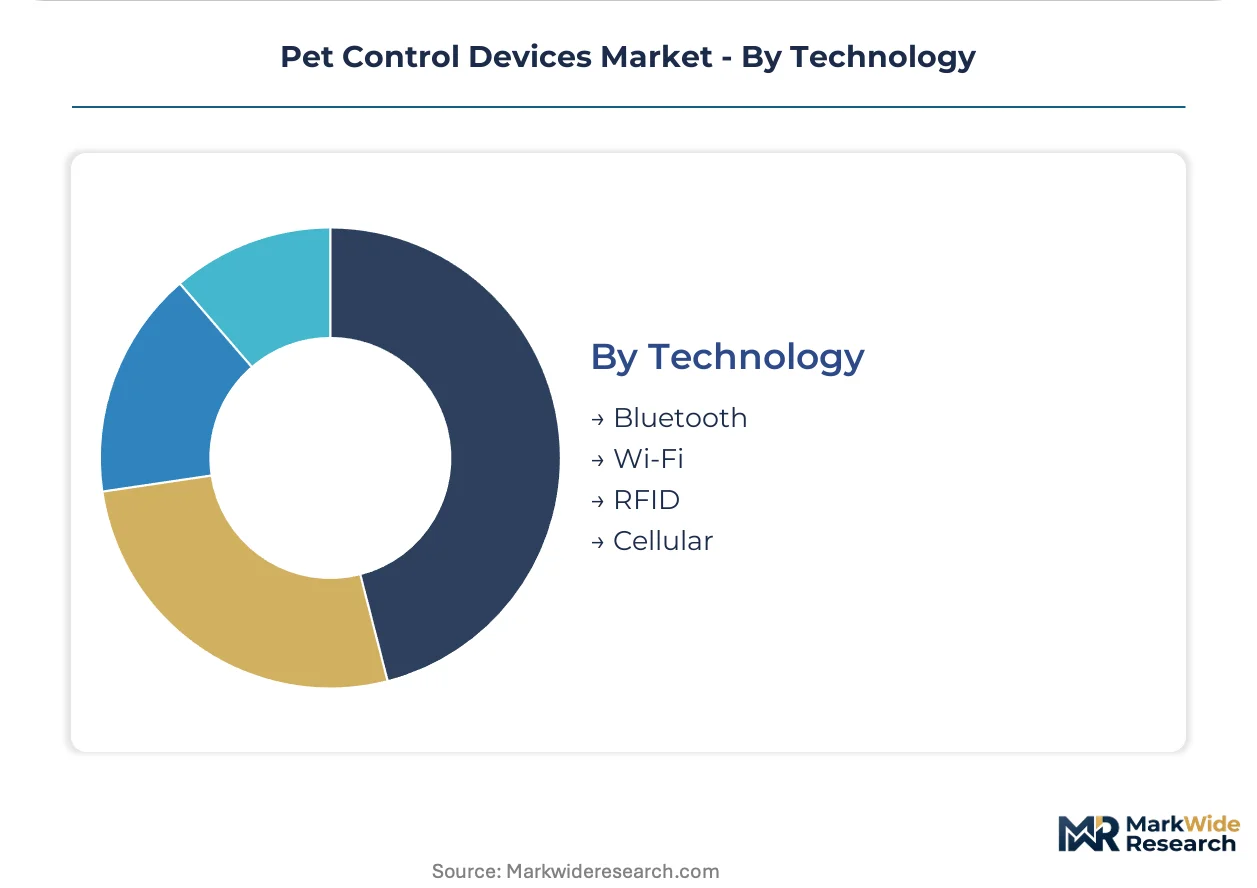
Technology:
Supply concentration in cellular module manufacturing creates cost deflation trajectories that restructure competitive positioning across connectivity tiers.
- Cellular:LTE-M and NB-IoT chipsets enabling wide-area coverage independent of smartphone proximity, with subscription revenue models built on carrier data plans. REACH chemical restrictions on collar materials and FCC transmitter power limits jointly shape hardware design cycles for manufacturers targeting transatlantic distribution.
- Bluetooth:Short-range wireless protocol for indoor proximity applications and smartphone-tethered control.
- Wi-Fi:Higher-bandwidth connectivity for home-based camera and sensor integration.
- RFID:Passive identification tags with limited range and no real-time tracking capability.
Cellular connectivity commands premium positioning; Bluetooth retains cost advantage in indoor-only deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with suburban United States households absorbing premium cellular subscriptions while rural markets in developing economies favor basic radio-frequency containment systems. Professional procurement channels in Western Europe and North America drive institutional-grade demand with compliance documentation requirements. Emerging adoption in East Asia concentrates in metropolitan pet-owning households with smartphone-integrated lifestyles.
United States
Suburban and exurban markets with elevated pet ownership rates are accelerating replacement cycles for legacy containment systems with satellite-linked alternatives. The Federal Communications Commission enforces Part 15 rules on unintentional radiators, constraining transmitter power and frequency stability for all RF-based devices. The Dallas-Fort Worth metroplex anchors distribution infrastructure for cellular-enabled training systems serving professional facilities.
Germany
Veterinary clinics in Bavaria and North Rhine-Westphalia are expanding procurement of biometric monitoring systems for remote patient management programs. The European Union's Radio Equipment Directive and ECHA-mandated REACH chemical restrictions on collar materials jointly shape product design cycles. Stuttgart's precision electronics cluster supplies antenna optimization expertise for IP67-rated wearable deployments.
United Kingdom
Greater London's dense urban environment drives demand for compact GPS trackers with theft recovery functionality among apartment-dwelling pet owners. CE marking requirements under the EU-UK Trade and Cooperation Agreement maintain alignment with European technical standards. Cambridge's technology corridor hosts edge computing development for predictive behavioral analytics.
Japan
Metropolitan Tokyo and Osaka households with declining birth rates and elevated pet humanization trends are adopting premium smart collars with health monitoring capabilities. METI oversees radio equipment type certification under the Radio Law, with JIS standards governing waterproofing specifications. Yokohama's consumer electronics manufacturing base produces compact sensor arrays for export markets.
Australia
Rural property owners in Queensland and Western Australia maintain strong demand for electric fence systems where physical perimeter construction remains impractical. The Australian Communications and Media Authority regulates spectrum allocation for pet containment devices under radiocommunications licensing frameworks. Sydney's veterinary technology sector pilots telemedicine integrations with collar-mounted biometric systems.
Pet Control Devices Market Competitive Landscape
Capability concentration sits with specialized RF engineering houses; scale advantage sits with diversified consumer electronics conglomerates. The market structures around three tiers: premium-positioned GPS ecosystem owners, mid-market cellular service bundlers, and value-oriented retail distributors. Strategic moves center on backward integration into collar manufacturing and direct-to-consumer channel bypass of retail intermediaries.
Within the premium hardware tier, Garmin Ltd. and Tractive GmbH occupy positions defined by proprietary technology control. Garmin leverages its captive GPS chipset ecosystem for outdoor training applications. Tractive anchors European market presence through cellular data plan structures. PetSafe Brands exemplifies the scale-driven distribution archetype with broad retail penetration and in-house manufacturing capabilities.
| Leading Market Players |
|---|
| PetSafe Brands |
| Whistle Labs |
| Garmin Ltd. |
| Tractive GmbH |
| FitBark Inc. |
| Petcube Inc. |
| Sure Petcare |
| PetPace LLC |
| Furbo |
| Others |
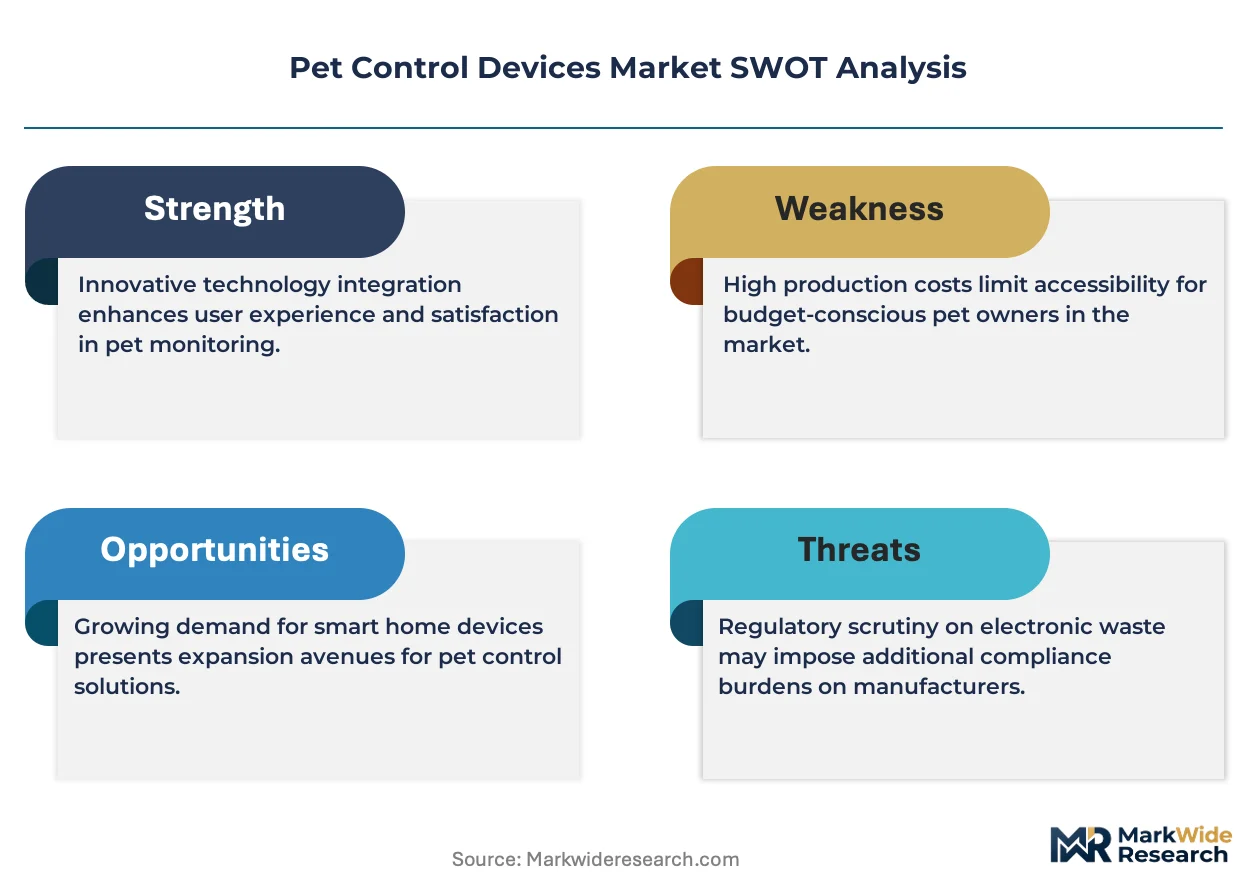
Value Network & Pricing Analysis
Asian semiconductor foundries supplying LTE-M and NB-IoT chipsets concentrate upstream leverage, redirecting margin capture toward subscription-based location services and cloud-stored biometric data downstream. Cellular module cost deflation compresses hardware margins while amplifying lifetime customer value through recurring software revenue pools.
Pricing Analysis
After-sales subscription revenue from cellular data plans and cloud analytics tiers drives lifetime value, displacing one-time hardware transactions as the dominant pricing model. Price differentiation hinges on certification grade—FCC Part 15 authorization versus uncertified alternatives—and after-sales service bundling including veterinary data sharing. Pricing pressure stems from cellular module cost deflation intensifying competition in hardware tiers. Pet owners in smartphone-integrated suburban households show lowest price sensitivity, while animal shelters concentrate price sensitivity in basic identification categories.
Supply Chain Analysis
Extended payment terms from Asian semiconductor foundries shape working capital structures for device manufacturers assembling IP67-rated housings. Supply concentrates in Taiwan for cellular chipsets, China for sensor arrays and battery components, and Germany for precision antenna optimization. Raw material dependencies include lithium-ion cells, GPS receiver modules, and REACH-compliant collar polymers. Tariff exposure on Asian semiconductor imports presents structural supply chain risk. Distribution runs through veterinary clinic procurement channels, direct-to-consumer e-commerce platforms, and broad retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures around a defensive moat of regulatory entrenchment—FCC Part 15 certification creates switching costs that filter marginal competitors and consolidate procurement relationships with certified suppliers.
For Market Incumbents: Pre-empt emerging AI-enabled behavioral analytics entrants by deepening backward integration into collar manufacturing and capturing direct-to-consumer channel relationships. FCC equipment authorization tightening accelerates compliance investments that marginal competitors cannot absorb. Certification documentation capabilities and API integration for veterinary clinic procurement represent priority defensive levers. For New Entrants and Emerging Players: Establish a beachhead in biometric monitoring systems for veterinary telemedicine providers, where institutional procurement channels demand enterprise-grade data management that incumbent retail distributors underserve. Animal shelters present the most penetrable segment for basic identification and containment needs. A go-to-market angle through state-level animal welfare legislation compliance creates regulatory-driven demand capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cellular service bundlers possessing tiered data plan infrastructures and European-installed bases. Long-term viability centers on recurring revenue attachment rates and customer lifetime value expansion across the projection horizon. Acquisition targets should demonstrate veterinary clinic procurement relationships and FCC certification capabilities. The signal to watch is state-level biometric reporting mandate adoption as inflection indicator for preventive care segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collar Manufacturing | In-house production of IP67-rated housings reduces REACH compliance costs and accelerates EU market access timelines. |
| Direct-to-Consumer Channel Launch | Manufacturer-owned e-commerce platforms bypass retail intermediaries and enable tiered subscription packaging for cellular data plans. |
| AI-Enabled Behavioral Analytics Development | Edge computing integration with veterinary telemedicine providers converts episodic clinic visits into continuous data relationships. |
| Veterinary Clinic Partnership Expansion | Institutional procurement channels with enterprise-grade API integration requirements concentrate in exurban professional training facilities. |
| FCC Certification Investment Acceleration | Part 15 equipment authorization capabilities filter competitors and consolidate supplier relationships with certified RF engineering houses. |
Research Methodology
Cross-validation between primary interviews with veterinary clinic procurement managers, professional dog trainers, RF engineering directors, and cellular module suppliers anchors the qualitative findings against secondary validation from FCC equipment authorization databases, ECHA REACH registration records, and veterinary telemedicine platform disclosures. Customs data on cellular chipset imports and SEC filings from diversified consumer electronics conglomerates provide trade flow and capital allocation triangulation. Bottom-up demand modeling across suburban household penetration rates and top-down market sizing from hardware shipment estimates converge on segment-level outputs.
Calibration against historical replacement cycles for radio-frequency containment systems and satellite-linked adoption curves structures the analytical framework across the analysis window. Segmentation dimensions include product type, application layer, end-user procurement channel, and connectivity technology tier. CAGRs derive from regression analysis of cellular subscription attach rates and hardware cost deflation trajectories. Veterinary clinic deployment rates and state-level animal welfare legislative momentum serve as industry-specific forecast inputs.
Sensitivities concentrate around FCC spectrum allocation decisions, REACH chemical restriction amendments, and cellular carrier data plan pricing shifts. Forecasts reflect documented assumptions on module cost trajectories and regulatory compliance timelines. Macroeconomic deviation in pet ownership economics, regulatory acceleration in biometric reporting mandates, or technological disruption in AI behavioral prediction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Waterproof Boots Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Helmet Lining Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Europe Lanyards Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Combat Boots Market
Protective Gear
Insect Repellent Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
China Pollution Mask Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Safety Shoes Market
Protective Gear
Earplug Distributor Market