
 Combat Boots Market | 2026-2036
Combat Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Combat Boots Market Outlook
Aftermarket sole replacement and resoling services is fragmenting as original manufacturers build captive refurbishment networks alongside independent cobblers. Danner leverages its recrafting program to extend product lifecycles and capture repeat revenue from institutional buyers. HAIX sustains a vertically integrated production model spanning German tanneries to Moldovan stitching facilities, insulating margin pools from raw material volatility. Rocky Brands competes through concentrated investment in domestic Berry Amendment-compliant supply chains, anchoring Pentagon contract eligibility.
Combat boots are ankle-to-mid-calf height footwear engineered with reinforced toe caps, puncture-resistant soles, and moisture-wicking liners, typically constructed from full-grain leather uppers bonded to rubber or polyurethane outsoles through cemented or stitch-down methods, designed to protect wearers during prolonged load-bearing activity across variable terrain. The tactical product type dominates procurement volumes among law enforcement agencies prioritizing lightweight chassis over ballistic protection, while the military category anchors the highest per-unit pricing due to integrated gore-tex membranes and flame-resistant treatments. Leather material grades command premium positioning in special operations contracts, whereas synthetic blends gain share in tropical deployment configurations where mold resistance outweighs abrasion durability.
FDA oversight of footwear chemical emissions intersects with EPA tanning effluent standards to elevate compliance costs for domestic manufacturers serving federal contracts. The Berry Amendment, administered through the Department of Defense, mandates US-origin materials for military end-use, restricting sourcing flexibility while protecting domestic tannery employment clusters in Tennessee and Pennsylvania. Stakeholders must monitor evolving NATO standardization agreements for sole specification interoperability, as allied joint procurement frameworks progressively reshape contract eligibility and testing protocols.
Market Dynamics
Berry Amendment compliance requirements are restructuring US defense procurement, redirecting contract volumes toward domestic tanneries in Tennessee and Pennsylvania while elevating input costs for non-compliant foreign suppliers.
Growth Catalysts
- NATO Standardization Agreements:Allied joint procurement frameworks for sole specification interoperability are consolidating testing protocols and expanding contract eligibility for cross-border suppliers.
- Flame-Resistant Treatment Integration:Special operations units are mandating advanced thermal protection layers, driving premium material substitution in high-specification contracts.
- Poland Forward Deployment:Accelerated replacement cycles among allied forces stationed near eastern borders are compressing boot turnover timelines and sustaining localized manufacturing demand.
Market Restraints
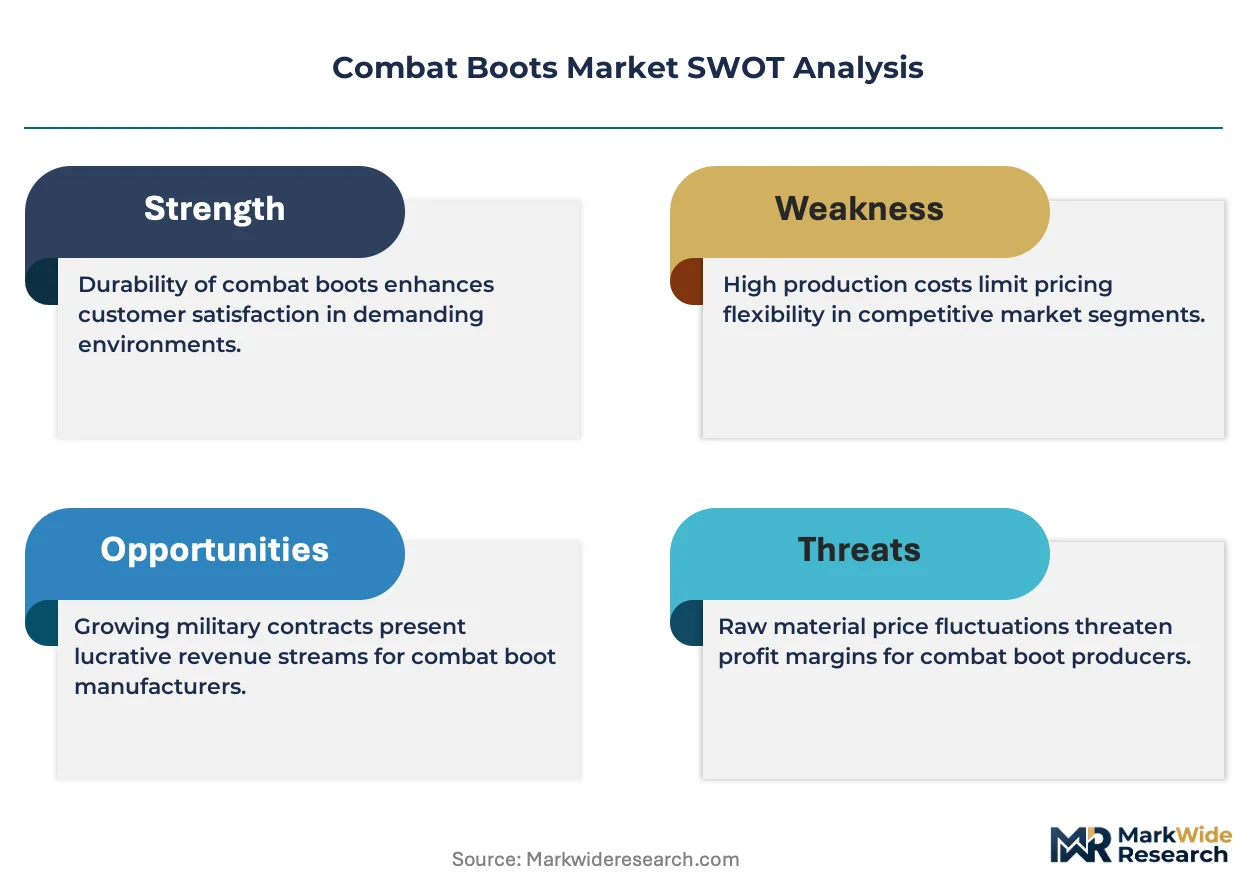
- Full-Grain Leather Price Volatility:European tannery capacity constraints and livestock supply fluctuations are compressing margins for premium-grade manufacturers.
- Berry Amendment Sourcing Rigidity:The Department of Defense's US-origin mandate restricts rubber outsole and synthetic material procurement flexibility, elongating supplier qualification timelines.
- Synthetic Uppers Performance Ceiling:Tropical deployment configurations face abrasion durability trade-offs that limit mold-resistant synthetic blends from penetrating special operations segments.
Strategic Opportunities
- Captive Refurbishment Networks:Aftermarket sole replacement services are consolidating under original manufacturer control, creating recurring revenue streams from institutional buyers.
- Jungle-Terrain Variant Expansion:NATO procurement agencies are expanding orders for specialized tropical configurations, opening white space beyond traditional cold-weather dominance.
- EPA Tanning Effluent Compliance:Stricter domestic environmental standards are advantaging capital-intensive US tanneries with advanced wastewater systems against lower-cost foreign competitors.
Industry Challenges
- Stitch-Down Skilled Labor Scarcity:Cemented construction dominance in commercial footwear has eroded the cobbler workforce capable of military-grade welted boot assembly.
- Gore-Tex Membrane Integration Complexity:Waterproof-breathable liner certification timelines extend product development cycles, delaying Pentagon contract eligibility for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combat Boots Market |
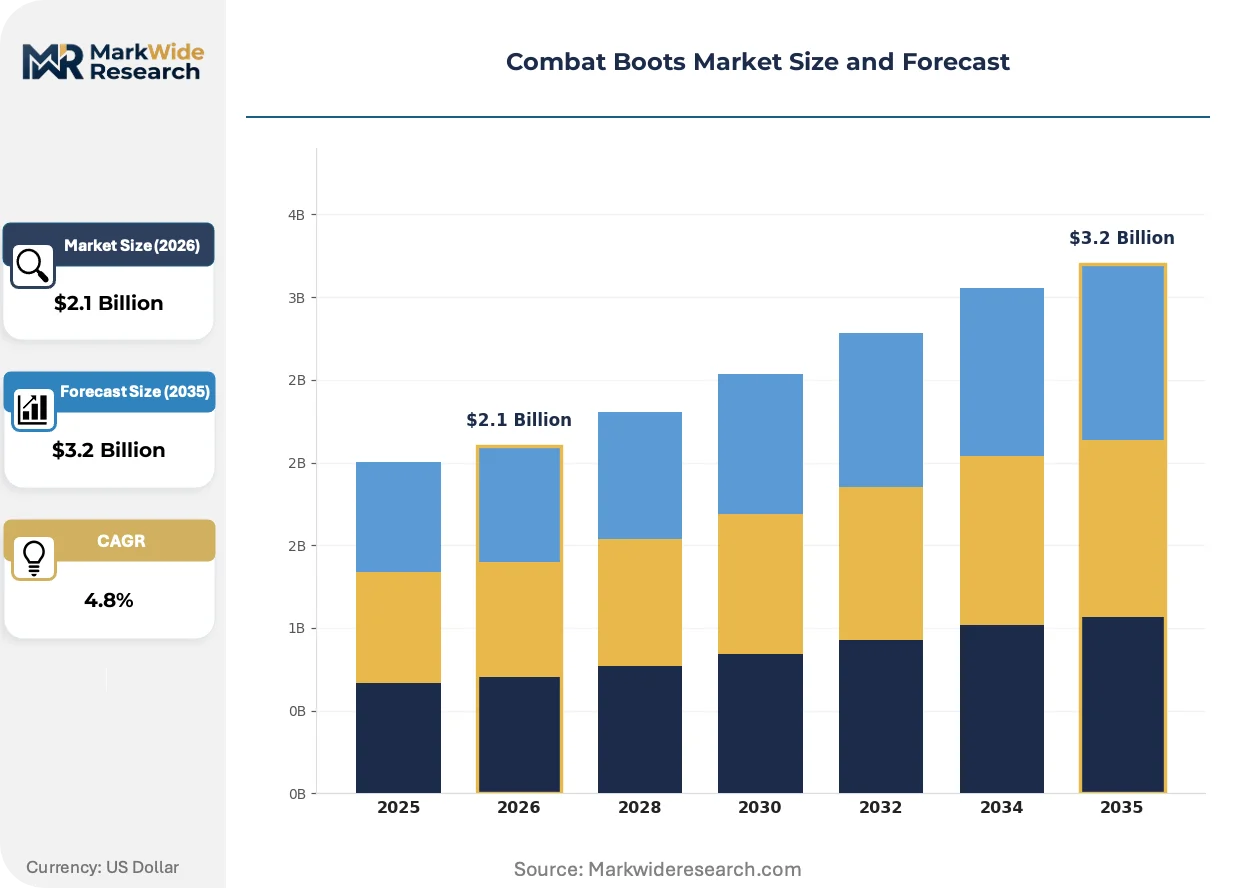
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tactical, Military, Outdoor, Fashion Material: Leather, Nylon, Canvas, Synthetic Use Case: Military Operations, Law Enforcement, Adventure Sports, Daily Wear Closure Type: Lace-Up, Zipper, Slip-On, Velcro |
| Companies Covered | Belleville Boot Company, Danner, Rocky Brands, HAIX, Bates Footwear, Wolverine World Wide, GARMONT, Magnum Boots, Under Armour, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combat Boots Market Strategic Shifts
Material science advances and procurement digitization are compressing product development timelines while elevating performance benchmarks across military and law enforcement segments.
Polyurethane midsole compounds are migrating from ethylene-vinyl acetate in tactical boot construction due to superior compression set resistance under prolonged load-bearing conditions. Law enforcement agencies are adopting these chassis at accelerated rates to reduce lower-extremity injury claims. This material transition is compressing price differentiation between mid-tier and premium product lines as performance thresholds converge.
REACH chemical restriction amendments are compelling European manufacturers to reformulate adhesives and waterproofing treatments ahead of sunset dates for legacy substances. The European Chemicals Agency's expanded substance of very high concern list is forcing retesting of existing product lines. German and Polish suppliers are responding fastest, leveraging proximity to certification laboratories to maintain NATO contract eligibility.
Institutional buyers are consolidating vendor relationships through multi-year framework agreements that bundle original equipment with refurbishment services. This purchasing pattern is displacing transactional spot-buying in federal and state-level procurement channels. The shift is most visible in US Pentagon sourcing, where recrafting program inclusion now weighs heavily in contract award criteria.
Combat Boots Market Segmentation
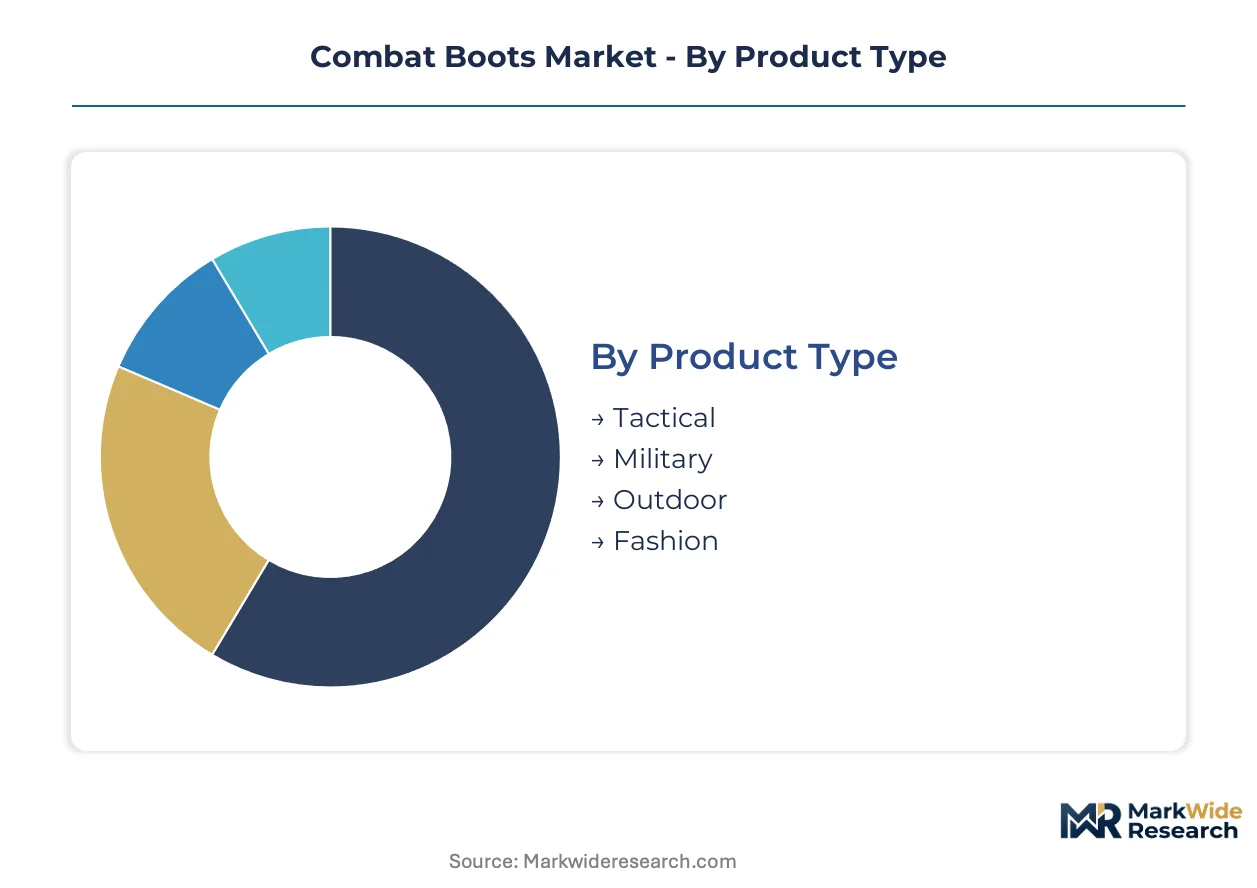
Segmentation in combat boots reveals how procurement priorities diverge across institutional buyers versus commercial consumers. Material specifications and closure mechanisms directly determine contract eligibility for defense applications while shaping margin structures for civilian distribution.
Product Type:
Application context defines performance requirements and pricing tiers across institutional and civilian procurement channels.
- Tactical:Lightweight chassis construction prioritizes mobility over ballistic protection for law enforcement patrol units. Agencies in Poland and Germany are consolidating vendor relationships through multi-year framework agreements that bundle original equipment with refurbishment services.
- Military:Integrated gore-tex membranes and flame-resistant treatments command the highest per-unit pricing in special operations contracts. NATO standardization agreements for sole specification interoperability are consolidating testing protocols and expanding contract eligibility for cross-border suppliers serving this segment.
- Outdoor:Hybrid construction blends durability features with weight reduction for recreational load-bearing activities.
- Fashion:Aesthetic styling overrides technical specifications in civilian retail channels with minimal institutional overlap.
Military commands the established base. The steepest expansion runs through Tactical.
Material:
Raw material selection governs Berry Amendment compliance eligibility and environmental certification pathways for defense contractors.
- Leather:Full-grain grades from Tennessee and Pennsylvania tanneries anchor Berry Amendment-compliant supply chains for Pentagon contracts. European tannery capacity constraints and livestock supply fluctuations are compressing margins for premium-grade manufacturers dependent on imported hides.
- Nylon:Mold-resistant synthetic blends gain share in tropical deployment configurations where moisture management outweighs abrasion durability requirements. REACH chemical restriction amendments are compelling European manufacturers to reformulate waterproofing treatments ahead of sunset dates.
- Canvas:Breathable woven construction serves hot-climate training rotations with reduced thermal retention.
- Synthetic:Engineered polymers enable flame-resistant treatment integration mandated by special operations procurement specifications.
Leather commands the established base. The steepest expansion runs through Synthetic.
Use Case:
Customer type determines volume concentration and replacement cycle frequency across institutional and civilian demand pools.
- Military Operations:Prolonged load-bearing activity across variable terrain requires reinforced toe caps and puncture-resistant soles bonded through stitch-down methods. Forward-deployed allied forces in Poland have accelerated localized boot replacement cycles, compressing turnover timelines.
- Law Enforcement:Polyurethane midsole compounds are displacing ethylene-vinyl acetate to reduce lower-extremity injury claims. US agencies are adopting these chassis at accelerated rates as workers compensation costs drive specification upgrades.
- Adventure Sports:Technical performance requirements overlap with military specifications at reduced durability thresholds.
- Daily Wear:Comfort prioritization and aesthetic preferences dominate purchasing decisions with minimal technical specification compliance.
Military Operations commands the established base. Law Enforcement shows the steepest expansion trajectory.
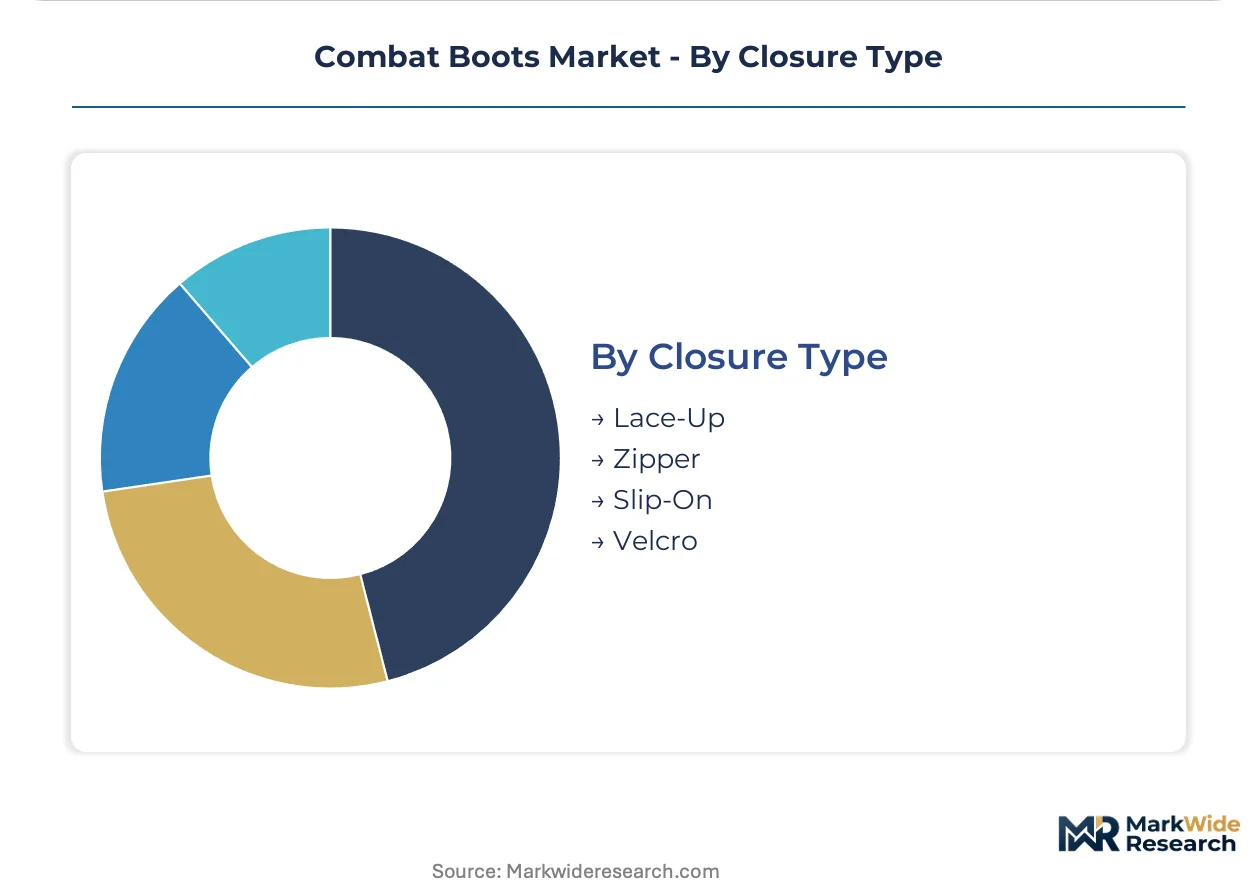
Closure Type:
Mechanism selection reflects the tension between field adjustability and rapid donning requirements across deployment scenarios.
- Lace-Up:Traditional eyelet construction permits customized tension distribution across the instep for extended patrol durations. Cemented construction dominance in commercial footwear has eroded the cobbler workforce capable of military-grade welted boot assembly supporting this closure type.
- Zipper:Speed-focused entry systems serve medical evacuation and rapid response units requiring sub-30-second donning capability.
- Slip-On:Elasticized goring accommodates quick transitions between operational and recovery phases in forward operating bases.
- Velcro:Hook-and-loop fasteners enable adjustment while wearing tactical gloves in cold-weather configurations.
Lace-Up commands the established base. Zipper gains share fastest among specialized response units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic tannery clusters in Tennessee and Pennsylvania anchor Berry Amendment-compliant supply chains for Pentagon contracts, while forward-deployed allied forces in Poland compress replacement cycles. German and Polish manufacturers leverage proximity to NATO certification laboratories to maintain contract eligibility.
United States
Pentagon procurement volumes concentrate among Berry Amendment-compliant domestic tanneries and rubber outsole manufacturers. The Department of Defense administers sourcing restrictions through the Berry Amendment, mandating US-origin materials for military end-use. Tennessee and Pennsylvania employment clusters in leather processing anchor federal contract eligibility for specialized boot fabricators.
Germany
Vertically integrated production models spanning German tanneries to Eastern European stitching facilities insulate margin pools from raw material volatility. ECHA REACH chemical restriction amendments compel reformulation of adhesives and waterproofing treatments ahead of sunset dates. Industrial concentrations in Bavaria maintain proximity to NATO standardization testing protocols.
Poland
Forward-deployed allied forces near eastern borders accelerate localized boot replacement cycles and sustain manufacturing demand. NATO joint procurement frameworks for sole specification interoperability consolidate testing protocols and expand cross-border supplier eligibility. Manufacturing clusters in Warsaw and Krakow regions serve compressed turnover timelines for cold-weather and jungle-terrain variants.
United Kingdom
Special operations procurement specifications drive premium material substitution for integrated gore-tex membranes and flame-resistant treatments. UK defense sourcing aligns with evolving NATO standardization agreements for interoperability compliance. Industrial capacity in the Midlands and Northwest England concentrates on high-specification contract manufacturing.
France
Law enforcement agencies prioritize lightweight chassis construction with polyurethane midsole compounds to reduce lower-extremity injury claims. ANSM and CNIL oversight intersects with EU chemical emissions frameworks for footwear. Lyon and Paris Basin manufacturing clusters serve domestic security forces and export markets across francophone Africa.
Combat Boots Market Competitive Environment
Specialist defense contractors and diversified footwear conglomerates split the market between mission-specific engineering and scale-driven cost efficiency. Three archetypes dominate: vertically integrated European specialists with captive tannery-to-assembly control, US-based Berry Amendment-compliant domestic producers, and diversified outdoor brands with tactical line extensions. Consolidation pressure intensifies through multi-year framework agreements bundling original equipment with refurbishment services, while capacity expansion concentrates in Poland and Germany to serve NATO procurement.
Among US-based defense specialists, Belleville Boot Company and Rocky Brands occupy positions anchored in Berry Amendment-compliant supply chains. Danner exemplifies the captive refurbishment network archetype through institutional recrafting programs. HAIX represents the vertically integrated European model with production control spanning raw material processing to finished assembly.
| Leading Market Players |
|---|
| Belleville Boot Company |
| Danner |
| Rocky Brands |
| HAIX |
| Bates Footwear |
| Wolverine World Wide |
| GARMONT |
| Magnum Boots |
| Under Armour |
| Others |
Value Chain & Pricing Dynamics
Undercapacity at European tanneries is compressing full-grain leather availability while simultaneously elevating input costs for premium-grade manufacturers. This utilization squeeze redirects Pentagon procurement toward Tennessee and Pennsylvania employment clusters, where domestic capacity expansion supports Berry Amendment compliance premiums.
Pricing Analysis
The Berry Amendment dictates the pricing tier structure across defense procurement channels, separating Berry-compliant domestic supply from non-compliant import alternatives. Three-tier pricing stratifies across special operations configurations, standard military issue, and law enforcement tactical lines. Price differentiation rests on certification grade and volume scale, with flame-resistant treatment integration commanding substantial premiums. Cost compression in mid-tier tactical segments is intensifying because polyurethane midsole standardization erodes former performance gaps. Law enforcement agencies exhibit highest price sensitivity due to municipal budget constraints, while special operations units demonstrate lowest sensitivity given mission-critical specifications.
Supply Chain Analysis
Export-control regimes limiting dual-use textile technologies constrain synthetic upper material flows from select Asian manufacturing centers. Geographic supply concentration centers on Germany, Poland, and the United States for finished assembly, with raw material processing anchored in Tennessee, Pennsylvania, and Bavarian tannery clusters. Raw material dependencies draw from full-grain cattle hides, rubber outsole compounds, and Gore-Tex membrane laminates. Single-source vulnerability around European tannery capacity represents the dominant structural risk. Distribution runs through institutional procurement frameworks and multi-year Pentagon contracts rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-year framework agreements bundling original equipment with refurbishment services, consolidating vendor relationships among NATO procurement agencies and US federal buyers.
For Market Incumbents: Build captive refurbishment network moats to lock in institutional recurring revenue and extend product lifecycles. Deepen backward integration into domestic tannery capacity to secure Berry Amendment compliance against emerging synthetic competitors. Anchor Pentagon contract eligibility through Tennessee and Pennsylvania supply chain certification. For New Entrants and Emerging Players: Establish a beachhead in law enforcement polyurethane midsole segments where performance standardization reduces incumbent brand advantages. Target jungle-terrain variant white space beyond traditional cold-weather dominance. Pursue NATO standardization agreement certification as the primary go-to-market pathway. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated specialists with captive refurbishment programs and institutional contract visibility. Long-term viability favors archetypes controlling upstream tannery assets alongside downstream service networks. Monitor EPA tanning effluent enforcement intensity as the signal indicating margin pressure inflection for capital-intensive domestic competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Refurbishment Network Expansion | Institutional recrafting programs extend lifecycle revenue from Pentagon and NATO buyers. |
| Backward Integration into Domestic Tanneries | Tennessee and Pennsylvania leather processing secures Berry Amendment contract eligibility. |
| Flame-Resistant Treatment Certification | Special operations procurement specifications mandate advanced thermal protection layers. |
| Jungle-Terrain Variant Development | NATO procurement agencies are expanding tropical configuration orders beyond cold-weather focus. |
| Multi-Year Framework Agreement Pursuit | Bundled equipment and service contracts displace transactional spot-buying in federal channels. |
Study Parameters
Cross-validation between procurement officer interviews and customs trade data anchors the qualitative findings in verifiable contract flow patterns. Primary fieldwork engaged defense procurement specialists, tannery operations managers, footwear manufacturing engineers, and institutional supply chain directors. Secondary validation drew from Pentagon contract award databases, EPA tanning effluent compliance records, NATO standardization agreement documentation, and Berry Amendment certification registries. Bottom-up vendor capacity assessments triangulate against top-down procurement volume estimates.
Calibration against historical replacement cycle data and forward-deployment inventory patterns informs the projection framework. Segmentation modeling spans product type, material grade, use case, and closure mechanism dimensions across the analysis window. CAGRs derive from installed base turnover rates, procurement budget trajectories, and segment-specific pricing elasticity. Forecast inputs incorporate NATO force posture adjustments and EPA environmental enforcement intensity projections.
Stress conditions across tannery capacity utilization, livestock supply fluctuations, and Berry Amendment interpretation strictness were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding allied force deployment levels and domestic sourcing mandate continuity. Material shifts in NATO collective defense spending commitments or EPA tanning wastewater regulation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Waterproof Boots Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Military Boots Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Europe Lanyards Market
Protective Gear
Heated Goggles Market
Protective Gear
China Pollution Mask Market
Protective Gear
Flavored Condoms Market
Protective Gear
Work Shoes Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Earplugs Market
Protective Gear
Waterproof Cases Market
Protective Gear
Bungee Cords and Accessories Market
Protective Gear
Tactical Boots Market