
 Work Boots Market | 2026-2036
Work Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Work Boots Market Analytics
Modular boot systems with interchangeable insoles, outsoles, and insulation liners is shifting how industrial buyers evaluate total cost of ownership. Wolverine World Wide leverages vertically integrated tanning and domestic manufacturing to sustain margin control across mid-tier and premium lines. Timberland PRO anchors its position through direct-to-contractor channel programs that bypass traditional retail markups. Red Wing Shoe Company differentiates via company-owned retail and mobile fitting services that lock in enterprise accounts.
Work boots are protective footwear engineered with reinforced toe caps, oil-resistant outsoles, and puncture-resistant midsoles designed to shield wearers from impact, compression, and electrical hazards in hazardous occupational environments. ASTM F2413 specifies minimum performance criteria for impact resistance, compression, and conductive properties that manufacturers must certify through third-party testing. Steel toe configurations retain the largest volume share among product type segments due to entrenched specification in construction and heavy manufacturing contracts, while composite toe variants gain ground in logistics and cold-storage facilities where metal detectors and thermal insulation matter. Leather dominates the material segment for durability and break-in conformity, though synthetic uppers expand in agriculture and food processing where washdown protocols accelerate replacement cycles.
OSHA 29 CFR 1910.136 mandates protective footwear in workplaces with foot injury hazards, while ASTM International publishes the F2413 standard referenced by procurement officers across construction and manufacturing. The EU PPE Regulation 2016/425 governs market access for imported safety footwear in Europe, requiring CE marking and notified body certification. Stakeholders must monitor evolving state-level heat stress regulations in the US Sun Belt, as breathable waterproof membranes and phase-change lining technologies become specification-critical for outdoor crews.
Market Dynamics
Composite-toe technology is converging with waterproof membrane systems to redefine specification criteria across construction and logistics procurement, compressing replacement cycles and elevating performance benchmarks for incumbent steel-toe suppliers.
Growth Catalysts
- Federal Infrastructure Spending:United States appropriations for bridge, highway, and utility projects sustain bulk procurement of ASTM F2413-certified footwear for site crews.
- OSHA 29 CFR 1910.136:Mandated protective footwear in workplaces with foot injury hazards drives consistent replacement demand across manufacturing and warehousing operations.
- Phase-Change Lining Technologies:Thermal regulation materials address heat stress protocols emerging in US Sun Belt states, opening specification opportunities for breathable waterproof variants.
Market Restraints
- Chrome-Tanned Leather Volatility:Tannery capacity concentration in specific geographies exposes mid-tier manufacturers to raw material cost swings and supply disruption.
- CE Marking Complexity:EU PPE Regulation 2016/425 requires notified body certification that extends lead times for non-European exporters seeking European market access.
- Synthetic Upper Durability Gap:Washdown-compatible materials in food processing applications sacrifice break-in conformity and long-term shape retention versus leather alternatives.
Strategic Opportunities
- Modular Boot Architecture:Interchangeable insoles, outsoles, and insulation liners enable total cost of ownership calculations that displace single-use procurement models.
- Mobile Fitting Services:On-site sizing and customization programs lock in enterprise accounts through reduced downtime and improved fit accuracy.
- State Heat Stress Mandates:Emerging breathable waterproof specifications in Texas, Arizona, and Florida create first-mover advantage for membrane technology suppliers.
Industry Challenges
- ASTM F2413 Third-Party Testing Bottlenecks:Certification backlogs at accredited laboratories delay product launches and compress selling seasons.
- Skilled Pattern-Maker Scarcity:Domestic boot last design and orthopedic modification expertise concentrates with aging craftspeople, constraining customization scale.
- Direct-to-Contractor Channel Buildout:Bypassing traditional retail requires substantial field sales investment and inventory positioning without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Work Boots Market |
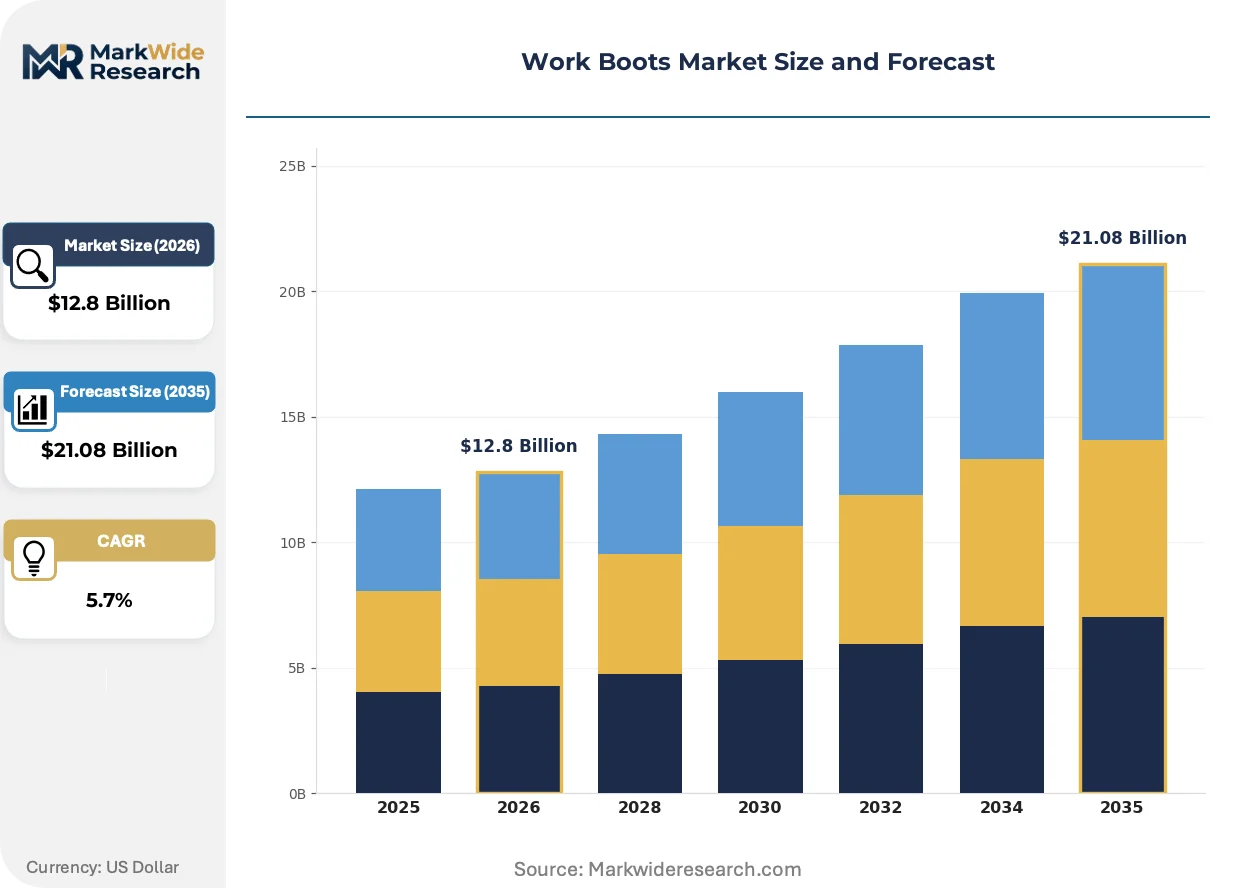
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Toe, Composite Toe, Soft Toe, Waterproof End User: Construction, Manufacturing, Logistics, Agriculture Material: Leather, Synthetic, Rubber, Nubuck Feature: Slip Resistant, Electrical Hazard, Insulated, Puncture Resistant |
| Companies Covered | Wolverine World Wide, Timberland PRO, Red Wing Shoe Company, Caterpillar, KEEN Utility, Dr. Martens, Rocky Boots, Ariat International, Thorogood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Work Boots Market Evolving Landscape
Protective footwear specification is pivoting from compliance checkboxes toward performance-based total cost metrics, rewarding suppliers who integrate modularity, thermal management, and channel efficiency into unified offerings.
Carbon fiber toe caps are converging with non-metallic puncture-resistant plates to deliver ASTM F2413 impact protection at reduced weight, enabling cold-storage operators and airport logistics contractors to meet metal-detector protocols without sacrificing safety ratings. Cold-chain facilities in Minnesota and Wisconsin have accelerated adoption, compressing the traditional steel-toe replacement cycle from eighteen months to ten months as thermal conductivity advantages become measurable in worker comfort metrics.
OSHA's emphasis on heat illness prevention is reshaping specification language in outdoor construction contracts, with breathable waterproof membranes now appearing as mandatory line items in municipal procurement documents across southern states. General contractors in Texas and Florida are requiring phase-change lining technologies in summer work boot specifications, forcing suppliers to recertify existing product lines or risk exclusion from bidding pools.
Enterprise buyers are consolidating vendor relationships around suppliers offering mobile fitting vans and on-site customization, displacing traditional retail purchasing for crews above fifty workers. Construction firms in the Dakotas and oilfield services operators in Oklahoma have pioneered this model, using fit-accuracy guarantees and reduced downtime to justify sole-source agreements that bypass distributor markups entirely.
Work Boots Market Segmentation
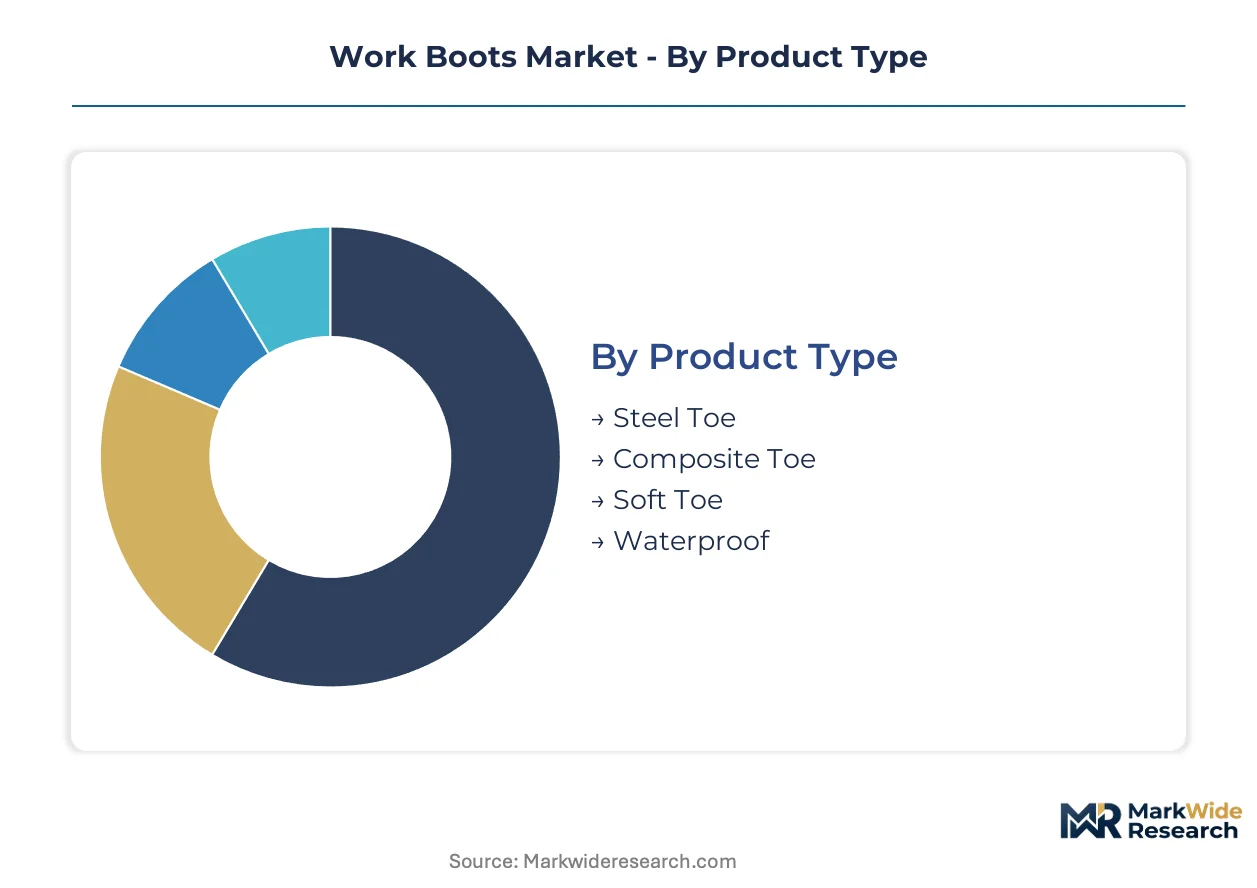
Work boot procurement diverges sharply across occupational hazards, with construction crews prioritizing impact protection while logistics operators weigh metal-detector compatibility. Specification language in enterprise contracts now ties reimbursement to certified performance tiers rather than material categories alone.
Product Type:
Buyer differentiation hinges on hazard exposure severity and workplace security protocols rather than cost sensitivity alone.
- Steel Toe:Reinforced steel caps deliver maximum impact resistance under ASTM F2413 compression standards. Construction firms in Texas and heavy manufacturing plants across Ohio specify steel toe as baseline PPE, though weight penalties and thermal conductivity limit cold-storage adoption.
- Composite Toe:Non-metallic toe caps using carbon fiber or Kevlar achieve equivalent safety ratings without triggering metal detectors. Airport logistics contractors in Atlanta and cold-chain operators in Minnesota have accelerated procurement, compressing replacement cycles as thermal comfort metrics improve.
- Soft Toe:Unreinforced designs serve warehouse supervisors and light assembly roles where impact hazards are minimal. Distribution centers in Pennsylvania favor soft toe for administrative staff requiring facility access without full protective specifications.
- Waterproof:Membrane-lined constructions with sealed seams protect against prolonged moisture exposure. Utility crews in Florida and agricultural workers in Iowa specify waterproof variants as mandatory for outdoor rotation schedules.
Volume sits with Steel Toe; growth tilts toward Composite Toe.
End User:
Procurement scale and replacement frequency separate enterprise accounts from fragmented small-business demand.
- Construction:Federal infrastructure contractors mandate ASTM F2413 certification across all site personnel, with bridge and highway projects in California sustaining bulk orders. General contractors now require mobile fitting services for crews exceeding fifty workers.
- Manufacturing:Heavy industrial plants specify puncture-resistant midsoles alongside toe protection. Automotive assembly lines in Michigan and metal fabrication facilities in Indiana drive consistent replacement demand through OSHA compliance audits.
- Logistics:E-commerce fulfillment centers prioritize lightweight designs for walking-intensive picking roles. Distribution hubs in Illinois and cross-dock facilities in Georgia specify composite toe to accommodate security screening protocols.
- Agriculture:Seasonal labor patterns create spiky demand aligned with planting and harvest cycles. Large-scale operations in Nebraska and dairy farms in Wisconsin require chemical-resistant outsoles and washdown-compatible uppers.
Construction commands procurement volume; logistics exhibits the steepest expansion trajectory as e-commerce fulfillment scales.
Material:
Total cost of ownership calculations now incorporate break-in time, washdown compatibility, and replacement cadence rather than upfront unit cost.
- Leather:Full-grain and split leather uppers dominate durability specifications, with chrome-tanned variants from domestic tanneries preferred for break-in conformity. Oilfield services in Oklahoma and electrical contractors in North Carolina specify leather for shape retention across extended wear cycles.
- Synthetic:Polyurethane and microfiber constructions enable rapid drying and chemical resistance. Food processing plants in Wisconsin and agricultural washdown operations in California accept shorter service life in exchange for sanitation compliance.
- Rubber:Injection-molded uppers and outsoles deliver complete liquid protection for wading applications. Utility workers in Louisiana and seafood processors in Alaska specify rubber for submerged or saturated environments.
- Nubuck:Sanded leather surfaces offer abrasion resistance with softer hand feel than full-grain alternatives. Landscaping crews in Florida and grounds maintenance operations in Arizona specify nubuck for comfort during kneeling and crouching tasks.
Leather retains volume leadership; synthetic materials are gaining share fastest in regulated processing environments.
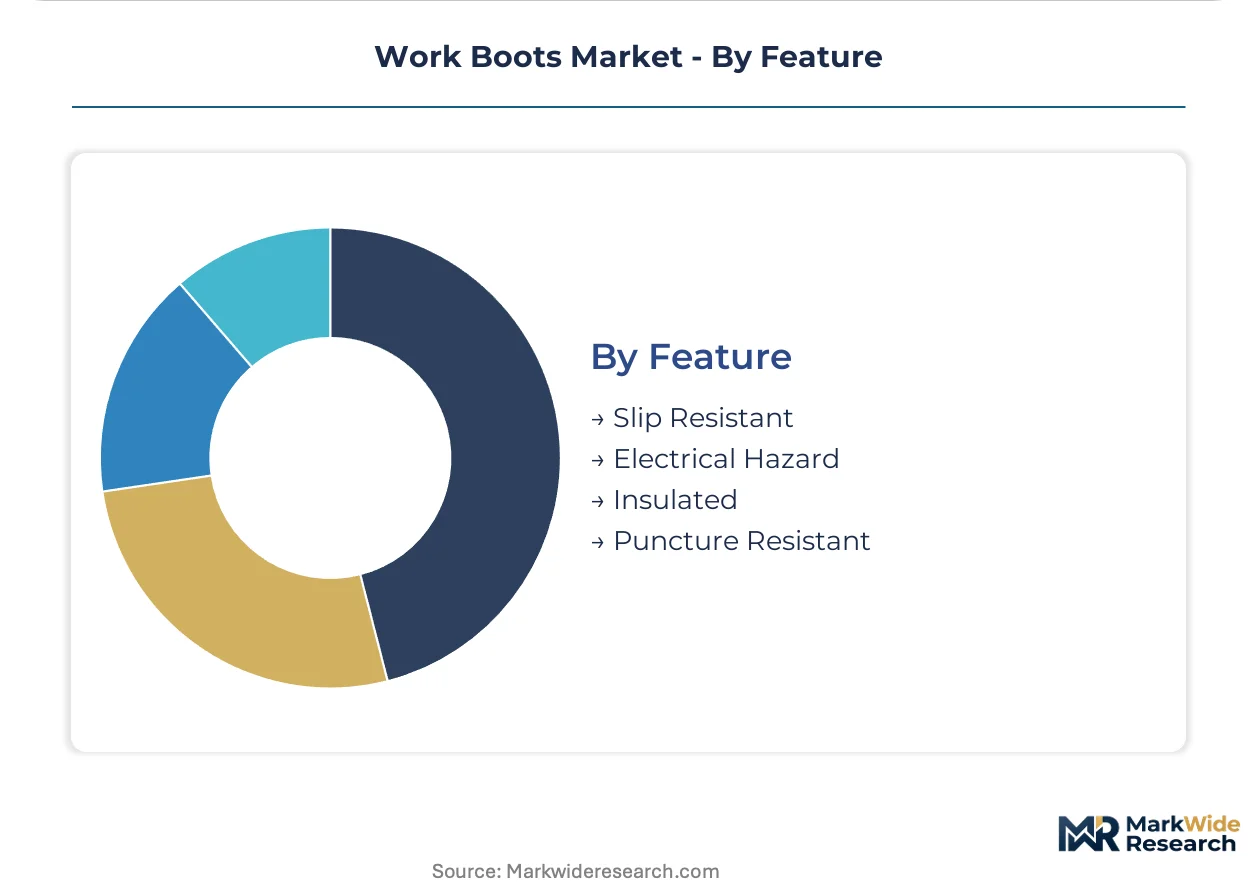
Feature:
Specification mandates increasingly bundle multiple protective characteristics rather than treating safety features as à la carte options.
- Slip Resistant:Oil- and chemical-resistant outsole compounds with specialized tread patterns reduce fall incidents on contaminated surfaces. Refinery contractors in Texas and commercial kitchen suppliers in New York require ASTM F2913-tested slip resistance ratings.
- Electrical Hazard:Non-conductive soles and heels provide secondary protection against accidental contact with energized circuits. Lineworkers in Georgia and manufacturing electricians in Ohio specify EH-rated footwear as condition of site access.
- Insulated:Thinsulate and proprietary thermal linings maintain foot temperature in sub-zero exposure. Cold-storage operators in Minnesota and outdoor construction crews in North Dakota specify insulated variants for winter rotation schedules.
- Puncture Resistant:Steel or composite plates embedded in midsoles prevent nail and debris penetration. Roofing contractors in Florida and demolition crews in Illinois mandate puncture resistance for debris-strewn work zones.
Slip Resistant features dominate specification frequency; Electrical Hazard ratings are climbing fastest as electrical safety enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones across the United States concentrate work boot demand through duty-deferred procurement for infrastructure and energy projects. Manufacturing clusters in Germany and China supply component materials, while domestic assembly operations in Mexico serve North American distribution networks.
United States
Federal infrastructure appropriations for bridge and highway construction sustain bulk procurement of ASTM F2413-certified protective footwear. OSHA 29 CFR 1910.136 mandates drive consistent replacement cycles across manufacturing and warehousing operations. Oilfield services clusters in Oklahoma and Texas specify leather-composite hybrid designs for extended wear in hazardous extraction environments.
Germany
Industrial machinery exports and automotive assembly operations generate steady demand for puncture-resistant and electrical hazard-rated footwear. EU PPE Regulation 2016/425 requires CE marking and notified body certification for all safety footwear market access. Manufacturing concentrations in Bavaria and Baden-Württemberg source premium leather uppers from domestic tanneries serving Mittelstand industrial clients.
China
Construction sector expansion and logistics infrastructure buildout drive volume procurement of steel-toe and composite-toe variants. GB standards administered by SAMR establish domestic safety footwear certification requirements. Manufacturing clusters in Guangdong and Zhejiang provinces supply synthetic upper materials and rubber outsole compounds for export-oriented production.
Canada
Natural resource extraction and cold-weather construction sustain demand for insulated and waterproof protective footwear variants. Health Canada and provincial occupational health regulators enforce CSA Z195 standards for protective footwear in hazardous workplaces. Energy sector operations in Alberta and mining activities in Ontario drive seasonal procurement cycles for thermal-rated boot systems.
United Kingdom
Utilities infrastructure maintenance and commercial construction sustain procurement of slip-resistant and electrical hazard-rated footwear. HSE regulations and EN ISO 20345 standards govern workplace footwear specifications across industrial sectors. London and Southeast England construction clusters specify lightweight composite-toe designs for urban logistics and facility maintenance roles.
Work Boots Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans vertically integrated domestic manufacturers, brand licensors leveraging contract production, and regional specialists serving niche occupational segments. Three archetypes dominate: heritage craft-based producers emphasizing fit customization, scale-driven manufacturers optimizing unit economics through automation, and brand licensors capturing retail and direct-to-contractor channels. Competitive moves concentrate on direct channel buildout bypassing distributor markups and modular product architectures enabling component replacement.
Among heritage-focused domestic manufacturers, Red Wing Shoe Company and Thorogood exemplify craft-based positioning through company-owned retail and mobile fitting services. Wolverine World Wide anchors the diversified portfolio archetype with vertically integrated tanning operations and multi-brand distribution. Timberland PRO occupies the direct-channel specialist tier, leveraging contractor-facing programs that displace traditional retail procurement for enterprise accounts.
| Leading Market Players |
|---|
| Wolverine World Wide |
| Timberland PRO |
| Red Wing Shoe Company |
| Caterpillar |
| KEEN Utility |
| Dr. Martens |
| Rocky Boots |
| Ariat International |
| Thorogood |
| Others |
Value Network & Pricing Analysis
ASTM F2413 certification tiers create a sharp bifurcation between premium certified suppliers and uncertified commodity producers, with this performance ladder simultaneously dictating pricing premiums of thirty to fifty percent and concentrating supply relationships around third-party testing laboratories in the United States and notified bodies in Germany. Procurement officers at federal infrastructure contractors now mandate certified performance documentation as a condition of payment authorization, effectively walling off uncertified Asian manufacturers from enterprise accounts regardless of unit cost advantages.
Pricing Analysis
Expedited certification timelines command measurable premiums in the current procurement environment, with general contractors in Texas and Florida paying elevated rates for ASTM F2413-compliant stock delivered within compressed windows versus standard lead-time inventory. Three-tier pricing structure across premium, standard, and economy levels separates mobile-fitting-enabled suppliers from distributor-dependent brands from direct-import alternatives. Cost compression in the economy tier is intensifying because tannery capacity constraints in specific geographies limit raw material arbitrage opportunities. Small agricultural operations and independent contractors exhibit the highest price sensitivity, while oilfield services operators and federal infrastructure prime contractors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with chrome-tanned leather processors concentrated in the United States and Italy, where environmental compliance costs have shuttered alternative tanneries across Eastern Europe and Latin America. Manufacturing draws from domestic assembly operations in Mexico, component suppliers in China, and specialized membrane technology providers in Germany and Japan. Tariff exposure on finished footwear imports from Asia threatens margin structures for brand licensors dependent on contract manufacturing. Distribution runs through direct-to-contractor field sales teams, industrial distributors serving small-business accounts, and company-owned retail networks for fit-customization services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ASTM F2413 third-party testing requirements create substantial barrier-to-entry moats for certified domestic and European manufacturers, effectively capturing enterprise procurement volumes against uncertified import competition.
For Market Incumbents: Hedge against synthetic upper substitution by securing captive tanning capacity or long-term leather supply agreements with domestic processors, while simultaneously building mobile fitting infrastructure to lock in oilfield services accounts threatened by direct-channel specialists. Certification backlogs at accredited laboratories represent a named threat to product launch cadence, demanding pre-positioned inventory investments as a defensive lever.
For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the most penetrable route for bypassing established distributor relationships, targeting mid-sized construction firms in the Dakotas and agricultural cooperatives in Nebraska with fit-accuracy guarantees and rapid replacement fulfillment. Food processing applications in Wisconsin present an underserved white-space segment where washdown-compatible synthetic constructions can displace leather alternatives despite shorter service life.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated domestic manufacturers given federal infrastructure spending sustainability and OSHA enforcement tightening. Long-term viability across the five-to-ten year window favors archetypes combining in-house tanning, domestic assembly, and direct channel control. The signal to watch is state-level heat stress mandate adoption velocity in Texas, Arizona, and Florida as an inflection indicator for breathable waterproof membrane demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Fitting Service Expansion | On-site sizing programs lock in enterprise accounts through reduced downtime guarantees. |
| Backward Integration into Tanning | Captive leather supply insulates margin structures from chrome-tanned volatility. |
| Composite-Toe Product Line Extension | Non-metallic variants capture cold-storage and airport logistics procurement shifts. |
| Direct-to-Contractor Channel Buildout | Bypassing distributor markups improves price competitiveness for bulk orders. |
| Phase-Change Lining Technology Investment | Thermal regulation capabilities address emerging Sun Belt heat stress mandates. |
Research Methodology
Document review covered customs and trade databases, SEC filings from diversified footwear manufacturers, and OSHA enforcement records, complemented by interviews with safety directors at construction firms, procurement leads at oilfield services operators, plant managers at domestic tanneries, and regulatory affairs specialists at notified bodies. Secondary validation drew from ASTM International certification registries, EU PPE Regulation compliance databases, and federal infrastructure procurement documents. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Cross-referencing historical shipment data against expert panel inputs established baseline volume estimates across the projection horizon. Segmentation dimensions modeled include toe protection type, end-use industry, material category, and regional regulatory cluster. CAGRs were derived through trend extrapolation adjusted for policy intervention effects. Industry-specific forecast inputs incorporated federal infrastructure appropriation schedules and state-level heat stress regulatory development timelines.
The model holds under stable OSHA enforcement intensity and continued federal infrastructure spending; deviation in tariff policy or tannery capacity closures would shift volume and value trajectories. Forecasts reflect documented assumptions regarding replacement cycle compression and specification migration toward composite materials. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Mobile Handset Protection Market
Protective Gear
Heated Goggles Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Insect Repellent Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Cooking Gloves Market
Protective Gear
Waterproof Cases Market
Protective Gear
Tactical Boots Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Pet Control Devices Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Flavored Condoms Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Europe Lanyards Market
Protective Gear
Boxed Glove for Food Market