
 Advanced Protective Gear and Armor Market | 2026-2036
Advanced Protective Gear and Armor Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Protective Gear and Armor Market Insights
North American specialty materials producers is realigning capacity toward ultra-high-molecular-weight polyethylene fiber output to meet military and federal agency backlogs. DuPont de Nemours, Inc. leverages its Kevlar production heritage to dominate aramid supply chains for soft armor vests. Honeywell International Inc. sustains competitive positioning through backward integration into Spectra fiber manufacturing. MSA Safety Inc. anchors industrial segment share with integrated head and respiratory protection platforms.
Advanced protective gear and armor encompasses engineered personal protection systems designed to attenuate ballistic, stab, blast, and environmental threats through layered composites, ceramics, and synthetic fibers, typically rated against NIJ or STANAG threat levels. These systems serve military, law enforcement, and hazardous industrial occupations where survivability depends on weight-optimized material performance. Body Armor commands the largest value pool as ceramic-polyethylene hybrid plates displace pure steel solutions across military end users. Helmets represents the fastest-growing product category, driven by modular accessory rails and integrated communications mounts. The Material dimension shows polyethylene gaining share against traditional Kevlar in hard armor applications due to superior weight-to-protection ratios at equivalent threat levels.
NIJ certification protocols in the United States, CE marking requirements under the EU PPE Regulation, and STANAG 4569 testing standards collectively dictate product qualification timelines and procurement eligibility across NATO-aligned defense markets. BIS standards in India and GB specifications in China impose additional localization requirements for foreign suppliers seeking domestic law enforcement contracts. Stakeholders must monitor evolving threats from armor-piercing ammunition variants and directed energy weapons, as these will force material science roadmaps and testing protocols to adapt faster than current certification cycles permit.
Market Dynamics
NIJ Standard-0101.06 certification acceleration across United States law enforcement agencies is compressing replacement cycles for legacy ballistic systems while forcing manufacturers to requalify entire product lines under stricter backface deformation thresholds.
Growth Catalysts
- Military Modernization Programs:NATO member states are expanding procurement volumes for next-generation ballistic systems, with polyethylene-ceramic hybrid plates displacing steel solutions across ground forces equipment refresh cycles.
- NIJ Certification Updates:The United States Department of Justice's revised testing protocols mandate enhanced multi-hit capability and edge-shot performance, creating replacement demand across federal and municipal police agencies.
- Ultra-High-Molecular-Weight Polyethylene Fiber:North American specialty materials producers are realigning capacity toward UHMWPE output to address military and federal agency backlogs for lightweight hard armor plates.
Market Restraints
- Ceramic Raw Material Concentration:Boron carbide and silicon carbide precursor supply concentrates among limited specialty chemical producers, exposing armor manufacturers to input cost volatility and allocation constraints.
- Aramid Fiber Supply Control:Kevlar production heritage creates asymmetric supplier power in soft armor vest supply chains, constraining pricing flexibility for downstream integrators.
- Multi-Jurisdictional Certification Burden:STANAG 4569, NIJ 0101.06, and CE marking under EU PPE Regulation impose overlapping test matrices that extend product qualification timelines and raise fixed compliance costs.
Strategic Opportunities
- Modular Helmet Platforms:Integrated communications mounts and accessory rails represent the fastest-growing product category as military end-users prioritize situational awareness over pure ballistic protection.
- India BIS Localization Requirements:Bureau of Indian Standards mandates for domestic law enforcement procurement create protected market access for suppliers establishing local manufacturing or joint ventures.
- Industrial Head-Respiratory Integration:MSA Safety Inc. demonstrates anchor positioning through combined protection platforms, suggesting white space for similar convergence in military and tactical segments.
Industry Challenges
- Armor-Piercing Ammunition Adaptation:Evolving projectile threats from tungsten-core and composite variants are forcing material science roadmaps to accelerate faster than current NIJ and STANAG certification cycles permit.
- Directed Energy Weapon Preparation:Laser and microwave weapon proliferation demands thermal management integration into passive armor systems, requiring cross-functional expertise scarce among traditional ballistic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Protective Gear and Armor Market |
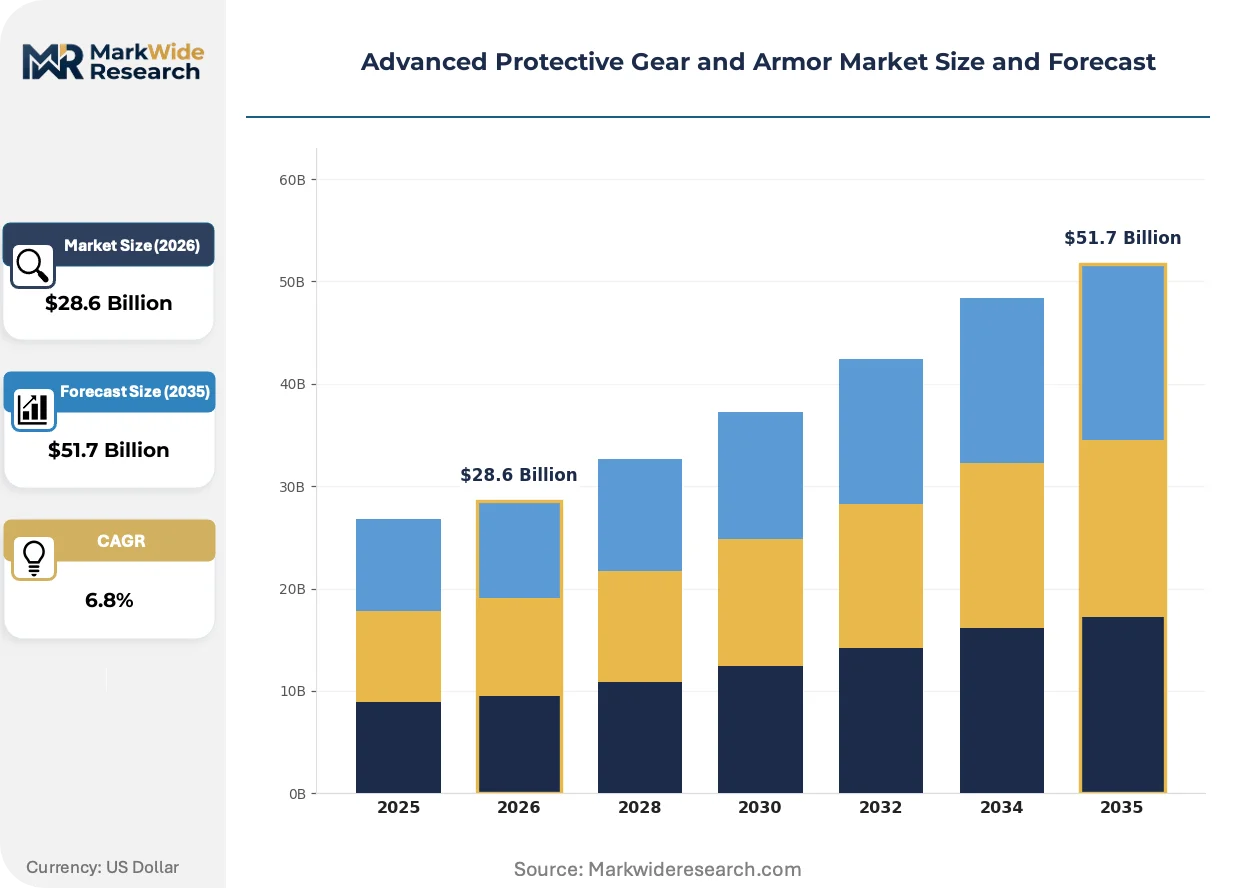
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Armor, Helmets, Shields, Protective Clothing Material: Kevlar, Carbon Fiber, Steel, Polyethylene End User: Military, Law Enforcement, Industrial, Civilian Deployment: On-Premise, Field Use, Tactical Operation, Training |
| Companies Covered | Point Blank Enterprises, Inc., MSA Safety Inc., Honeywell International Inc., Rheinmetall AG, Avon Protection plc, 3M Company, BAE Systems plc, ArmorSource LLC, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Protective Gear and Armor Market Trends and Innovations
Material science convergence with systems engineering is redefining protective equipment from standalone ballistic barriers to integrated survivability platforms, compressing development cycles and raising performance thresholds simultaneously.
Polyethylene-ceramic hybrid plate construction is unifying hard armor design by combining the multi-hit durability of ceramic strike faces with the weight efficiency of UHMWPE backings. United States Special Operations Command and NATO rapid response units are fielding these systems at accelerated procurement tempos. This unification is compressing the addressable market for pure steel plates while elevating minimum performance standards across military tender specifications.
EU PPE Regulation CE marking requirements under MDR classification are tightening conformity assessment procedures for law enforcement body armor sold in European member states. Notified bodies must now evaluate biological compatibility and ergonomic safety alongside ballistic performance, extending technical file preparation timelines. French and German federal police procurement offices are responding by consolidating supplier qualification pools to manufacturers with established EU authorized representative infrastructure.
Buying patterns among United States municipal police departments are compressing vendor selection cycles through federal equipment grant dependency. Department of Justice Byrne JAG program disbursements increasingly restrict eligible vendors to those holding current NIJ compliant product listings, displacing smaller regional suppliers from consideration. California and Texas state procurement consortiums exemplify this concentration most visibly, with multi-agency blanket purchase agreements favoring established federal contractors.
Advanced Protective Gear and Armor Market Segmentation
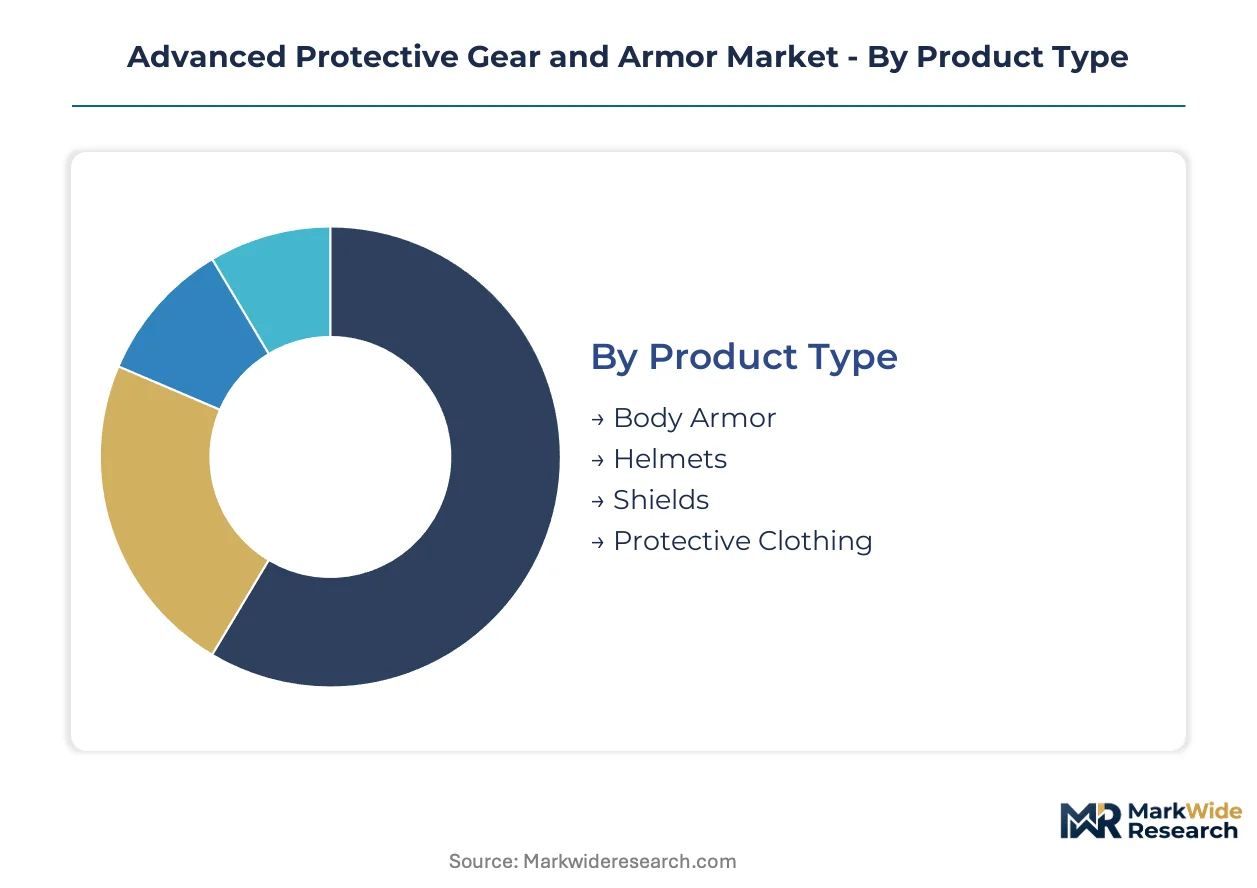
Segmentation in protective gear markets reveals how certification requirements, threat specifications, and procurement channels fragment demand across incompatible technical standards. Each dimension carries distinct margin structures and qualification barriers that determine supplier access.
Product Type:
NIJ 0101.06 governs body armor and shields sold to United States law enforcement, while STANAG 4569 applies to military helmets and tactical systems across NATO procurement channels. CE marking under EU PPE Regulation creates separate conformity pathways for European police and industrial protective clothing.
- Body Armor:Ceramic-polyethylene hybrid plates combine multi-hit durability with weight efficiency, displacing steel solutions across United States Department of Defense ground forces equipment refresh cycles. NIJ certification mandates compress replacement timelines for federal and municipal police agencies.
- Helmets:Modular platforms with integrated communications mounts and accessory rails are gaining procurement priority among NATO rapid response units and United States Special Operations Command. STANAG 4569 testing requirements extend qualification timelines but lock in supplier relationships.
- Shields:Transparent polycarbonate and glass composites rated for specific threat levels serve tactical entry teams and corrections facilities.
- Protective Clothing:Flame-resistant and chemical-protective ensembles address industrial hazard environments outside ballistic threat profiles.
Leading the category by volume: Body Armor. Growing fastest: Helmets.
Material:
Cost tiers separate military-grade polyethylene and ceramic composites from industrial-grade steel and aramid solutions, with price differentials reflecting raw material scarcity and processing complexity.
- Polyethylene:Ultra-high-molecular-weight fiber delivers superior weight-to-protection ratios at equivalent NIJ threat levels, driving capacity realignment among North American specialty materials producers. United States military backlogs sustain above-average adoption rates.
- Kevlar:Aramid fiber heritage dominates soft armor vest supply chains through established production infrastructure, constraining pricing flexibility for downstream integrators. Legacy law enforcement procurement favors familiar qualification histories.
- Carbon Fiber:High stiffness-to-weight properties serve specialized aerospace and vehicle armor applications with limited personal protection penetration.
- Steel:Pure steel plates face market compression as hybrid ceramic-polyethylene systems unify hard armor design across military tender specifications.
Polyethylene leads material demand by military procurement volume. Carbon fiber expands most quickly from aerospace crossover applications.
End User:
Customer type determines funding mechanisms, replacement cycles, and threat specification stringency, with military and law enforcement segments commanding premium pricing against industrial and civilian markets.
- Military:NATO modernization programs and United States Department of Defense spending sustain above-average procurement volumes for next-generation ballistic systems. STANAG 4569 testing standards dictate product eligibility across aligned defense markets.
- Law Enforcement:Federal police equipment grants and NIJ compliance requirements concentrate vendor selection among established contractors. California and Texas state procurement consortiums exemplify multi-agency blanket purchase concentration.
- Industrial:MSA Safety Inc. anchors segment share through integrated head and respiratory protection platforms, demonstrating convergence opportunities.
- Civilian:Unregulated private acquisition channels operate outside certification-mandated procurement systems with variable quality assurance.
Military end users dominate segment value. Law enforcement replacement demand is accelerating fastest.
Deployment:
Application context shapes performance requirements, with field use and tactical operation demanding ruggedized systems against controlled training environments.
- Field Use:Extended wear requirements prioritize weight optimization and moisture management for dismounted infantry and patrol operations.
- Tactical Operation:Rapid donning systems and modular configurability serve entry teams and emergency response units with mission-variable threat profiles.
- On-Premise:Facility-based security and corrections applications accept heavier solutions with reduced mobility requirements.
- Training:Non-ballistic replica systems and reduced-weight alternatives preserve operational equipment lifespan during repetitive drills.
Field Use leads deployment category volume. Tactical Operation is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boron carbide precursor production concentrates in United States specialty chemical corridors, anchoring North American ceramic armor plate supply chains. Ultra-high-molecular-weight polyethylene fiber capacity expansion across the Southeast sustains military backlogs for lightweight hard armor systems.
United States
Department of Defense modernization programs and Byrne JAG federal equipment grants drive procurement volumes for next-generation ballistic systems. NIJ Standard-0101.06 certification mandates compress replacement cycles across municipal police agencies. South Carolina and Virginia industrial clusters host polyethylene fiber production realignment toward military-grade output.
Germany
Bundeswehr equipment refresh cycles and NATO rapid response unit procurement sustain demand for STANAG 4569-rated helmet platforms. EU PPE Regulation CE marking under MDR classification tightens conformity assessment for law enforcement body armor. Bavaria-based defense contractors consolidate supplier qualification pools toward established EU authorized representative infrastructure.
France
French federal police procurement offices prioritize modular helmet systems with integrated communications mounts for tactical units. CE marking requirements extend technical file preparation timelines for biological compatibility evaluation. Paris and Lyon metropolitan defense industrial bases concentrate ceramic-polyethylene hybrid plate integration capacity.
India
Bureau of Indian Standards mandates for domestic law enforcement procurement create protected market access for localized manufacturing. Central Armed Police Forces equipment modernization drives polyethylene and ceramic composite plate adoption. Tamil Nadu and Maharashtra industrial corridors attract joint venture formation for BIS-compliant armor assembly.
United Kingdom
Ministry of Defence spending on soldier modernization programs sustains above-average procurement for lightweight hard armor plates. UKCA marking transition from CE certification creates parallel conformity assessment requirements for law enforcement suppliers. Midlands defense manufacturing clusters specialize in modular helmet platform assembly with accessory rail integration.
Advanced Protective Gear and Armor Market Competitive Landscape
Global majors compete with regional champions across certification infrastructure and military procurement channel access. Market structure tiers between defense prime contractors holding STANAG qualification histories and specialty materials suppliers controlling fiber precursor production. Three archetypes dominate: vertically integrated chemical-to-armor manufacturers, modular systems integrators, and component specialists with NIJ compliance expertise. Competitive moves concentrate on capacity expansion for UHMWPE fiber output and strategic partnerships to satisfy multi-jurisdictional certification burdens.
Among United States-based material science conglomerates, DuPont de Nemours, Inc. and Honeywell International Inc. occupy positions reflecting Kevlar heritage and Spectra fiber backward integration respectively. MSA Safety Inc. exemplifies the integrated protection platform archetype through combined head and respiratory system offerings. These three anchors demonstrate how supplier power concentrates around raw material control and established federal contractor status.
| Leading Market Players |
|---|
| Point Blank Enterprises, Inc. |
| MSA Safety Inc. |
| Honeywell International Inc. |
| Rheinmetall AG |
| Avon Protection plc |
| 3M Company |
| BAE Systems plc |
| ArmorSource LLC |
| DuPont de Nemours, Inc. |
| Others |
Pricing and Supply Chain Analysis
Polyethylene-ceramic hybrid plate manufacturing migration from steel-dominant processes simultaneously compresses per-unit production economics and concentrates supplier power among North American specialty materials producers with captive UHMWPE fiber capacity. This technological transition rewards integrated manufacturers while squeezing margins for downstream assemblers dependent on spot-market ceramic precursor purchases.
Pricing Analysis
Warranty and lifecycle refurbishment bundling separates premium military contractors from standard law enforcement suppliers, with STANAG-qualified vendors commanding extended service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with NIJ Level IV plates carrying substantial premiums over Level IIIA soft armor. Pricing pressure stems from federal equipment grant consolidation favoring established contractors with compliant product listings. Municipal police departments exhibit highest price sensitivity due to budget constraints, while United States Special Operations Command demonstrates lowest sensitivity prioritizing weight-to-protection ratios.
Supply Chain Analysis
Reverse-logistics flows for ballistic plate refurbishment and helmet remanufacturing remain underdeveloped, creating stranded value in end-of-life protective equipment. Geographic concentration centers on United States boron carbide precursor production, Southeast Asian UHMWPE fiber processing expansion, and German ceramic composite integration capacity. Raw material dependencies include silicon carbide powders, ultra-high-molecular-weight polyethylene fibers, and aramid fabric weaves. Single-source vulnerability concentrates in specialty ceramic precursor supply among limited chemical producers. Distribution runs through defense prime contractor networks and federal procurement channels with direct agency relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification infrastructure and military procurement channel access, with multi-jurisdictional compliance burdens forcing weaker regional suppliers toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from polyethylene fiber capacity expansion by securing long-term offtake agreements with specialty materials producers before allocation constraints tighten. Defensive positioning demands accelerated STANAG 4569 requalification investments to lock in NATO procurement relationships against emerging competitors. Backward integration into ceramic precursor processing mitigates supply volatility exposure from concentrated boron carbide suppliers. For New Entrants and Emerging Players: Capture protected market access through BIS-compliant joint ventures in Tamil Nadu and Maharashtra industrial corridors, where Indian Central Armed Police Forces modernization creates localized demand. White space exists in modular helmet platform assembly with integrated communications mounts, where rapid NATO procurement tempos outpace incumbent capacity expansion. Go-to-market positioning should emphasize EU authorized representative infrastructure to bypass CE marking timeline disadvantages. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated chemical-to-armor manufacturers given UHMWPE fiber supply scarcity and military backlog sustainability. Long-term viability favors archetypes controlling raw material production and holding multi-jurisdictional certification histories. Acquisition targets should demonstrate established NIJ compliance expertise and federal contractor status. The signal to watch is directed energy weapon thermal management integration requirements, which will force material science roadmaps beyond current supplier capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| UHMWPE Fiber Capacity Expansion | Backward integration into Spectra fiber production secures supply allocation for military backlogs. |
| STANAG 4569 Requalification Investment | Extended testing timelines lock in NATO rapid response unit procurement relationships. |
| BIS Localization Joint Venture | Tamil Nadu manufacturing partnerships satisfy Indian law enforcement domestic content mandates. |
| Modular Helmet Platform Development | Integrated communications mounts address United States Special Operations Command priority requirements. |
| Ceramic Precursor Supply Agreement | Long-term boron carbide contracts mitigate input cost volatility from specialty chemical concentration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across defense procurement officers, NIJ certification laboratory directors, specialty materials plant managers, and law enforcement equipment grant administrators. Secondary validation drew from United States Department of Justice compliance listings, NATO standardization office documentation, Bureau of Indian Standards notifications, and European Commission PPE regulation guidance. Bottom-up segment modeling triangulated against top-down macroeconomic demand indicators.
Granularity-level modeling operated at product type, material composition, end user, and deployment context dimensions, with additional disaggregation by NIJ threat level and STANAG rating tier. Value projections across the analysis window derived from unit economics applied to procurement volume estimates, with CAGRs synthesized from replacement cycle analysis and modernization program announcements. Forecast inputs incorporated polyethylene fiber capacity expansion timelines, federal equipment grant disbursement patterns, and evolving armor-piercing ammunition threat specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to directed energy weapon proliferation and ceramic precursor supply disruptions. Projections reflect assumptions regarding sustained NATO modernization spending and NIJ certification update implementation timelines without anticipating breakthrough material science advances. Practitioners should monitor armor-piercing ammunition variant development and thermal management integration requirements for early signals of roadmap disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Food Processing Uniforms Market
Protective Gear
Diving Suits Market
Protective Gear
Hand Gloves Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
China Pollution Mask Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Boxed Glove for Food Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Heated Goggles Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Dust Covers Market
Protective Gear
Military Boots Market
Protective Gear
Safety Shoes Market
Protective Gear
Helmet Lining Market
Protective Gear
Waterproof Cases Market