
 Military Boots Market | 2026-2036
Military Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Military Boots Market Outlook
Multi-source to dual-source procurement patterns is realigning how defense agencies contract footwear suppliers. Belleville Boot Company leverages its Berry Amendment-certified U.S. manufacturing footprint to anchor Pentagon supply agreements. Wolverine World Wide sustains diversified production across Bates and other portfolio labels, competing for both military and tactical commercial channels. Rocky Brands differentiates through specialized cold-weather and mountain warfare designs that occupy niche specification tiers.
Military boots are ankle-to-knee protective footwear engineered with vulcanized rubber outsoles, full-grain leather uppers, and moisture-wicking lining systems designed to prevent immersion foot and maintain thermal stability across operational theaters. Combat boots lead procurement volume due to universal infantry issuance requirements, while tactical boots represent the fastest-expanding category as law enforcement and security contractors adopt military-grade specifications. Waterproof configurations command premium positioning within material segmentation, reflecting end-user prioritization of extended patrol capability in wetland and maritime environments.
The U.S. Department of Defense enforces Berry Amendment compliance mandating domestic sourcing of textiles and footwear for military end-use, while NATO standardization agreements shape interoperability requirements across allied force procurement. The U.S. Army's Product Manager Soldier Equipment and ISO 20347 occupational footwear standards collectively define performance benchmarks for slip resistance, puncture protection, and flame resistance. Stakeholders must monitor how U.S. defense budget authorization cycles and evolving EU procurement directives for military personal equipment reshape accessible contract pools and certification pathways.
Market Dynamics
The U.S. Department of Defense's Berry Amendment enforcement is compressing supplier qualification timelines while NATO standardization agreements simultaneously expand interoperability testing protocols across allied procurement systems.
Growth Catalysts
- Multi-terrain operational requirements:Special Forces procurement programs across NATO-aligned defense ministries are mandating footwear systems capable of rapid terrain transition without equipment changeout.
- Domestic sourcing mandates:The Berry Amendment's textile and footwear provisions are redirecting Pentagon contract flows toward U.S.-based manufacturing facilities with verified supply chain documentation.
- Law enforcement specification upgrades:Federal and municipal tactical units are adopting military-grade boot standards, expanding addressable demand beyond traditional defense channels.
Market Restraints
- Full-grain leather price volatility:Tannery capacity concentration in specific geographic clusters exposes manufacturers to raw material cost swings without short-term substitution options.
- Berry Amendment compliance overhead:Domestic sourcing verification requirements impose documentation and audit burdens that disqualify offshore production alternatives regardless of cost efficiency.
- Vulcanized rubber supply concentration:Specialized outsole compound production relies on a limited supplier base, creating single-source vulnerability for puncture-resistant formulations.
Strategic Opportunities
- EU defense procurement harmonization:The European Defence Fund's personal equipment standardization initiatives are opening cross-border contract pools for certified suppliers meeting PESCO interoperability benchmarks.
- Maritime patrol specialization:Amphibious warfare units require waterproof configurations with extended submersion ratings, commanding specification tiers with limited current supply.
- ISO 20347 certification pathways:Occupational footwear standards adoption by private security contractors creates parallel commercial demand channels with reduced Berry Amendment friction.
Industry Challenges
- Multi-standard testing protocols:Simultaneous compliance with U.S. Army Product Manager Soldier Equipment specifications, NATO standardization agreements, and ISO 20347 benchmarks stretches certification timelines and testing budgets.
- Thermal stability engineering talent:Specialized knowledge in moisture-wicking lining system design and cold-weather insulation integration remains concentrated within legacy defense suppliers, constraining new entrant capability development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Boots Market |
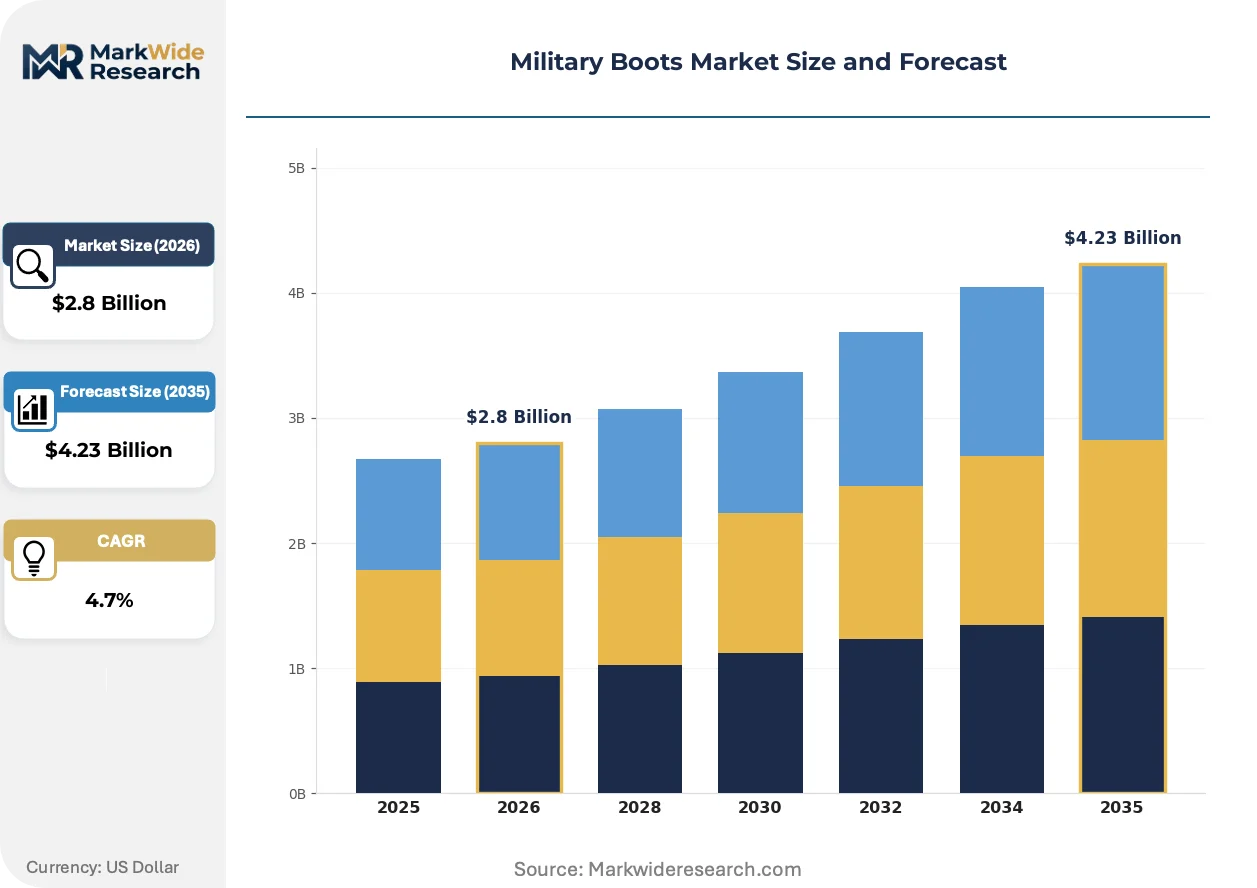
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combat Boots, Tactical Boots, Desert Boots, Waterproof Boots Material: Leather, Nylon, Synthetic, Rubber End User: Army, Navy, Air Force, Special Forces Usage Environment: Outdoor, Urban, Combat, Training |
| Companies Covered | Belleville Boot Company, Wolverine World Wide, Rocky Brands, HAIX, Bates Footwear, Altama, LOWA, Danner, Magnum Boots, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Boots Market Strategic Shifts
Material science advances and procurement digitization are compressing product development cycles while redefining performance verification methods across military footwear supply chains.
Carbon fiber shank reinforcement is electrifying load-bearing efficiency in combat boot midsole architecture. U.S. Army airborne units are field-testing reduced-weight configurations during rapid deployment exercises. This technology is electrifying competitive positioning by enabling manufacturers to meet stringent puncture protection thresholds without traditional steel plate mass penalties.
REACH Regulation substance restrictions are eliminating specific chemical treatments previously standard in leather tanning and rubber vulcanization processes. European defense procurement channels now require full material disclosure documentation extending through tier-three suppliers. Waterproof boot configurations destined for EU member state forces face the most acute reformulation pressure as legacy DWR coatings exceed newly restricted substance thresholds.
Direct-to-unit digital catalog ordering is fragmenting traditional centralized procurement patterns. U.S. Marine Corps expeditionary units now access approved manufacturer portals for rapid size-exchange and theater-direct fulfillment, bypassing conventional defense logistics agency distribution. This channel shift concentrates most visibly in forward-deployed Pacific theater operations where resupply latency drives preference for manufacturer-integrated inventory systems.
Military Boots Market Segmentation
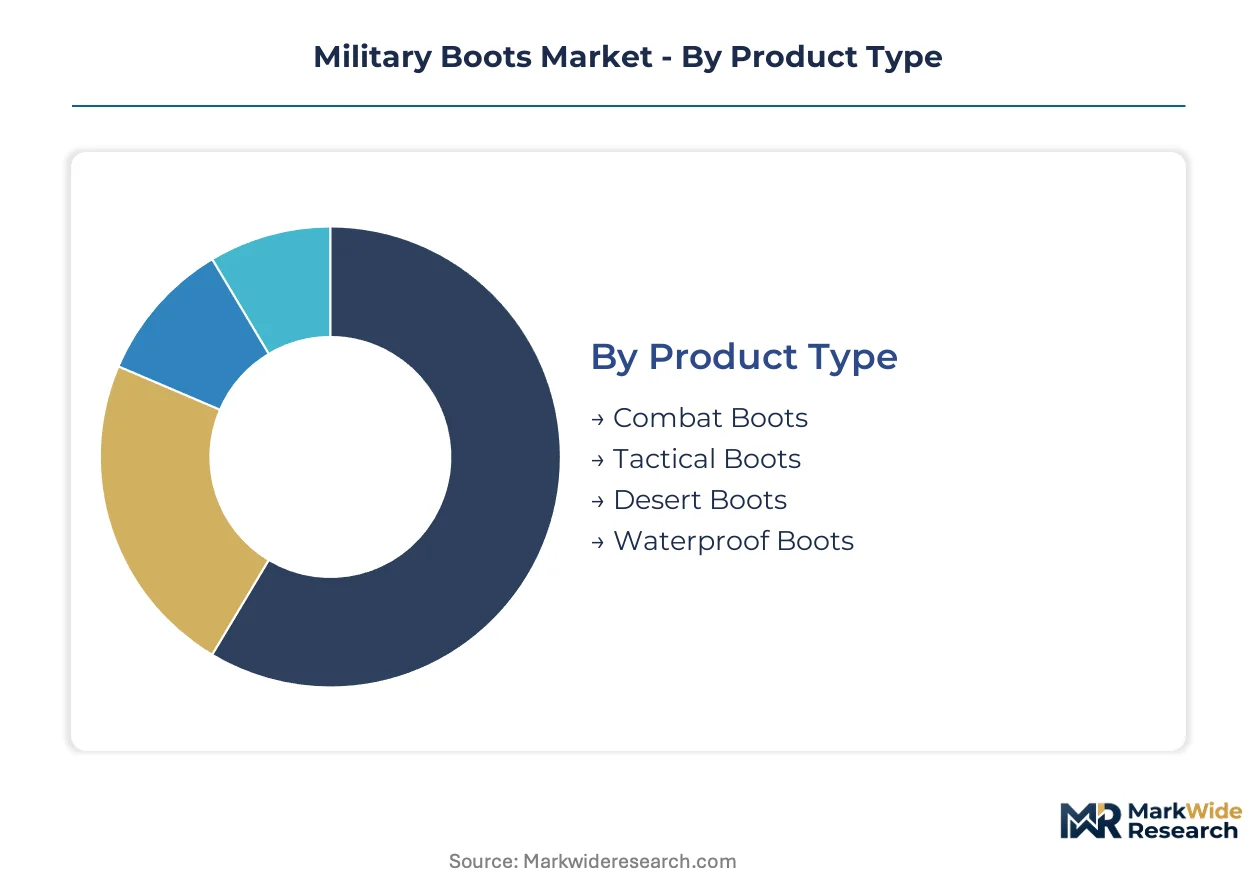
Procurement officers structure footwear acquisition around operational tempo and terrain specificity rather than unit size alone. Segmentation clarity enables defense agencies to match boot specifications against mission profiles while suppliers align R&D investment toward contractable performance tiers.
Product Type:
Replacement cycles for military footwear compress during active deployment periods and extend during garrison duty, creating uneven demand patterns across product categories.
- Combat Boots:Full-grain leather uppers with vulcanized rubber outsoles and moisture-wicking lining systems form the standard-issue foundation for universal infantry deployment. Pentagon volume commitments through Army and Marine Corps modernization programs anchor procurement schedules for this category.
- Tactical Boots:Lightweight synthetic constructions with accelerated break-in periods address law enforcement and security contractor specifications that diverge from full military compliance. Federal and municipal tactical units across the United States are adopting military-grade standards, expanding addressable demand beyond traditional defense channels.
- Desert Boots:Suede leather and nylon mesh hybrids prioritize sand penetration resistance and thermal regulation for arid theater operations.
- Waterproof Boots:Extended submersion-rated configurations with sealed membrane barriers serve amphibious warfare and maritime patrol requirements.
Volume placements concentrate in Combat Boots; the faster expansion belongs to Tactical Boots.
Material:
Cost tier differentiation separates premium full-grain constructions from economy synthetics in defense contracting frameworks.
- Leather:Tannery capacity concentration in specific geographic clusters exposes manufacturers to raw material cost swings without short-term substitution options. NATO standardization agreements and U.S. Army Product Manager Soldier Equipment specifications both prioritize leather durability benchmarks.
- Synthetic:Engineered polymer weaves reduce mass and accelerate drying cycles for expeditionary units operating across multiple climate zones. REACH Regulation substance restrictions are eliminating specific chemical treatments previously standard in synthetic production.
- Nylon:High-tensile ballistic fabrics reinforce ankle support zones and abrasion panels.
- Rubber:Specialized outsole compound production relies on a limited supplier base, creating single-source vulnerability for puncture-resistant formulations.
Leather dominates specification-heavy contracts; synthetic materials are climbing the fastest in Special Forces procurement.
End User:
Customer type determines certification burden and contract duration, with uniformed services demanding Berry Amendment compliance that private security contractors can bypass.
- Army:The largest uniformed service by headcount drives standardized procurement through centralized Defense Logistics Agency channels with multi-year volume commitments.
- Special Forces:Small-unit procurement with rapid terrain transition requirements commands premium pricing for multi-terrain footwear systems. Direct-to-unit digital catalog ordering is fragmenting traditional centralized patterns for this end user.
- Navy:Amphibious and maritime patrol units specify waterproof configurations with corrosion-resistant hardware.
- Air Force:Flight line and security personnel require flame-resistant materials meeting distinct specification tiers.
Army contracts anchor annual volume; Special Forces represents the steepest expansion trajectory.
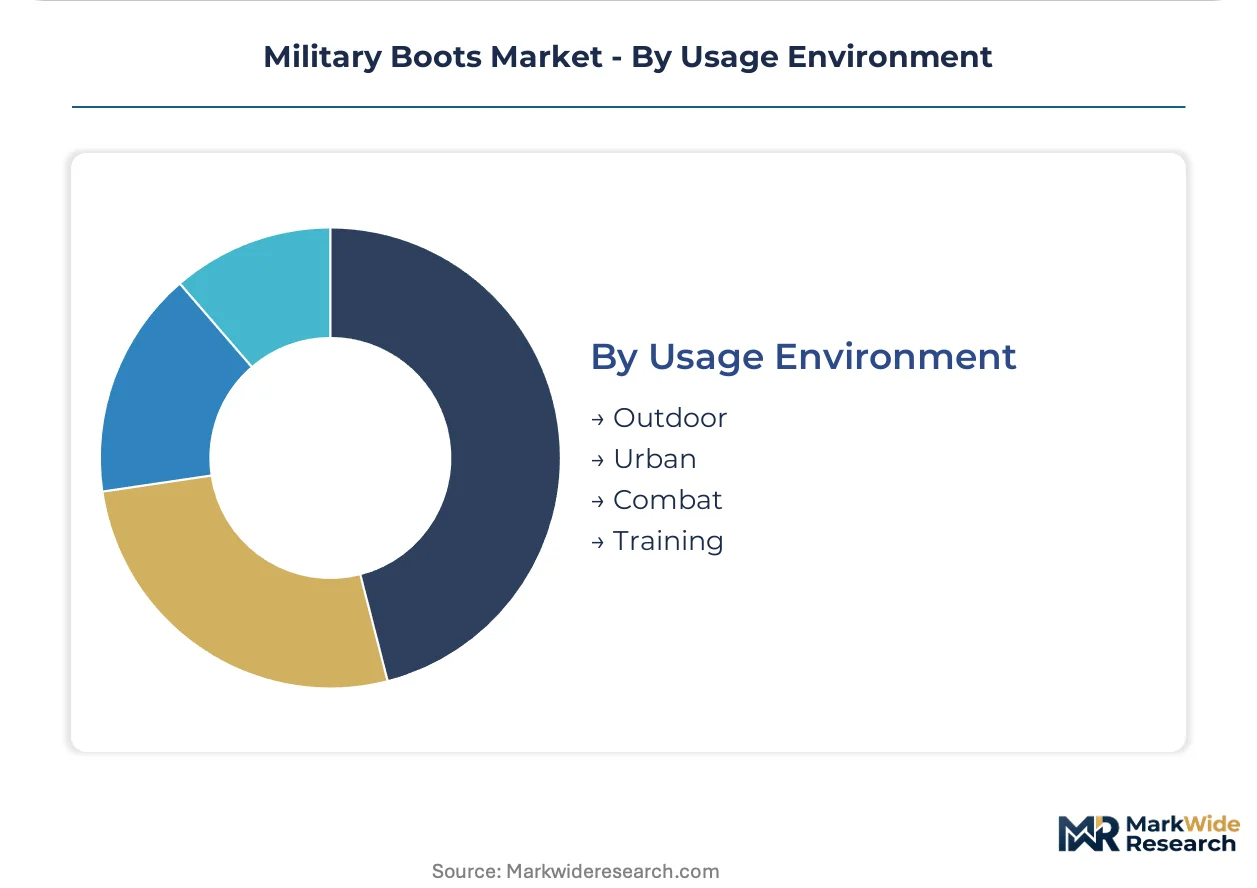
Usage Environment:
Application context dictates performance thresholds, with combat-rated specifications requiring extensive testing protocols that training environments can relax.
- Combat:Puncture protection, flame resistance, and slip resistance certifications under ISO 20347 and NATO standardization agreements define mandatory performance floors. Multi-standard testing protocols stretch certification timelines for manufacturers serving this environment.
- Training:Reduced durability requirements permit cost optimization through simplified construction methods while maintaining basic safety standards. U.S. Marine Corps expeditionary units access approved manufacturer portals for rapid size-exchange in this usage category.
- Outdoor:Extended patrol capability prioritizes thermal stability and moisture management across variable weather conditions.
- Urban:Concrete and asphalt abrasion patterns favor modified outsole compounds with enhanced lateral stability.
Combat-rated placements absorb the majority of defense procurement spend; Training environments are gaining share fastest through private security contractor adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates defense procurement volume through Pentagon modernization programs, while NATO allies and Pacific theater partners drive interoperability demand for multi-terrain footwear systems.
United States
Army and Marine Corps modernization programs anchor annual volume commitments through Defense Logistics Agency channels. The Berry Amendment mandates domestic sourcing verification for textile and footwear procurement, compressing supplier qualification timelines. Wolverine World Wide maintains diversified production across Michigan-based facilities to compete for both military and tactical commercial contracts.
Germany
Bundeswehr special operations units command premium specifications for alpine and cold-weather configurations. ECHA REACH Regulation substance restrictions eliminate legacy chemical treatments in leather tanning and rubber vulcanization processes. Bavaria-based suppliers face acute reformulation pressure as waterproof boot configurations exceed newly restricted DWR coating thresholds.
United Kingdom
Ministry of Defence special forces procurement emphasizes rapid terrain transition capability without equipment changeout. NATO standardization agreements shape interoperability testing protocols for allied force equipment. Industrial clusters in the Midlands and Northwest England concentrate legacy defense footwear manufacturing with established Product Manager Soldier Equipment specification familiarity.
France
Direction Générale de l'Armement procurement prioritizes amphibious warfare configurations with extended submersion ratings. EU Green Deal and CSRD reporting requirements extend supply chain disclosure obligations through tier-three suppliers. The Auvergne-Rhône-Alpes region hosts specialized tannery capacity exposed to full-grain leather price volatility from geographic concentration.
Australia
Australian Defence Force Pacific theater operations drive preference for manufacturer-integrated inventory systems with rapid resupply capability. The country's national defense procurement regulator enforces ISO 20347 occupational footwear standards alongside NATO interoperability benchmarks. Victoria and New South Wales industrial zones accommodate regional distribution hubs for forward-deployed expeditionary units.
Military Boots Market Competitive Environment
Capacity expansion dominates the current landscape as Berry Amendment compliance requirements redirect contract flows toward U.S.-based manufacturing facilities. The vendor base stratifies across three tiers: legacy defense specialists with Pentagon certification history, diversified footwear conglomerates serving parallel commercial channels, and regional fabricators targeting NATO allied procurement. M&A activity and strategic partnerships concentrate among mid-cap specialists seeking geographic diversification and technology licensing access.
Within the legacy defense specialist tier, Belleville Boot Company and Rocky Brands exemplify archetypes anchored by Berry Amendment-certified domestic manufacturing footprints. HAIX occupies a position representing European-based specialists navigating REACH Regulation reformulation pressures. Wolverine World Wide sits within the diversified conglomerate archetype, sustaining portfolio breadth across military and tactical commercial segments.
| Leading Market Players |
|---|
| Belleville Boot Company |
| Wolverine World Wide |
| Rocky Brands |
| HAIX |
| Bates Footwear |
| Altama |
| LOWA |
| Danner |
| Magnum Boots |
| Others |
Value Chain & Pricing Dynamics
Specialized vulcanized rubber compound formulators in the U.S. Midwest and Bavaria command wage premiums that propagate through three-tier pricing spreads separating Berry Amendment-certified combat boots from commercial tactical alternatives and economy training configurations.
Pricing Analysis
Extended-warranty and rapid-resupply service bundles differentiate Pentagon contract tiers from unbundled commercial sales. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with ISO 20347 and NATO standardization compliance commanding substantial premiums. Cost compression in the synthetic material tier is intensifying because REACH Regulation reformulation expenses are being passed through leather-dependent suppliers. Private security contractors exhibit highest price sensitivity due to bypassing Berry Amendment compliance overhead, while Special Forces units demonstrate lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Freight cost differentials between domestic U.S. manufacturing and offshore alternatives are narrowing as fuel surcharges and port congestion penalties accumulate. Tannery capacity concentrates in the Auvergne-Rhône-Alpes region of France, the U.S. Midwest, and Bavaria, Germany, drawing from full-grain hides, specialized rubber compounds, and ballistic nylon weaves. Single-source vulnerability pervades puncture-resistant vulcanized rubber formulations. Distribution runs through Defense Logistics Agency centralized channels for Army volume commitments, with direct-to-unit digital portals fragmenting Special Forces procurement patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Berry Amendment-certified domestic manufacturing capacity operates at effective utilization ceilings, propping pricing power for qualified suppliers against offshore cost advantages.
For Market Incumbents: Deepen backward integration into tannery operations and captive rubber compounding to defend against full-grain leather price volatility and single-source vulcanized rubber vulnerability. Expand capacity in Michigan-based facilities to capture Army modernization program volume commitments before qualification timelines compress further. For New Entrants and Emerging Players: Direct-to-unit digital catalog platforms offer the lowest-friction entry vector for bypassing Defense Logistics Agency incumbent relationships. Target private security contractor segments with ISO 20347-certified synthetic constructions that avoid Berry Amendment compliance overhead, then leverage field performance data to pursue NATO standardization agreements. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing dormant Berry Amendment certification infrastructure given Pentagon domestic sourcing mandate acceleration. Long-term viability favors manufacturers with demonstrated Product Manager Soldier Equipment specification familiarity and established alpine or cold-weather engineering talent pools. Watch for EU defense procurement harmonization announcements under PESCO frameworks as inflection signals for cross-border contract pool access.| Strategic Initiative | Industry Significance |
|---|---|
| Berry Amendment Certification Investment | Unlocks Pentagon contract flows through verified domestic sourcing documentation. |
| REACH Regulation Reformulation Program | Preserves European defense channel access by eliminating restricted DWR coating substances. |
| Direct-to-Unit Digital Platform Launch | Captures Special Forces procurement fragmentation bypassing traditional logistics channels. |
| Carbon Fiber Shank Technology Licensing | Enables puncture protection compliance without steel plate mass penalties for airborne units. |
| Multi-Terrain Footwear System Development | Addresses NATO rapid terrain transition mandates expanding across allied procurement programs. |
Study Parameters
Defense Logistics Agency procurement databases, NATO standardization agreement documentation, and EU defense procurement directive filings formed the secondary backbone. Primary interviews with U.S. Army Product Manager Soldier Equipment officials, tannery procurement leads, commercial tactical distributors, and private security contractor equipment officers combined with secondary validation. Bottom-up and top-down triangulation reconciled unit issuance forecasts against defense budget authorization flows.
The analytical lens alternated between bottom-up segment builds and top-down budget allocation verification across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user service branch, and usage environment intensity. CAGRs were derived from deployment cycle analysis and modernization program schedules, with inputs from Special Forces procurement velocity and law enforcement specification upgrade trajectories.
The model holds under steady defense budget authorization cycles; deviation in Berry Amendment enforcement intensity or EU defense fund harmonization timelines would shift supplier qualification dynamics. Forecasts reflect documented assumptions about procurement digitization adoption rates and REACH substance restriction implementation schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Mobile Protective Cases Market
Protective Gear
China Pollution Mask Market
Protective Gear
Bungee Cords and Accessories Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Earplug Distributor Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Work Boots Market
Protective Gear
Helmets Market
Protective Gear
Pet Control Devices Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Boxed Glove for Food Market
Protective Gear
Waterproof Boots Market
Protective Gear
Dust Covers Market
Protective Gear
Hand Gloves Market
Protective Gear
Heated Goggles Market