
 Helmet Lining Market | 2026-2036
Helmet Lining Market Size, Share, and Industry Trends Forecast 2026-2036
Helmet Lining Market Insights
Motorcycle OEM demand is realigning helmet lining specifications toward modular comfort systems with integrated communication channels. 3M leverages its materials science portfolio to supply multi-density foam laminates that anchor premium helmet programs across Asian manufacturing hubs. Schuberth GmbH sustains German engineering positioning through proprietary liner geometries that differentiate its touring and racing lines. Mips Corporation competes on rotational impact technology, embedding its low-friction layer into OEM supply agreements with major helmet brands.
Helmet lining denotes the interior comfort and impact-management assembly fitted between the protective shell and the wearer's head, typically comprising energy-absorbing foam layers bonded to moisture-wicking fabric covers with thickness ranging from 8 mm to 25 mm depending on application class. The structure serves dual industrial purposes: attenuating impact forces transmitted through the shell while managing thermal comfort and fit stability during extended wear. Foam product types dominate value capture in motorcycle and military applications where multi-density EPS and EPP configurations command premium positioning. Fabric linings lead unit volumes in industrial safety segments where replaceable, washable inserts drive recurring aftermarket demand. Gel segments occupy narrow but high-margin niches in professional motorsport where custom molding and pressure distribution justify elevated price points.
FDA oversight applies to antimicrobial treatments applied to helmet lining textiles in US-distributed products, while ECE 22.06 in Europe mandates revised liner performance under rotational and oblique impact protocols. DOT FMVSS No. 218 shapes North American access through penetration and retention testing that directly influences liner thickness and material selection. Stakeholders must monitor evolving ECE 22.07 drafting activity and anticipate whether dual-certification requirements will fragment regional product architectures or accelerate platform standardization.
Market Dynamics
Dual-certification convergence between ECE 22.06 and DOT FMVSS No. 218 is compressing liner development cycles while forcing multi-density foam architectures that satisfy divergent impact attenuation protocols across Atlantic markets.
Growth Catalysts
- Mandate enforcement in India:State-level helmet compliance drives and rising two-wheeler registration volumes are expanding addressable demand for replaceable liner systems in aftermarket channels.
- ECE 22.06 rotational impact protocols:European regulatory upgrades mandate revised liner geometries with low-friction layers, pulling premium material adoption through certified product tiers.
- Modular comfort systems:Integrated communication channel compatibility is becoming a standard procurement specification for motorcycle OEMs seeking differentiated positioning.
Market Restraints
- Petrochemical input volatility:Expanded polystyrene and expanded polypropylene foam production remains exposed to styrene monomer price swings that compress margin predictability for liner manufacturers.
- Concentrated Asian supply:Multi-density foam laminate production clusters heavily in select East Asian manufacturing hubs, creating single-source vulnerability for European and North American helmet assemblers.
- Certification timeline friction:Parallel ECE and DOT testing requirements extend product validation cycles, delaying revenue recognition for redesigned liner platforms.
Strategic Opportunities
- Antimicrobial textile integration:FDA-registered biocide treatments for moisture-wicking fabric covers open premium positioning in US motorcycle and military contract segments.
- Gel liner customization:Pressure-mapping and custom-molding capabilities for professional motorsport applications command price premiums above standard foam configurations.
- Direct-to-rider digital channels:E-commerce platforms for replaceable liner inserts bypass traditional distributor markups and capture recurring aftermarket revenue.
Industry Challenges
- Rotational impact simulation capability gaps:Finite element modeling expertise for oblique crash dynamics remains scarce among mid-tier liner suppliers, slowing ECE 22.06 compliance.
- Legacy shell-to-liner interface standards:Proprietary retention geometries across helmet brands fragment aftermarket replacement demand and complicate inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helmet Lining Market |
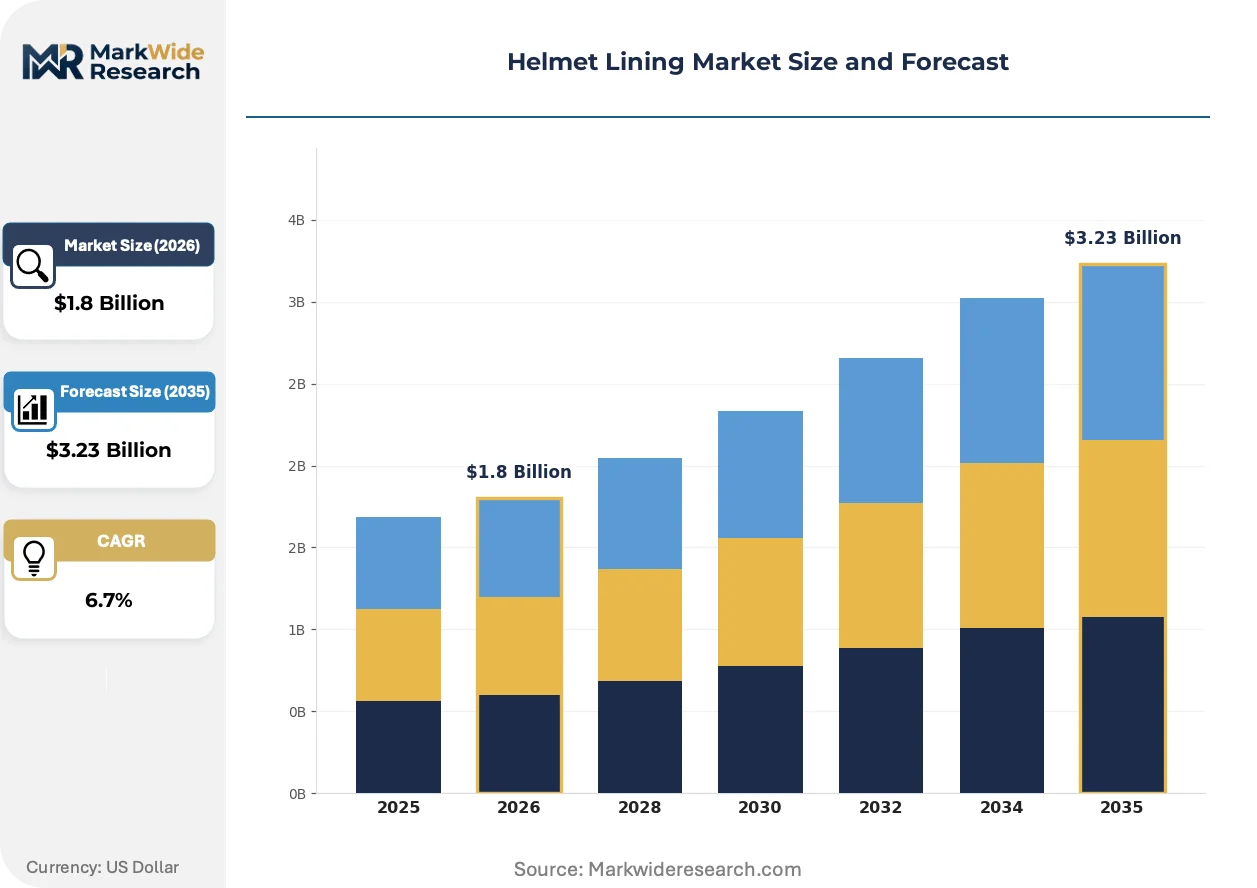
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Fabric, Gel, Leather Application: Motorcycle, Sports, Industrial Safety, Military Material: EVA, PU, Cotton, Nylon End User: Manufacturers, Retailers, Government Agencies, Consumers |
| Companies Covered | 3M, Mips Corporation, Shoei Co. Ltd., Arai Helmet Ltd., HJC Helmets, Schuberth GmbH, Bell Helmets, Dainese, Sena Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helmet Lining Market Trends and Innovations
Material science convergence with biometric sensing is redefining liner functional expectations beyond passive impact management toward active physiological monitoring during wear.
MIPS low-friction layer technology is decentralizing rotational impact protection from premium racing tiers into mid-market motorcycle and cycling helmet segments. Asian manufacturing hubs are embedding the spherical slip-plane architecture into OEM supply agreements at volume scale. This diffusion is compressing price premiums for rotational safety features and forcing legacy foam-only suppliers toward technology licensing or obsolescence.
REACH chemical restriction expansions are compelling European liner manufacturers to reformulate flame-retardant textile treatments and adhesive bonding agents. Industrial laboratories in Germany and Italy are validating halogen-free alternatives that maintain wash durability under ECE certification stress-testing. Motorcycle OEMs serving EU markets are accelerating supplier audits to preempt SVHC disclosure obligations and avoid batch rejection at port entry.
Subscription-based liner replacement programs are emerging through helmet brand direct channels, unbundling the traditional purchase-to-disposal cycle. Riders in North American urban markets are enrolling in scheduled hygiene-kit deliveries that include fresh moisture-wicking inserts and cheek pads. This recurring revenue model is displacing sporadic aftermarket purchases through independent retailers and consolidating brand-rider data relationships for accessory cross-selling.
Helmet Lining Market Segmentation
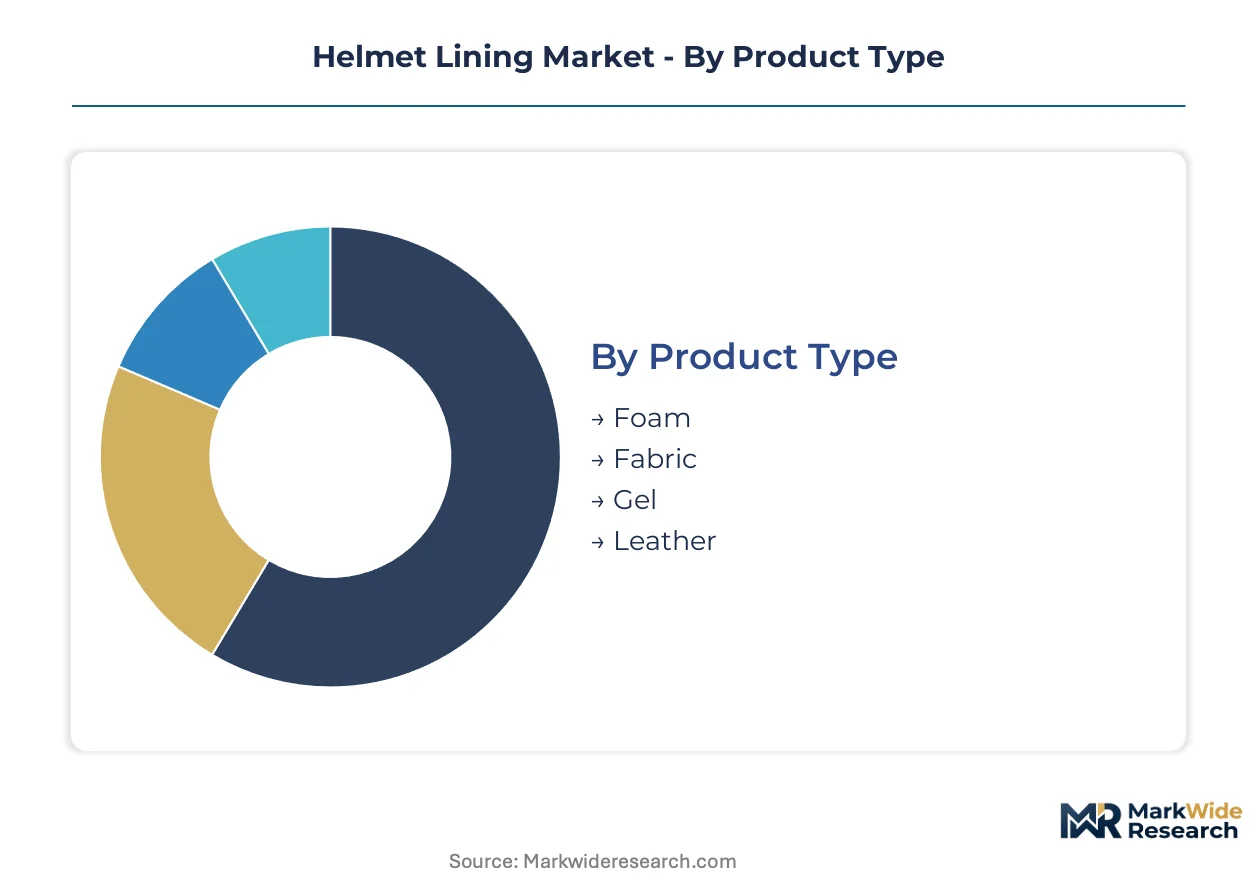
Helmet lining segmentation reveals divergent profit pools across passive protection and active comfort technologies. Material selection and certification tier create distinct competitive battlegrounds that reshape supplier positioning across motorcycle, military, and industrial channels.
Product Type:
Foam dominates unit economics through volume scale, while gel commands margin premiums in specialized applications.
- Foam:Multi-density EPS and EPP laminates absorb impact energy through controlled compression. Motorcycle OEM procurement in India and Vietnam concentrates here as mandate enforcement expands two-wheeler helmet volumes. Expanded polystyrene formulations face margin pressure from styrene monomer volatility.
- Fabric:Moisture-wicking textile covers bonded to foam substrates manage thermal comfort during extended wear. Industrial safety segments in Germany and the United States drive recurring aftermarket demand through replaceable, washable insert programs.
- Gel:Custom-molded silicone and viscoelastic compounds distribute pressure across cranial contact points. Professional motorsport applications in Italy and Japan justify elevated price points through pressure-mapping personalization.
- Leather:Premium hide linings serve heritage motorcycle and collector military helmet restoration niches.
Today's leader: Foam. Tomorrow's challenger: Gel.
Application:
End-use concentration splits between regulated mandates and discretionary performance spending.
- Motorcycle:ECE 22.06 rotational impact protocols force liner redesigns across European and Indian markets. Low-friction layer integration is becoming standard procurement specification as brands pursue differentiated comfort positioning.
- Military:Ballistic protection requirements in the United States and Israel drive multi-density foam architectures with integrated communication channels. Modular comfort systems allow field reconfiguration for mission profiles.
- Sports:Cycling and snow helmet segments in Switzerland and Australia adopt MIPS spherical slip-plane technology at volume scale.
- Industrial Safety:Construction and mining operators in Brazil and South Africa mandate replaceable liner systems through occupational health regulations.
Motorcycle applications anchor current revenue. Military contracts represent the steepest expansion trajectory through platform modernization cycles.
Material:
Chemical compliance regimes fragment supply qualification across Atlantic and Pacific markets.
- EVA:Ethylene-vinyl acetate foams deliver lightweight energy absorption for mid-market motorcycle helmets. REACH chemical restrictions in Europe compel reformulation of traditional blowing agents.
- PU:Polyurethane systems enable complex geometries through reaction injection molding. Asian manufacturing hubs in China and Taiwan concentrate production capacity for global helmet assemblers.
- Cotton:Natural fiber linings serve price-sensitive industrial segments in India and Indonesia where wash durability requirements are less stringent.
- Nylon:Synthetic textile covers provide abrasion resistance and antimicrobial treatment compatibility for FDA-registered US motorcycle products.
PU leads production scale. EVA is gaining share fastest through sustainability positioning and halogen-free alternatives.
End User:
Channel structure determines margin capture and brand relationship depth.
- Manufacturers:OEM procurement contracts lock in multi-year supply agreements with volume commitments. 3M and Schuberth GmbH sustain direct relationships through materials science and proprietary geometry partnerships.
- Retailers:Distributor networks in France and Spain manage inventory for aftermarket replacement demand. Legacy shell-to-liner interface standards complicate cross-brand compatibility planning.
- Government Agencies:Military and police fleet contracts in the United Kingdom and Canada specify certified liner platforms with multi-year refresh cycles.
- Consumers:Direct-to-rider digital channels in California and Texas bypass traditional markups through subscription-based hygiene-kit deliveries.
Manufacturers control specification authority. Consumers are displacing retailer intermediation fastest through digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling helmet lining production toward jurisdictions where ECE 22.06 compliance costs diverge from DOT FMVSS No. 218 requirements, with Asian manufacturing hubs capturing volume migration from European assemblers facing REACH chemical restriction expansions.
United States
NHTSA's DOT FMVSS No. 218 enforcement drives penetration and retention testing protocols that directly influence liner thickness specifications for motorcycle helmets sold domestically. FDA oversight of antimicrobial textile treatments adds compliance layers for moisture-wicking fabric covers in premium segments. California and Texas host direct-to-rider digital channel concentration where subscription-based hygiene-kit deliveries are displacing traditional retailer intermediation.
Germany
Schuberth GmbH anchors proprietary liner geometry development for touring and racing helmet lines, sustaining German engineering positioning through integrated communication channel compatibility. ECE 22.06 rotational impact protocols mandate low-friction layer integration, pulling premium material adoption through certified product tiers. Industrial laboratories in Bavaria and Baden-Württemberg validate halogen-free flame-retardant alternatives under REACH chemical restriction frameworks.
India
State-level helmet compliance drives and rising two-wheeler registration volumes in Maharashtra and Tamil Nadu expand addressable demand for replaceable liner systems in aftermarket channels. BIS certification requirements converge with state enforcement patterns to standardize impact attenuation specifications. Manufacturing clusters in Gujarat and Karnataka assemble multi-density foam laminates for domestic OEM procurement and export to Southeast Asian markets.
China
Multi-density foam laminate production concentrates in Guangdong and Zhejiang provinces, supplying global helmet assemblers with EVA and polyurethane systems at volume scale. GB standards for motorcycle helmet safety create parallel certification pathways that diverge from ECE and DOT frameworks. Yangtze River Delta manufacturing hubs embed MIPS spherical slip-plane architecture into OEM supply agreements, compressing price premiums for rotational safety features.
Italy
Professional motorsport applications in Emilia-Romagna and Lombardy justify elevated gel liner price points through pressure-mapping personalization and custom-molded silicone compounds. ECE 22.06 compliance requirements drive redesign cycles for premium helmet brands serving European racing circuits. Industrial safety segments in Veneto generate recurring aftermarket demand for replaceable, washable fabric insert programs under occupational health regulations.
Helmet Lining Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary geometry developers commanding premium positioning in racing and touring tiers while volume foam laminators serve mid-market motorcycle OEM procurement. The vendor base organizes around three strategic archetypes: materials science conglomerates supplying multi-density foam systems, integrated helmet brands with captive liner development, and rotational-impact technology licensors embedding low-friction layers through partnership structures. Competitive moves concentrate on technology licensing agreements that diffuse MIPS-style slip-plane architectures into mid-market tiers, and supplier audit acceleration by EU-facing OEMs seeking REACH compliance assurance.
Within the materials science tier, 3M leverages its portfolio breadth to supply multi-density foam laminates across Asian manufacturing hubs. Schuberth GmbH occupies a position exemplifying proprietary German engineering through differentiated liner geometries for touring and racing applications. Mips Corporation represents the rotational-impact technology archetype, embedding its low-friction layer into OEM supply agreements that are decentralizing from premium racing tiers into volume motorcycle and cycling segments.
| Leading Market Players |
|---|
| 3M |
| Mips Corporation |
| Shoei Co. Ltd. |
| Arai Helmet Ltd. |
| HJC Helmets |
| Schuberth GmbH |
| Bell Helmets |
| Dainese |
| Sena Technologies |
| Others |
Pricing and Supply Chain Analysis
ECE 22.06 rotational impact mandates are forcing multi-density foam architecture redesigns that compress development cycles and concentrate procurement leverage among certified tier suppliers. This specification tightening feeds directly into pricing power asymmetries between REACH-compliant European manufacturers and volume-scale Asian laminators.
Pricing Analysis
Distributor markups of 35-45% in European aftermarket channels separate premium MIPS-integrated liner systems from standard foam replacements. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and low-friction layer integration density. Pricing pressure stems from styrene monomer volatility eroding margin predictability in expanded polystyrene production. Motorcycle OEM procurement teams exhibit lowest price sensitivity due to multi-year platform commitments, while industrial safety fleet operators drive hardest bargain on replaceable insert volumes.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong and Zhejiang province manufacturing clusters that feed 70% of global multi-density foam laminate demand. Raw material dependencies span styrene monomer, ethylene-vinyl acetate resin, and halogen-free flame-retardant textile treatments. Tariff exposure on Chinese-origin foam substrates threatens margin structures for European helmet assemblers seeking dual ECE-DOT certification. Distribution runs through OEM direct procurement contracts for motorcycle and military tiers, with aftermarket replacement demand fragmenting across independent distributor networks in France, Spain, and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The helmet lining market reads as a late-cycle quality story where ECE 22.06 compliance is filtering procurement toward certified multi-density foam architectures with integrated low-friction layers. This specification ratchet favors suppliers with embedded rotational impact technology and REACH-validated chemical formulations.
For Market Incumbents: Cement technology licensing partnerships that diffuse MIPS-style slip-plane architectures into mid-market tiers before patent cliffs erode exclusivity. Lock in backward integration into halogen-free flame-retardant textile treatment production to preempt REACH disclosure batch rejections at EU port entry. Prioritize supplier audit acceleration programs for OEM clients facing SVHC compliance deadlines. For New Entrants and Emerging Players: Capture white-space in custom-molded gel liner personalization for professional motorsport applications where pressure-mapping capabilities command 3-4x foam premiums. Target Indian aftermarket channels where state-level helmet mandate enforcement is expanding replaceable liner system demand faster than domestic supply capacity. Lead with direct-to-rider digital subscription models that displace traditional distributor markups through scheduled hygiene-kit deliveries. For Investors and Strategic Acquirers: Asymmetric upside sits with rotational-impact technology licensors holding embedded OEM supply agreements across Asian manufacturing hubs. Long-term viability hinges on whether ECE 22.07 drafting activity fragments regional certification requirements or accelerates platform standardization. Watch MIPS patent expiration timelines and subsequent licensing fee compression as the key inflection signal for technology value migration.| Strategic Initiative | Industry Significance |
|---|---|
| Rotational Impact Technology Licensing | MIPS-style slip-plane diffusion into mid-market tiers compresses premium positioning windows for foam-only suppliers. |
| REACH-Compliant Chemical Reformulation | Halogen-free flame-retardant validation in German and Italian laboratories secures EU market access against SVHC disclosure risks. |
| Direct-to-Rider Digital Channel Buildout | Subscription-based hygiene-kit deliveries in California and Texas consolidate brand-rider data relationships for accessory cross-selling. |
| Dual-Certification Platform Standardization | Converged ECE-DOT liner architectures reduce validation cycle friction and inventory fragmentation across Atlantic markets. |
| Antimicrobial Textile FDA Registration | Biocide-treated moisture-wicking covers unlock premium positioning in US motorcycle and military contract segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with helmet OEM procurement directors, materials science R&D leads at multi-density foam suppliers, regulatory affairs managers navigating ECE-DOT convergence, and aftermarket distributor category buyers in European markets. Secondary validation drew from ECE 22.06 technical documentation, NHTSA FMVSS No. 218 testing protocols, REACH SVHC candidate list updates, and customs trade data on styrene monomer and EVA resin flows. Bottom-up liner unit economics and top-down helmet production forecasts were triangulated against certification database entries.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across foam/gel/fabric/leather product types, motorcycle/military/sports/industrial application channels, and EVA/PU/cotton/nylon material grades. CAGRs were derived from fitted trend extrapolation moderated by regulatory implementation timelines and petrochemical input cost trajectories. Industry-specific forecast inputs included two-wheeler registration volumes in Maharashtra and Tamil Nadu, state-level helmet enforcement pattern shifts, and MIPS technology licensing penetration curves.
Regulatory timeline delays, styrene monomer price spike persistence, and ECE 22.07 standard fragmentation are the dominant revision risks that could compress or extend projected adoption curves. Forecasts embed assumptions about certification convergence and chemical compliance cost pass-through that may shift with policy implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Waterproof Boots Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Diving Suits Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Cooking Gloves Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Safety Shoes Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Flavored Condoms Market
Protective Gear
Work Boots Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Heated Goggles Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Earplugs Market