
 Hand Gloves Market | 2026-2036
Hand Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Gloves Market Analysis
Medical-grade certification is rotating from a niche requirement toward baseline procurement standards across institutional buyers. Ansell leverages its integrated manufacturing footprint in Southeast Asia to sustain cost-competitive nitrile output for hospital systems. Honeywell anchors its position through specialized chemical-resistant portfolios targeting semiconductor cleanrooms and petrochemical maintenance. DuPont differentiates via Kevlar-reinforced industrial designs that command premium positioning in metal fabrication and glass handling.
Hand gloves are protective garments engineered from elastomeric films or woven textiles, typically measured by puncture resistance (ASTM F2878), thickness in mils, and elongation-at-break percentages, serving to isolate the wearer from mechanical, chemical, thermal, or biological hazards. Disposable nitrile formulations now dominate hospital procurement due to latex allergy prevalence and superior solvent resistance, while reusable neoprene variants retain margin pools in chemical processing where extended duty cycles offset higher unit costs. Industrial leather-palm segments remain mature across construction and agriculture, though cut-level upgrades to ANSI A4-A9 standards are shifting replacement demand toward engineered yarn blends.
OSHA mandates under 29 CFR 1910.138 require employer-provided hand protection matched to identifiable hazards, directly shaping industrial procurement workflows and compliance documentation. FDA enforcement of 21 CFR 878.4460 for surgeon's and patient examination gloves governs biocompatibility testing and quality system requirements for medical channel access. Stakeholders must monitor evolving EPA restrictions on N-nitrosamine formation in nitrile vulcanization, as regulatory thresholds for these carcinogenic byproducts are tightening in both North American and European jurisdictions without grandfathering existing inventory.
Market Dynamics
Healthcare procurement departments are consolidating vendor relationships as nitrile supply chains concentrate in Malaysian and Thai manufacturing clusters, forcing buyers to negotiate longer-term contracts with fewer suppliers.
Growth Catalysts
- FDA 21 CFR 878.4460 Enforcement:Biocompatibility testing mandates for medical gloves are elevating certification barriers, filtering out uncertified suppliers and expanding compliant manufacturers' addressable market.
- Semiconductor Cleanroom Expansion:Chemical-resistant glove demand from chip fabrication facilities is accelerating as fabs multiply across Arizona, Texas, and South Korea.
- India Hospital Infrastructure:Government hospital bed expansion targets under Ayushman Bharat are driving institutional glove procurement at scale.
Market Restraints
- Acrylonitrile Price Volatility:Nitrile polymer feedstock costs fluctuate with crude oil derivatives, compressing manufacturer margins unpredictably.
- Southeast Asian Supply Concentration:Over 60% of nitrile glove production sits in Malaysian and Thai facilities, creating geographic risk exposure.
- Latex Allergy Substitution Ceiling:Natural rubber remains entrenched in developing-market price-sensitive segments despite nitrile performance advantages.
Strategic Opportunities
- Indonesia Food Processing Formalization:Halal certification requirements and cold-chain infrastructure investments are creating first-time institutional glove demand.
- EU Green Deal Chemistry Restrictions:REACH Annex XVII amendments targeting N-nitrosamines are advantaging early reformulation adopters with EU market access.
- Direct Hospital System Contracts:Bypassing distributor markups through GPO-negotiated direct sourcing is reshaping channel economics.
Industry Challenges
- ISO 374 Chemical Permeation Testing Backlogs:Certification laboratory capacity constraints are extending new product launch timelines.
- Legacy ERP Integration:Hospital procurement systems require custom API development to automate glove inventory replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Gloves Market |
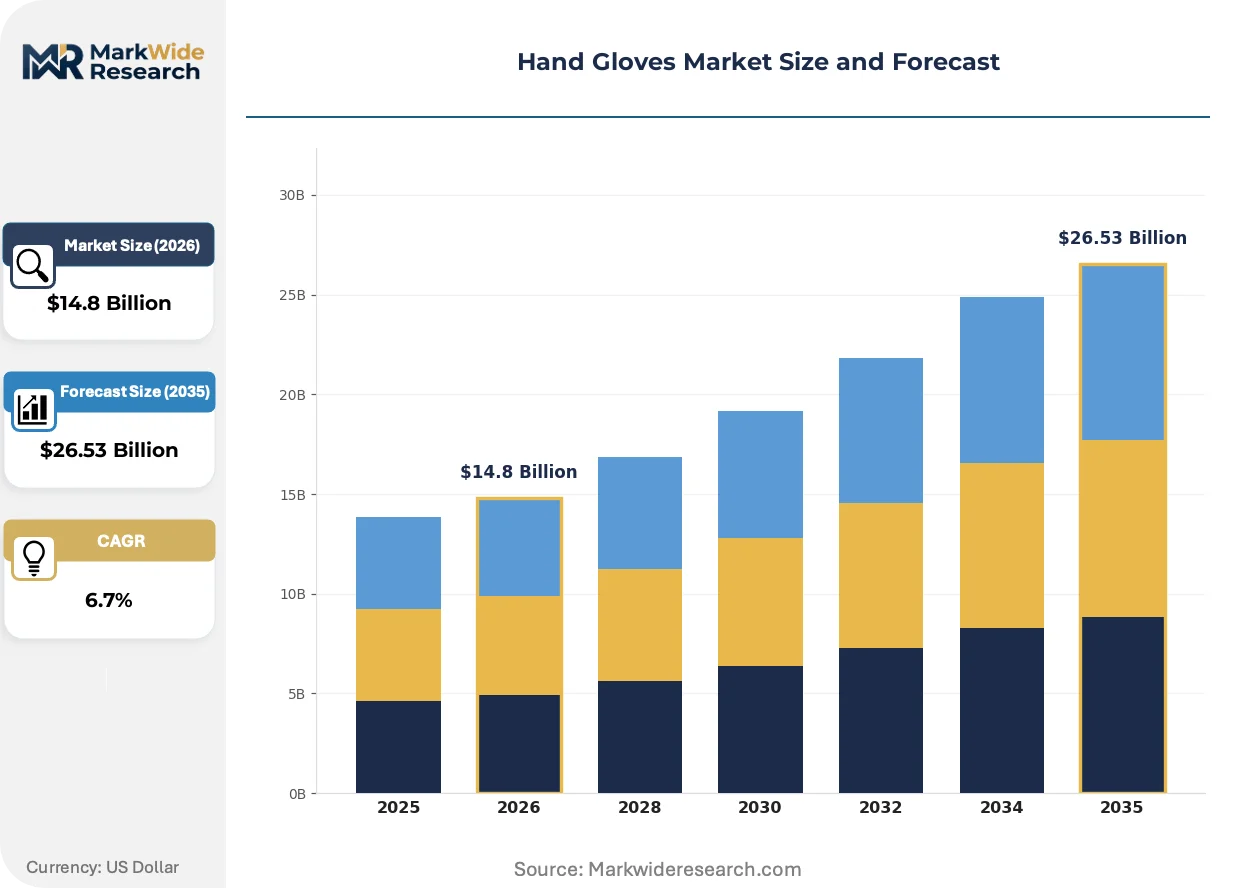
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Industrial, Medical Material: Latex, Nitrile, Vinyl, Neoprene Application: Catering, Healthcare, Automotive, Cleaning End User: Hospitals, Food Industry, Manufacturing, Agriculture |
| Companies Covered | Ansell, Honeywell, 3M, Top Glove Corporation, MCR Safety, DuPont, Showa Group, Superior Glove, Lakeland Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Gloves Market Emerging Trajectories
Polymer science advances and regulatory chemistry restrictions are converging to redefine material specifications across medical and industrial glove categories simultaneously.
Chloroprene-nitrile hybrid formulations are supplanting pure nitrile in extended-wear surgical applications, with Mayo Clinic and Cleveland Clinic procurement committees piloting 8-hour shift durability trials. The structural consequence is compression of single-use discard rates and redefinition of cost-per-procedure metrics.
EPA scrutiny of N-nitrosamine byproducts under TSCA Section 6 is compelling Malaysian manufacturers to accelerate vulcanization process modifications. The industrial consequence is temporary production slowdowns and inventory drawdowns. Medical-grade nitrile suppliers with pre-reformulation stocks are capturing displaced demand.
Consolidated purchasing through healthcare Group Purchasing Organizations is fragmenting distributor influence, with Premier and Vizient members negotiating manufacturer-direct pricing tiers. Hospital systems in Texas and Florida are most visible in this shift, leveraging volume concentration to extract service-level guarantees previously reserved for national distributors.
Hand Gloves Market Segmentation
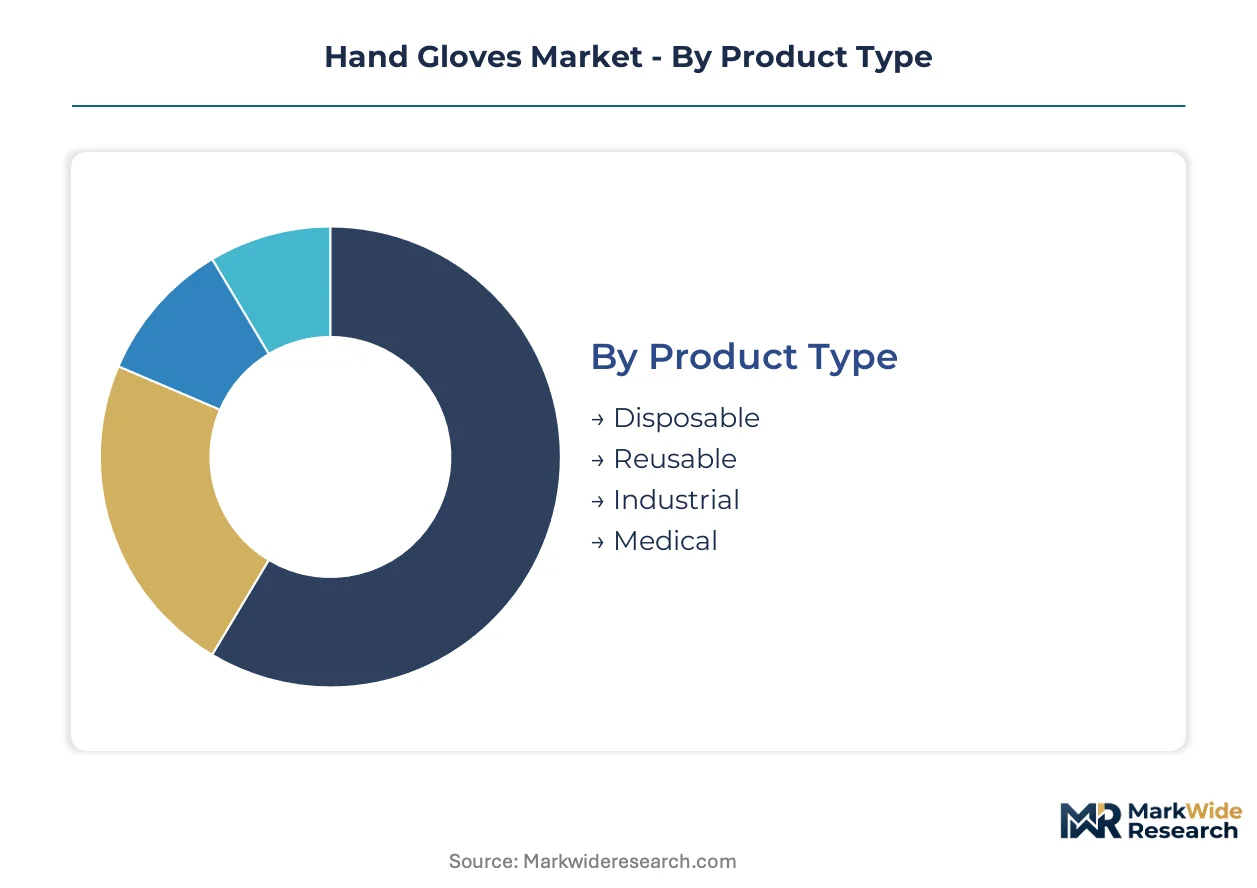
Segmentation in hand gloves reveals how material chemistry and end-use certification create distinct margin architectures. Procurement patterns diverge sharply between regulated medical channels and price-sensitive industrial buyers, forcing manufacturers to maintain parallel production lines with incompatible quality systems.
Product Type:
Substitution pressure concentrates in disposable categories where nitrile formulations displace latex across hospital systems, while reusable segments face erosion from automated handling systems in manufacturing plants.
- Disposable:Single-use nitrile and vinyl formulations dominate hospital procurement under FDA 21 CFR 878.4460 biocompatibility mandates. Mayo Clinic and Cleveland Clinic procurement committees are piloting 8-hour shift durability trials to reduce per-procedure discard rates. Demand concentrates in United States hospital systems tightening infection control protocols under Joint Commission standards.
- Reusable:Neoprene and engineered yarn blends serve chemical processing and metal fabrication where extended duty cycles offset higher unit costs. Ansell leverages integrated Southeast Asian manufacturing to sustain cost-competitive output for industrial laundries servicing petrochemical maintenance contracts.
- Industrial:Leather-palm and cut-resistant designs target construction and agriculture applications. Cut-level upgrades to ANSI A4-A9 standards are shifting replacement demand toward Kevlar-reinforced constructions from DuPont.
- Medical:Examination and surgical grades require ISO 10993 biocompatibility testing and FDA quality system compliance. Honeywell anchors position through specialized chemical-resistant portfolios targeting semiconductor cleanrooms.
Disposable retains volume leadership; Medical holds the steepest expansion curve as certification barriers filter uncertified suppliers.
Material:
Cost tier stratification separates premium elastomers from commodity vinyl, with mid-range nitrile capturing hospital procurement consolidation.
- Latex:Natural rubber formulations retain entrenched positions in developing-market price-sensitive segments despite allergy prevalence. Malaysian and Thai manufacturers face EPA scrutiny of N-nitrosamine byproducts under TSCA Section 6, compelling vulcanization process modifications.
- Nitrile:Acrylonitrile-butadiene copolymers deliver superior solvent resistance and puncture resistance per ASTM F2878. Advanced polymer blending technologies from Southeast Asian producers are improving tensile strength while reducing dermatitis incidence in United States healthcare facilities.
- Vinyl:Polyvinyl chloride offers lowest unit cost for food handling and basic cleaning applications. India food processing sector formalization under FSSAI hygiene codes is accelerating first-time institutional demand.
- Neoprene:Chloroprene-based formulations serve extended-wear chemical protection in semiconductor fabrication and pharmaceutical manufacturing. Chloroprene-nitrile hybrids are supplanting pure nitrile in surgical applications requiring 8-hour shift durability.
Nitrile commands the premium tier; Vinyl expands most quickly in emerging market food processing formalization.
Application:
Customer type differentiation separates institutional procurement with compliance documentation from spot-market industrial purchasing.
- Catering:Food-grade nitrile and vinyl gloves serve commercial kitchens and institutional food service. Indonesia halal certification requirements and cold-chain infrastructure investments are creating first-time institutional glove demand from centralized processing facilities.
- Healthcare:Examination and surgical applications drive medical-grade nitrile consumption. United States hospital systems are consolidating vendor relationships as supply chains concentrate in Malaysian and Thai manufacturing clusters.
- Automotive:Chemical-resistant neoprene and nitrile formulations protect against solvents and hydraulic fluids. Semiconductor cleanroom expansion across Arizona and Texas fabs is accelerating chemical-resistant glove demand from chip fabrication facilities.
- Cleaning:General-purpose latex and vinyl serve janitorial and sanitation applications. OSHA mandates under 29 CFR 1910.138 require employer-provided hand protection matched to identifiable hazards in commercial cleaning operations.
Healthcare retains volume leadership; Automotive gains share fastest from semiconductor fabrication capacity expansion.
End User:
Geography determines regulatory exposure, with United States hospital systems facing Joint Commission audit pressure while Indian infrastructure expansion drives volume.
- Hospitals:Acute care and surgical centers require FDA-compliant examination and surgical gloves. Premier and Vizient Group Purchasing Organizations are fragmenting distributor influence through manufacturer-direct pricing tiers.
- Food Industry:Processing plants and commercial kitchens demand food-contact-compliant nitrile and vinyl. EU Green Deal chemistry restrictions under REACH Annex XVII amendments targeting N-nitrosamines are advantaging early reformulation adopters.
- Manufacturing:Metal fabrication, electronics assembly, and chemical processing require task-specific protection. ISO 374 chemical permeation testing backlogs at certification laboratories are extending new product launch timelines for industrial glove suppliers.
- Agriculture:Pesticide handling and harvesting operations use chemical-resistant and general-purpose designs. Legacy ERP integration requirements in agricultural cooperatives demand custom API development to automate glove inventory replenishment.
Hospitals retain volume leadership; Food Industry holds the steepest expansion curve from halal certification and cold-chain formalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia and Thailand maintain substantial export surpluses in nitrile glove manufacturing while the United States and Germany absorb premium medical-grade imports. Import dependency patterns diverge sharply between acute-care hospital systems and industrial procurement channels.
United States
Joint Commission audit pressure is consolidating vendor relationships among hospital systems in Texas and Florida. FDA enforcement of 21 CFR 878.4460 biocompatibility mandates filters uncertified suppliers from institutional procurement. Arizona and Texas semiconductor fabs are accelerating chemical-resistant glove demand from chip fabrication facilities.
Germany
REACH Annex XVII amendments targeting N-nitrosamines are advantaging early reformulation adopters with EU market access. Industrial laundries servicing petrochemical maintenance contracts in the Rhine-Ruhr region sustain reusable neoprene demand. Bavarian automotive suppliers require ISO 374-certified chemical permeation protection for solvent handling operations.
Malaysia
EPA scrutiny under TSCA Section 6 is compelling vulcanization process modifications among nitrile manufacturers in the Klang Valley. Advanced polymer blending technologies from Malaysian producers are improving tensile strength specifications for United States healthcare exports. Port Klang logistics clusters handle bulk container shipments to North American hospital Group Purchasing Organizations.
India
Ayushman Bharat hospital bed expansion targets are driving institutional glove procurement at scale in Maharashtra and Karnataka. FSSAI hygiene code formalization in food processing is accelerating first-time vinyl and nitrile demand. Gujarat pharmaceutical manufacturing clusters require medical-grade examination gloves for sterile operations.
Thailand
Integrated manufacturing footprints in the Eastern Economic Corridor sustain cost-competitive nitrile output for export markets. Thai producers face concurrent EPA and REACH chemistry restrictions on vulcanization byproducts. Bangkok-based distributors are negotiating direct contracts with United States hospital systems to bypass traditional importer markups.
Hand Gloves Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. Market structure tilts toward consolidation as Group Purchasing Organizations fragment distributor influence through manufacturer-direct pricing tiers. Three archetypes dominate: integrated Southeast Asian manufacturers with captive polymer supply, diversified industrial conglomerates with multi-hazard portfolios, and specialized cleanroom suppliers targeting semiconductor fabrication. Capacity expansion and strategic partnerships represent the dominant competitive moves as players defend access to hospital system contracts.
Within the integrated manufacturing tier, Top Glove Corporation and Ansell occupy positions as archetypal scale-driven exporters from Southeast Asian production bases. DuPont exemplifies the materials-science conglomerate archetype, leveraging Kevlar-reinforced constructions for premium industrial positioning. Honeywell sits within the diversified safety equipment category, anchoring chemical-resistant portfolios for semiconductor and petrochemical end users.
| Leading Market Players |
|---|
| Ansell |
| Honeywell |
| 3M |
| Top Glove Corporation |
| MCR Safety |
| DuPont |
| Showa Group |
| Superior Glove |
| Lakeland Industries |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with Malaysian and Thai manufacturers lock in both nitrile supply access and price visibility for United States hospital Group Purchasing Organizations, insulating procurement committees from acrylonitrile feedstock volatility while committing volume through multi-year agreements.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures across chemical-resistant glove categories, with three-tier pricing stratification separating FDA 510(k)-cleared medical grades from ISO 374-certified industrial variants and uncertified general-purpose tiers. Price differentiation hinges on biocompatibility testing depth and geographic delivery cost from Southeast Asian ports. Cost compression in standard nitrile examination gloves is intensifying because Malaysian manufacturers absorb EPA-mandated vulcanization reformulation expenses. Food processing buyers in India exhibit highest price sensitivity, while semiconductor cleanroom operators accept premium positioning for particle-controlled formulations.
Supply Chain Analysis
Port congestion at Port Klang and container availability constraints on the Asia-North America trade lane are extending order-to-delivery cycles for hospital system procurement departments. Manufacturing concentrates in Malaysia, Thailand, and Indonesia, with nitrile butadiene rubber and acrylonitrile monomer feeding from petrochemical complexes in the Strait of Malacca. Single-source vulnerability runs through Klang Valley production clusters concentrated within seismic and flood risk zones. Distribution runs through healthcare Group Purchasing Organizations consolidating previously fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hand gloves sit in early-cycle expansion as infection control protocol tightening across United States hospital systems and Indian infrastructure build-out create sustained procurement tailwinds through the analysis window.
For Market Incumbents: Compound certification depth advantages by accelerating FDA 21 CFR 878.4460 quality system investments ahead of smaller competitors, while securing captive acrylonitrile supply through backward integration into Malaysian petrochemical partnerships. Emerging Indonesian and Vietnamese manufacturers threaten margin pools in price-sensitive vinyl segments. For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways offer fastest regulatory clearance for nitrile examination glove entrants targeting direct hospital contracts outside established Group Purchasing Organization networks. White-space concentrates in Indonesian halal-certified food processing and Indian Ayushman Bharat hospital procurement. Go-to-market through state-level distributor partnerships bypasses national incumbent lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated Southeast Asian manufacturers with captive polymer supply and established United States hospital system relationships, positioned to capture volume concentration as procurement consolidates. Five-to-ten year viability rests on EPA and REACH chemistry compliance adaptation speed. The signal to watch is N-nitrosamine testing backlog resolution at third-party laboratories as reformulation adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Supply | Captive feedstock secures margin stability against crude derivative volatility for Malaysian producers. |
| FDA 510(k) Pre-Submission Investment | Accelerated clearance timelines unlock Group Purchasing Organization contract eligibility for emerging manufacturers. |
| Direct Hospital System Contracting | Bypassing distributor markups reshapes channel economics for Texas and Florida health systems. |
| Chloroprene-Nitrile Hybrid Formulation | Extended-wear durability trials at Mayo Clinic redefine cost-per-procedure metrics in surgical applications. |
| EU REACH Annex XVII Reformulation | Early N-nitrosamine compliance secures market access as chemistry restrictions tighten without grandfathering. |
Methodological Framework
Desk research of customs trade databases, FDA 510(k) clearance records, and hospital procurement contract filings preceded structured interviews with Group Purchasing Organization contracts managers, Malaysian plant operations directors, biomedical engineers at United States health systems, and nitrile compound formulators. Bottom-up volume estimates from end-use application segmentation were triangulated against top-down trade flow analysis across the analysis window.
Variance decomposition across material type, end-use certification tier, and geographic demand cluster shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling incorporating Joint Commission audit frequency, semiconductor fabrication capacity announcements, and Indian hospital bed expansion targets. Forecast inputs included acrylonitrile price index trajectories and EPA TSCA Section 6 enforcement timelines.
Underlying assumptions cover sustained FDA enforcement of 21 CFR 878.4460 biocompatibility mandates and continued Malaysian-Thai manufacturing dominance, with deviation risk concentrated in accelerated domestic production incentives in the United States or India. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Battery Heated Gloves Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Dust Covers Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Diving Suits Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Waterproof Cases Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Tactical Boots Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Pet Control Devices Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Helmets Market