
 Diving Suits Market | 2026-2036
Diving Suits Market Size, Share, and Industry Trends Forecast 2026-2036
Diving Suits Market Intelligence
EN 14225-2 certification for cold-water diving suits is collapsing the supplier base for professional applications, forcing smaller manufacturers to absorb testing costs or exit the segment. Aqua Lung International leverages its vertically integrated neoprene supply chain to sustain compliance margins across European and North American distribution channels. Johnson Outdoors Inc. anchors its competitive position through deep relationships with military procurement programs, while Cressi Sub S.p.A. differentiates via heritage brand equity in Mediterranean recreational markets.
Diving suits are engineered protective garments constructed from closed-cell neoprene foam laminates or tri-laminate membrane fabrics, designed to thermally insulate human operators during submerged operations at depths exceeding recreational limits. Their primary commercial purpose centers on preventing hypothermia and barotrauma across extended-duration underwater work in petroleum extraction, salvage, and scientific research environments. Wetsuits dominate volume shipments in tropical recreational markets where cost sensitivity and rental-channel turnover shape procurement patterns, while dry suits command premium positioning in professional and military usage segments where thermal protection integrity at depth is non-negotiable. Neoprene material formulations are experiencing fastest-growing demand as bio-based elastomer alternatives enter pilot production, though petroleum-derived chloroprene rubber still occupies the majority of supply contracts.
EU PPE Regulation 2016/425 and the associated CE marking framework govern market access for diving suits sold within European member states, with notified bodies conducting annual factory audits that directly shape manufacturer cost structures. The US Coast Guard and OSHA maritime safety standards impose parallel compliance burdens for commercial diving operations in American territorial waters, creating dual-certification requirements for suppliers serving transatlantic clients. Stakeholders must monitor the divergence between regional thermal performance testing protocols, as misalignment between EN and ANSI methodologies threatens to fragment product development roadmaps and inflate certification expenditures.
Market Dynamics
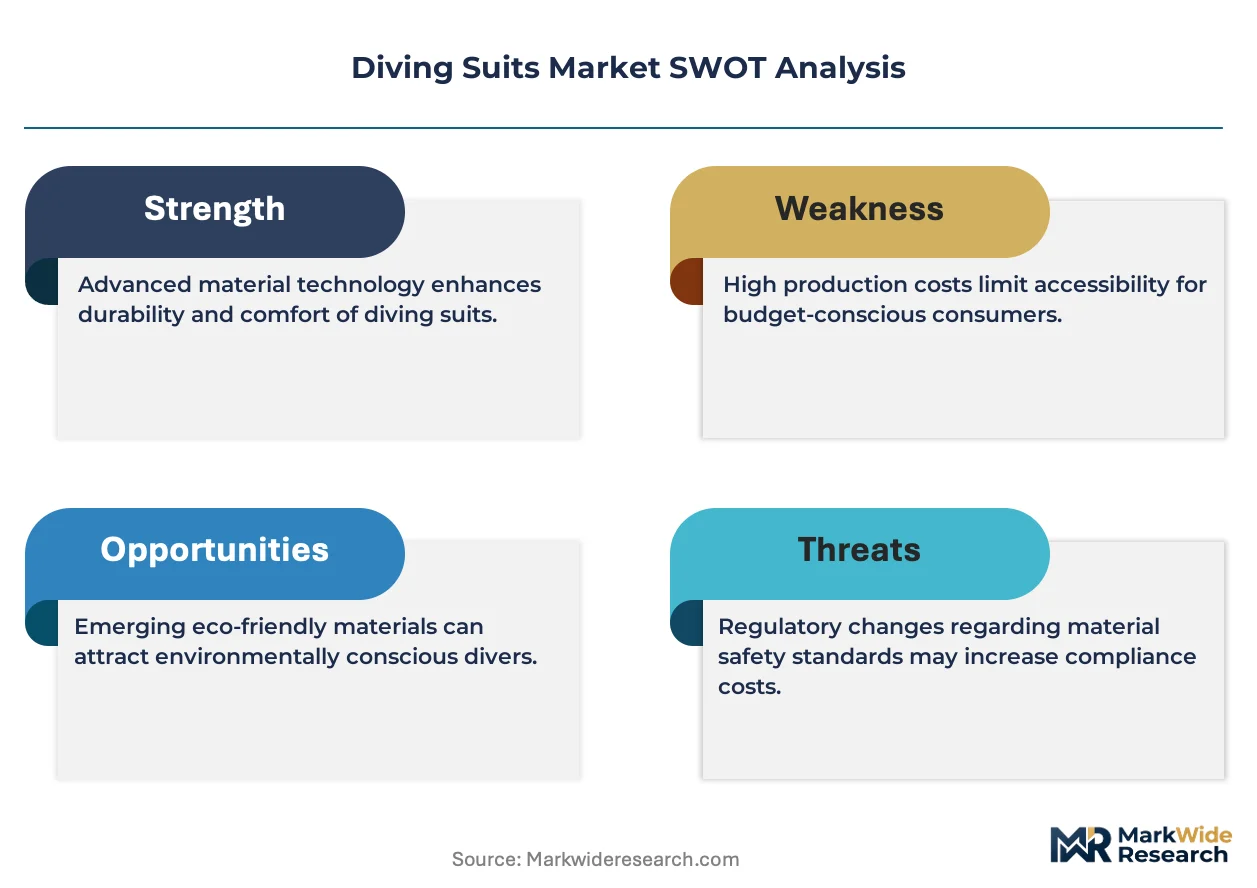
EN 14225-2 cold-water certification requirements are compressing the professional-grade supplier base, forcing manufacturers to absorb six-figure testing expenditures or abandon European commercial channels entirely. This regulatory concentration is redistributing competitive advantage toward vertically integrated neoprene producers with captive laboratory capacity.
Growth Catalysts
- Offshore energy infrastructure:Southeast Asian coastal economies including Vietnam and Indonesia are scaling petroleum extraction platforms and wind farm installations simultaneously, generating concurrent demand for thermal protection systems in commercial diving contractor fleets.
- EU PPE Regulation 2016/425:Mandatory CE marking through notified body audits is professionalizing procurement standards across European maritime safety agencies, eliminating non-compliant rental inventory from commercial diving operations.
- Bio-based chloroprene elastomers:Pilot production of petroleum-alternative neoprene formulations is attracting sustainability-mandated procurement from research institutions and government scientific diving programs seeking Scope 3 emission reductions.
Market Restraints
- Petroleum-derived feedstock volatility:Chloroprene rubber prices track naphtha and butadiene commodity swings, compressing margin stability for manufacturers locked into annual supply contracts with fixed pricing terms.
- Notified body bottleneck:EU PPE certification capacity concentrates among seventeen accredited laboratories across Germany, France, and Italy, creating twelve-to-eighteen month queue delays for new product approvals.
- Tri-laminate membrane substitution:Advanced membrane dry suits for military and scientific applications are displacing traditional neoprene in depth-critical segments, threatening volume foundations for foam-laminate specialists.
Strategic Opportunities
- Underpenetrated Mediterranean scientific diving:Greece, Croatia, and Cyprus lack indigenous professional-grade manufacturing, creating white space for certified suppliers to establish direct distribution to marine research stations and archaeological conservation programs.
- US Coast Guard modernization:Federal procurement programs for maritime emergency response teams specify updated thermal protection standards, opening replacement cycles for dual-certified EU-US suppliers.
- Rental-channel digitization:Equipment-as-a-service platforms are penetrating tropical recreational markets, enabling manufacturers to capture recurring revenue streams from dive resort operators previously served through wholesale distribution.
Industry Challenges
- Certification timeline compression:Divergence between EN 14225-2 thermal testing protocols and ANSI/CEA standards for North American commercial diving is forcing parallel development tracks, inflating R&D overhead and delaying product launches.
- Specialized polymer compounding expertise:Closed-cell neoprene formulation knowledge concentrates among aging technical workforces in Japan and Italy, constraining capacity expansion for manufacturers attempting vertical integration into material production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diving Suits Market |
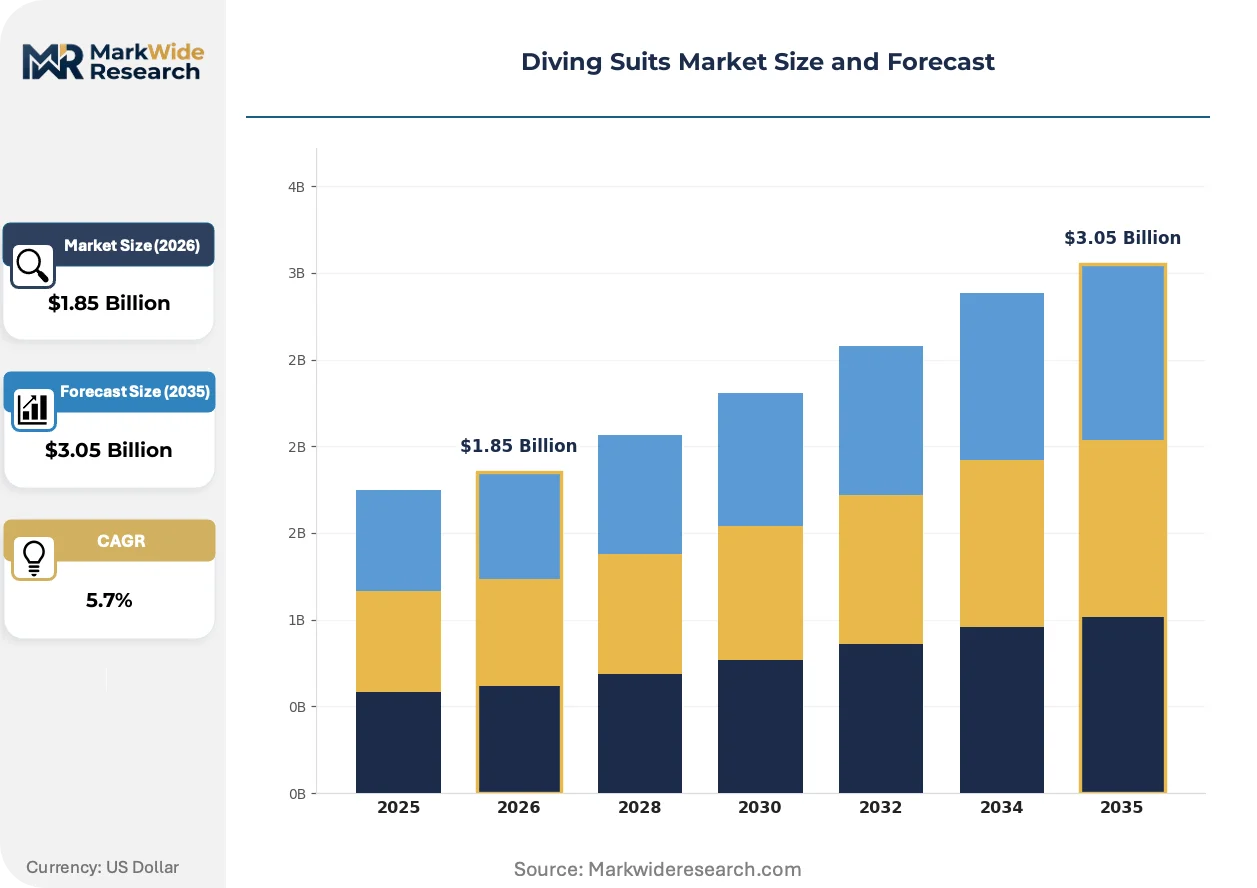
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wetsuits, Dry Suits, Semi-Dry Suits, Shorty Suits Material: Neoprene, Nylon, Rubber, Polyurethane Usage: Recreational Diving, Professional Diving, Commercial Diving, Military Diving Size: Small, Medium, Large, Extra-Large |
| Companies Covered | Aqua Lung International, Johnson Outdoors Inc., Cressi Sub S.p.A., Mares S.p.A., Beuchat International, Huish Outdoors LLC, Bare Sports Inc., Scubapro, Typhoon International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diving Suits Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization pressures are restructuring competitive positioning across professional and recreational segments. Manufacturers are redirecting R&D investment toward certification-compliant thermal systems and sustainable feedstock alternatives.
Closed-cell neoprene foam laminates with integrated phase-change materials are displacing conventional wetsuit constructions in scientific and military procurement specifications. Research institutions including the Scripps Institution of Oceanography and military diving units are specifying these thermal management systems for extended-duration operations below fifteen degrees Celsius. The technology is displacing volume demand for standard neoprene thickness gradations in professional channels.
EU Regulation 2016/425 and its associated CE marking framework are tightening factory audit frequencies for diving suit manufacturers serving European commercial diving contractors. Notified bodies now conduct unannounced inspections of lamination and seam-sealing processes, elevating quality system documentation requirements. Professional-grade suppliers are responding by consolidating production in single-facility configurations to simplify audit traceability.
Scientific diving programs are unbundling after-sales service from equipment procurement, establishing direct maintenance contracts with specialized repair technicians rather than manufacturer service networks. This pattern is compressing traditional distributor margins in North American and Australian research diving markets. The shift is most visible in California and Queensland where university consortiums have centralized equipment lifecycle management.
Diving Suits Market Segmentation
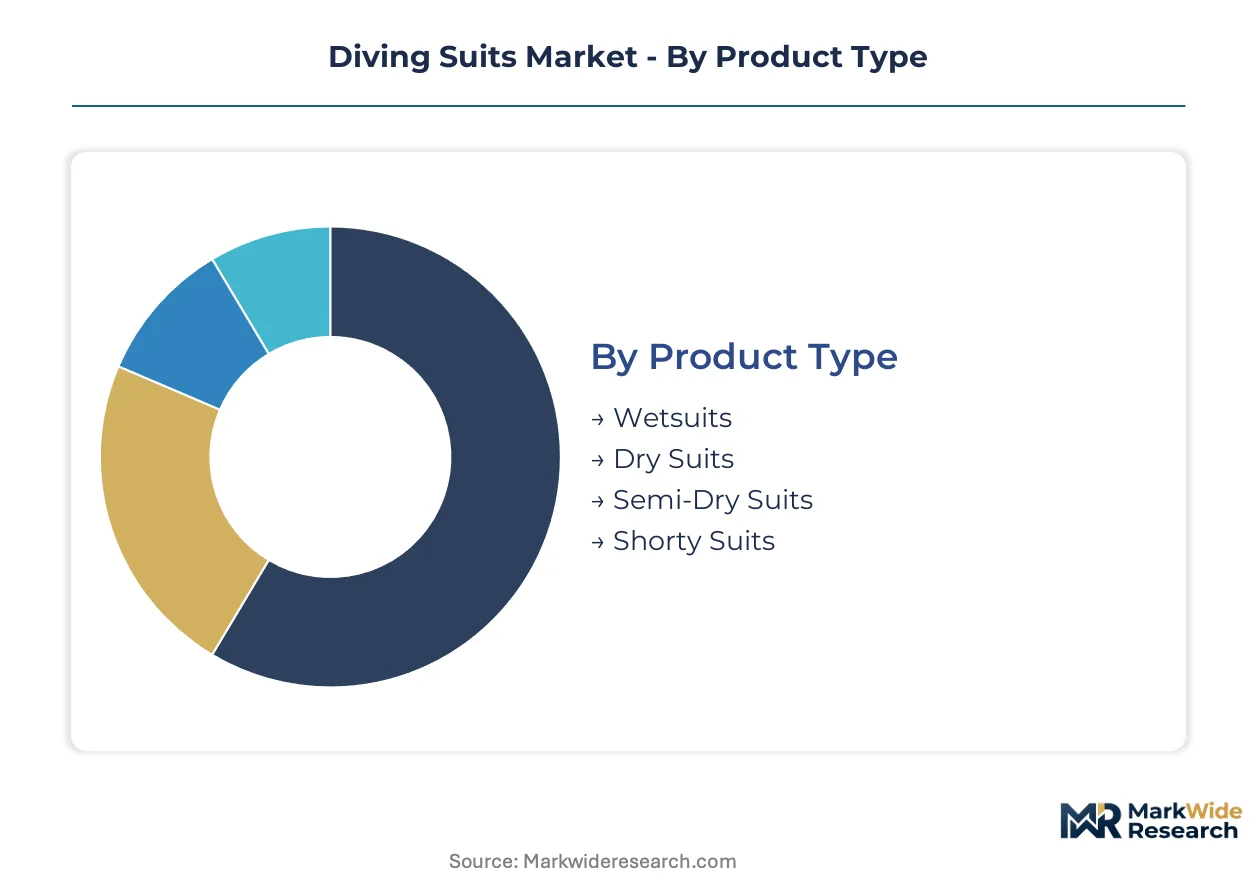
Diving suit procurement channels diverge sharply between recreational rental operators and professional fleet managers, with certification requirements and thermal performance specifications dictating supplier eligibility. Understanding segment-specific channel economics reveals why material choices and sizing strategies vary dramatically across end-use categories.
Product Type:
Channel economics split sharply: rental fleets in tropical markets favor standardized wetsuit configurations, while commercial diving contractors source dry suits through specialized procurement programs with multi-year service agreements.
- Wetsuits:Closed-cell neoprene foam laminates in 3mm to 7mm thickness gradations serve recreational dive operators in Southeast Asian coastal economies. Thailand and Indonesia's marine tourism infrastructure drives volume demand through wholesale distribution to resort rental fleets.
- Dry Suits:Tri-laminate membrane or compressed neoprene constructions with integrated seals and inflation systems prevent water ingress during extended-duration operations. Norwegian and Scottish offshore energy contractors specify these for thermal protection integrity below ten degrees Celsius.
- Semi-Dry Suits:Hybrid constructions with limited water flushing suit temperate-water recreational markets.
- Shorty Suits:Truncated designs for surface snorkeling and warm-water training applications.
Wetsuits dominate installed base volume across tropical rental channels. Dry suits are where expansion concentrates in professional and military procurement specifications.
Material:
Cost tier alignment shapes material selection: petroleum-derived chloroprene rubber occupies mid-market professional applications, while bio-based alternatives command premium positioning in sustainability-mandated scientific programs.
- Neoprene:Chloroprene rubber foam laminates provide compressible thermal insulation across variable depths. Japanese and Italian polymer compounders control formulation expertise for closed-cell density specifications required by EN 14225-2 certification.
- Nylon:Woven face fabrics laminated to neoprene cores reduce surface abrasion in rental-channel turnover environments.
- Rubber:Natural and synthetic rubber compounds serve specialized military specifications for chemical resistance.
- Polyurethane:Spray-applied or sheet membranes create waterproof barriers in hybrid dry suit constructions.
Neoprene anchors the material mix across volume segments. Bio-based chloroprene alternatives are climbing the fastest in research institution procurement.
Usage:
Customer type determines certification burden: recreational users purchase through retail and rental intermediaries, while commercial and military end-users impose direct factory audit requirements on suppliers.
- Recreational Diving:Individual consumers and resort operators procure through wholesale distribution with minimal regulatory oversight beyond basic product safety standards.
- Professional Diving:Scientific research stations and archaeological conservation programs in Greece and Croatia specify EN 14225-2 certified equipment with documented thermal performance testing.
- Commercial Diving:Offshore petroleum extraction contractors in Vietnam and Indonesia require fleet-standardized thermal protection systems with centralized maintenance protocols.
- Military Diving:Naval procurement programs in the US and EU member states impose dual-certification requirements spanning OSHA maritime safety and CE marking frameworks.
Recreational usage represents the broadest installed base. Commercial and military applications are where margin expansion and supplier consolidation concentrate.
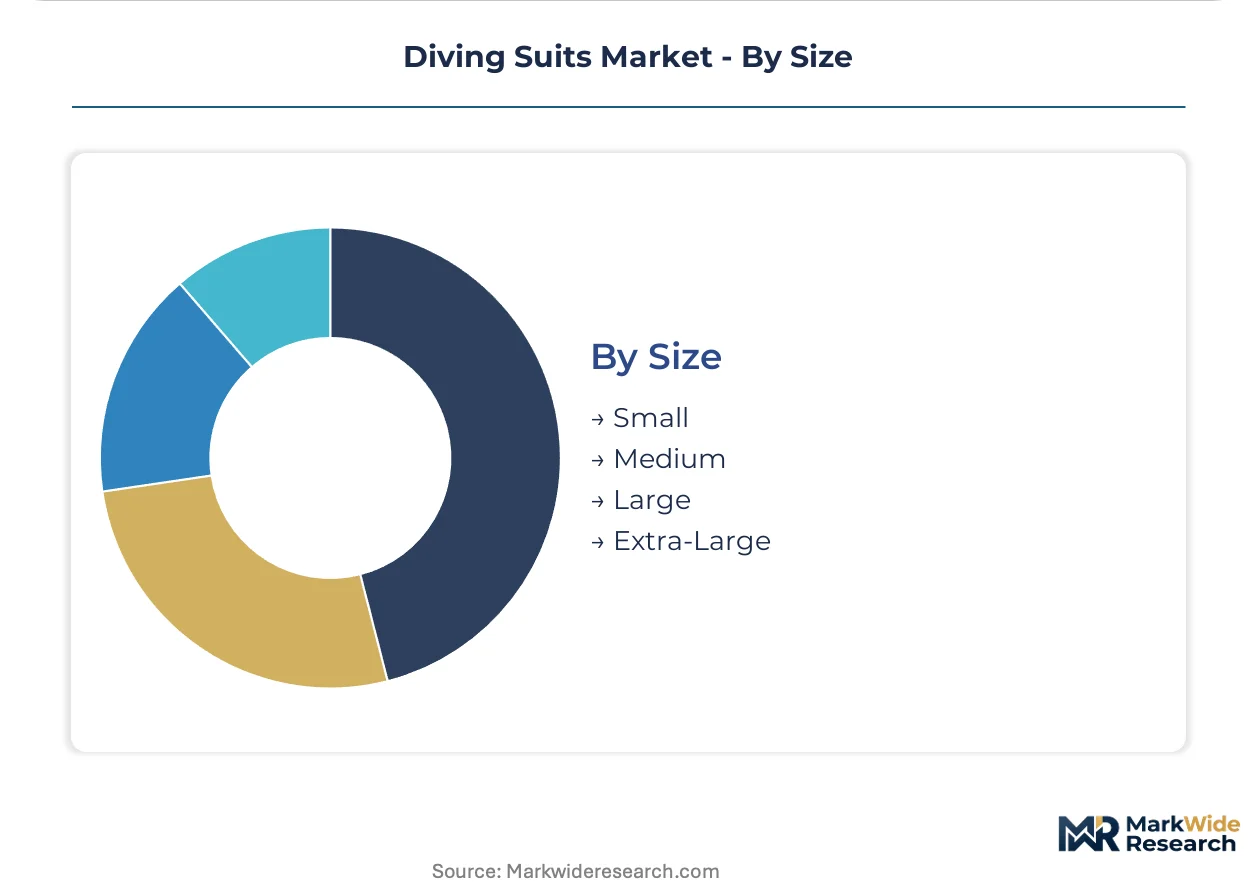
Size:
Regional anthropometric variation drives sizing strategy: Asian markets concentrate demand in small and medium configurations, while North American and European channels require expanded extra-large inventories.
- Small:Southeast Asian and East Asian recreational markets dominate demand, with Japanese dive operators maintaining highest per-capita rental turnover.
- Medium:The most universally stocked configuration across global distribution channels.
- Large:North American and Australian markets show concentration, with German and Dutch commercial divers also clustering in this range.
- Extra-Large:Limited but non-negotiable inventory requirement for North American military and commercial contractor procurement.
Medium sizes dominate unit economics across rental fleets. Large and extra-large configurations are where regional distribution complexity and inventory carrying costs concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU PPE Regulation 2016/425 and updated EN 14225 standards are redistributing manufacturing capacity toward jurisdictions with notified body proximity and captive certification infrastructure. Southeast Asian coastal economies are absorbing fleet modernization demand from concurrent offshore energy and marine tourism scaling.
United States
US Coast Guard and OSHA maritime safety standards govern commercial diving contractor procurement across Gulf of Mexico petroleum extraction platforms and Pacific Northwest scientific research stations. Federal procurement programs for maritime emergency response teams specify updated thermal protection standards. California university consortiums have centralized equipment lifecycle management, compressing traditional distributor margins in research diving markets.
Germany
Notified body concentration in Germany, France, and Italy creates twelve-to-eighteen month queue delays for new product approvals, elevating competitive advantage for manufacturers with established laboratory relationships. The country's national maritime safety regulator enforces CE marking through unannounced factory audits of lamination and seam-sealing processes. Industrial clusters in Bavaria and North Rhine-Westphalia host vertically integrated neoprene compounders serving professional-grade supply contracts.
Vietnam
Offshore wind farm installations and petroleum extraction platform scaling generate concurrent demand for thermal protection systems in commercial diving contractor fleets. The country's national industrial development programs prioritize maritime infrastructure investment. Ho Chi Minh City and Da Nang serve as distribution hubs for regional fleet procurement serving Southeast Asian offshore energy corridors.
Norway
Scottish and Norwegian offshore energy contractors specify dry suits for thermal protection integrity below ten degrees Celsius in North Sea extraction environments. The country's national petroleum safety authority mandates documented thermal performance testing for professional diving operations. Stavanger and Bergen concentrate commercial diving contractor headquarters and fleet maintenance facilities.
Japan
Closed-cell neoprene formulation knowledge concentrates among aging technical workforces in Japan and Italy, constraining capacity expansion for manufacturers attempting backward integration into material production. The country's national industrial standards body maintains JIS specifications for diving equipment parallel to EN frameworks. Tokyo and Osaka house polymer compounding specialists supplying density specifications required by cold-water certification protocols.
Diving Suits Market Key Industry Players
Player mix skews toward vertically integrated material producers and heritage equipment manufacturers with established certification track records. The supplier base is compressing under EN 14225-2 testing expenditure burdens, with smaller fabricators abandoning European commercial channels. Two strategic archetypes dominate: neoprene supply chain owners with captive laboratory capacity, and military procurement specialists with deep government relationships. Competitive moves concentrate on backward integration into polymer compounding and consolidation of production in single-facility configurations to simplify audit traceability.
Among vertically integrated specialists, Aqua Lung International exemplifies the archetype of neoprene supply chain owners sustaining compliance margins across European and North American distribution channels. Johnson Outdoors Inc. occupies a position within the military procurement tier, anchoring competitive positioning through government program relationships. Cressi Sub S.p.A. represents heritage brand equity concentration in Mediterranean recreational markets, sitting within the specialist tier where regional brand recognition shapes distributor access.
| Leading Market Players |
|---|
| Aqua Lung International |
| Johnson Outdoors Inc. |
| Cressi Sub S.p.A. |
| Mares S.p.A. |
| Beuchat International |
| Huish Outdoors LLC |
| Bare Sports Inc. |
| Scubapro |
| Typhoon International Ltd |
| Others |
Cost & Logistics Intelligence
EU PPE Regulation 2016/425 gates both supplier qualification and price differentiation simultaneously, as CE marking through notified body audits creates a dual-track market where certified manufacturers command premium positioning while uncertified competitors retreat to unregulated recreational channels.
Pricing Analysis
Cost-plus contracts with naphtha and butadiene indexation dominate professional-grade procurement, insulating manufacturers from petroleum feedstock volatility while compressing margins during commodity spikes. Price differentiation stems from certification grade—EN 14225-2 compliance separates premium dry suits from standard wetsuits—and volume scale, with fleet-standardized contracts earning discounts against one-off scientific orders. Pricing pressure intensifies in tropical recreational tiers due to rental-channel digitization and equipment-as-a-service platforms. Commercial diving contractors exhibit lowest price sensitivity, prioritizing thermal performance integrity and maintenance bundling over unit cost.
Supply Chain Analysis
Notified body concentration in Germany, France, and Italy creates a certification chokepoint that constrains European market access and elevates compliance costs for distant manufacturers. Raw material dependencies center on Japanese and Italian chloroprene rubber compounders, Taiwanese woven face fabric suppliers, and German lamination adhesive specialists. Single-source vulnerability concentrates in closed-cell neoprene formulation expertise held by aging technical workforces. Distribution runs through specialized diving equipment distributors serving commercial contractor fleets, with direct procurement emerging in scientific and military segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diving suits market is approaching a platform-economics inflection as equipment-as-a-service digitization and centralized lifecycle management by university consortiums unbundle traditional manufacturer-distributor relationships.
For Market Incumbents: Shield certification-derived margins by consolidating production in single-facility configurations to simplify EU notified body audit traceability. Deepen backward integration into bio-based chloroprene elastomer pilot production to capture sustainability-mandated scientific procurement. Defend against tri-laminate membrane substitution in military and depth-critical segments through integrated phase-change material R&D. For New Entrants and Emerging Players: EN 14225-2 fast-track certification partnerships with German or Italian notified bodies unlock professional-grade market access ahead of twelve-to-eighteen month standard queues. Target underpenetrated Mediterranean scientific diving in Greece and Croatia where indigenous manufacturing is absent. Pursue direct distribution to marine research stations bypassing traditional wholesale channels compressed by centralized equipment lifecycle management. For Investors and Strategic Acquirers: EU Regulation 2016/425 enforcement tightening reshapes the acquisition landscape toward notified body-proximate manufacturers with captive laboratory capacity. Long-term viability favors vertically integrated neoprene compounders serving dual-certified EU-US supplier positions. Watch bio-based elastomer cost parity progression as the signal for petroleum-alternative feedstock inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive chloroprene rubber supply secures EN 14225-2 certification margins against feedstock volatility. |
| Single-Facility Production Consolidation | Simplified audit traceability reduces EU notified body inspection burden and compliance documentation overhead. |
| Equipment-as-a-Service Platform Launch | Recurring revenue capture from dive resort operators displaces wholesale distributor intermediation. |
| Bio-Based Elastomer Pilot Scale-Up | Scope 3 emission reductions attract sustainability-mandated procurement from government scientific diving programs. |
| Dual-Certification Laboratory Investment | Parallel EN and ANSI thermal testing capability accelerates transatlantic product launches and reduces R&D overhead duplication. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, polymer compounding industry filings, and maritime safety regulatory databases. Primary interviews engaged commercial diving contractor fleet managers, notified body certification engineers, neoprene compounder technical directors, and marine research station equipment officers. Secondary validation drew from EU PPE Regulation implementation reports, EN standard committee documentation, and offshore energy contractor procurement disclosures. Bottom-up triangulation across product type, material formulation, and usage segment estimates converged with top-down market sizing.
Segmentation dimensions modeled include product type, material composition, usage category, and regional regulatory cluster across the analysis window. Value projections incorporate fleet modernization cycle timing, certification queue delays, and bio-based feedstock substitution elasticity. CAGRs derive from historical shipment patterns adjusted for regulatory enforcement intensity and petroleum derivative price trajectory assumptions. Industry-specific inputs include notified body capacity constraints and scientific diving program centralization trends.
Decision-makers should treat outputs as directional under sustained EU regulatory enforcement and Southeast Asian offshore energy scaling assumptions; material deviation in certification timeline compression or feedstock cost parity would warrant model refresh. Practitioners should keep alternative scenarios live as bio-based elastomer production economics and tri-laminate membrane penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Heated Goggles Market
Protective Gear
Dust Covers Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Cooking Gloves Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
China Pollution Mask Market
Protective Gear
Helmets Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Work Shoes Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Earplugs Market